FedEx Freight FDXF
-15.7%vs Day 1Spinoff of FedEx (FDX) · Classic Spinoff (80.1% Retained Stake) · Spun Jun 1, 2026
Expected return (11/13/2026): -16% Gain to loss: 0.0 : 1Largest North American LTL carrier by revenue; shipments turned positive in September 2026 and 2027 is guided to the company's framework (an operating ratio near 87%), which is the base case. After a 15% rise on the results the price implies a return toward the 2023-24 peak margins. FedEx expects to sell its retained 19.9% by about September 2027.
Current Stats
Post-Spinoff Performance
| Timeline | |
| Spinoff date | June 1, 2026 · NYSE |
| Days since spinoff | 166 days |
| Structure | Classic Spinoff |
| §355(e) window closes statutory; a tax matters agreement may bar more, and for longer | June 1, 2028 |
| Parent | FedEx (FDX) |
| Day-1 reaction | |
| Day 1 open | $164.00 |
| Day 1 return (open→close) | -8.8% |
| Day 1 price (close) | $149.53 |
| Day 1 range | $141.33 – $166.90 +18.1% spread |
| Day 1 low held? | Breached after 25 sessions to -26.8% below |
| Price levels | |
| Post-spin low (closing) | $107.95 on Oct 21, 2026 · 142 days post-spin |
| Lowest traded | $103.48 on Oct 28, 2026 · 149 days post-spin |
| Current price (Nov 13, 2026) | $133.93 |
| Returns | |
| Return vs Day 1 (close) | -10.4% |
| — range by day 1 entry theoretical bounds | -19.8% to -5.2% |
| Return vs post-spin low | +24.1% |
| First-quarter return (≈90d) | -10.8% |
| Versus benchmarks | |
| S&P 500 over same window | -0.0% |
| Shares & ownership | |
| Shares outstanding Sep 30, 2026 | 149,518,133 |
| Diluted average shares the EPS denominator | 149,900,000 |
| Free float | 119,418,150 80% of shares outstanding |
| Held by institutions | 69% insiders 20.5% |
| Share count trend Nov 2025 → Sep 2026 | +0.0% broadly flat |
| Volume & liquidity | |
| Traded per day 20-session median | $148M |
| Normal volume baseline | 1,264,600 shares · now 0.92x |
| Day 1 volume | 5.9x normal · first week 3.5x |
| Decay | half in 5 sessions · normal by 9 |
Computed from split-adjusted closing prices. Returns are total return — (end price + dividends received − start price) ÷ start price — with no reinvestment assumed.
Price History
Closing price, split-adjusted, with volume below. No dividends have been paid, so price return and total return are the same. Source: Yahoo Finance. Data through Nov 14, 2026.
Raw daily price & volume data
| Date | Open | High | Low | Close | Volume | Float | Turnover | Market cap | Dividend | Split |
|---|---|---|---|---|---|---|---|---|---|---|
| 2026-11-13 | $131.05 | $134.01 | $130.76 | $133.93 | 725,000 | 119,418,150 | 0.48% | $20.02B | — | — |
| 2026-11-12 | $131.68 | $133.51 | $129.71 | $131.00 | 1,051,500 | 119,418,150 | 0.70% | $19.59B | — | — |
| 2026-11-11 | $128.63 | $132.88 | $128.43 | $132.64 | 813,100 | 119,418,150 | 0.54% | $19.83B | — | — |
| 2026-11-10 | $128.05 | $130.39 | $126.62 | $129.83 | 786,800 | 119,418,150 | 0.53% | $19.41B | — | — |
| 2026-11-09 | $123.56 | $130.40 | $122.79 | $129.05 | 1,341,700 | 119,418,150 | 0.90% | $19.30B | — | — |
| 2026-11-06 | $122.38 | $124.03 | $120.40 | $123.56 | 797,900 | 119,418,150 | 0.53% | $18.47B | — | — |
| 2026-11-05 | $130.96 | $132.09 | $123.23 | $124.41 | 1,273,900 | 119,418,150 | 0.85% | $18.60B | — | — |
| 2026-11-04 | $133.00 | $134.05 | $128.91 | $129.43 | 1,796,500 | 119,418,150 | 1.20% | $19.35B | — | — |
| 2026-11-03 | $129.74 | $131.64 | $126.13 | $130.26 | 1,712,100 | 119,418,150 | 1.15% | $19.48B | — | — |
| 2026-11-02 | $126.97 | $135.43 | $126.14 | $131.85 | 2,472,200 | 119,418,150 | 1.65% | $19.71B | — | — |
| 2026-10-30 | $115.20 | $128.00 | $115.20 | $126.04 | 3,597,000 | 119,418,150 | 2.41% | $18.85B | — | — |
| 2026-10-29 | $108.01 | $110.60 | $106.36 | $109.69 | 2,129,400 | 119,418,150 | 1.42% | $16.40B | — | — |
| 2026-10-28 | $108.89 | $108.89 | $103.48 | $108.33 | 1,780,300 | 119,418,150 | 1.19% | $16.20B | — | — |
| 2026-10-27 | $109.53 | $109.94 | $106.21 | $108.50 | 1,057,100 | 119,418,150 | 0.71% | $16.22B | — | — |
| 2026-10-26 | $110.30 | $112.07 | $108.18 | $109.45 | 857,000 | 119,415,647 | 0.57% | $16.36B | — | — |
| 2026-10-23 | $110.92 | $111.21 | $106.85 | $110.05 | 1,014,400 | 119,415,647 | 0.68% | $16.45B | — | — |
| 2026-10-22 | $108.00 | $113.23 | $107.90 | $111.02 | 1,816,600 | 119,415,647 | 1.21% | $16.60B | — | — |
| 2026-10-21 | $110.25 | $110.50 | $107.37 | $107.95 | 1,010,100 | 119,415,647 | 0.68% | $16.14B | — | — |
| 2026-10-20 | $110.17 | $113.14 | $109.20 | $109.54 | 1,045,500 | 119,415,647 | 0.70% | $16.38B | — | — |
| 2026-10-19 | $113.25 | $113.25 | $108.68 | $110.20 | 2,065,700 | 119,415,647 | 1.38% | $16.48B | — | — |
| 2026-10-16 | $110.96 | $114.08 | $110.43 | $113.21 | 1,553,000 | 119,415,647 | 1.04% | $16.93B | — | — |
| 2026-10-15 | $109.82 | $111.33 | $109.07 | $110.50 | 1,188,300 | 119,415,647 | 0.79% | $16.52B | — | — |
| 2026-10-14 | $109.78 | $110.45 | $105.75 | $108.69 | 1,512,900 | 119,415,647 | 1.01% | $16.25B | — | — |
| 2026-10-13 | $112.39 | $113.62 | $108.61 | $110.09 | 1,122,800 | 119,415,647 | 0.75% | $16.46B | — | — |
| 2026-10-12 | $115.28 | $115.51 | $111.31 | $113.12 | 1,343,600 | 119,415,647 | 0.90% | $16.91B | — | — |
| 2026-10-09 | $115.68 | $115.99 | $113.04 | $115.47 | 958,700 | 119,415,647 | 0.64% | $17.26B | — | — |
| 2026-10-08 | $113.74 | $116.09 | $112.77 | $115.65 | 1,647,200 | 119,415,647 | 1.10% | $17.29B | — | — |
| 2026-10-07 | $110.39 | $114.62 | $110.00 | $113.48 | 1,546,300 | 119,418,638 | 1.03% | $16.97B | — | — |
| 2026-10-06 | $111.94 | $112.71 | $109.40 | $112.10 | 967,200 | 119,418,638 | 0.65% | $16.76B | — | — |
| 2026-10-05 | $112.48 | $114.43 | $111.33 | $111.58 | 1,477,600 | 119,418,638 | 0.99% | $16.68B | — | — |
| 2026-10-02 | $113.03 | $114.46 | $111.32 | $112.89 | 1,553,900 | 119,418,638 | 1.04% | $16.88B | — | — |
| 2026-10-01 | $109.09 | $112.08 | $107.67 | $110.67 | 2,564,200 | 119,418,638 | 1.71% | $16.55B | — | — |
| 2026-09-30 | $112.72 | $112.72 | $109.38 | $109.38 | 2,129,600 | 119,418,638 | 1.42% | $16.35B | — | — |
| 2026-09-29 | $111.61 | $114.23 | $111.30 | $112.06 | 1,111,300 | 119,418,638 | 0.74% | $16.75B | — | — |
| 2026-09-28 | $112.79 | $113.59 | $110.50 | $112.30 | 1,557,700 | 119,418,638 | 1.04% | $16.79B | — | — |
| 2026-09-25 | $113.81 | $117.59 | $113.12 | $113.18 | 1,531,500 | 119,418,638 | 1.02% | $16.92B | — | — |
| 2026-09-24 | $119.21 | $119.76 | $113.75 | $113.81 | 1,922,600 | 119,418,638 | 1.29% | $17.02B | — | — |
| 2026-09-23 | $118.45 | $120.57 | $116.20 | $119.22 | 1,438,200 | 119,418,638 | 0.96% | $17.82B | — | — |
| 2026-09-22 | $118.84 | $120.50 | $117.07 | $119.00 | 1,735,600 | 119,418,638 | 1.16% | $17.79B | — | — |
| 2026-09-21 | $121.39 | $121.41 | $116.03 | $117.60 | 1,681,700 | 119,418,638 | 1.12% | $17.58B | — | — |
| 2026-09-18 | $122.20 | $123.90 | $120.01 | $120.13 | 6,265,900 | 119,418,638 | 4.19% | $17.96B | — | — |
| 2026-09-17 | $124.15 | $124.44 | $120.24 | $122.37 | 2,105,200 | 119,418,638 | 1.41% | $18.29B | — | — |
| 2026-09-16 | $125.61 | $125.61 | $120.84 | $121.73 | 2,146,100 | 119,418,638 | 1.44% | $18.20B | — | — |
| 2026-09-15 | $129.67 | $129.89 | $122.63 | $126.94 | 1,523,800 | 119,418,638 | 1.02% | $18.98B | — | — |
| 2026-09-14 | $128.00 | $130.67 | $125.68 | $129.44 | 1,597,900 | 119,418,638 | 1.07% | $19.35B | — | — |
| 2026-09-11 | $124.59 | $128.88 | $124.28 | $128.31 | 1,488,300 | 119,418,638 | 1.00% | $19.18B | — | — |
| 2026-09-10 | $124.50 | $126.00 | $122.44 | $124.02 | 1,022,700 | 119,418,638 | 0.68% | $18.54B | — | — |
| 2026-09-09 | $127.98 | $129.50 | $124.16 | $124.79 | 1,371,600 | 119,418,638 | 0.92% | $18.66B | — | — |
| 2026-09-08 | $130.52 | $132.61 | $128.74 | $129.07 | 1,153,500 | 119,418,638 | 0.77% | $19.30B | — | — |
| 2026-09-04 | $126.31 | $131.55 | $126.27 | $129.45 | 1,128,800 | 119,418,638 | 0.76% | $19.35B | — | — |
| 2026-09-03 | $124.98 | $128.78 | $123.24 | $127.19 | 1,821,100 | 119,418,638 | 1.22% | $19.02B | — | — |
| 2026-09-02 | $127.50 | $129.39 | $125.89 | $126.60 | 1,121,700 | 119,418,638 | 0.75% | $18.93B | — | — |
| 2026-09-01 | $133.57 | $135.70 | $126.53 | $127.57 | 1,044,500 | 119,418,638 | 0.70% | $19.07B | — | — |
| 2026-08-31 | $132.81 | $135.23 | $131.61 | $133.74 | 1,460,300 | 119,418,638 | 0.98% | $19.99B | — | — |
| 2026-08-28 | $133.03 | $134.58 | $131.53 | $133.45 | 774,100 | 119,418,638 | 0.52% | $19.95B | — | — |
| 2026-08-27 | $131.50 | $133.98 | $130.30 | $133.25 | 925,800 | 119,418,638 | 0.62% | $19.92B | — | — |
| 2026-08-26 | $128.01 | $134.21 | $127.65 | $131.27 | 1,429,100 | 119,418,638 | 0.96% | $19.63B | — | — |
| 2026-08-25 | $132.53 | $133.31 | $128.71 | $128.75 | 1,135,600 | 119,418,638 | 0.76% | $19.25B | — | — |
| 2026-08-24 | $137.00 | $137.75 | $130.25 | $131.27 | 1,229,100 | 119,418,638 | 0.82% | $19.63B | — | — |
| 2026-08-21 | $138.18 | $140.24 | $135.38 | $137.32 | 722,400 | 119,418,638 | 0.48% | $20.53B | — | — |
| 2026-08-20 | $137.28 | $137.75 | $132.87 | $136.40 | 1,093,100 | 119,418,638 | 0.73% | $20.39B | — | — |
| 2026-08-19 | $141.00 | $145.26 | $138.04 | $138.17 | 1,131,200 | 119,418,638 | 0.76% | $20.66B | — | — |
| 2026-08-18 | $143.50 | $144.00 | $139.12 | $139.23 | 1,120,300 | 119,418,638 | 0.75% | $20.82B | — | — |
| 2026-08-17 | $149.00 | $149.00 | $143.73 | $143.82 | 1,263,200 | 119,418,638 | 0.84% | $21.50B | — | — |
| 2026-08-14 | $151.09 | $152.67 | $146.08 | $150.29 | 2,201,100 | 119,418,638 | 1.47% | $22.47B | — | — |
| 2026-08-13 | $142.02 | $152.02 | $140.70 | $151.99 | 3,146,700 | — | 2.10% | $22.72B | — | — |
| 2026-08-12 | $139.57 | $142.14 | $138.80 | $141.24 | 892,300 | — | 0.60% | $21.12B | — | — |
| 2026-08-11 | $140.69 | $143.83 | $138.10 | $139.51 | 975,600 | — | 0.65% | $20.86B | — | — |
| 2026-08-10 | $143.48 | $144.79 | $141.30 | $141.35 | 780,800 | — | 0.52% | $21.13B | — | — |
| 2026-08-07 | $146.56 | $150.00 | $142.97 | $144.76 | 1,328,900 | — | 0.89% | $21.64B | — | — |
| 2026-08-06 | $142.28 | $146.53 | $141.58 | $146.42 | 842,100 | — | 0.56% | $21.89B | — | — |
| 2026-08-05 | $143.06 | $145.91 | $142.55 | $143.03 | 846,200 | — | 0.57% | $21.38B | — | — |
| 2026-08-04 | $139.77 | $144.16 | $139.00 | $142.70 | 1,141,400 | — | 0.76% | $21.33B | — | — |
| 2026-08-03 | $141.00 | $144.70 | $139.00 | $139.02 | 637,800 | — | 0.43% | $20.78B | — | — |
| 2026-07-31 | $136.63 | $141.92 | $136.63 | $140.53 | 878,300 | — | 0.59% | $21.01B | — | — |
| 2026-07-30 | $144.59 | $147.33 | $135.64 | $137.55 | 1,563,100 | — | 1.05% | $20.56B | — | — |
| 2026-07-29 | $150.45 | $153.78 | $143.50 | $144.36 | 901,400 | — | 0.60% | $21.58B | — | — |
| 2026-07-28 | $150.13 | $153.64 | $147.45 | $150.99 | 757,800 | — | 0.51% | $22.57B | — | — |
| 2026-07-27 | $157.24 | $158.35 | $149.26 | $150.30 | 1,122,700 | — | 0.75% | $22.47B | — | — |
| 2026-07-24 | $155.15 | $159.04 | $149.44 | $158.00 | 1,255,300 | — | 0.84% | $23.62B | — | — |
| 2026-07-23 | $149.37 | $155.34 | $148.78 | $154.79 | 1,449,800 | — | 0.97% | $23.14B | — | — |
| 2026-07-22 | $149.63 | $152.27 | $148.11 | $149.32 | 599,400 | — | 0.40% | $22.32B | — | — |
| 2026-07-21 | $150.11 | $153.40 | $148.25 | $150.38 | 664,000 | — | 0.44% | $22.48B | — | — |
| 2026-07-20 | $152.00 | $154.59 | $148.41 | $150.14 | 831,700 | — | 0.56% | $22.45B | — | — |
| 2026-07-17 | $152.49 | $158.27 | $150.46 | $152.26 | 1,326,100 | — | 0.89% | $22.76B | — | — |
| 2026-07-16 | $143.93 | $153.29 | $141.19 | $152.43 | 1,531,700 | — | 1.02% | $22.79B | — | — |
| 2026-07-15 | $145.00 | $145.35 | $139.57 | $141.80 | 1,264,600 | — | 0.85% | $21.20B | — | — |
| 2026-07-14 | $148.14 | $149.05 | $144.09 | $144.75 | 1,799,300 | — | 1.20% | $21.64B | — | — |
| 2026-07-13 | $151.34 | $152.45 | $147.81 | $148.37 | 1,304,200 | — | 0.87% | $22.18B | — | — |
| 2026-07-10 | $155.66 | $156.70 | $147.19 | $149.53 | 1,305,700 | — | 0.87% | $22.36B | — | — |
| 2026-07-09 | $145.00 | $155.69 | $145.00 | $154.25 | 1,190,900 | — | 0.80% | $23.06B | — | — |
| 2026-07-08 | $144.10 | $146.37 | $140.67 | $143.30 | 1,323,400 | — | 0.89% | $21.42B | — | — |
| 2026-07-07 | $154.38 | $154.38 | $144.45 | $144.72 | 1,122,900 | — | 0.75% | $21.64B | — | — |
| 2026-07-06 | $151.06 | $156.18 | $150.50 | $152.68 | 985,100 | — | 0.66% | $22.83B | — | — |
| 2026-07-02 | $155.68 | $157.32 | $149.31 | $150.81 | 1,091,000 | — | 0.73% | $22.55B | — | — |
| 2026-07-01 | $151.00 | $156.49 | $148.33 | $155.77 | 2,519,600 | — | 1.69% | $23.29B | — | — |
| 2026-06-30 | $149.84 | $154.05 | $145.49 | $151.00 | 2,118,500 | — | 1.42% | $22.58B | — | — |
| 2026-06-29 | $152.49 | $154.94 | $147.46 | $149.69 | 1,978,200 | — | 1.32% | $22.38B | — | — |
| 2026-06-26 | $155.36 | $157.50 | $144.27 | $153.89 | 6,564,800 | — | 4.39% | $23.01B | — | — |
| 2026-06-25 | $161.02 | $164.13 | $157.75 | $158.53 | 1,217,500 | — | 0.81% | $23.70B | — | — |
| 2026-06-24 | $169.00 | $170.98 | $157.96 | $160.45 | 1,805,800 | — | 1.21% | $23.99B | — | — |
| 2026-06-23 | $162.00 | $171.66 | $161.00 | $166.47 | 1,694,400 | — | 1.13% | $24.89B | — | — |
| 2026-06-22 | $165.45 | $169.54 | $160.08 | $160.94 | 2,276,200 | — | 1.52% | $24.06B | — | — |
| 2026-06-18 | $165.00 | $167.42 | $160.10 | $162.85 | 3,231,500 | — | 2.16% | $24.35B | — | — |
| 2026-06-17 | $163.90 | $165.85 | $157.80 | $161.90 | 2,465,500 | — | 1.65% | $24.20B | — | — |
| 2026-06-16 | $162.10 | $167.02 | $160.02 | $163.84 | 1,914,300 | — | 1.28% | $24.49B | — | — |
| 2026-06-15 | $173.91 | $177.81 | $166.04 | $167.16 | 1,707,700 | — | 1.14% | $24.99B | — | — |
| 2026-06-12 | $180.54 | $182.00 | $168.11 | $174.76 | 1,477,800 | — | 0.99% | $26.13B | — | — |
| 2026-06-11 | $177.00 | $188.33 | $177.00 | $180.00 | 1,894,500 | — | 1.27% | $26.91B | — | — |
| 2026-06-10 | $175.50 | $186.11 | $169.99 | $175.35 | 2,595,700 | — | 1.74% | $26.22B | — | — |
| 2026-06-09 | $178.12 | $194.27 | $178.12 | $188.46 | 2,448,900 | — | 1.64% | $28.18B | — | — |
| 2026-06-08 | $167.02 | $183.00 | $166.13 | $178.77 | 1,759,900 | — | 1.18% | $26.73B | — | — |
| 2026-06-05 | $157.48 | $175.00 | $157.48 | $167.84 | 2,924,900 | — | 1.96% | $25.09B | — | — |
| 2026-06-04 | $150.66 | $166.27 | $150.66 | $157.71 | 2,928,400 | — | 1.96% | $23.58B | — | — |
| 2026-06-03 | $152.30 | $153.21 | $145.01 | $152.00 | 4,596,400 | — | 3.07% | $22.72B | — | — |
| 2026-06-02 | $150.01 | $158.49 | $149.11 | $153.34 | 4,482,500 | — | 3.00% | $22.93B | — | — |
| 2026-06-01 | $164.00 | $166.90 | $141.33 | $149.53 | 7,419,200 | — | 4.96% | $22.36B | — | — |
Close is split-adjusted to current shares. It is not dividend-adjusted: dividends are listed separately, so total return is (end price + dividends received − start price) ÷ start price, checkable by hand. Volume is as-traded.
Momentum: MACD and RSI
Top: MACD (navy) and its signal line (gold); bars show the gap between them, teal when MACD is above.
Bottom: RSI over 14 days; above 70 is usually read as overbought and below 30 as oversold.
The lines start late because MACD needs 26 trading days of prices and RSI 14 before the first value.
The colored strip under the charts shows the state label day by day; hover for the state and the reason.
Both measure momentum in the price and say nothing about value. Hover for each day's arithmetic.
Source: closing prices from this site's daily price archive (Yahoo Finance), not adjusted for dividends. Data through Nov 14, 2026.
How these are calculated
Short Selling
Bars: shares sold short each day in trades reported to FINRA (off-exchange
trades, roughly half of all volume).
Line: the short share of that volume, averaged over 20 sessions.
Gold points: short interest, the shares sold short and not yet bought back,
reported twice a month, also shown as a percentage of the free float and of
shares outstanding.
Daily short volume includes market makers' routine hedging, so a change in the
share is more informative than its level. Hover for each day's figures.
Sources: FINRA; float from this site's daily share records; shares outstanding
from the company's latest quarterly filing. Data through Nov 13, 2026.
Index-Fund Holdings
Daily positions of State Street's SPDR index funds, by the fund's file date.
These are the index funds whose daily holdings can be collected; iShares and
Vanguard funds, often larger holders, publish holdings that cannot be
collected automatically and appear in the written analysis from their
quarterly filings.
Collection began on October 11, 2026. A fund that drops the stock shows as an
exit.
Source: State Street Global Advisors. Data through
Nov 12, 2026.
Update — October 30, 2026: transition-period results, how the money moves, the debt, where FedEx Freight is, and the asymmetry — HOLD → TRIM, target $108 → $112
Written against the October 30, 2026 close of $126.04, up 14.9% on the day after the results. Sources: the results release, the recast calendar quarters and the 10-Q for the period to September 30, 2026, all filed October 29, 2026; the investor presentation and the call transcript; the term loan and revolving credit agreements, the indenture, the tax matters agreement and the stockholder agreement with FedEx; FedEx’s own 10-Q of October 28, 2026; FINRA short interest, Form 13F and N-PORT holdings, and FedEx Freight’s published list of service centers. The analysis of August 24, 2026 is left as published. This section adds the first results as a standalone company, the debt and covenants, the network, three scenarios with weights, and who has been trading, and it corrects two figures about FedEx’s retained stake. The rating moves from HOLD to TRIM and the target from $108 to $112.
The one-line version
The results confirmed the company’s plan, and the stock has priced it in. In the four months to September 30, 2026, revenue rose 9.2% and the adjusted operating ratio was 84.5%; shipments turned positive in September for the first time in 2026, and management said 2027 will be “broadly consistent” with its medium-term framework of 4–6% revenue growth and 10–12% profit growth. Three cases on the published method give best $143.67, base $115.88 and worst $78.48; the base case is the company’s own framework. Weighted 20 / 55 / 25, the value is $112.09, −11% against the close, with 20 cents of probability-weighted gain for each dollar of loss. The price implies about 41% on the best case, a return to an operating ratio of about 82% that FedEx Freight reached only in 2023 and 2024. The debt is investment grade and covenant-light: $4.4 billion, 88% fixed, the first $1.5 billion due in 2029, leverage of 2.61× against a limit that tightens to 3.50× in January 2027. The overhang has a date: FedEx said on October 28, 2026 that it expects to sell all 29,751,545 retained shares, 19.9% of the company, by about September 30, 2027.
What happened since August 24
| Date | Event | What it means |
|---|---|---|
| September 2, 2026 | The chief commercial officer, Michael Lyons, was terminated for a breach of the code of conduct (8-K) | The head of pricing left during the contract-renewal season; analysts cited it in cuts that month |
| September 10, 2026 | Bernstein started coverage at Market Perform, $133 (Investing.com) | The bear argument: yield behind peers, a mix of small accounts, more leased terminals |
| September 18, 2026 | 6.27 million shares traded, four times a normal day, on the quarterly index rebalance and options expiry | The largest volume since June |
| September 29, 2026 | BofA cut its target from $157 to $140, keeping Buy (Investing.com) | Weaker shipments, the commercial officer’s exit, thin disclosure |
| September 30, 2026 | Close of $109.38, then the low since the spin; short interest rose to 5.5 million shares | Down 27% from the first day’s $149.53 |
| October 5, 2026 | C.H. Robinson agreed to buy RXO for $30.25 a share, about $5.8 billion (release) | A larger freight broker buying from less-than-truckload carriers; a small negative for carriers’ pricing |
| October 7, 2026 | The credit agreements were amended to add back stock compensation to covenant EBITDA (described in the 10-Q) | More room under the leverage covenant |
| October 8 and 15, 2026 | Stifel cut its target from $160 to $129; Raymond James from $180 to $165 | Targets fell into the results |
| October 28, 2026 | FedEx’s 10-Q: “We expect to fully monetize our remaining stake in FedEx Freight within 12 months from the balance sheet date, subject to market conditions.” The shares touched $103.48 during the day | The sale moves from a June 2028 deadline to about September 2027 |
| October 29, 2026 | Results for the four months to September 30, 2026, after the close | Below |
| October 30, 2026 | The shares rose 14.9% to $126.04 | Below |
The results and what management said
The four months to September 30, 2026 (the company moved its year-end from May 31 to December 31; the transition period runs June to December 2026):
- Revenue $3,281 million, up 9.2%. Average daily shipments fell 1.4%, weight per shipment rose 1.3%, and revenue per hundredweight rose 8.6%, of which 0.3% was base price and the rest fuel surcharges.
- Adjusted operating income $510 million, up 16.4%; adjusted operating ratio 84.5%. Reported operating income was $383 million after $127 million of separation costs.
- Free cash flow $239 million: operating cash flow of $390 million less $151 million of capital spending.
- Calendar third quarter: revenue $2,442 million and adjusted operating income $358 million, an adjusted operating ratio of 85.3%.
- Monthly shipments against 2025: −7.6% in January, −5.2% in May, −2.2% in July, −0.7% in August and +0.9% in September.
The guidance for October–December 2026 is revenue of $2.30–2.37 billion and adjusted operating income of $185–205 million, an operating ratio of about 91.6% in the seasonally weakest quarter (92.2% a year earlier). The company’s bridge for the quarter adds 4.25 points of margin from net yield, “largely fuel”, and takes away 2.7 points for incentive pay and 0.85 points for the transition services FedEx still provides. Calendar 2026 therefore ends at an adjusted operating ratio of about 87.8%, against 86.0% in 2025 and 83.2% in 2024.
On the call:
- Pricing. The chief executive, John Smith: “Since June 1, we have successfully renewed approximately 25% of our contractual portfolio and achieved our strongest renewal pricing performance in recent years.” No percentage was given. The general rate increase of 6.9% on January 8, 2027 applies to “approximately 1/3 of our revenue base.” The chief financial officer, Marshall Witt, on base price: “took a while for us to lose it. It is going to take a while for us to gain it”, with the aim of getting back to the peer average.
- 2027. Witt: growth and margins “broadly consistent with the medium-term framework”, with incremental margins of “roughly 30%… at or slightly better than that in 2027”; figures in January 2027.
- Costs of the separation. Transition services from FedEx cost about $7 million a month, down from $9–9.5 million, and run into the first half of 2027.
- Capital. Capital spending of about $365 million for June–December 2026 and about 5% of revenue over the medium term; debt repayment toward gross leverage of about 2.5 times; a dividend and buyback plan “in January… subject to board approval”, with buybacks intended to offset share issuance.
- Not discussed: FedEx’s retained stake, terminal counts and 2027 capital spending.
Against peers, FedEx Freight’s base price is the weak point. Revenue per hundredweight excluding fuel rose 0.3%, against 5.1% at Old Dominion and 3.6% at XPO; Saia reported contract renewals of 10.8%. Peers’ October updates showed volumes turning up: Old Dominion’s tons per day +1.6% with yield up 5.5–6%, XPO’s shipments up in the mid-7% range, Saia’s tonnage up 10%. TFI International, whose U.S. business runs at an operating ratio of about 97%, reported a 43% fall in less-than-truckload operating income the same evening.
Why the stock rose 14.9% on October 30
Following the site’s method for results-day moves:
- Against the right baseline. From the first day of trading to October 29, 2026 the shares fell 26.6%, in line with Old Dominion (−24.6%), Saia (−28.9%) and TFI (−28.0%) and well below transportation stocks as a whole (IYT −3.8%) and the S&P 500 (+1.4%). The October 30 rise came on a day when TFI International fell 17.1% on its own results, Old Dominion moved +0.1%, Saia +0.4% and XPO +3.6%, transportation stocks flat, and the S&P 500 −1.8%, so the move was FedEx Freight’s own.
- The print. Earnings of $1.49 a share for the calendar third quarter against a consensus of about $1.38, and a fourth-quarter guide above expectations (Reuters via Investing.com). The quality of the beat is mixed: the margin gain in the fourth-quarter bridge is mostly fuel, which reverses if diesel falls.
- The next-year language. “Broadly consistent with the medium-term framework” was the first statement that 2027 is on plan. Jefferies called the targets “becoming more achievable” while cutting its target from $200 to $180; JPMorgan raised its target from $149 to $151 and Evercore ISI from $135 to $139. After the results the average of 14 targets was $145.43 and the median $140.50 (stockanalysis.com).
- Positioning. Short interest had tripled since June, to 6.30 million shares on October 15, 2026, 4.4 days of trading. A short base that size covering into a beat adds to a move like this (an inference; no published source attributes the move to it).
- Against the model. The base case already is the company’s framework, so the call confirmed it. The market is resetting from a price near the worst case (the October 28 low of $103.48 was about $25 above it) to one above the base case. The results leave the cases where they were; renewal pricing without a percentage and a fourth quarter carried by fuel are the open questions for January 2027.
How the money moves
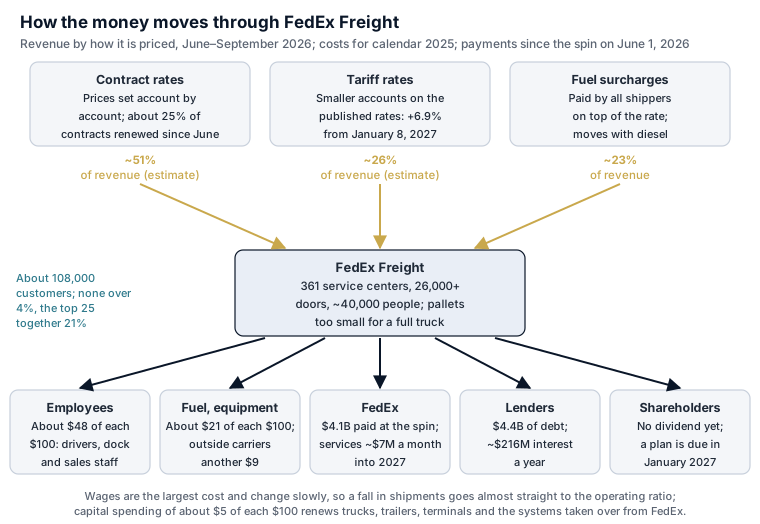
Who pays:
- About 108,000 customers, none above 4% of revenue; the top five took 9% and the top 25 took 21% in the year to May 31, 2026. FedEx itself paid $158 million, about 1.8%, for freight it hands over.
- Revenue by how it is priced, June–September 2026, adding to 100%: fuel surcharges about 23%, contract rates about 51% and tariff rates about 26% (estimates: management said the January rate increase applies to about a third of revenue, and that third is applied here to revenue before fuel).
- Contract rates are renewed account by account through the year; about a quarter of the contracts were renewed between June 1 and October 29, 2026.
- Tariff rates, paid mostly by smaller accounts, rise 6.9% on January 8, 2027.
- Fuel surcharges were $10.10 of $44.03 per hundredweight in the four months to September 30, 2026, up from about 16% of revenue a year earlier. They are paid on top of both kinds of rate, follow the diesel price with a short lag, and the company has no fuel hedges.
Where each $100 of revenue went, calendar 2025 (Calendar 2025, as recast, with standalone interest, tax and capital spending estimated). On a standalone basis about $9 of each $100 became free cash flow in 2025, about $790 million (an estimate). The four months to September 30, 2026 produced $239 million of reported free cash flow, about $7 per $100, after separation costs and a working-capital build of $120 million. People are almost half the cost: salaries and benefits took about $48 of each $100, which is why volume matters so much in a downturn. The company’s target is free cash flow above $1 billion by 2029. Separation costs, about $230 million in the seven months to December 2026, and transition-services fees to FedEx of about $7 million a month into the first half of 2027 are not in the recurring figure. Source: the calendar-year 2025 and 2024 recast and the 10-Q to September 30, 2026; per-$100 figures are calculations.
Wages are the cost that decides the margin. Salaries and benefits took about $48 of each $100 in 2025. They move with headcount and hours, which management adjusts with a lag, so a fall in shipments goes largely to the operating ratio; the 2022–2026 downturn took it from 80% to 88%.
The debt, tranche by tranche
| Tranche | Amount ($M) | Rate | Matures | Repaying early | Security | Notes |
|---|---|---|---|---|---|---|
| 4.300% notes | 1,000 | 4.300% fixed | March 15, 2029 | Make-whole (Treasuries + 0.10%); par from February 15, 2029 | Senior unsecured | |
| Delayed-draw term loan | 500 | SOFR + 1.00–1.75% by rating (1.25% at BBB-/Baa3); 5.15% at September 30 | May 25, 2029 | At any time at par (breakage only); no amortization | Senior unsecured | $600M drawn May 27, 2026; $100M prepaid; repaid amounts cannot be redrawn |
| 4.650% notes | 1,000 | 4.650% fixed | March 15, 2031 | Make-whole (T + 0.15%); par from February 15, 2031 | Senior unsecured | |
| 4.950% notes | 700 | 4.950% fixed | March 15, 2033 | Make-whole (T + 0.15%); par from January 15, 2033 | Senior unsecured | |
| 5.250% notes | 1,000 | 5.250% fixed | March 15, 2036 | Make-whole (T + 0.20%); par from December 15, 2035 | Senior unsecured | |
| Finance leases | 255 | 4.89% weighted average | Weighted average 6.1 years | — | The leased assets | $45M current |
| Total drawn | 4,455 | 4.82% (the 10-Q’s weighted rate on the notes and term loan); 88% fixed | ||||
| Five-year revolving credit | $1.2B | SOFR + 1.00–1.75% by rating; commitment fee 0.09–0.25% | June 1, 2031 (extendable) | Senior unsecured | Undrawn at September 30, 2026; $50M letter-of-credit sub-limit; $600M accordion |
FedEx Freight borrowed $4.3 billion before the spin and paid FedEx $4,122 million in cash on June 1, 2026; in December 2025 it had also paid FedEx about $1.0 billion to buy back receivables FedEx had been factoring. The notes are senior unsecured, guaranteed by FedEx Freight, Inc. and FedEx Custom Critical; FedEx’s own guarantee fell away at the spin. $100 million of the term loan was prepaid in the four months to September 30, 2026. Ratings: BBB- (S&P) and Baa3 (Moody’s), the lowest investment grade. Cash was $388 million, so net debt was $4,033 million including finance leases. Operating leases of $1,841 million and about $280 million of build-to-suit leases not yet started are not in the table. Source: the indenture, the term loan agreement, the revolving credit agreement, the FY2026 10-K and the 10-Q to September 30, 2026, Note 7. As of September 30, 2026.
Principal due by year, including scheduled amortization. The term loan and the first notes fall due together in 2029: $1.5 billion, about 1.4 years of free cash flow at the company’s 2029 target of more than $1 billion. Finance leases are shown by year in proportion to the 10-K’s payment schedule (an estimate).
$4.4 billion of debt, investment grade at the lowest rung, borrowed to pay FedEx. $3.7 billion is fixed-rate notes due 2029–2036, $500 million a floating term loan due May 2029, and $255 million finance leases. The $1.2 billion revolver is undrawn. FedEx Freight paid FedEx $4,122 million in cash at the spin, on top of about $1.0 billion in December 2025 to buy back receivables FedEx had been factoring.
FedEx Freight can repay everything due to 2033 from its own cash (estimates, $ billions; free cash flow after interest and tax from the model, before dividends and buybacks):
| Base case | Worst case | |
|---|---|---|
| Free cash flow, October–December 2026 (separation costs, capital spending of about $214 million) | − ~$0.10B | − ~$0.10B |
| Free cash flow, 2027–2033 | + ~$7.05B | + ~$4.52B |
| Cash at September 30, 2026 | + $0.39B | + $0.39B |
| Available to repay debt | = ~$7.34B | = ~$4.81B |
| Notes and term loan due 2029–2033, and finance leases | − $3.46B | − $3.46B |
| Left after repaying them, before dividends and buybacks | = ~$3.88B | = ~$1.35B |
The 2029 wall is the only tight point. $1.5 billion falls due between March and May 2029. In the base case free cash flow over 2027 and 2028, about $1.7 billion, covers it; in the worst case it is about $1.1 billion, and part of the 2029 maturities would be refinanced or drawn on the revolver.
Interest expense, 2027–2033
Interest expense, $ millions, by the rate on the replacement notes (estimates; the term loan on the futures path for SOFR plus 1.25%):
| Refinancing rate | 2027 | 2028 | 2029 | 2030 | 2031 | 2032 | 2033 |
|---|---|---|---|---|---|---|---|
| 4.5% | ~$220 | ~$223 | ~$222 | ~$219 | ~$218 | ~$218 | ~$215 |
| 5.5% | ~$220 | ~$223 | ~$233 | ~$234 | ~$241 | ~$243 | ~$246 |
| 6.5% | ~$220 | ~$223 | ~$244 | ~$249 | ~$264 | ~$268 | ~$277 |
The company guides to about $55 million for October–December 2026, which the model reproduces. A one-point move in SOFR changes 2027 interest by about $5 million, about 2.5 cents a share after tax. Source: model in the site’s analysis files, from the terms of the notes and the term loan.
| Covenant | Limit | Now | Room | Protects |
|---|---|---|---|---|
| Total leverage (total debt less unrestricted cash up to $250 million, over consolidated EBITDA for four quarters) | 3.75× at most for quarters ending before January 1, 2027; 3.50× from then on; 4.00× for four quarters after an acquisition of $500 million or more | 2.61× at September 30, 2026 (the 10-Q) | EBITDA could fall about 25% before 3.50× (an estimate: about $1.61 billion of covenant EBITDA). In the worst case, 2027 ends near 3.0× with no debt repaid (an estimate), under the limit by about 0.5× | Term loan and revolver; the lenders can accelerate on a breach |
| Dividends and buybacks (credit agreements) | Restricted only while an event of default continues | None paid; a 2027 dividend and buyback plan is due in January 2027, subject to the board | — | Term loan and revolver |
| Change of control | An event of default under the bank agreements if anyone reaches 40% of the vote or the board changes majority; noteholders can put at 101% only if a change of control comes with a downgrade below investment grade by both S&P and Moody’s | FedEx holds 19.9% and must vote it in proportion to other holders | — | Bank agreements; indenture |
| Mergers, share issuance and buybacks (tax matters agreement with FedEx) | From June 1, 2026 to June 1, 2028: no merger or acquisition proposal for the company, no sale of more than 20% of gross assets, no headcount cut over 20% in the active business, and buybacks only within the IRS safe harbor for open-market repurchases, unless FedEx consents or a tax opinion is obtained; the indemnity to FedEx is uncapped | In force | — | Tax matters agreement |
The covenant’s EBITDA adds back non-cash pension cost, impairments, stock compensation (from an October 7, 2026 amendment described in the 10-Q but not filed) and up to $400 million of spin costs, so it is larger than reported EBITDA. The notes carry no financial covenant beyond a limit on secured debt of 15% of total assets.
Other obligations that behave like debt:
| Item | Amount | Note |
|---|---|---|
| Operating leases | $1,841M | About 250 of the roughly 365 locations are leased |
| Leases signed but not started | ~$280M | Mostly build-to-suit terminals, starting 2027–2028 |
| Pension | $22M net liability | A new plan split from FedEx’s on June 1, 2026, $7M underfunded at transfer; gains and losses are booked each fourth quarter |
| Tax indemnity to FedEx | Uncapped | Applies if FedEx Freight’s own actions make the spin taxable |
Where FedEx Freight is
A national network of about 365 locations, by the 10-K: about 115 owned and 250 leased, of which about 355 are terminals that handle freight (more than 320 in the United States) and about 10 are relay points for linehaul drivers. They hold more than 26,000 doors, which the company describes as the most in the industry, and nearly 30,000 vehicles, about 17,000 of them tractors. About 40,000 people work there.
| Carrier | Terminals | Source |
|---|---|---|
| FedEx Freight | ~355 (361 service centers on its list) | 10-K; company location pages, October 30, 2026 |
| XPO (North America) | 356 facilities | 10-K |
| Estes | over 300 | Trade press |
| Old Dominion | 260 | 10-K |
| ArcBest (ABF) | 229 | 10-K |
| Saia | 213 | 10-K |
The network
The 361 service centers on the company’s own list: 328 in the United States (including Alaska, Hawaii and Puerto Rico), 14 in Canada and 19 in Mexico. The 10-K counts about 365 locations, about 115 owned and 250 leased, with more than 26,000 doors. Points are at the postal code, so terminals in the same city overlap. Click a point for details. Map data © OpenStreetMap contributors. Source: FedEx Freight’s service center locations, retrieved October 30, 2026, placed by postal code with OpenStreetMap; counts from the FY2026 10-K, Item 2. As of October 30, 2026.
Every one of the 361 service centers on the company’s own list, placed by postal code: 328 in the United States (including Alaska, Hawaii and Puerto Rico), 14 in Canada and 19 in Mexico. California (30) and Texas (26) have the most, then Illinois (15), Ohio and Pennsylvania (13 each). Mexico’s centers may be run with a partner; the sources found do not say.
Headquarters and the largest terminals
FedEx Freight does not publish which terminals are its main sorting hubs or how many doors each has. Door counts here come from company and trade-press reports and carry their year. Since 2024 it opened Greenwood, Indiana (125 doors) and a new Sioux Falls terminal, closed seven small terminals, and bought one terminal from the Yellow bankruptcy, at Sparks, Nevada, for $22.47 million. Click a point for details. Map data © OpenStreetMap contributors. Source: the FY2026 10-K, FedEx Freight’s location pages, FedEx newsroom releases and trade press (door counts with their year); points placed with OpenStreetMap. As of October 30, 2026.
Memphis is the headquarters; Harrison, Arkansas, the old American Freightways home, still holds administrative offices. The largest terminals with published door counts are Denver (Commerce City), West Phoenix, Nashville (Antioch), North Dallas (Lewisville) and Joliet, each with roughly 170–280 doors in reports from 2003 to 2022; FedEx Freight does not publish which are its main sorting hubs. Since 2024 it opened new terminals at Greenwood, Indiana, and Sioux Falls, South Dakota, closed seven smaller ones, and bought one terminal from the Yellow bankruptcy, at Sparks, Nevada, for $22.47 million in January 2024. Its peers bought far more: XPO 28 terminals, Estes 52 and Saia 28 owned or leased.
The scenarios and the asymmetry
The August 24, 2026 valuation was a single case: a mid-cycle adjusted operating ratio of 85% on about $9.3 billion of revenue, depreciation at 5.8% of revenue, at 11 times EBITDA, weighted 75% with a discounted cash flow at 11% (25%), for $108. The model was rebuilt on that method and reproduces $108.44 with the published inputs. It now runs three cases on calendar years, with 2026 at the company’s guidance (revenue $9,339 million, an adjusted operating ratio of 87.8%). Every case uses the same 11% discount rate and 11 times multiple, so the differences come from the business.
| Best | Base | Worst | |
|---|---|---|---|
| What has to happen | Volumes grow again in 2027 and renewals keep pricing firm | The company’s framework | A 2027 freight recession |
| Revenue growth, 2027 / 2028 / after | 6.5% / 6% / 4% | 5% / 4.5% / 3% | −4% / 0% / 2.5% |
| Adjusted operating ratio, 2027 / 2028 | 86% / 84% | 87% / 86% | 89.5% / 89% |
| Mid-cycle operating ratio, from 2029 | 82% | 85% | 88% |
| Value per share | $143.67 | $115.88 | $78.48 |
| Against $126.04 | +14% | −8% | −38% |
How the cases tie to the record: 82% is two points short of the 80% of fiscal 2023 and 2024, the post-pandemic peak and the year Yellow failed; 85% is the published mid-cycle and the company’s 2029 target of about 15% margin; 88% is near this year’s ratio and inside the 87.2–93.9% of the five years before fiscal 2022. In 2008–2009 FedEx Freight lost money for two years and peers’ ratios rose 5–12 points, so the worst case is a moderate recession; a repeat of 2008–2009 would be worse.
The base value is higher than August’s $108 for one main reason: the mid-cycle multiple is now applied to 2028’s revenue, the year the base case reaches its framework margin, which adds about $10 a share. Depreciation is carried at 5.0% of revenue, the rate of the last four months (4.6–4.7%) rounded up, rather than 5.8%, which takes about $4.50 away. The rest is the discounted cash flow, now on the guided 2026.
| Change to the base case, one at a time | Value | Change |
|---|---|---|
| The framework a year late, settling at 86% | $104.07 | −$11.81 |
| Multiple 10× | $105.64 | −$10.25 |
| A flat 2027 (revenue 0%, ratio 88.5%), then the base path | $108.19 | −$7.70 |
| Mid-cycle operating ratio 86% | $108.57 | −$7.32 |
| Diesel falls: 2027 revenue flat, base margins | $109.09 | −$6.80 |
| Growth 1 point a year slower | $112.04 | −$3.85 |
| Discount rate 12% | $114.31 | −$1.58 |
| Discount rate 10% | $117.57 | +$1.69 |
| Growth 1 point a year faster | $119.84 | +$3.96 |
| Mid-cycle operating ratio 84% | $123.20 | +$7.32 |
| Multiple 12× | $126.13 | +$10.25 |
The operating ratio and the multiple decide the value; each point of mid-cycle ratio is worth about $7.30 a share, and each turn of multiple about $10. The discount rate matters little, because three-quarters of the value comes from the multiple.
Three weightings, and what the price implies:
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $113.48 | −10% | 0.26 to 1 |
| Best guess: 20 / 55 / 25 | $112.09 | −11% | 0.20 to 1 |
| Stress: 10 / 40 / 50 | $99.96 | −21% | 0.06 to 1 |
| What the price implies: 41% / 55% / 4% | $126.04 | 0% | 1.0 to 1 |
The weights are a judgment. All values are estimates from the rebuilt model.
Why the best guess leans away from the best case. Each case stands for a range of 2028–2029 operating ratios: 82% or better, about 12% likely on the evidence; 82–84%, about 18%; 84–86%, the company’s plan, about 35%; 86–88%, about 20%; above 88%, about 15%. Splitting each band next to the base case gives about 20 / 55 / 25.
- The best case needs about twice the guided profit growth. An operating ratio of 82% by 2029 requires adjusted operating income of about $2.0–2.2 billion, growth of about 19–24% a year, against the company’s 10–12%. FedEx Freight’s base price is three to five points behind its peers’, and it has just lost its chief commercial officer. The best case gets 20%, below the standard 25%.
- The worst case keeps its 25%. The ratio is near 88% now and about 91.6% in the fourth quarter; the fourth quarter’s margin gain is fuel, which reverses if diesel falls; the September ISM survey’s prices index was 77.9, a stagflation risk; TFI’s loss-making U.S. business could cut prices; and a larger C.H. Robinson buys freight more cheaply.
- The evidence for the middle: nine months of expanding manufacturing (ISM 54.5 in September 2026), Cass shipments up 1.9% in September 2026 after three and a half years of decline, peers’ October volumes up 1.6–10% with pricing up 5–6%, FedEx Freight’s own shipments positive in September, and a 6.9% rate increase.
- What would move the weights: toward the best case, a renewal percentage in January 2027 near peers’ 5–10% and fourth-quarter base price above 2%; toward the worst case, ISM readings below 50 in October or November 2026, or a fall in diesel.
What the price implies. Holding the base case at its 55% weight, the price is matched by the best-case weight that solves
best weight × $143.67 + 55% × $115.88 + (45% − best weight) × $78.48 = $126.04
which gives a best weight of ($126.04 − $63.74 − $35.32) ÷ ($143.67 − $78.48) = $26.99 ÷ $65.19 = 41%, leaving 4% on the worst case. The market is pricing a recession as unlikely and a return to the 2023–2024 margins as about twice as likely as the evidence suggests. The same reverse calculation on single assumptions gives the base path with a mid-cycle ratio of about 83.6% instead of 85%, or the base case at 12.0 times instead of 11.
The asymmetry on the best guess:
| Measure | At $126.04 | What it means |
|---|---|---|
| Expected return (header chip) | −11% | The probability-weighted value, $112.09, against the price |
| Gain to loss (header chip) | 0.20 to 1 | +$3.53 of probability-weighted gain against −$17.48 of loss |
| Expected base-case gain ÷ expected worst-case loss | No gain | The base case is below the price, so only the best case gains |
| Best-case gain ÷ worst-case loss | 0.37 to 1 | +$17.63 against −$47.56 |
How the measures are calculated. Gain = case value − price; loss = price − case value. Weights are the best guess: 20% best, 55% base, 25% worst.
| Measure | Formula | At $126.04 |
|---|---|---|
| Expected return | (20% × best + 55% × base + 25% × worst) ÷ price − 1 | ($28.73 + $63.74 + $19.62) ÷ $126.04 − 1 = −11% |
| Gain to loss | (20% × best gain) ÷ (55% × base loss + 25% × worst loss) | $3.53 ÷ ($5.59 + $11.89) = 0.20 |
| Best ÷ worst | best gain ÷ worst loss | $17.63 ÷ $47.56 = 0.37 |
| Price-implied best weight, base at 55% | (price − 55% × base − 45% × worst) ÷ (best − worst) | $26.99 ÷ $65.19 = 41% |
Both header chips take the color of the rating band the price is in. On the best guess, the price is in the BUY band below $89.67 (where gain to loss is above 3 to 1; it reaches 3 to 1 at $100.89), ACCUMULATE up to $101.90, HOLD up to $124.55, TRIM up to $149.45 and SELL above. Gain to loss is 2 to 1 at $105.37 and 1 to 1 at $112.09.
Who has been trading FedEx Freight
Closing prices rebased to June 1 = 100. Baskets are equal-weighted: less-than-truckload carriers (Old Dominion, Saia, XPO, ArcBest, TFI International); FedEx, the former parent; transportation and the S&P 500 through their ETFs (IYT, SPY). Source: Yahoo Finance closes.
FedEx Freight fell with the other less-than-truckload carriers. To October 29, 2026 it tracked the group closely, while the transportation ETF and the S&P 500 were roughly flat, so most of the fall was the industry’s freight recession and its valuation. FedEx, the former parent, held up better.
Daily volume (bars) and cumulative volume as a share of the 149.52 million shares outstanding (line). Gold bars mark days with a notable event; hover over one to see what happened. Source: this site's daily price archive (Yahoo Finance), through Oct 30, 2026.
About 122% of the shares have changed hands since the spin, about a third of it in June, when FedEx holders who did not want a freight carrier sold. From July the median day was about 1.3 million shares. The largest day since June was the September 18, 2026 index rebalance, at 6.3 million; October 30, 2026 traded 3.6 million.
Index membership now. FedEx Freight went straight into the S&P 500 at the spin, replacing EPAM Systems, and into the Dow Jones Transportation Average, replacing American Airlines (S&P Dow Jones Indices).
| Index | Member | Evidence |
|---|---|---|
| S&P 500, and S&P 500 Value (100% value) | Yes | SPDR holdings files, October 29, 2026; SPY holds 1.46M shares. The weight implies a float factor of about 0.80, excluding FedEx’s stake |
| S&P 500 Growth, S&P 100, MidCap 400 | No | Not held by SPYG, OEF or MDY |
| Dow Jones Transportation Average | Yes | S&P notice; price-weighted, so little fund money follows it |
| S&P Transportation Select Industry (XTN), S&P U.S. Spin-Off Index (CSD), IYT | Yes | 2.52%, 4.58% and 1.95% weights |
| Russell 1000, Russell Midcap and their value indexes | Yes | IWB, IWR (449,564 shares), IWD and IWS holdings |
| Russell growth indexes, Russell 2000 | No | Not held by IWF, IWP or IWM |
| CRSP U.S. Small Cap and Small Cap Value | Yes, at June 30, 2026 | Vanguard Small-Cap (2.46M shares) and Small-Cap Value (1.56M); unusual for its size, and not confirmed after September |
| MSCI USA (probably the mid-cap segment) | Yes | ACWI and MSCI USA factor ETFs |
| FTSE Global All Cap | Probably | Vanguard Total World holds it |
Registered index funds hold about 22 million shares, about 18% of the shares FedEx does not own (an estimate from N-PORT filings and ETF files at mixed dates).
What could move it in the next year:
| Event | When | Which way | Size (estimates) | Likelihood (a judgment) |
|---|---|---|---|---|
| FedEx sells its 19.9% | FedEx expects by about September 30, 2027; the tax deadline is June 1, 2028 | Index funds buy as the float rises by about 25%; the market absorbs the rest | Index buying of 5.5–8.9M shares; net supply of about 21–24M shares, 11–16 days of volume | Likely within 12 months: FedEx’s stated expectation, subject to market conditions |
| MSCI USA Momentum deletion | Announced November 11, effective November 30, 2026 | Selling | About 0.2M shares, 0.1 day | About 60% |
| S&P style rebalance (value to partly growth) | Announced about December 4, effective about December 21, 2026 | Two-way, about zero net | Under 0.2M shares | About 25% |
| CRSP move from small to mid cap | A quarterly rebalance | Net selling | About 1.1M shares net, 7M gross | Under 10% |
| Russell reconstitution | Rank day October 30, effective December 11, 2026 | None expected | About zero | Under 2% |
How FedEx sells decides the price effect. A sale to the market, through an underwritten offering or an exchange with FedEx’s lenders, leaves about 21–24 million shares for active buyers after index funds take their part. A distribution to FedEx’s own shareholders would place most of the shares with funds that already hold FedEx Freight in proportion, with less net selling. FedEx carried the stake at $109.38 a share on September 30, 2026, after a $1,238 million unrealized loss in the quarter. No registration for a resale has been filed yet.
Holders. The biggest holders at June 30, 2026 (Form 13F; FedEx files no 13F):
| Holder | Shares | % of company | Change from the implied day-one position |
|---|---|---|---|
| FedEx (13G) | 29,751,545 | 19.9% | Retained at the spin |
| BlackRock (13G at September 30, 2026: 8,843,510) | 9,078,495 | 6.1% | −3% |
| Dodge & Cox | 7,182,771 | 4.8% | +44% |
| Vanguard (13G: 8,194,621) | 7,059,822 | 4.7% | +2% |
| Vanguard Portfolio Management | 4,856,936 | 3.2% | +36% |
| PRIMECAP | 4,048,660 | 2.7% | −2% |
| Invesco | 3,470,101 | 2.3% | +115% (mostly the equal-weight S&P 500 fund) |
| Viking Global | 2,366,634 | 1.6% | +145% |
| Slate Path Capital | 2,247,200 | 1.5% | New |
| Point72 | 1,199,248 | 0.8% | New |
| Fidelity | 1,330,220 | 0.9% | −58% |
Implied day-one positions are each manager’s FedEx shares at March 31, 2026 divided by two. State Street’s June 30, 2026 13F has no line for FedEx Freight although SPY alone holds 1.46 million shares; it is left out. Boston Partners, Hotchkis & Wiley, Ameriprise and Citadel sold their whole implied positions.
There has been no open-market buying or selling by insiders. Every Form 4 since the spin is a conversion of FedEx awards or a grant; no Form 144 has been filed, and no director or officer adopted a trading plan in the quarter to September 30, 2026. The company has no buyback yet.
Short interest and volatility
| Report | Settled | Short | % float | % outst. | Days to cover |
|---|---|---|---|---|---|
| First after the spin | Jun 15, 2026 | 2.16M | 1.8% | 1.4% | 1.0 |
| Three months earlier | Jul 15, 2026 | 3.36M | 2.8% | 2.2% | 2.4 |
| Latest | Oct 30, 2026 | 5.91M | 5.0% | 4.0% | 3.6 |
The latest share of float is higher than 8 of the 9 earlier reports since the spin. Short interest in shares, with its share of the float and of shares outstanding. FINRA settlement dates; figures are published about eight business days later. Days to cover is short interest divided by average daily volume, as reported by FINRA. Float and shares outstanding on or before each date, from this site's daily share records and the company's filings.
Short interest tripled into the results. It rose from 2.2 million shares on June 15, 2026 to 6.3 million on October 15, 2026, about 5.3% of the shares FedEx does not own, and days to cover rose from 1.0 to 4.4. Within six months of a spin part of this is hedging against FedEx shares, and some may be positioned for FedEx’s sale of its stake. A short base of 4.4 days covering into a beat is consistent with the size of the October 30 rise. The figure for October 31, 2026, published in mid-November, will show how much was bought back; high and still rising short interest after the results would argue for more weight on the worst case.
| Volatility, annualized | Last 20 sessions | Last 60 sessions | Since the spin |
|---|---|---|---|
| To November 13, 2026 | 60% | 44% | 49% |
At the last 60 sessions' volatility, one standard deviation over a month is about ±14%, or $117.90 to $152.14 from the $133.93 close; about two months in three end inside that range if volatility holds. The median daily move since the spin is 1.9%.
| Results day | Released | Close before | Close after | Move | Times a median day |
|---|---|---|---|---|---|
| June 25, 2026 | After the close | $158.53 | $153.89 | -2.9% | 1.5× |
| October 29, 2026 | After the close | $109.69 | $126.04 | +14.9% | 7.9× |
Average move on a results day: 8.9% either way, against a median day's 1.9%. The move is measured from the close before the release to the close of the first session after it.
Volatility has fallen since June. Measured since the spin it is about 45% a year, against about 35% over the last 60 sessions and 27% over the last 20 before the results; June’s selling by FedEx holders probably accounts for much of the difference. The two results days so far moved −2.9% (June 26, 2026) and 14.9% (October 30, 2026).
Notes on earlier sections
- FedEx retained 29,751,545 shares, not “roughly 30.1 million”. The August 24, 2026 analysis gave ~30.1 million shares and about $3.9 billion. The figure is 29,751,545 (FedEx’s Form 4 and Schedule 13G), 19.9% of 149.5 million. Data correction. It changes the size of the overhang by about 1%.
- FedEx now expects to sell the stake by about September 30, 2027. The same section dated the disposal to the tax deadline of June 1, 2028. FedEx’s 10-Q of October 28, 2026 says it expects “to fully monetize” the stake within 12 months of September 30, 2026, subject to market conditions. A change in the business: the overhang arrives up to eight months sooner.
- Depreciation. The August model carried depreciation and amortization at 5.8% of revenue. In the four months to September 30, 2026 it ran at 4.6%, after FedEx-allocated amounts ended at the spin. The model now uses 5.0%, which lowers the base value by about $4.50. Clarification of an assumption.
- Interest. The August analysis estimated about $206 million a year of interest. With the term loan at 5.15% and fees, the run rate is about $216–220 million (the company guides to about $55 million for the fourth quarter of 2026). Clarification. It costs about 5 cents a share a year.
What it means for the rating
TRIM, target $108 → $112. The target is the best-guess value, $112.09. At $126.04 the expected return is −11% and probability-weighted losses outweigh gains about five to one; the price sits in the TRIM band, which runs from $124.55 to $149.45.
- Why the target rose: the results put 2027 on the company’s plan, which is the base case; the model now values mid-cycle earnings on 2028’s revenue. The cases did not change on the results.
- Why the rating fell: the price rose 14.9% in a day to above the base case, so the stock now needs the best case to be more likely than the worst to earn its price.
- Why not HOLD: HOLD needs the price within 10% of the target, below $124.55. The price implies about 41% on a return to 82%, which nine years of history and a base price three to five points behind peers do not support.
- Why not SELL: the base case is below the price by less than 10%, the debt is sound, and the January 2027 renewal percentage could move the weights toward the best case. SELL starts above $149.45.
| Price | Action | What moves it |
|---|---|---|
| Below $89.67 | BUY | Near the worst case; gain to loss above 3 to 1 |
| $89.67–101.90 | ACCUMULATE | |
| $101.90–124.55 | HOLD | Within 10% of the target |
| $124.55–149.45 | TRIM | The price at the close |
| Above $149.45 | SELL | |
| The bands move up | A renewal percentage near peers’ 5–10%, base price above 2% in the fourth quarter, 2027 guidance at the top of the framework | |
| The bands move down | ISM below 50, falling diesel without base-price gains, a renewal percentage below 3%, a sale of FedEx’s stake at a deep discount |
What the next results (the 10-KT for June–December 2026, early 2027, date not announced) must show:
| Test | Base case | Read |
|---|---|---|
| Fourth-quarter adjusted operating ratio | About 91.6% (the guide) | Worse than 92% is a warning |
| Base price (revenue per hundredweight excluding fuel) | Rising | Above 2% supports the best case |
| Average daily shipments | Positive, after +0.9% in September | Negative again argues for the worst case |
| 2027 guidance | Revenue +4–6%, margin about 13% | Below the framework lowers the base case |
| Renewal percentage | Not disclosed yet | Near peers’ 5–10% raises the best-case weight |
| Dividend and buyback plan | Due in January 2027 | A buyback beyond offsetting dilution would be new |
| FedEx’s stake | A sale by September 2027 | The method of sale decides the net supply |
Post-Spin Analysis — August 24, 2026
Written against the August 25 close of $128.75. Primary sources: the FY2026 Form 10-K (filed 2026-08-05, for the year ended May 31, 2026) and the calendar-year 2025/2024 recast furnished on 2026-08-06. Both landed after our last published grade.
The one-line version
FedEx Freight is a good LTL operator at the bottom of a freight cycle, priced for a mid-cycle recovery that has not started.
Its adjusted operating ratio was 88.3% in the year just ended, against 80.0% at the FY2023–24 peak. This is a cyclical trough, not a broken business. But nine years of segment disclosure show the peak was the anomaly, not the trough — FedEx Freight ran 87.2% to 93.9% in the five years before FY2022, and reached 80% only in the post-COVID freight boom and the year Yellow liquidated. We now carry 85% as mid-cycle, not 82.5%, and that single revision is worth about $15 a share.
Two things the pre-spin summary could not show remain genuinely negative: volumes are falling (average daily shipments −4%, and −24% from the FY2019 peak), and reported earnings contain $373M of related-party interest income that ends at separation, replaced by ~$206M of interest expense on $4.3B of new debt raised to pay the parent.
What is better than we said. The CEO ran this exact business from 2018 to 2021 and improved its operating ratio 470 basis points doing it, and the CFO has executed a spinoff before. The “no standalone track record” markdown was too harsh, and the grade below is revised for it.
At $128.75 the shares trade at 16.3x trailing EBITDA against a peer median of 15.2x, while carrying 3.8x leverage — the most in the LTL group. There is no spinoff discount here. And FedEx must sell its retained 19.9% before June 2028 — a known, dated, forced seller of roughly 29 days’ volume. FedEx’s chairman also chairs this board, which aligns the placement incentives but underlines the real point: this is a 19.9%-owned affiliate, not yet a fully independent company.
Rating: HOLD. Target $108. Grade: proposed A− (3.80) → B+ (3.15), taking effect with the next published report.
What the business actually is
The largest less-than-truckload carrier in North America by revenue, separated from FedEx on June 1, 2026 in an 80.1% distribution — FedEx retained 19.9%. Roughly $8.8B of revenue, 86,100 average daily shipments, a national terminal network, and a fleet carried at $6.7B gross / $2.9B net.
LTL is a scale-and-density business: the moat is the terminal network, and it is genuinely hard to replicate. That much of the pre-spin thesis holds. What the filings add is how well the network is being run, and the answer is: not well.
Management Team
The August 10-K names the leadership for the first time, and it is materially better than “no standalone track record” implies. This is not a new team learning a new business.
| Role | Name | Background |
|---|---|---|
| President & CEO | John A. Smith (64) | Ran this exact business before — President & CEO of FedEx Freight August 2018 – February 2021. Then President & CEO of FedEx Ground (2021–2023) and COO, US and Canada, of Federal Express (2024–2026). At FedEx Freight in operations roles from 2000; 26 years in the building |
| CFO | Marshall W. Witt (60) | CFO of TD SYNNEX for twelve years (2013–2025), where he executed the Concentrix spinoff in 2020. Before that, SVP Finance and Controller of FedEx Freight, in a 15-year FedEx career |
| COO | Clinton D. McCoy (53) | FedEx Freight since at least 2016 — district operations, engineering and quality, operations support. Promoted to COO February 2025 |
| Chief Specialized Services & Commercial Officer | Michael B. Lyons (47) | FedEx Freight since 2007, via FP&A and freight strategy |
| CTO | Michael Rodgers (62) | The outside hire — CTO of Pilot Travel Centers 2015–2024, before that senior technology roles at J.C. Penney and Saks |
| Chief HR & Legal Officer | Clement Edward Klank III (58) | FedEx corporate governance, securities and tax law from 1998 |
Two things stand out.
The CEO has run this P&L before, and the record is checkable. Smith took FedEx Freight in August 2018 and left in February 2021. Across FY2019–FY2021 the segment operating ratio went 91.9% → 91.8% → 87.2% — a 470 basis-point improvement, through a pandemic. That is not the whole story (the freight cycle was turning in his favor by late FY2021) but it is the opposite of an unknown quantity, and the scorecard below is revised for it.
The CFO was hired for a separation, not for freight. Witt spent twelve years as a public-company CFO and took a business through a spinoff at TD SYNNEX — and he already knows this specific company from the inside. For a business whose first eighteen months are dominated by standing up standalone functions, refinancing, and a mandatory parent share placement, that is a deliberate and well-matched hire.
The board — strong on operations, and still half a FedEx board
Nine directors. The operating bench is genuinely good for an LTL carrier:
- Cindy J. Miller — CEO of Stericycle through its 2024 sale to Waste Management, and before that nearly 30 years at UPS, latterly President of Global Freight Forwarding. A competitor’s senior freight executive who has also sold a company.
- Stephen E. Gorman — COO of Delta Air Lines, CEO of Greyhound, and Lead Independent Director of ArcBest — a direct LTL competitor — from 2015 to 2022.
- Donald E. Frieson — EVP Supply Chain at Lowe’s, 19 years at Walmart. The customer’s-eye view of an LTL network.
- Amy J. Salcido — President, U.S. of Kyndryl, the IBM separation. Someone who has lived inside a large spinoff.
- John P. Sauerland — CFO of Progressive for a decade; chairs Audit.
- Jeffrey A. Davis — serial CFO: Dollar Tree, Qurate, J.C. Penney, Darden, Walmart U.S.
Four of the nine directors have direct ties to the former parent, and one of them is the chairman:
| Director | The tie |
|---|---|
| R. Brad Martin — Chairman of FedEx Freight | Simultaneously executive Chairman and Chairman of the Board of FedEx, the former parent |
| Samantha M. Smith | A current FedEx employee — staff director of global public policy, since 2020 |
| Robert A. King | Four decades in FedEx Internal Audit, to January 2025 — and chairs the Risk Oversight Committee |
| Stephen E. Gorman | A FedEx director until the separation date |
The obvious reading is a conflict of interest. We think that reading is wrong, and the right one is more interesting.
FedEx still owns 19.9% of this company. It is not a departed parent with a free hand — it is the largest shareholder, and it holds the same stock everyone else does until June 2028. A placement executed badly costs FedEx more than it costs anyone else, because FedEx owns the block being placed. On the single decision where a conflict would matter most, the incentives are aligned rather than opposed, and having the seller’s chairman in the room arguably makes a disorderly placement less likely, not more.
What the board composition actually tells you is something different: FedEx Freight is not yet an independent company. It is a 19.9%-owned affiliate with a shared chairman, a sitting parent employee on its board, a brand it licenses rather than owns, and a transition services agreement running up to 24 months. The 10-K’s own language — that continuing FedEx positions “could create, or appear to create, potential conflicts of interest” — is the acknowledgement of a company still partly inside its parent.
That matters for how you read everything else on this page. The standalone cost base is not yet fully standalone. The first “standalone” quarters will be reported by a company still buying services from FedEx. And the independence that the spinoff thesis depends on — management running the business for LTL economics rather than for a parcel parent — does not fully arrive until the retained stake clears. The date on that is June 2028, and it is the same date as everything else that matters here.
The number that changes the thesis
FedEx Freight’s reported profit contains a large item that does not survive the separation.
| Calendar 2025 ($M) | |
|---|---|
| Operating income | 1,022 |
| Related-party interest income | 373 |
| Other, net | 9 |
| Income before income taxes | 1,404 |
That $373M is interest FedEx paid on intercompany balances. It is 27% of pre-tax income, it has no operating substance, and it ends at separation. In its place the company now carries $4.3B of its own debt at a 4.79% weighted-average rate — roughly $206M a year of interest expense where there was $373M of interest income.
That is a ~$579M annual swing in pre-tax income, and it is structural.
Reconstructing FY2026 (year ended May 31, 2026) on a standalone basis:
| ($M except per share) | |
|---|---|
| Reported operating income | 540 |
| Add back separation and other costs | 492 |
| Adjusted operating income | 1,032 |
| Less: full-year standalone interest | (206) |
| Pro-forma pre-tax income | 826 |
| Tax at 25% | (206) |
| Pro-forma net income | 620 |
| Pro-forma EPS (149.5M shares) | $4.14 |
| Reported FY2026 diluted EPS | $4.38 |
The reported figure and the pro-forma figure look similar, which is exactly the trap: they arrive there by completely different routes. Reported EPS is flattered by interest income that is gone and understated by separation costs that are temporary. The pro-forma number is the one to value.
At $128.75 that is 30.4x — but read that number carefully: FY2026 was a cyclical trough. On our mid-cycle estimate the same price is about 22x. The disappearing interest income is structural; the depressed operating ratio behind it is not. See Valuation below.
The financial record — nine years, and the trough is not the surprise
The whole valuation of this company turns on one number: what operating ratio FedEx Freight earns in a normal year. The page you are reading previously answered that with a single comparison — 83.2% in calendar 2024 — and treated 88.3% as the deviation. Nine years of segment disclosure say the comparison was the wrong way round.
| FY (ends May 31) | Revenue | Operating ratio | Operating income | Shipments/day | Rev/shipment |
|---|---|---|---|---|---|
| 2017 | $6,070M | 93.9% | $371M | 101.6k | $235.20 |
| 2018 | $6,812M | 92.8% | $490M | 106.4k | $251.93 |
| 2019 | $7,582M | 91.9% | $615M | 112.7k | $265.98 |
| 2020 | $7,102M | 91.8% | $580M | 103.0k | $272.56 |
| 2021 | $7,833M | 87.2% | $1,005M | 108.4k | $282.95 |
| 2022 | $9,532M | 82.6% | $1,663M | 111.7k | $334.57 |
| 2023 | $9,632M | 80.0% | $1,925M | 99.7k | $379.76 |
| 2024 | $9,082M | 80.0% | $1,814M | 94.0k | $376.81 |
FY2017–FY2024 as reported by FedEx Corp for the FedEx Freight segment. See the basis note below before comparing these to FY2025–FY2026.
And on the standalone basis the new company reports:
| FY (ends May 31) | Revenue | Operating ratio | Operating income | Shipments/day | Rev/shipment |
|---|---|---|---|---|---|
| 2024 | $9,424M | 81.4% | $1,753M | — | — |
| 2025 | $8,892M | 84.2% | $1,404M | 90.1k | $373.52 |
| 2026 | $8,795M | 88.3% (adj) | $1,032M (adj) | 86.1k | $386.63 |
The basis note, because it matters. From FY2025 FedEx moved Custom Critical into the Freight segment, and the standalone carve-out allocates corporate cost differently. FY2024 is reported on both bases and shows the size of the gap: $9,082M / 80.0% on FedEx’s segment basis against $9,424M / 81.4% standalone — about 140 basis points. So the two tables are not directly comparable, and we have not spliced them. But the gap is small, measured, and in a known direction: the older segment figures flatter the standalone business by roughly 1.4 points, not by five or ten.
What this does to “mid-cycle”
FedEx Freight has earned an 80–83% operating ratio in exactly three years of the nine on record: FY2022, FY2023 and FY2024. In the five years before that it ran 87.2% to 93.9%. A mid-cycle assumption of 82.5–83.5% is therefore calibrated on the three best consecutive years in the company’s recorded history — and those three years were the post-COVID goods boom, followed by the August 2023 liquidation of Yellow Corporation, which removed roughly a tenth of US LTL capacity in a single quarter.
That is not a cycle. That is a cycle plus a competitor dying.
The counter-argument is real, and it is why this is not a bear case. Three of the things that improved are structural, not cyclical:
- Yellow is not coming back. The capacity it took out is permanently gone, and with it the most persistently irrational pricing in the industry. Every year from FY2017 to FY2020 was competed against a Yellow that was underpricing to survive.
- Price has re-based, not spiked. Revenue per shipment went from $235.20 in FY2017 to $386.63 in FY2026 — +64%, and it kept rising straight through the downturn, including +3.5% in the worst year. Pricing discipline has held where volume has not.
- The cost base is genuinely smaller. Headcount went from ~49,000 in FY2019 to ~40,000 by FY2024 — down 18% — on higher revenue, and service centers from ~400 to ~360.
So mid-cycle is better than the 91–94% of the late 2010s and worse than the 80% of the boom. Our estimate is that FY2025’s 84.2% is itself close to mid-cycle — not a way-station on the road back to 80%. That single revision is the most consequential change on this page, and the valuation section below carries it through.
Why this matters so much: on the discounted cash flow model used here, every 100 basis points of terminal operating ratio is worth about $6 a share. The difference between assuming 82.5% and assuming 85% is roughly $15 — more than the entire gap between the old price target and the old share price.
The trough in detail
Revenue fell in all four quarters of calendar 2025, and the margin fell faster.
| Calendar quarters ($M) | Q1 | Q2 | Q3 | Q4 |
|---|---|---|---|---|
| Revenue 2024 | 2,292 | 2,355 | 2,313 | 2,132 |
| Revenue 2025 | 2,162 | 2,289 | 2,259 | 2,068 |
| YoY | −5.7% | −2.8% | −2.3% | −3.0% |
| Operating margin 2024 | 18.4% | 19.0% | 17.7% | 12.0% |
| Operating margin 2025 (ex-separation) | 14.3% | 19.0% | 14.2% | 7.8% |
For the fiscal year ended May 31, 2026, against the prior year:
| FY2026 | FY2025 | |
|---|---|---|
| Revenue | $8,795M | $8,892M (−1%) |
| Average daily shipments | 86,100 | 90,100 (−4%) |
| Revenue per shipment | $386.63 | $373.52 (+4%) |
| Operating income (reported) | $540M | $1,404M (−62%) |
| Operating margin (reported) | 6.1% | 15.8% |
| Adjusted operating margin | 11.7% | 15.8% |
| Adjusted operating ratio | 88.3% | 84.2% |
Read the volume line against the price line, and against peers. Shipments fell 4% while revenue per shipment rose 4% — and the company attributes that rise to “higher fuel surcharges and weight per shipment,” not base rates. So the top line was held roughly flat by a fuel pass-through, while the underlying business moved less freight. That is the opposite of the volume-led growth you want to see — though for context, Old Dominion’s tonnage fell 9.2% in a comparable month while prioritising yield over volume. A 4% shipment decline is not an outlier in this market; it is roughly the middle of it.
Every major cost line rose as a percentage of revenue: salaries 46.7% → 48.6%, depreciation 5.3% → 5.8%, fuel 5.1% → 5.6%, other 10.6% → 11.7%. Only maintenance improved. This is textbook operating deleverage, and management names the cause plainly: “weak industrial production, global trade policy uncertainty, and excess capacity in the LTL industry.”
The company’s own outlook is explicitly negative: “We expect inflation and elevated interest rates to continue to negatively affect our results of operations for the remainder of calendar year 2026.”
No standalone quarter has been reported yet. FedEx Freight’s fiscal year ended the day before it began trading. Its first quarter as an independent company covers June–August 2026 and reports in the autumn. The single most informative event in this company’s life as a public stock is still ahead of it, and everything above is a pre-separation record.
Where FedEx Freight sits in the value chain
Nobody in less-than-truckload has pricing power independent of industry capacity, and that reframes what is wrong with this business. The 88.3% operating ratio is not evidence of a weak competitive position. It is evidence of a cost position, and those are fixed differently.
The customer side is favorable, and it does not help
| Against | Position |
|---|---|
| Customers — shippers | Structurally good and practically irrelevant. Thousands of fragmented shippers, no meaningful concentration. That ought to confer pricing power. It does not, because the price is set elsewhere |
| Competitors — Old Dominion, XPO, Saia, ArcBest, TFI | The determinant. Industry capacity utilisation sets LTL price. When capacity is tight every carrier prices well; when it is loose none of them do |
| Substitutes — truckload, intermodal, parcel | A live ceiling. Freight moves between modes on price, so LTL cannot price far above the alternatives |
| Inputs — drivers, fuel, equipment | Drivers are the binding constraint and the largest cost at 48.6% of revenue. Fuel is passed through by surcharge, but not automatically |
Compare that customer position with a supplier selling to three carmakers. Fragmentation is supposed to be the good outcome — and FedEx Freight has it in full, with no customer worth naming. It earns an 88.3% operating ratio anyway. Customer fragmentation is not sufficient for pricing power when a commodity service is sold into a market with visible excess capacity.
The filings say plainly that the price is not moving
Revenue per shipment rose 4% in FY2026, and none of that is price. The 10-K attributes it to “higher fuel surcharges and weight per shipment” — and goes further, warning that the yield metric “is not a true measure of price” and that changes in it “do not necessarily indicate actual changes in underlying base rates.”
A company that volunteers that its revenue-per-unit growth is not a price signal is telling you it did not get one. Management names the reason directly: “weak industrial production, global trade policy uncertainty, and excess capacity in the LTL industry.”
And even the fuel pass-through is contested. The risk factors state that “if we are unable to maintain or increase our fuel surcharges because of competitive pricing pressures” fuel costs could hurt results — with no hedging in place. The one mechanism that looks like automatic pricing is itself subject to competition.
The terminal network is a barrier to entry, not a source of pricing power
Roughly 360 service centers and a national linehaul network cannot be rebuilt at any sensible cost. That is a genuine and durable barrier — it is why LTL has five serious carriers rather than fifty, and why new entrants do not appear.
But look at what it does not do. Old Dominion runs the same class of asset against the same industry price and earns a 74.5% operating ratio against FedEx Freight’s 88.3% — a gap of nearly fourteen points, between two companies facing identical market conditions.
A barrier that every incumbent shares protects the industry’s structure, not any one member’s margin. The network earns you the right to compete. What separates 74.5% from 88.3% is density and execution — shipments per terminal, dock productivity, linehaul load factor, purchased-transportation discipline.
Which is why this is a more hopeful diagnosis than it sounds
If FedEx Freight’s problem were market power, it would be unfixable. A supplier that cannot raise price and has no structural protection is stuck where it is.
Its problem is cost, and cost is management’s to change. The nine-year record shows this business running 91.8–93.9% in the late 2010s and 80.0% at the peak — a 1,390 basis-point range on the same terminal network, driven by density and discipline rather than by anything the market granted. And the current chief executive improved the operating ratio 470 basis points the last time he held the job.
That is the investment case, stated structurally: you are not waiting for pricing power that never existed. You are waiting for volume to refill a network that is already built, and for a management team to close a gap against a peer that proves the gap is closeable.
In depth: competitive dynamics
Operating ratio is the LTL industry’s scoreboard: total operating expenses divided by revenue, so lower is better. Judging FedEx Freight on its trough year alone gets the answer wrong.
| FedEx Freight adjusted operating ratio | |
|---|---|
| Calendar 2024 | 83.2% |
| Fiscal 2025 (May year-end) | 84.2% |
| Calendar 2025 | 86.0% |
| Fiscal 2026 (May year-end) | 88.3% |
But note how small a window that table is. Over the nine-year record above, this business has ranged from 80.0% to 93.9% — a 13.9-point swing, not a 5-point one. Reading 83.2% as “the number that matters for valuation” was the error corrected earlier on this page. Against the peer set, on the same quarter:
| Carrier | Q4 CY2025 OR | Full-cycle character |
|---|---|---|
| Old Dominion | ~74.5% | best in class, by a wide margin |
| XPO | 84.4% | improving — 180bp better year on year |
| Saia | 91.9% | deteriorating; bought Yellow terminals into the downturn |
| FedEx Freight | 92.2% | trough quarter; 83.2% in calendar 2024 |
| ArcBest | 96.2% | unionized; not covering its cost of freight |
In the FY2022–24 window FedEx Freight ran second only to Old Dominion among the majors — but that window was three years long. Across the full nine-year record it sat mid-pack, at 91.8–93.9% from FY2017 to FY2020 while Old Dominion was already well below 80%. The honest statement is that this is the largest LTL carrier in North America with a terminal network that cannot be rebuilt at any sensible cost, and a cost structure that is good but not best-in-class. An earlier version of this analysis understated it by anchoring on the trough quarter; the version before that overstated it by anchoring on the peak.
Two structural items still deserve attention:
It does not own its own brand. The FedEx name, logo and purple-and-orange trade dress are used under a Trademark License Agreement with the former parent. The 10-K flags that any elimination of those rights “could materially adversely affect our reputation, business, and results of operations.”
It is non-union — which in this industry is an asset, not merely a fact. The 10-K notes unions “have in the past attempted to organize employees at FedEx Freight and could attempt to do so again,” and flags the Faster Labor Contracts Act passed by the U.S. House in June 2026. With salaries at 48.6% of revenue, successful organizing would be the largest single cost event available. But see the next section for why non-union status is also what makes this company a survivor.
Does a recession kill LTL carriers? Yes — and that is the opportunity
LTL is a high-fixed-cost network business, so downturns are brutal. They are also how the industry consolidates, and the pattern is remarkably consistent.
| Failure | Year | What it was |
|---|---|---|
| Consolidated Freightways | 2002 | Third-largest carrier, ~$2.3B revenue, 20,000 employees, unionized |
| Jevic Transportation | 2008 | Failed under Yellow’s ownership in the financial crisis |
| Yellow Corporation | 2023 | ~$4.6B revenue, 30,000 employees including 22,000 Teamsters, ~10% of US LTL capacity |
Every one was unionized, levered, or both. That is the profile that dies in a freight recession — not scale, and not a weak quarter.
What happened to the survivors is the point. With Yellow’s roughly 10% of capacity removed, the publicly traded LTL carriers as a group posted their second-best profitability quarter on record in the following quarter. FedEx Freight was among the beneficiaries, taking volume directly — management noted at the time that Yellow carried “a lot of low-quality revenue” and that customers moved to higher-service carriers.
So the honest answer to “does a recession kill LTL companies” is: it kills the weak ones, and pays the strong ones handsomely.
FedEx Freight enters this downturn non-union, at 2.62x net leverage, with an undrawn $1.2B revolver and no debt maturity that forces its hand. It is not on the casualty list. It is on the list of companies that get paid when someone else is.
Who is weak this time. ArcBest at a 96.2% operating ratio is not covering the cost of hauling freight; it is the unionized carrier in the group. Saia at 91.9% and deteriorating bought aggressively into Yellow’s terminal auction and added capacity into a falling market. Neither is Yellow yet — but the industry’s own excess capacity, which FedEx Freight names as a cause of its weak pricing, is the mechanism that eventually removes one of them.
Can FedEx Freight take share? It already has, from Yellow. Its constraint is not network reach — it has the largest network in the country — it is service consistency and price discipline in an oversupplied market. When capacity exits, the largest network with the best service reputation is structurally advantaged. That is the bull case, and it is a real one.
The retained stake is a dated, mandatory overhang
This is the most precisely specified fact about the stock, and the reason its debut was soft.
FedEx retained 19.9% of the shares. To preserve the tax-free status of the separation, FedEx must generally dispose of those shares within 24 months of completion — that is, by June 1, 2028. The 10-K states the consequence without hedging: such a disposition “may decrease the market price of our common stock.”
That is roughly 30.1 million shares, about $3.9B at the current price, that must reach the market inside the next 21 months. Against recent trading of about $143M a day, it is on the order of 29 full days of volume.
This is not a reason the stock is cheap. It is a reason it should be cheaper, and the overhang does not clear until it is gone. Any thesis here has to survive a known forced seller with a deadline.
One thing works in the holder’s favor, and it is easy to miss. FedEx is not an indifferent seller — it owns the block, so every dollar it loses through a disorderly placement is a dollar off its own $3.9B position. That is why the shared chairman between the two boards reads as alignment rather than conflict: the seller is also the largest shareholder, and stays that way until the last share is placed. The overhang is a supply problem, not an agency problem.
Financials
The balance sheet is now genuinely levered.
| Instrument | Amount | Rate | Matures |
|---|---|---|---|
| Senior unsecured notes (issued 2026-02-05) | $3,700M | — | multiple series |
| Delayed-draw term loan | $600M | 4.91% | 2029 |
| Total debt (net of $36M costs) | $4,299M | 4.79% wtd avg | |
| Revolving credit facility | $1,200M — undrawn | 5-year |
| At May 31, 2026 | |
|---|---|
| Cash | $251M |
| Net debt | $4,048M |
| Net leverage | 2.62x adjusted EBITDA |
| Including operating leases ($1,824M) | 3.80x |
| Total assets | $6,884M |
| Net property and equipment | $2,923M |
Where the money went. The 10-K is explicit: “we distributed, from the net proceeds of such borrowings, $4.1 billion of cash to FedEx as part of the consideration for the assets FedEx contributed to us.” The debt was raised to pay the parent. This is a separation in which the departing business was capitalised for the parent’s benefit, and it is why the leverage exists at all.
Cash flow looks alarming, and one large part of it is explicable.
| ($M) | FY2026 | FY2025 |
|---|---|---|
| Cash provided by operating activities | 167 | 1,531 |
| Capital expenditures | (379) | (437) |
| Free cash flow | (212) | 1,094 |
The collapse is mostly a working-capital unwind: FedEx Freight had been selling its receivables to FedEx under a factoring agreement, which ended at separation. Receivables jumped from $132M to $1,154M as a result — roughly $1B of one-time cash absorption. Normalize for it and FY2026 operating cash flow would be near $1.2B.
But two things do not normalize. Bad-debt expense rose because the company now carries its own receivables risk, and it will do so permanently. And there is no dividend: the company says only that it “expects to begin paying a regular cash dividend in the foreseeable future,” with nothing declared.
Capital allocation — what the parent took, and what is left
The three-year cash flow statement is the most revealing page in this filing.
| ($M) | FY2024 | FY2025 | FY2026 | 3-yr total |
|---|---|---|---|---|
| Cash from operations | 1,541 | 1,531 | 167 | 3,239 |
| Capital expenditures | (461) | (437) | (379) | (1,277) |
| Free cash flow | 1,080 | 1,094 | (212) | 1,962 |
| Proceeds from debt issuance | — | — | 4,271 | 4,271 |
| Net transfers to Parent | (1,125) | (1,077) | (3,910) | (6,112) |
FedEx extracted $6.1B from this business over three years against $2.0B of free cash flow it generated — roughly three times over. In FY2024 and FY2025 the sweep was almost exactly equal to free cash flow: $1,080M earned, $1,125M taken; $1,094M earned, $1,077M taken. The business was run as a cash source, retaining nothing. Then in FY2026 it borrowed $4.3B and sent $3.9B of that after it.
This is not unusual in a spinoff, and the 10-K states it plainly — “we distributed, from the net proceeds of such borrowings, $4.1 billion of cash to FedEx as part of the consideration for the assets FedEx contributed to us.” But it defines the starting position: a business entering independence at a cyclical trough, with no retained cash, no dividend, and $4.3B of debt it did not previously carry.
Capex is running below depreciation, and that is a bill not yet paid
| ($M) | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Capital expenditures | 461 | 437 | 379 |
| Depreciation and amortization (cash flow basis) | 404 | 416 | 449 |
| Capex / D&A | 114% | 105% | 84% |
Capex fell 18% over three years while depreciation rose 11%. For a business whose principal assets are roughly 30,000 vehicles and 360 terminals, spending 84% of depreciation is a deferral, not a saving. The fleet ages, and the spend comes back.
This has a direct valuation consequence. The discounted cash flow model below carries capital expenditure and working capital at a combined 5.1% of revenue throughout — against depreciation of 5.8%. The model therefore assumes this company never again spends as much as it depreciates, for seven consecutive years, on a truck fleet. Correcting that to 6.5% of revenue costs about $4 a share — not fatal, but it is a thumb on the scale and it should be named.
There is no capital return, and a covenant that could keep it that way
No dividend has been declared. The company says only that it “expects to begin paying a regular cash dividend in the foreseeable future.” There is no buyback authorisation.
The credit facilities require a total leverage ratio no higher than 3.75:1.00 for the first two reported quarters, tightening to 3.50:1.00 from roughly January 2027. Against $4,299M of gross debt, FY2026 adjusted EBITDA of $1,544M puts the company at about 2.8x — meaning adjusted EBITDA can fall about 20% before the 3.50x test binds.
In a business that just posted an 88.3% operating ratio and whose management expects conditions to stay negative through calendar 2026, a 20% EBITDA cushion is adequate rather than comfortable. The facilities also restrict dividends and buybacks outright during an event of default. The realistic reading is that capital return waits for the cycle — which removes one of the usual supports under a spinoff’s share price in its first two years.
Valuation
| At $128.75 | |
|---|---|
| Market capitalization | $19.25B |
| Enterprise value | $23.30B |
| EV including operating leases | $25.12B |
| EV / FY2026 adjusted EBITDA ($1,544M) | 15.1x |
| EV / CY2025 adjusted EBITDA ($1,700M) | 13.7x |
| Pro-forma P/E (on trough earnings — see below) | 30.4x |
Those are trough multiples, computed on the worst operating year this business has had. They are the wrong basis for a cyclical carrier, and the next section reworks them on mid-cycle earnings.
Trough versus mid-cycle — the distinction that decides this
On the year just ended, FedEx Freight looks expensive. On mid-cycle earnings it looks fair. Both are true, and which one you use is the whole argument — which is why the nine-year record above matters more than any other exhibit on this page. Here is the same calculation at four different views of mid-cycle:
| Mid-cycle operating ratio on ~$9.3B | 83.5% | 84.2% | 85.0% | 86.0% |
|---|---|---|---|---|
| the old assumption | FY2025 actual | our estimate | cautious | |
| Operating income | $1,535M | $1,469M | $1,395M | $1,302M |
| EBITDA | $2,074M | $2,009M | $1,934M | $1,841M |
| EV / EBITDA | 11.2x | 11.6x | 12.0x | 12.7x |
| Pro-forma EPS | $6.66 | $6.34 | $5.96 | $5.50 |
| P/E | 19.3x | 20.3x | 21.6x | 23.4x |
| Value at 11x EBITDA | $126 | $121 | $115 | $108 |
| Value at 12x EBITDA | $139 | $134 | $128 | $121 |
For reference, the trough year just reported — FY2026, an 88.3% adjusted operating ratio — puts the shares at 15.1x EBITDA and 30.4x earnings. That figure is a trough artefact and should not be used.
We carry 85% as mid-cycle, between FY2025’s actual 84.2% and a cautious 86%. That is a full point and a half worse than this page previously assumed, and it is the single change that moves the price target. At 85%, FedEx Freight trades at 12.0x mid-cycle EBITDA and 21.6x mid-cycle earnings — which is not a cheap multiple for a levered cyclical, as the peer section below shows.
Discounted cash flow
Unlevered FCF, FY2027–FY2033. Revenue growing 2–4% a year; depreciation at 5.8% of revenue; tax at 25%; capital expenditure and working capital combined at 5.1% of revenue. WACC 11%, exit multiple 11x.
The original model reverted the operating ratio to 82.5% — better than any year on record except FY2023 and FY2024. We show it alongside three shallower paths:
| ($M) — the 82.5% path | FY27 | FY28 | FY29 | FY30 | FY31 | FY32 | FY33 |
|---|---|---|---|---|---|---|---|
| Revenue | 8,971 | 9,330 | 9,703 | 10,043 | 10,344 | 10,654 | 10,974 |
| Operating ratio | 87.5% | 85.5% | 84.0% | 83.0% | 82.5% | 82.5% | 82.5% |
| EBITDA | 1,642 | 1,894 | 2,115 | 2,290 | 2,410 | 2,482 | 2,557 |
| Unlevered FCF | 904 | 1,080 | 1,232 | 1,351 | 1,430 | 1,473 | 1,517 |
Value per share at 11% WACC and an 11x exit, across terminal operating ratios and the two capital-spending assumptions discussed above:
| Terminal operating ratio | capex+WC at 5.1% (as modeled) | at 6.5% (above depreciation) |
|---|---|---|
| 82.5% — the original assumption | $103 | $98 |
| 84.5% | $91 | $86 |
| 86.0% | $82 | $78 |
| 88.0% — no recovery at all | $72 | $68 |
Every 100 basis points of terminal operating ratio is worth about $6 a share. That single sensitivity dominates WACC, exit multiple and capital spending combined, and it is why the nine-year record was worth the work.
The DCF and the multiple work disagree, and the disagreement is honest. At an 85% mid-cycle the DCF says $83–91 and capitalising mid-cycle EBITDA says $115–128. The gap is seven years of discounting at 11% applied to a business whose recovery is back-end weighted. For a cyclical at a trough that is exactly when a DCF is least reliable and a normalized multiple is most — but it is also exactly when a normalized multiple is most dependent on getting “normal” right, which is the trap this page previously fell into. We weight the multiple more heavily and land between them, nearer the multiple.
Earnings-based valuation
A P/E on this company is uncomparable across the separation date, and by an unusually large margin. Reported pre-tax income for FY2024 and FY2025 contains $330M and $388M of related-party interest income and no interest expense at all. Post-separation it carries roughly $206M of real interest and none of the income. Normalizing all three years to the standalone capital structure:
| ($M except per share) | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Operating income (as reported) | 1,753 | 1,404 | 540 |
| add back separation and other costs | — | — | 492 |
| Adjusted operating income | 1,753 | 1,404 | 1,032 |
| less standalone interest | (206) | (206) | (206) |
| Normalized pre-tax | 1,547 | 1,198 | 826 |
| Tax at 25% | (387) | (300) | (206) |
| Normalized net income | 1,160 | 898 | 620 |
| Normalized EPS (149.5M shares) | $7.76 | $6.01 | $4.14 |
| P/E at $128.75 | 16.6x | 21.4x | 31.1x |
| Reported diluted EPS | $10.53 | $9.00 | $4.38 |
Read the last two rows together. Reported EPS fell from $10.53 to $4.38 — a 58% collapse that overstates what happened. Normalized EPS fell from $7.76 to $4.14 — a 47% collapse that is the real number. In neither case is the reported figure usable, and in FY2024 the gap between them is $2.77 a share.
The useful comparison is the middle column. FY2025 — a year we now think is close to mid-cycle — supports $6.01 of normalized earnings, and the shares trade at 21.4x that. For context, that is a higher multiple than the market pays for TFI International or ArcBest, and roughly what it pays for Saia.
Price target: $108 · range $83–128 · HOLD
Method Value DCF — 85% terminal OR, 11% WACC, 11x exit $88 DCF — same, with capex at 6.5% of revenue $83 (bear) DCF — 85% terminal OR, 12x exit $95 Mid-cycle EPS $5.96 at 18x $107 Peer median 15.2x on LTM adjusted EBITDA $118 Mid-cycle EBITDA $1,934M at 11x $115 Mid-cycle EBITDA $1,934M at 12x $128 (bull) DCF — no recovery, 88% flat $72 (deep bear) Base $108 is −16% to the August 25 close of $128.75.
The target moved down from $120, and the reason is almost entirely one input. The old target assumed a mid-cycle operating ratio of 82.5–83.5%. Nine years of segment disclosure show that FedEx Freight has achieved that in exactly three years — the post-COVID freight boom plus the year Yellow liquidated — and ran 87.2% to 93.9% in the five years before. We now carry 85% as mid-cycle, and at roughly $6 a share per 100 basis points, that revision is worth about $15. Nothing about the business got worse; our estimate of normal did. A further $2 comes from moving the tax rate to 25% — the three-year effective range was 24.3% to 25.9%, and the 23.2% previously used was below all of it.
Recommendation: HOLD — and the reason is now price as well as timing. This is a genuinely good network business run by someone who has run it before. But it trades at 16.3x trailing EBITDA against a peer median of 15.2x, while carrying 3.8x leverage — the most in the group — with no standalone quarter yet reported and a mandatory seller in the register. The industry is not paying a spinoff discount for this, and it should be.
The specific reason to wait is the forced seller. FedEx must place roughly 30.1 million shares — about $3.9B, some 29 days of trading volume — before June 2028. That is a mechanical, dated source of supply with no view attached to it. Buying ahead of it means paying up and then absorbing it.
What would make this a BUY. Evidence of the operating ratio turning in the first standalone quarters, or the retained stake clearing at a discount. Get both and this is straightforwardly attractive — the largest network in a consolidating industry, run by the executive who improved its operating ratio 470 basis points last time he had the job, is not a business to be structurally bearish on. We want to own this. We want to own it lower, and after the seller is gone.
What this most resembles
FedEx Freight has three characteristics that should drive its outcome, and the universe lets each be tested separately: a parent that retained ~20% and must sell it, an asset-heavy cyclical business spun at a trough, and revenue that is entirely transactional. The three cuts point the same way, which is what makes them worth reading.
Cut 1 — the parent kept a stake
The 80.1 / 19.9 split is not arbitrary. Distributing at least 80% is what buys tax-free treatment; keeping just under 20% is what avoids equity-method accounting. It is a standard structure, and the universe has a usable cohort:
| Company | Parent | Spun | vs Day 1 | Annualised excess vs S&P |
|---|---|---|---|---|
| GE HealthCare | GE | Jan 2023 | +24.4% | −17.0pp |
| Solventum | 3M | Apr 2024 | +29.6% | −7.2pp |
| Sylvamo | International Paper | Oct 2021 | +30.4% | −6.2pp |
| Vestis | Aramark | Oct 2023 | −24.2% | −28.9pp |
| N-able | SolarWinds | Jul 2021 | −71.0% | −28.2pp |
| Concentra | Select Medical | Nov 2024 | +53.5% | +4.5pp |
One of six beat the S&P. Median annualised excess −12.1pp, against a universe-wide median of −7.2% and a base rate of 32.7% beating.
Note what the “vs Day 1” column does not do: four of the six are positive on that measure while five underperform the index. A retained-stake spinoff can rise and still be a bad investment, because the relevant comparison is the opportunity cost, not the entry price. That is the trap this cut exists to expose.
Cut 2 — asset-heavy cyclicals
| Company | Spun | vs Day 1 | Excess | Max drawdown |
|---|---|---|---|---|
| nVent Electric | May 2018 | +595.5% | +15.6pp | −57.5% |
| Wabtec | Feb 2019 | +309.5% | +6.7pp | −49.7% |
| ESAB | Apr 2022 | +84.2% | +6.1pp | −41.8% |
| Carrier Global | Apr 2020 | +282.6% | +6.0pp | −41.6% |
| Pentair | Oct 2012 | +167.0% | −4.5pp | −58.9% |
| MasterBrand | Dec 2022 | +18.3% | −14.9pp | −64.7% |
| GXO Logistics | Aug 2021 | −27.5% | −15.6pp | −69.6% |
| Seaport Entertainment | Aug 2024 | −0.7% | −20.0pp | −48.0% |
| Industrial Logistics Properties | Dec 2018 | −31.3% | −22.7pp | −94.0% |
| Amentum | Sep 2024 | −33.4% | −31.9pp | −50.8% |
| Concentrix | Dec 2020 | −70.0% | −34.7pp | −89.8% |
| Magnera | Nov 2024 | −42.6% | −41.0pp | −65.4% |
Four of fourteen beat — 29%, which is essentially the universe base rate of 32.7%. So asset-heavy cyclicals are not unusually likely to lose.
But the median excess is −17.8pp against −7.2% for the universe, and every name in the table drew down at least 41%. The odds of winning are ordinary; the losses when you lose are much bigger. For position sizing that distinction matters more than the hit rate.
Cut 3 — what separated the winners
This is the cut that should worry a FedEx Freight buyer, because the pattern is clean:
| Winner | What it actually sells |
|---|---|
| nVent | electrical enclosures — niche, specified-in |
| Wabtec | rail equipment — large parts and services annuity |
| ESAB | welding consumables — recurring by construction |
| Carrier | HVAC — aftermarket, plus a secular tailwind |
All four carry an aftermarket, a consumable, or a contracted annuity. None is a pure cyclical. The losers — GXO, Amentum, Concentrix, Magnera, Seaport — are transactional or re-competed businesses whose revenue has to be won again every period.
FedEx Freight is entirely transactional. Every dollar is freight priced at prevailing rates; there is no installed base, no consumable, no multi-year contract book. Structurally it belongs with the second group.
The closest sector precedent, and the closest timing precedent
Sector: the XPO family. GXO (contract logistics, 2021) returned −15.6pp annualised excess; RXO (brokerage, 2022) −16.3pp. Both were spun out of the company that is now FedEx Freight’s most improved competitor, and both underperformed materially. Freight spinoffs have not been kind.
Timing: Carrier Global. Spun from RTX on April 3, 2020 — into the deepest demand collapse in modern history. It rose 23.1% on day one and has since returned +282.6%, beating the index by 6pp annualised. Buying a cyclical spun at the bottom absolutely can work. Carrier had two things FedEx Freight does not: an aftermarket annuity, and a secular tailwind in efficiency and decarbonisation. LTL tonnage tracks industrial production and has no secular growth rate.
What the comparables actually change
They do not challenge the business quality. FedEx Freight has the largest LTL network in the country and a cost structure that is good if not best-in-class, and nothing above contradicts that.
They challenge the entry. Three independent cuts — structure, business type, sector — all land in the same place: this profile of spinoff has historically produced ordinary odds and outsized losses, and the retained-stake cohort specifically has underperformed while looking fine on a price-versus-day-1 basis.
The practical read. The overhang cohort suggests the discount does not close while the parent still holds stock; the cyclical cohort suggests the drawdown between here and the recovery could be far larger than the 8% this name has seen so far. Both argue for the same thing: wait for the stake to clear, and expect a better price than $137 while waiting.
In depth: valuation against peers
The whole HOLD rests on FedEx Freight being fully priced against its own industry, so the comparison deserves numbers rather than an assertion. Prices at the August 25, 2026 close. Enterprise value includes operating leases for every name, which matters in a sector where carriers finance terminals and tractors differently.
| Carrier | Price | EV (incl. leases) | LTM EBITDA | EV/EBITDA | Net debt / EBITDA | Fwd P/E | Q4 CY2025 OR |
|---|---|---|---|---|---|---|---|
| Old Dominion | $198.34 | $40.9B | $1.79B | 22.8x | −0.1x (net cash) | 29.9x | ~74.5% |
| XPO | $191.93 | $26.2B | $1.38B | 19.0x | 2.7x | 29.8x | 84.4% |
| Saia | $343.92 | $9.3B | $0.62B | 15.2x | 0.3x | 24.4x | 91.9% |
| TFI International | $134.18 | $13.9B | $0.99B | 14.0x | 2.9x | 17.0x | not pure LTL |
| ArcBest | $135.56 | $3.3B | $0.29B | 11.5x | 1.0x | 14.3x | 96.2% |
| Peer median | 15.2x | 1.0x | 24.4x | ||||
| FedEx Freight | $128.75 | $25.1B | $1.54B (adj) | 16.3x | 3.8x | 25.5x | 92.2% |
| FedEx Freight on our 85% mid-cycle | $1.93B | 13.0x | 3.0x | 21.6x |
Three readings, and they point the same way.
1. On trailing numbers there is no discount. 16.3x against a peer median of 15.2x, and a forward P/E of 25.5x against a median of 24.4x. FedEx Freight is priced slightly above the middle of its own industry — while carrying a trough operating ratio, no standalone quarter of history, and a mandatory 19.9% seller in the register.
2. On mid-cycle numbers it is modestly cheap, and correctly so. At 13.0x it sits below the median. But it should: it is the most levered carrier in the group by a wide margin. Net debt including leases is 3.8x EBITDA. Old Dominion runs net cash. Saia is at 0.3x. The two names closest to FedEx Freight on leverage — XPO at 2.7x and TFI at 2.9x — are both still a full turn less levered. A cyclical carrying 3.8x into a downturn deserves a lower multiple than one carrying none, and the ~2-turn discount to Old Dominion does not obviously cover the difference.
3. The multiple spread across this group is enormous, and it tracks the operating ratio almost exactly. Old Dominion at 74.5% earns 22.8x. ArcBest at 96.2% earns 11.5x. The market pays roughly one turn of EV/EBITDA for every 120 basis points of operating ratio. That is the clearest evidence available that the operating-ratio assumption is the entire valuation, and it is a useful cross-check on our own work: moving FedEx Freight from an 82.5% mid-cycle to 85% should cost roughly two turns, which is close to what the DCF independently says.
The one number that should give a bull pause. Old Dominion — the best operator in the industry, with net cash, a 74.5% operating ratio and decades of standalone execution — trades at 22.8x. FedEx Freight, at 3.8x leverage with no public track record and an operating ratio 18 points worse, trades at 16.3x. That is a 28% discount for a very large difference in quality.
In depth: is FedEx Freight an acquisition target?
Not before June 1, 2028, and the retained stake is the reason.
The separation was structured to be tax-free under §355. An acquisition of 50% or more of FedEx Freight’s stock within two years is presumed to be part of a plan related to the distribution, which would make the separation taxable to FedEx — and the tax matters agreement places that cost on this side of the line.
The 19.9% retained stake cuts the same way twice. It must be sold by June 2028 to preserve the tax-free treatment, and until it is sold there is a large holder whose disposal FedEx must complete on a schedule. A buyer arriving before then would collide with both constraints at once.
After that date, the picture is more interesting than for most spinoffs of this size. A national LTL network is a scarce asset with a short list of natural owners — and a company trading at a 13-point operating-ratio discount to best-in-class is, in principle, exactly what a strategic acquirer or an activist would want to fix. The catalyst is real but it is dated 2028, and the shares must be underwritten on their own economics until then.
Tail scenarios
Outcomes outside the base/bull/bear frame — low probability, high magnitude, but short of black swan. The convenient thing about this company is that the operating ratio converts almost everything into share price at a known rate: roughly $6 per 100 basis points.
Upside tails
1. Another carrier fails. This industry has just demonstrated what that is worth. Yellow liquidated in August 2023, and in the two years around it FedEx Freight’s operating ratio went from 87.2% to 80.0%. Two names in the peer table are currently candidates: ArcBest at a 96.2% operating ratio is not covering the cost of hauling freight, and Saia at 91.9% is deteriorating after buying Yellow’s terminals into a downturn. ArcBest is roughly $4B of revenue. If a capacity exit of that size delivered even a third of what Yellow delivered — 240 basis points — that is about $14 a share, and FedEx Freight is the largest network and the natural taker of the freight.
2. The forced seller clears, and the overhang goes with it. FedEx must place ~30.1 million shares by June 2028. That is the single largest identifiable source of supply in this stock and it is dated, mechanical and public — which is exactly why it suppresses the price. A clean placement removes it permanently, and the stock is already 14% below where it started trading. The overhang is the reason to wait; its removal is the reason the wait ends.
3. The CEO repeats what he did last time. Smith ran this business from August 2018 to February 2021 and the operating ratio improved 470 basis points across FY2019–FY2021. Applying the same improvement from today’s 88.3% reaches 83.6% — which is roughly the mid-cycle this page used to assume, and about $28 a share above our 85% base case. This is the bull case in one sentence, and it is not a fantasy: the man has done it in this building.
Downside tails
1. Organized labor arrives. The 10-K names a specific, dated catalyst: “In June 2026, the U.S. House of Representatives passed the Faster Labor Contracts Act which, if enacted, would alter the process for negotiating initial collective bargaining agreements following union organization efforts,” and warns that the NLRB “could take actions that make it easier for our employees … to organize.”
FedEx Freight is the largest non-union LTL carrier in the country. ArcBest is the unionized one, and it runs a 96.2% operating ratio against FedEx Freight’s 88.3%. Salaries and benefits are 48.6% of revenue — $4,276M. Not all of that 7.9-point gap is the labor model, but some of it is. Closing even a third of it costs roughly $230M of operating income — 22% of adjusted operating profit, and about $16 a share. This is the largest single structural risk on the page and it has a legislative clock attached.
2. The covenant binds before the cycle turns. Total leverage must stay under 3.50x from roughly January 2027. At $4,299M of gross debt against $1,544M of adjusted EBITDA, the company sits near 2.8x — about 20% of EBITDA headroom. FY2026 adjusted EBITDA already fell more than that from FY2025. A second year of the same decline puts a first-year public company into a covenant conversation, at which point dividends and buybacks are unavailable and the lenders set the agenda.
3. Capital spending catches up at the worst moment. Capex has run at 84% of depreciation and falling. That is not sustainable for a fleet of ~30,000 vehicles. The catch-up spend lands on the same years as the covenant step-down and the trough cash flow — three pressures converging, which is how balance sheets that look fine on paper become binding in practice.
4. The volume decline is structural, not cyclical. This is the tail the nine-year table exposes and it is the one least discussed. Weight per shipment has fallen from 1,161 pounds in FY2017 to 946 in FY2024 — down 19% — and shipments per day from a FY2019 peak of 112.7k to 86.1k, down 24%. Revenue has been held up almost entirely by price: $235 to $387 per shipment. If the freight itself is permanently lighter and less frequent — nearshoring, smaller and more frequent retail replenishment, e-commerce parcel taking the light end — then the ~$9.3B revenue base every mid-cycle calculation on this page assumes may not return. Every 5% shortfall against $9.3B is worth roughly $9 a share.
5. Independence arrives late, and the standalone cost base is understated until it does. FedEx Freight is still buying services from FedEx under a transition agreement that can run 24 months, still licensing the brand it trades under, and still 19.9% owned. The first “standalone” quarters will not show the full standalone cost. The 10-K says the company “anticipates” further one-time costs and that replacement services “may vary from the historical costs.” If the true run-rate of independence is even 50 basis points of revenue above what is currently absorbed, that is $44M a year and about $3 a share — small on its own, but it lands on top of everything else in this list and it will be mistaken for operating deterioration when it appears.
What would change this view
| Direction | Trigger |
|---|---|
| Better | The first standalone quarter showing an adjusted operating ratio below 87%, which would make the self-help case credible rather than hoped-for · average daily shipments returning to growth · a credible multi-year operating-ratio target with milestones · FedEx placing its 19.9% in a single block at a modest discount, clearing the overhang early |
| Worse | Operating ratio above 89% in the first standalone quarter · shipments still falling into calendar 2027 · union organizing succeeding at scale, against salaries already at 48.6% of revenue · leverage rising as free cash flow stays negative |
| Dated, next 12 months | The first two standalone quarters (autumn 2026 and early 2027) · the 3.50x leverage covenant taking effect around January 2027 · Senate action on the Faster Labor Contracts Act, which passed the House in June 2026 |
| Would move mid-cycle back up | Two consecutive years near 84% or better, which would make FY2025 look like a floor rather than the middle · a competitor exiting capacity, as Yellow did in 2023 |
| Thesis-breaking | Loss or material renegotiation of the FedEx Trademark License Agreement · a debt-funded acquisition before the operating ratio is fixed · union representation at scale |
Investment Scorecard
Scored on the five weighted dimensions set out in our methodology.
| Dimension | Weight | Score | Rationale |
|---|---|---|---|
| Financial Profile | 25% | 2.5 | Trough operating ratio of 88.3%, volumes −4%, net leverage 2.62x (3.80x including leases — the highest in the LTL peer group), negative FY2026 free cash flow and no dividend. Marked down further on the three-year cash flow record: FedEx extracted $6.1B against $2.0B of free cash flow generated, capital expenditure has fallen to 84% of depreciation on a 30,000-vehicle fleet, and the 3.50x covenant leaves roughly 20% of EBITDA headroom. Offset by $8.8B of revenue, an undrawn $1.2B revolver and no forcing maturity |
| Competitive Position | 25% | 3.5 | Largest LTL network in North America, a terminal footprint that cannot be replicated, a proven share-taker when capacity exits, and pricing power that held through the downturn — revenue per shipment +64% since FY2017, still rising in the worst year. Marked down from 4.0 because the nine-year record does not support “second only to Old Dominion”: FedEx Freight ran 91.8–93.9% from FY2017 to FY2020 while Old Dominion was already far better. The gap to best-in-class is persistent, not cyclical |
| Strategic Rationale | 20% | 3.5 | Separating LTL from parcel lets the business be run for LTL economics, and Old Dominion demonstrates the ceiling. Discounted because $4.1B of debt-funded cash went to the parent and the leverage stayed here |
| Management & Governance | 20% | 3.5 | Raised from 2.5 on the leadership disclosure. CEO John Smith ran this exact business 2018–2021 and improved its operating ratio 470bp; CFO Marshall Witt was a public-company CFO for twelve years and executed the Concentrix spinoff; the board carries two career transport operators, three former CFOs and a spinoff veteran. That is not an unproven team. Held below 4.0 not for conflict — FedEx owns 19.9% and its interests are aligned on the placement — but because four of nine directors have direct former-parent ties, including a current FedEx employee: this is a partly-owned affiliate, not yet an independent company |
| Acquisition Potential | 10% | 2.5 | Blocked until June 2028 by §355(e) and by the retained stake that must itself be sold by then. Beyond that date, a scarce national network trading below best-in-class economics is a natural target — and a plausible consolidator itself |
| Weighted Score | 3.15 | ||
| Investment Grade | B+ · Solid Opportunity |
What the value-chain work changed: the diagnosis, not the score
Nothing moved, and the reason is more interesting than a quarter-point would have been. Setting out the bargaining position properly does not make the competitive case worse — it relocates the problem.
- Competitive Position holds at 3.5. The terminal network is a genuine barrier to entry and the section confirms it. What it also establishes is that no LTL carrier has pricing power independent of industry capacity, so the 88.3% operating ratio is not a market-power failure. Old Dominion earns 74.5% on the same class of asset against the same industry price.
- Management & Governance holds at 3.5. The fourteen-point gap to best-in- class is density and execution, which is management’s to close — but the current gap predates this chief executive, and he improved the operating ratio 470 basis points the last time he held the job.
The target is unchanged at $108. What the section changes is the character of the wait: you are not waiting for pricing power that never existed, you are waiting for volume to refill a network that is already built. That is a more tractable proposition than the operating ratio alone suggests, and it is the strongest structural argument for the eventual BUY.
Proposed grade change: A− (3.80) → B+ (3.15)
A one-notch downgrade on new disclosure. The A− was set before separation. Three items in the August filings were not previously visible:
- $373M of related-party interest income inside reported profit that ends at separation, against $206M of new interest expense — a ~$579M structural swing in pre-tax income;
- $4.1B of debt-funded cash paid to the former parent, leaving 2.62x leverage here;
- a mandatory 19.9% disposal by June 2028, which the 10-K itself says “may decrease the market price.”
What does not justify a downgrade — and an earlier draft of this analysis wrongly treated as though it did — is the 88.3% operating ratio by itself. That is a trough figure in a cyclical industry. Valuing a freight carrier off its worst year is a category error.
What the nine-year record adds, and why 3.20 became 3.15. Two further markdowns, each charged to one dimension only:
- Financial Profile 3.0 → 2.5, on the cash flow record: $6.1B extracted by the parent against $2.0B of free cash flow generated, capital expenditure at 84% of depreciation, and ~20% of covenant headroom.
- Competitive Position 4.0 → 3.5, because “second only to Old Dominion in a normal year” does not survive the longer record — FY2017 to FY2020 ran 91.8–93.9%.
And one markdown reversed, by a full point. Management & Governance 2.5 → 3.5. The “no standalone track record” penalty was simply wrong: the CEO ran this business for two and a half years and improved its operating ratio 470 basis points, and the CFO has taken a company through a separation before.
We also reversed our own first reading of the board. An earlier draft of this page scored the shared chairman as the clearest governance markdown here. That was a mistake: FedEx owns 19.9% of the company, so on the placement — the one decision where a conflict would bite — its interests are aligned with everyone else’s, not opposed to them. What the board composition really shows is that FedEx Freight is not yet independent, which is a fact about the company, not a failing of its governance. It is scored as such, and it holds the dimension at 3.5 rather than 4.0.
Strategic Rationale is deliberately unchanged at 3.5. The parent’s cash extraction is the same fact already charged to Financial Profile, and charging it twice would be double-counting a single objection.
The standing A− remains our published grade until the next report carries the change.
What would earn the grade back: two or three standalone quarters showing the operating ratio turning, and the retained stake placed. This is the largest LTL network in North America, run by the executive who last improved it, in an industry with two carriers currently not covering their cost of freight — the questions here are about price, leverage and timing, not about whether the business is any good.