Honeywell Aerospace HONA
-30.0%vs Day 1Spinoff of Honeywell (HON) · Classic Spinoff (3-Way) · Spun Jun 29, 2026
Expected return (11/13/2026): +17% Gain to loss: 4.1 : 1Largest pure-play aerospace supplier: $19.3B backlog (+12%), guidance held and earnings per share raised at Q3 2026, first dividend declared. The commercial aftermarket (+2%) and the segment margin (25.0%, 23.9% without tariff refunds) are still held back by a few constrained suppliers. Spun with $16B of fixed-rate debt and nothing due before 2028.
Current Stats
Post-Spinoff Performance
| Timeline | |
| Spinoff date | June 29, 2026 · S&P 500 (Nasdaq) |
| Days since spinoff | 138 days |
| Structure | Classic Spinoff |
| §355(e) window closes statutory; a tax matters agreement may bar more, and for longer | June 29, 2028 |
| Parent | Honeywell (HON) |
| Day-1 reaction | |
| Day 1 open | $230.00 |
| Day 1 return (open→close) | -4.3% |
| Day 1 price (close) | $220.19 |
| Day 1 range | $212.50 – $239.98 +12.9% spread |
| Day 1 low held? | Breached after 9 sessions to -30.6% below |
| Price levels | |
| Post-spin low (closing) | $149.59 on Nov 5, 2026 · 129 days post-spin |
| Lowest traded | $147.40 on Nov 6, 2026 · 130 days post-spin |
| Current price (Nov 13, 2026) | $165.01 |
| Returns | |
| Return vs Day 1 (close) | -24.9% |
| — range by day 1 entry theoretical bounds | -31.1% to -22.2% |
| Return vs post-spin low (price) | +10.3% |
| Total return vs low incl. dividends since | +10.6% |
| First-quarter return (≈90d) | -27.9% |
| Versus benchmarks | |
| S&P 500 over same window | +2.0% |
| Shares & ownership | |
| Shares outstanding Sep 30, 2026 | 317,031,836 |
| Diluted average shares the EPS denominator | 317,700,000 |
| Free float | 316,635,546 100% of shares outstanding |
| Held by institutions | 80% insiders 0.9% |
| Share count trend Dec 2025 → Sep 2026 | +0.0% broadly flat |
| Volume & liquidity | |
| Traded per day 20-session median | $485M |
| Normal volume baseline | 3,100,550 shares · now 0.97x |
| Day 1 volume | 2.7x normal · first week 2.2x |
| Decay | half in 8 sessions · normal by 8 |
Computed from split-adjusted closing prices. Returns are total return — (end price + dividends received − start price) ÷ start price — with no reinvestment assumed.
Price History
Closing price, split-adjusted, with volume below. The Price line excludes dividends; Price + dividends adds the cash paid out, with no reinvestment assumed. Individual payments are listed in the table below. Source: Yahoo Finance. Data through Nov 14, 2026.
Raw daily price & volume data · dividends marked
| Date | Open | High | Low | Close | Volume | Float | Turnover | Market cap | Dividend | Split |
|---|---|---|---|---|---|---|---|---|---|---|
| 2026-11-13 | $166.23 | $167.35 | $162.78 | $165.01 | 2,853,700 | 316,635,546 | 0.90% | $52.31B | $0.40 | — |
| 2026-11-12 | $168.28 | $170.63 | $166.11 | $166.23 | 2,642,900 | 316,635,546 | 0.83% | $52.70B | — | — |
| 2026-11-11 | $166.47 | $169.65 | $165.37 | $169.53 | 2,289,700 | 316,635,546 | 0.72% | $53.75B | — | — |
| 2026-11-10 | $163.44 | $167.87 | $163.01 | $166.47 | 2,694,200 | 316,635,546 | 0.85% | $52.78B | — | — |
| 2026-11-09 | $155.87 | $167.30 | $154.45 | $164.77 | 3,956,200 | 316,635,546 | 1.25% | $52.24B | — | — |
| 2026-11-06 | $149.29 | $154.23 | $147.40 | $152.92 | 2,611,600 | 316,635,546 | 0.82% | $48.48B | — | — |
| 2026-11-05 | $155.77 | $158.17 | $148.50 | $149.59 | 3,722,600 | 316,635,546 | 1.17% | $47.42B | — | — |
| 2026-11-04 | $158.51 | $162.44 | $154.46 | $156.39 | 4,974,500 | 316,635,546 | 1.57% | $49.58B | — | — |
| 2026-11-03 | $159.75 | $161.30 | $156.23 | $157.50 | 3,292,600 | 316,635,546 | 1.04% | $49.93B | — | — |
| 2026-11-02 | $157.26 | $161.70 | $156.79 | $157.95 | 3,977,400 | 316,635,546 | 1.25% | $50.08B | — | — |
| 2026-10-30 | $158.58 | $161.49 | $151.31 | $154.15 | 5,241,300 | 316,638,717 | 1.65% | $48.87B | — | — |
| 2026-10-29 | $166.18 | $166.18 | $153.00 | $160.04 | 7,433,700 | 316,638,717 | 2.34% | $50.74B | — | — |
| 2026-10-28 | $165.96 | $177.47 | $163.67 | $177.03 | 5,342,400 | 316,638,717 | 1.69% | $56.12B | — | — |
| 2026-10-27 | $168.54 | $169.14 | $165.63 | $167.90 | 2,517,200 | 316,638,717 | 0.79% | $53.23B | — | — |
| 2026-10-26 | $164.15 | $169.04 | $164.06 | $168.64 | 2,632,300 | 316,635,546 | 0.83% | $53.46B | — | — |
| 2026-10-23 | $160.37 | $167.85 | $155.54 | $163.31 | 3,360,300 | 316,603,750 | 1.06% | $51.77B | — | — |
| 2026-10-22 | $162.08 | $164.51 | $160.39 | $163.02 | 2,919,000 | 316,556,534 | 0.92% | $51.68B | — | — |
| 2026-10-21 | $159.99 | $163.64 | $159.56 | $162.46 | 1,913,200 | 316,556,534 | 0.60% | $51.50B | — | — |
| 2026-10-20 | $162.75 | $164.88 | $158.45 | $159.90 | 3,090,600 | 316,556,534 | 0.97% | $50.69B | — | — |
| 2026-10-19 | $169.12 | $169.40 | $162.43 | $162.49 | 2,436,300 | 316,556,534 | 0.77% | $51.51B | — | — |
| 2026-10-16 | $164.25 | $170.30 | $163.13 | $168.09 | 5,085,800 | 316,556,534 | 1.60% | $53.29B | — | — |
| 2026-10-15 | $157.96 | $164.90 | $156.47 | $163.11 | 2,433,400 | 316,556,534 | 0.77% | $51.71B | — | — |
| 2026-10-14 | $157.44 | $159.20 | $155.21 | $156.73 | 2,155,900 | 316,556,534 | 0.68% | $49.69B | — | — |
| 2026-10-13 | $157.33 | $159.63 | $155.10 | $158.18 | 1,433,400 | 316,556,534 | 0.45% | $50.15B | — | — |
| 2026-10-12 | $156.84 | $159.20 | $156.07 | $157.27 | 1,604,800 | 316,556,534 | 0.51% | $49.86B | — | — |
| 2026-10-09 | $154.27 | $158.42 | $152.56 | $157.94 | 2,937,200 | 316,556,534 | 0.93% | $50.07B | — | — |
| 2026-10-08 | $151.73 | $154.30 | $149.88 | $154.01 | 3,264,100 | 316,556,534 | 1.03% | $48.83B | — | — |
| 2026-10-07 | $154.80 | $155.69 | $151.15 | $153.07 | 1,985,200 | 316,524,839 | 0.63% | $48.53B | — | — |
| 2026-10-06 | $156.19 | $160.00 | $154.95 | $157.39 | 2,017,100 | 316,524,839 | 0.64% | $49.90B | — | — |
| 2026-10-05 | $153.88 | $156.15 | $152.20 | $155.74 | 2,501,100 | 316,524,839 | 0.79% | $49.37B | — | — |
| 2026-10-02 | $155.37 | $156.92 | $153.52 | $154.63 | 1,782,900 | 316,524,839 | 0.56% | $49.02B | — | — |
| 2026-10-01 | $155.17 | $155.99 | $152.26 | $154.07 | 2,582,600 | 316,524,839 | 0.81% | $48.85B | — | — |
| 2026-09-30 | $155.60 | $156.89 | $153.42 | $154.97 | 2,384,600 | 316,559,704 | 0.75% | $49.13B | — | — |
| 2026-09-29 | $151.81 | $156.10 | $151.39 | $155.44 | 2,542,800 | 316,559,704 | 0.80% | $49.27B | — | — |
| 2026-09-28 | $157.31 | $158.00 | $151.85 | $152.32 | 3,699,400 | 316,559,704 | 1.17% | $48.28B | — | — |
| 2026-09-25 | $159.01 | $160.97 | $156.74 | $158.78 | 2,285,000 | 316,559,704 | 0.72% | $50.32B | — | — |
| 2026-09-24 | $161.57 | $163.97 | $158.29 | $158.46 | 2,765,500 | 316,559,704 | 0.87% | $50.22B | — | — |
| 2026-09-23 | $166.70 | $168.50 | $161.57 | $163.33 | 2,976,400 | 316,559,704 | 0.94% | $51.77B | — | — |
| 2026-09-22 | $168.98 | $169.27 | $166.03 | $167.32 | 3,873,700 | 316,559,704 | 1.22% | $53.03B | — | — |
| 2026-09-21 | $163.85 | $170.32 | $163.00 | $169.03 | 3,974,700 | 316,559,704 | 1.25% | $53.57B | — | — |
| 2026-09-18 | $166.99 | $167.15 | $162.00 | $163.60 | 13,256,000 | 316,559,704 | 4.18% | $51.85B | — | — |
| 2026-09-17 | $169.74 | $169.74 | $164.75 | $167.13 | 7,623,300 | 316,559,704 | 2.41% | $52.97B | — | — |
| 2026-09-16 | $159.73 | $166.21 | $158.82 | $164.18 | 4,624,900 | 316,559,704 | 1.46% | $52.04B | — | — |
| 2026-09-15 | $163.55 | $164.62 | $158.10 | $158.50 | 5,280,900 | 316,559,704 | 1.67% | $50.23B | — | — |
| 2026-09-14 | $154.00 | $165.00 | $154.00 | $164.08 | 4,121,500 | 316,559,704 | 1.30% | $52.00B | — | — |
| 2026-09-11 | $154.68 | $158.44 | $154.35 | $158.26 | 2,516,700 | 316,559,704 | 0.79% | $50.16B | — | — |
| 2026-09-10 | $150.03 | $155.34 | $149.19 | $153.75 | 3,155,000 | 316,559,704 | 1.00% | $48.73B | — | — |
| 2026-09-09 | $154.50 | $155.03 | $150.97 | $151.58 | 3,178,800 | 316,559,704 | 1.00% | $48.04B | — | — |
| 2026-09-08 | $158.64 | $160.35 | $154.78 | $155.42 | 4,516,100 | 316,559,704 | 1.42% | $49.26B | — | — |
| 2026-09-04 | $155.00 | $161.29 | $154.03 | $161.01 | 3,167,300 | 316,559,704 | 1.00% | $51.03B | — | — |
| 2026-09-03 | $152.44 | $155.88 | $150.88 | $154.96 | 3,905,400 | 316,559,704 | 1.23% | $49.11B | — | — |
| 2026-09-02 | $154.31 | $154.79 | $151.97 | $152.55 | 2,770,500 | 316,559,704 | 0.87% | $48.35B | — | — |
| 2026-09-01 | $158.29 | $159.25 | $153.63 | $154.24 | 2,667,900 | 316,559,704 | 0.84% | $48.88B | — | — |
| 2026-08-31 | $161.00 | $161.21 | $155.97 | $158.11 | 4,261,800 | 316,566,043 | 1.34% | $50.11B | — | — |
| 2026-08-28 | $160.85 | $163.58 | $158.80 | $162.37 | 2,540,400 | 316,566,043 | 0.80% | $51.46B | — | — |
| 2026-08-27 | $162.16 | $163.92 | $158.90 | $160.75 | 3,048,200 | 316,566,043 | 0.96% | $50.95B | — | — |
| 2026-08-26 | $160.51 | $167.57 | $160.29 | $164.01 | 3,731,300 | 316,566,043 | 1.18% | $51.98B | — | — |
| 2026-08-25 | $161.89 | $163.82 | $159.11 | $160.36 | 2,556,300 | 316,566,043 | 0.81% | $50.82B | — | — |
| 2026-08-24 | $164.60 | $166.85 | $160.89 | $161.20 | 3,110,500 | 316,566,043 | 0.98% | $51.09B | — | — |
| 2026-08-21 | $166.77 | $168.44 | $164.23 | $164.73 | 4,053,400 | 316,566,043 | 1.28% | $52.21B | — | — |
| 2026-08-20 | $170.00 | $172.94 | $164.99 | $165.89 | 3,035,200 | 316,566,043 | 0.96% | $52.58B | — | — |
| 2026-08-19 | $165.95 | $176.25 | $164.26 | $170.37 | 7,279,600 | 316,566,043 | 2.30% | $54.00B | — | — |
| 2026-08-18 | $160.87 | $164.61 | $160.39 | $160.76 | 4,707,000 | 316,566,043 | 1.49% | $50.95B | — | — |
| 2026-08-17 | $166.00 | $166.53 | $161.25 | $161.56 | 3,566,100 | 316,566,043 | 1.13% | $51.20B | — | — |
| 2026-08-14 | $169.69 | $171.49 | $165.03 | $166.36 | 3,418,100 | 316,566,043 | 1.08% | $52.73B | — | — |
| 2026-08-13 | $166.80 | $171.20 | $165.11 | $169.81 | 2,508,000 | — | 0.79% | $53.82B | — | — |
| 2026-08-12 | $168.91 | $173.00 | $166.84 | $167.80 | 4,087,500 | — | 1.29% | $53.18B | — | — |
| 2026-08-11 | $161.99 | $170.17 | $161.23 | $165.93 | 4,337,300 | — | 1.37% | $52.59B | — | — |
| 2026-08-10 | $163.35 | $165.49 | $159.01 | $163.09 | 4,798,200 | — | 1.51% | $51.69B | — | — |
| 2026-08-07 | $156.24 | $168.88 | $154.01 | $168.51 | 8,048,300 | — | 2.54% | $53.41B | — | — |
| 2026-08-06 | $155.00 | $167.31 | $150.03 | $156.47 | 20,631,100 | — | 6.51% | $49.59B | — | — |
| 2026-08-05 | $219.42 | $222.54 | $203.64 | $203.64 | 4,401,500 | — | 1.39% | $64.54B | — | — |
| 2026-08-04 | $211.03 | $217.06 | $207.40 | $216.48 | 2,816,300 | — | 0.89% | $68.61B | — | — |
| 2026-08-03 | $203.99 | $211.00 | $199.48 | $208.27 | 3,328,300 | — | 1.05% | $66.01B | — | — |
| 2026-07-31 | $202.31 | $209.77 | $202.01 | $206.74 | 2,319,000 | — | 0.73% | $65.52B | — | — |
| 2026-07-30 | $205.29 | $205.29 | $198.88 | $204.32 | 2,174,100 | — | 0.69% | $64.76B | — | — |
| 2026-07-29 | $215.90 | $215.90 | $203.84 | $205.19 | 2,102,500 | — | 0.66% | $65.03B | — | — |
| 2026-07-28 | $208.85 | $219.20 | $208.85 | $215.90 | 2,215,400 | — | 0.70% | $68.43B | — | — |
| 2026-07-27 | $206.33 | $211.79 | $202.98 | $210.83 | 1,850,500 | — | 0.58% | $66.82B | — | — |
| 2026-07-24 | $198.29 | $204.91 | $192.03 | $204.07 | 2,709,400 | — | 0.85% | $64.68B | — | — |
| 2026-07-23 | $200.59 | $208.64 | $193.33 | $195.87 | 3,436,200 | — | 1.08% | $62.08B | — | — |
| 2026-07-22 | $200.30 | $208.70 | $199.01 | $207.78 | 2,348,800 | — | 0.74% | $65.85B | — | — |
| 2026-07-21 | $202.86 | $203.50 | $195.16 | $200.14 | 3,221,200 | — | 1.02% | $63.43B | — | — |
| 2026-07-20 | $207.28 | $210.00 | $198.88 | $202.47 | 3,279,200 | — | 1.03% | $64.17B | — | — |
| 2026-07-17 | $207.52 | $217.83 | $205.01 | $211.63 | 2,548,500 | — | 0.80% | $67.07B | — | — |
| 2026-07-16 | $211.70 | $215.79 | $204.20 | $208.37 | 2,878,500 | — | 0.91% | $66.04B | — | — |
| 2026-07-15 | $203.15 | $215.50 | $203.00 | $212.55 | 2,107,800 | — | 0.67% | $67.37B | — | — |
| 2026-07-14 | $213.05 | $215.98 | $205.56 | $207.51 | 3,334,200 | — | 1.05% | $65.77B | — | — |
| 2026-07-13 | $220.67 | $221.59 | $210.23 | $213.05 | 2,956,700 | — | 0.93% | $67.52B | — | — |
| 2026-07-10 | $222.78 | $228.95 | $218.85 | $220.75 | 1,926,200 | — | 0.61% | $69.96B | — | — |
| 2026-07-09 | $225.67 | $230.90 | $217.25 | $223.12 | 3,395,200 | — | 1.07% | $70.72B | — | — |
| 2026-07-08 | $230.59 | $235.95 | $223.03 | $224.35 | 4,156,700 | — | 1.31% | $71.11B | — | — |
| 2026-07-07 | $237.93 | $246.02 | $233.64 | $238.14 | 4,866,100 | — | 1.54% | $75.48B | — | — |
| 2026-07-06 | $249.01 | $266.62 | $236.70 | $237.70 | 7,550,800 | — | 2.38% | $75.34B | — | — |
| 2026-07-02 | $229.99 | $248.73 | $221.50 | $247.15 | 5,557,200 | — | 1.75% | $78.33B | — | — |
| 2026-07-01 | $212.92 | $231.73 | $212.57 | $227.29 | 6,509,700 | — | 2.05% | $72.04B | — | — |
| 2026-06-30 | $220.85 | $227.99 | $214.50 | $221.08 | 5,986,300 | — | 1.89% | $70.07B | — | — |
| 2026-06-29 | $230.00 | $239.98 | $212.50 | $220.19 | 8,471,200 | — | 2.67% | $69.81B | — | — |
Close is split-adjusted to current shares. It is not dividend-adjusted: dividends are listed separately, so total return is (end price + dividends received − start price) ÷ start price, checkable by hand. Volume is as-traded.
Momentum: MACD and RSI
Top: MACD (navy) and its signal line (gold); bars show the gap between them, teal when MACD is above.
Bottom: RSI over 14 days; above 70 is usually read as overbought and below 30 as oversold.
The lines start late because MACD needs 26 trading days of prices and RSI 14 before the first value.
The colored strip under the charts shows the state label day by day; hover for the state and the reason.
Both measure momentum in the price and say nothing about value. Hover for each day's arithmetic.
Source: closing prices from this site's daily price archive (Yahoo Finance), not adjusted for dividends. Data through Nov 14, 2026.
How these are calculated
Short Selling
Bars: shares sold short each day in trades reported to FINRA (off-exchange
trades, roughly half of all volume).
Line: the short share of that volume, averaged over 20 sessions.
Gold points: short interest, the shares sold short and not yet bought back,
reported twice a month, also shown as a percentage of the free float and of
shares outstanding.
Daily short volume includes market makers' routine hedging, so a change in the
share is more informative than its level. Hover for each day's figures.
Sources: FINRA; float from this site's daily share records; shares outstanding
from the company's latest quarterly filing. Data through Nov 13, 2026.
Index-Fund Holdings
Daily positions of State Street's SPDR index funds, by the fund's file date.
These are the index funds whose daily holdings can be collected; iShares and
Vanguard funds, often larger holders, publish holdings that cannot be
collected automatically and appear in the written analysis from their
quarterly filings.
Collection began on October 11, 2026. A fund that drops the stock shows as an
exit.
Source: State Street Global Advisors. Data through
Nov 12, 2026.
Update — October 29, 2026: third-quarter results — BUY → ACCUMULATE, target $197 → $192
Rated at the October 29, 2026 close of $160.04, the first session after the results, which were released after the October 28 close of $177.03. Sources: the third-quarter results release and the 8-K of October 28, 2026 (results, the first dividend, the Tempe plant), and the second-quarter results release for the earlier guidance, the third-quarter 10-Q filed the same evening, and the conference call (transcript). Earlier sections are left as published.
The one-line version
The third quarter passed every test the October 6, 2026 update set except supply. Guidance was held on sales and raised on earnings per share and second-half free cash flow, the backlog grew 12% to $19.3 billion, and the company declared its first dividend, $0.40 a quarter. The commercial aftermarket grew only 2%, still limited by parts from a small number of suppliers, and the segment margin, 25.0%, was 0.4 points below a year earlier even with about $50 million of one-off tariff refunds in it. Management expects no refunds in the fourth quarter and a margin back in the mid-23s. The stock gave back its pre-results rise. It rose from $157.27 on October 12 to $177.03 on October 28, then fell 9.6% to $160.04 on October 29, a day aerospace and defense stocks (ITA) rose 3.2%, as the call pointed to a flat margin in 2027. The valuation now charges capital spending at the company’s 2026 rate, 3.5% of sales against 3.1%, which takes about $5.60 a share off the base case, partly offset by lower net debt; the target moves from $197 to $192. At $160.04 the expected return is 20% and the gain to loss 5.1 to 1, inside the ACCUMULATE band; BUY on the common rating scale needs 25%, below about $154.
Rating: BUY below $154 · ACCUMULATE $154–175 · HOLD $175–214 · TRIM above $214 · Target $192 · Grade: B+ (3.20)
What happened since October 13
| Date | Event | Read |
|---|---|---|
| Oct 13–28 | The stock rose 12.6%, from $157.27 to $177.03, including 5.4% on October 28 before the results. Over the same days ITA rose 0.8%, RTX 4.9% and TransDigm 1.5%; GE Aerospace fell 2.4%, Howmet 11.6% and Boeing 11.8%. No company news explains the move | The discount to the valuation had mostly closed before the results |
| Oct 28 | Third-quarter results and updated guidance (below) | Passes on guidance, cash and orders; supply and margin still weak |
| Oct 28 | First quarterly dividend, $0.40 a share, record November 13, paid December 4, 2026 | About $507 million a year, 20% of 2026 adjusted earnings per share; a yield of 0.9% |
| Oct 29 | The stock fell 9.6% on the day after the results, to $160.04 on 7.4 million shares, about three times its recent daily volume, while ITA rose 3.2% and GE Aerospace, Howmet, TransDigm and HEICO rose 3.5–5.5%. JPMorgan cut its target to $210 from $235 (Rallies) and RBC to $210 from $250 | The market reset its 2027 expectations (below) |
| Oct 28 | A new plant in Tempe, Arizona: $500 million, 300,000 square feet, opening in late 2028, about 600 jobs. It brings complex machining, which the supply base is short of, in house, for Control Systems products and $15 billion of new program wins | Addresses the supply constraint, from 2029 |
No repurchases were made under the $3.5 billion authorization (third-quarter 10-Q).
The quarter against the tests
| Test (October 6, 2026) | Third quarter | Verdict |
|---|---|---|
| Guidance: no second cut; 4–5% organic growth reaffirmed | Organic growth 4–5% held; adjusted EBIT narrowed to $4.375–4.425 billion (midpoint $4.40 billion, unchanged); adjusted earnings per share raised to $7.85–8.00 from $7.60–7.90 | Passes |
| Second-half free cash flow on track; below $1.0 billion would end the BUY | $500 million in the third quarter. The second-half range was raised to $1.2–1.4 billion, which leaves $0.7–0.9 billion for the fourth quarter | Passes |
| Orders: book-to-bill below 1 would raise the worst case’s weight | Backlog $19.3 billion, up 12% (up 9% at the second quarter); orders over the last twelve months up 9%, led by Defense and Space | Passes |
| Supply: output at the constrained suppliers improving | Commercial aftermarket growth “limited by mechanical component availability”; international defense volumes lower on supply. The chief executive reported “encouraging signs from pacing suppliers” and expects higher output in 2027 | Not yet |
| Segment margin stabilizing year on year | 25.0% against 25.4% in the third quarter of 2025, including about $50 million of tariff refunds; about 23.9% without them | Not yet |
| Aftermarket growth holding | +2% ($2.13 billion); commercial original equipment +8% organic | Weak |
| Capital allocation | First dividend declared; no repurchases | As expected |
- Adjusted earnings per share were $2.21, against a consensus of about $2.00 from four analysts (Unusual Whales). The second quarter had missed.
- The previous free-cash-flow range is shown as $1.0–1.4 billion in this release; the second-quarter release gave $1.0–1.5 billion, the figure used on this page. On either, the new range raises the midpoint.
- The full-year sales guidance needs little from the fourth quarter. Sales were up 4.8% in the first nine months; repeating the third quarter’s 2% in the fourth gives about 4% for the year, the bottom of the range.
What management said on the call
From the call on the evening of October 28, 2026 (transcript); Jim Currier is chief executive, Josh Jepsen chief financial officer.
- Supply is improving but still sets the pace. Currier: “Our suppliers produced more of what we needed from them across the four combined categories compared to last quarter.” Output rose 5% from the second quarter. Complex machining improved and castings are qualifying new sources; in bearings, “the most difficult category for us this year, a second-source supplier ramped its production considerably quarter over quarter.”
- The tariff refunds will not repeat. Jepsen: “For the fourth quarter, we do not currently anticipate any IEEPA tariff refunds, presenting a more than 100 basis point sequential margin headwind,” and the fourth-quarter margin “should be more similar to the first half of the year.” On the exit rate: “We will exit this year in the mid-23s. I think that is a good jumping-off point.”
- 2027. Currier expects output growth to “accelerate through 2027 as supply chain actions take hold”; Jepsen expects pricing to improve as long-term contracts with aircraft makers are renewed. No 2027 guidance was given.
- Capital spending and buybacks. Jepsen: “We continue to expect capital expenditures of about $650 million for the year,” with “a step-up next year,” the Tempe plant among the priorities. On buybacks: “we seek to opportunistically repurchase our shares.”
- The stock fell about 3% after hours, to about $172, from the $177.03 close (Investing.com).
Why the stock fell 10% the next day
The results beat on earnings per share and raised guidance, and the stock still fell about 3% after hours and 9.6% on October 29, 2026, to $160.04, on a day aerospace stocks rose. The reasons given in the call, in analyst notes and in commentary:
- 2027 margins look flat. The chief financial officer called the mid-23s exit margin “a good jumping-off point,” and JPMorgan’s analyst recalled management’s line that the path to 2030 is “not a linear path” in profit or margin. Jepsen added that 2027 carries investment in the supply base, in depreciation and operating costs. The 2025 standalone margin was 24.5%, so 2026 ends about a point lower, and 2027 is unlikely to win much of it back. Analysts who had a margin recovery in 2027 are lowering their estimates.
- Part of the beat will not repeat. About $50 million of tariff refunds (roughly $0.12 a share) lifted the third quarter; the fourth quarter loses them, and its organic sales will be “modestly below” the full-year range (Investing.com).
- More capital spending: $650 million in 2026 and a step-up in 2027 that includes the $500 million plant.
- Positioning. The stock had risen 13% in the two weeks before the results, the class actions filed after the August fall are still active, and aerospace investors reward “beats and raises” (Wolfe Research, August 2026, Yahoo Finance).
- The case made for the stock: demand is intact (orders up 12%, backlog a record), and Jepsen said supply shortfalls cost “about 4 points of growth” in the quarter (transcript). One independent writer reads the fall as the market mistaking a supply problem for a demand problem (Every Spinoff). Retail comment on StockTwits was mixed and light.
What it means for this valuation. The base case already had a slow margin recovery: about 23.9% in 2027, 24.4% in 2030 and 26% only by 2040. A margin held at 23.5% in 2027 and 2028 takes $0.44 a share off it. The assumption the results do put in question is growth: the model has revenue growing 8.5% in 2027, its peak year, against 2% in the third quarter and a fourth quarter below 4–5%. At 4% growth in 2027 the base case is $10.21 lower (table below).
The margin by segment
| Segment | Sales | Growth (organic) | Segment margin | Third quarter 2025 |
|---|---|---|---|---|
| Electronic Solutions | $1,784M | +4% (+5%) | 31.6% | 29.9% |
| Engines and Power Systems | $1,515M | +3% (+2%) | 16.5% | 20.2% |
| Control Systems | $1,345M | 0% (0%) | 28.4% | 27.9% |
| Total | $4,644M | +2% (+2%) | 25.0% | 25.4% |
Segment margin is segment adjusted EBIT over sales, from the release. The total includes corporate costs.
- The fall is in Engines and Power Systems, down 3.7 points, where the company cites unfavorable mix and higher costs; tariff refunds and price lifted the other two segments.
- Against the first half the margin is level. It was 23.6% in the first half of 2026; the third quarter’s 25.0% is 23.9% without the refunds, and management guides the fourth quarter to the mid-23s. The base case starts from about 23.8% in 2026 and needs the margin to reach 26% by 2040; the company’s new standalone costs are in the third quarter for the first time.
Cash, the dividend and the debt
- Cash rose to $1.56 billion at September 26, 2026, from $1.06 billion at the end of June. The $16.0 billion of notes is unchanged, so net debt fell to about $14.45 billion from the $14.8 billion this page has used, about 3.0 times 2026 adjusted EBITDA (an estimate). Net interest was $187 million in the quarter.
- The dividend takes about $507 million a year, about a fifth of the roughly $2.3 billion of free cash flow the business produced before 2026. It is paid from cash the valuation already counts and does not change it.
- Capital spending runs above the valuation’s, and the valuation now uses the company’s rate. The October 13, 2026 cases charged 3.1% of sales, about $570 million in 2026; the company expects about $650 million (3.5%), with a step-up in 2027 that includes the $500 million Tempe plant. The cases below charge 3.5% in every year, which takes $5.57 off the base case (an estimate). The 2027 guidance will show whether the step-up goes above 3.5%.
- The Honeywell trademark license cost $54 million in the quarter. The environmental accrual was $815 million at September 26, 2026, against $823 million at December 31, 2025 and the $828 million this page has used; $69 million was paid in the nine months. The company still says reasonably possible losses could make it two to three times higher.
- No shares were bought under the $3.5 billion authorization; the 10-Q shows 40,328 shares acquired outside it.
The scenarios and the asymmetry, at the new net debt and capital spending
The cases keep the October 13, 2026 assumptions with two changes. Net debt is $14.45 billion at September 26, 2026, which adds about $1.10 a share to each case, and capital spending is 3.5% of sales, the company’s 2026 rate, which takes $3.90 to $6.00 off. The results hold the 2026 adjusted EBIT midpoint and the organic growth range, which anchor the model’s first year.
| Best | Base | Worst | |
|---|---|---|---|
| October 13, 2026 (net debt $14.8B, capital spending 3.1%) | $242.47 | $205.58 | $109.79 |
| Net debt $14.45B | $243.57 | $206.68 | $110.90 |
| October 28, 2026 (and capital spending 3.5%) | $237.57 | $201.11 | $107.00 |
| vs $160.04 | +48% | +26% | −33% |
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $186.70 | +17% | 3.0 to 1 |
| Best guess: 15 / 70 / 15 (unchanged) | $192.46 | +20% | 5.1 to 1 |
| Stress: 10 / 40 / 50 | $157.70 | −1% | 0.9 to 1 |
| What the price implies: 0 / 56 / 44 | $160.04 | 0% | 1.0 to 1 |
The weights are a judgment. All values are estimates from the rebuilt model.
- The weights are unchanged. The October 13 update named the evidence that would raise the worst case’s weight: a cut to guidance or book-to-bill below 1. Neither happened. Evidence for the best case would be a margin recovering beyond the tariff refunds and aftermarket growth no longer held back by supply, and neither has happened yet either.
- The price is back near where it was before the rise. With no weight on the best case, $160.04 implies 56% on the base case and 44% on the worst, against 74% and 26% at the $177.03 close before the results and 50% and 50% at $157.27 on October 12. On single assumptions it implies the base growth path with the margin falling to 20.7%, below the 23.5% the company expects to exit 2026 at, or the base case at a 10.1% discount rate.
- The two chips at $160.04: expected return +20% and gain to loss 5.1 to 1, both blue, the ACCUMULATE band.
| Measure | At $160.04 | Formula |
|---|---|---|
| Expected return | +20% | (15% × $237.57 + 70% × $201.11 + 15% × $107.00) ÷ $160.04 − 1 |
| Gain to loss | 5.1 to 1 | (15% × $77.53 + 70% × $41.07) ÷ (15% × $53.04) = ($11.63 + $28.75) ÷ $7.96 |
| Expected base ÷ expected worst | 3.6 to 1 | $28.75 ÷ $7.96 |
| Best ÷ worst | 1.5 to 1 | $77.53 ÷ $53.04 |
| Base ÷ worst | 0.8 to 1 | $41.07 ÷ $53.04 |
| Change to the base case, one at a time | Value | Change |
|---|---|---|
| 2027 revenue growth 4% instead of 8.5% | $190.90 | −$10.21 |
| 2027 and 2028 margin held at 23.5% | $200.67 | −$0.44 |
| Both | $190.48 | −$10.63 |
On the best-guess weights, a base case of $190.48 gives a value of $185.02, a 16% expected return at $160.04.
What it means for the rating
BUY → ACCUMULATE, target $197 → $192. The target is the best-guess value, $192.46. The rating follows the site’s rating scale (see the Methodology page), applied here for the first time: BUY at an expected return of 25% or more with gain to loss of 3 to 1 or better, ACCUMULATE from 10% to 25%, HOLD from −10% to 10%, TRIM from −25% to −10%. At the $160.04 close the expected return is 20% and the gain to loss 5.1 to 1, so the stock is in the ACCUMULATE band, about $6 above the BUY line. Two things moved it from BUY: charging capital spending at the company’s own rate lowered every case, and the BUY line is higher on the common scale, at a 25% expected return against the 10% the October 13, 2026 update used, where the BUY held below $178.86.
It is ACCUMULATE and not BUY because the price is above the 25% line and the results raised a question about 2027 growth that the model answers generously, at 8.5%; at 4% growth the value on the best-guess weights is $185 and the expected return 16%. It is not HOLD because the results removed the two risks the October 6, 2026 update named, a second guidance cut and weak cash, and the cases are otherwise intact.
| Action | Level | Reason |
|---|---|---|
| Buy | Below about $154 | Expected return 25% or more on the best guess; gain to loss is 6.5 to 1 there |
| Accumulate | $154–175 | Expected return 10–25% |
| Hold | $175–214 | Expected return −10% to 10%, around the $192 target |
| Trim | Above about $214 | Expected return below −10%; the base case is $201.11 |
| Move the bands down | 2027 guidance for organic growth well below the model’s 8.5%, book-to-bill below 1, the margin below 23% without one-off items, or 2027 capital spending above 3.5% of sales | The worst case’s weight rises, or every case falls; 4% growth in 2027 takes about $10 off the base case |
| Move the bands up | Aftermarket growth back above mid-single digits with the segment margin above 25% without one-off items | The best case’s weight rises |
What the fourth-quarter results (early 2027, date not yet announced) must show:
| Item | Why it matters | The base case needs |
|---|---|---|
| Fourth-quarter free cash flow | The raised second-half range leaves $0.7–0.9 billion for the quarter | Within the range |
| 2027 guidance | The first full standalone year; management expects “higher sales and output growth in 2027”; the model has 8.5% | Organic growth near 8.5%; at 4% the base case is about $10 lower |
| Segment margin without one-off items | 23.9% in the third quarter; guided to the mid-23s in the fourth; the base case needs a recovery to 26% | The mid-23s in the fourth quarter, and a 2027 guide above it |
| Commercial aftermarket growth | +2% in the third quarter, limited by supply | A visible step up |
| Engines and Power Systems margin | Fell from 20.2% to 16.5% | Stabilizing |
| 2027 capital spending | $650 million in 2026, the 3.5% of sales the valuation now uses; a step-up in 2027 with the Tempe plant | No more than 3.5% of sales |
| Repurchases | $3.5 billion authorized, none made | Any start, and its size against the dividend |
| The environmental accrual | $815 million at September 26; the worst case carries 2.5 times the accrual | No large increase |
Update — October 13, 2026: how the money moves, the debt, where Honeywell Aerospace is, and the asymmetry — BUY, target $197
Written against the October 12, 2026 close of $157.27. Sources: the information statement (2025 carve-out and pro forma statements), the exchange-offer prospectus of July 13, 2026 (terms of the notes), the second-quarter 2026 10-Q, the revolving credit agreements and trademark licence filed at the spin, and, for individual sites, company pages, press releases and Foreign-Trade Zone records. The analyses below are left as published; this section adds four views they lacked, sets the scenario weights on the evidence, adds short interest and volatility, and corrects three statements about the debt. The rating is unchanged; the target moves from $195 to $197.
The one-line version
Airlines pay for most of the profit. Of $17.4 billion of revenue in 2025, 44% came from aftermarket parts, repairs and service plans, 26% from the U.S. Government and 15% from aircraft makers; services earn about twice the gross margin of products. As a standalone company the business turns each $100 of revenue into about $13.50 of free cash flow, about $2.3 billion a year, before a weak 2026. The debt is long and loose: $16.0 billion of fixed-rate notes with nothing due before 2028, no financial covenants and investment-grade ratings; free cash flow repays every maturity to 2033 with about $12 billion to spare. The asymmetry supports the BUY: in three cases on the published method (best $242, base $206, worst $110), weighted 15 / 70 / 15 on the evidence, the expected return at $157.27 is 25% with $6.50 of probability-weighted gain for each $1 of loss. The price implies no chance of the best case and an even split between the base and worst cases. Two costs sit outside the headline profit measure: $225 million a year to Honeywell for the name, and $828 million of environmental cleanup that management says could be two to three times larger. Physically, it is about 120 facilities, about three-quarters of them manufacturing and engineering sites, with plants in Mexico, India, China, Malaysia and Europe and four Department of Energy sites it runs but does not own.
How the money moves
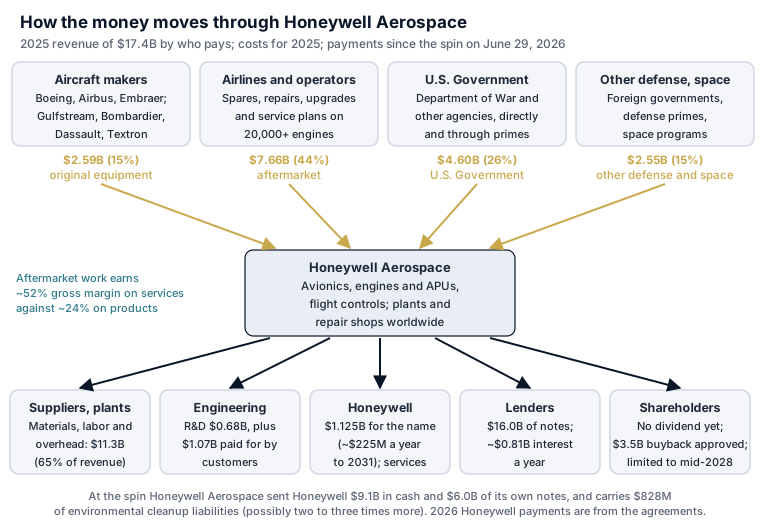
Four kinds of customer. Aircraft makers buy new equipment (15% of 2025 revenue); airlines, business-jet operators and repair shops buy spares, repairs, upgrades and service plans on more than 20,000 engines (44%); the U.S. Government, through the Department of War, the Department of Energy and the defense primes, paid $4.6 billion (26%); and foreign governments, primes and space programs the rest (15%). No customer is above 10% of revenue and no single aircraft program above 8%.
The aftermarket is where the margin is. The company does not report margins by end market, but its services earned a gross margin of about 52% in 2025 against about 24% on products. Equipment is sold to aircraft makers to win decades of spares and repairs on the installed base, and the incentives can be large: a Bombardier agreement cut 2024 revenue by $372 million, and the Flexjet settlement cut 2025 revenue by $312 million.
Where each $100 of revenue went, 2025, as if standalone (2025 carve-out results with the pro forma standalone costs; estimates marked in the text). The add-back line reverses the Flexjet charge, separation costs, environmental expense, depreciation and stock compensation, as the company’s adjusted measures do; environmental cash is then charged at the current-year accrual (~$149M). Taxes at the 2025 book rate. 2026 is weaker: first-half free cash flow was ~$5 per $100 after separation costs and a working-capital build, and the second half is guided to $1.0–1.5B. Source: the information statement (carve-out and pro forma statements); per-$100 figures are calculations.
Two costs are left out of the company’s adjusted profit. Honeywell Aerospace pays Honeywell $1.125 billion to use the Honeywell name: $18.75 million a month, about $225 million a year, until 2031. And it carries $828 million of environmental cleanup liabilities across about 327 sites, $149 million of it due within a year; management says reasonably possible losses could make the total two to three times higher, with payments running more than 20 years. Both are excluded from adjusted EBIT, and both are cash; the waterfall above charges them, the cleanup at the amount due within a year.
2026 is a weaker year than the waterfall. In the first half free cash flow was about $5 per $100 of revenue: separation costs of $522 million, a working-capital build and the $375 million Flexjet payment. The company guides to $1.0–1.5 billion in the second half. At the spin it paid Honeywell $9.1 billion in cash and handed over $6.0 billion of its own notes; it has paid no dividend yet and has not begun the $3.5 billion buyback approved on July 23, 2026.
The debt, tranche by tranche
| Tranche | Amount ($M) | Rate | Matures | Repaying early | Security | Notes |
|---|---|---|---|---|---|---|
| 3.900% notes | 1,250 | 3.900% fixed | March 16, 2028 | Make-whole (Treasuries + 0.10%) at any time | Senior unsecured | |
| 4.000% notes | 1,250 | 4.000% fixed | March 16, 2029 | Make-whole (T + 0.10%); par from February 16, 2029 | Senior unsecured | |
| Floating-rate notes | 500 | SOFR + 0.63%, reset quarterly | March 16, 2029 | Not callable | Senior unsecured | The only floating debt |
| 4.300% notes | 2,000 | 4.300% fixed | March 16, 2031 | Make-whole (T + 0.10%); par from February 16, 2031 | Senior unsecured | |
| 4.600% notes | 1,750 | 4.600% fixed | March 16, 2033 | Make-whole (T + 0.15%); par from January 16, 2033 | Senior unsecured | |
| 4.950% notes | 3,250 | 4.950% fixed | March 16, 2036 | Make-whole (T + 0.15%); par from December 16, 2035 | Senior unsecured | |
| 5.622% notes | 1,000 | 5.622% fixed | March 16, 2046 | Not callable before March 16, 2031; then make-whole (T + 0.15%) | Senior unsecured | Issued to Honeywell |
| 5.732% notes | 3,500 | 5.732% fixed | March 16, 2056 | Not callable before March 16, 2031; then make-whole (T + 0.15%) | Senior unsecured | Issued to Honeywell |
| 5.852% notes | 1,500 | 5.852% fixed | March 16, 2066 | Not callable before March 16, 2031; then make-whole (T + 0.20%) | Senior unsecured | Issued to Honeywell |
| Total drawn | 16,000 | 4.96% (fixed notes 4.97%; floating at SOFR + 0.63%) | ||||
| Five-year revolving credit | $3.0B | SOFR + 0.75–1.25% by rating (0.875% at A3/BBB+); ~0.08% on the unused amount | March 6, 2031 | Senior unsecured | Undrawn; backs a $4.0B commercial paper program (none outstanding found) | |
| 364-day revolving credit | $1.0B | SOFR + 0.75–1.25% by rating | March 5, 2027 (can be termed out to March 5, 2028) | Senior unsecured | Undrawn |
All nine tranches are senior unsecured notes issued on March 16, 2026; none amortizes. Honeywell’s guarantee fell away at the spin, and no subsidiary guarantees them. The 2046, 2056 and 2066 notes ($6.0 billion) were handed to Honeywell, which used them to retire its own term loan; the other $10.0 billion raised cash, of which $9.1 billion went to Honeywell. A further $6 million of other debt is not shown. Source: the exchange-offer prospectus of July 13, 2026 and the second-quarter 2026 10-Q, Note 9. As of June 27, 2026.
Principal due by year, including scheduled amortization. Nothing is due before March 2028; $6.0 billion is due after 2045.
$16.0 billion of senior unsecured notes, almost all fixed, the first due in March 2028. About $6.75 billion falls due from 2028 to 2033 and $9.25 billion from 2036 to 2066. The $4.0 billion of revolvers is undrawn and backs a commercial paper program with nothing outstanding found.
Honeywell Aerospace can repay every maturity to 2033 from its own cash (estimates, $ billions; free cash flow at the 2025 standalone rate of ~$2.34 billion a year, the second half of 2026 at the guidance midpoint):
| Base case | Downside: two years at half the free cash flow | |
|---|---|---|
| Free cash flow, second half of 2026 | $1.25B | $1.25B |
| Free cash flow, 2027–2033 | + ~$16.38B | + ~$14.04B |
| Cash at June 27, 2026 | + $1.06B | + $1.06B |
| Available to repay debt | = ~$18.69B | = ~$16.35B |
| Notes due 2028–2033 | − $6.75B | − $6.75B |
| Left after repaying them, before dividends and buybacks | = ~$11.94B | = ~$9.60B |
The debt leaves the business room. At 3.1 times adjusted EBITDA net leverage is high for an A3/BBB+ credit, and the ratings, which set the revolver’s price and the cost of the next notes, are the thing to watch. The amounts due are well within the cash the business produces.
Interest expense, 2026–2033
Almost all the interest is fixed, so the exposure is to refinancing. Only the $500 million floating note moves with SOFR: a one-point rise costs about $5 million a year. The notes due 2028–2033 will be refinanced at whatever rate applies then. Interest expense, $ millions, by the rate on the replacement notes (estimates; the 2026 figure runs from the notes’ issue on March 16, 2026):
| Refinancing rate | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 | 2032 | 2033 |
|---|---|---|---|---|---|---|---|---|
| 4.5% | ~$639 | ~$809 | ~$816 | ~$823 | ~$824 | ~$827 | ~$828 | ~$827 |
| 5.5% | ~$639 | ~$809 | ~$826 | ~$845 | ~$849 | ~$868 | ~$873 | ~$885 |
| 6.5% | ~$639 | ~$809 | ~$836 | ~$867 | ~$874 | ~$909 | ~$918 | ~$944 |
The first half of 2026 reported $229 million, which the model reproduces. Source: model in the site’s analysis files, from the notes’ terms.
Even at 6.5%, interest rises only about $135 million a year by 2033, about $0.34 a share after tax, because the long notes are fixed until 2046–2066.
| Covenant | Limit | Now | Room | Protects |
|---|---|---|---|---|
| Financial maintenance covenants | None: the revolvers state they do not restrict dividends or contain financial covenants | — | — | Revolvers and notes |
| Secured debt and sale-leasebacks | Liens on principal U.S. manufacturing property capped at 10% of consolidated net tangible assets; sale-leasebacks only within that cap or if the proceeds retire debt | No secured debt | Wide | Notes and revolvers |
| Change of control | No repurchase right for noteholders; revolver lenders may end their commitments if anyone acquires 50% of the votes | — | — | Notes; revolvers |
| Buybacks (tax matters agreement with Honeywell, not the debt) | For two years after June 29, 2026, only certain open-market purchases | $3.5 billion authorized July 23, 2026; none bought by June 27, 2026 | Restriction ends June 29, 2028 | Shares |
Ratings at June 27, 2026: Moody’s A3 (stable), S&P BBB+ (positive), Fitch A- (stable), from the 10-Q. The revolver margin and commitment fee step with the ratings.
Other obligations that behave like debt:
| Item | Amount | Note |
|---|---|---|
| Environmental cleanup | $828M accrued | Could be two to three times higher; payments beyond 20 years |
| Honeywell trademark licence | ~$1.05B still to pay | $18.75M a month to 2031 |
| Operating leases | $296M | About 10 years, ~4% |
| Pension | +$2,727M (a surplus) | An overfunded U.S. plan transferred from Honeywell, on the balance sheet from the third quarter of 2026 |
| Supply-chain financing in payables | $453M | Plus $344M of receivables sold in the first half of 2026 |
Source: second-quarter 2026 10-Q and information statement. No asbestos liability is assigned to Honeywell Aerospace in any of the separation filings.
The scenarios and the asymmetry
The August 26, 2026 valuation was a single case: blended growth, a 26% terminal margin and a 9.0% discount rate, worth $205. To test the BUY, the same model now runs three cases. It was rebuilt from the published assumptions and reproduces the published grid within about $1.50 a share, and every case uses the same 9.0% discount rate and 2.75% long-run growth, so the differences come from the business alone.
| Best | Base | Worst | |
|---|---|---|---|
| What has to happen | The casting shortage clears in 2027 and growth returns toward the 2023–25 record | The published case | A 2027 aerospace downturn of the 2020 kind, then slower growth and no margin recovery |
| Growth | 10% at peak; $47.5B of revenue by 2040 | 8.5% at peak; $43.5B by 2040 | Revenue −15% in 2027, +3% in 2028, then the guidance-anchored path |
| Margin | Recovers to 28% | Recovers to 26% | 19% in 2027, 21% in 2028, then stuck at 23.5% |
| Environmental cleanup | As accrued | As accrued | 2.5 times the accrual: $1.24B more |
| Value per share | $242.47 | $205.58 | $109.79 |
| vs $157.27 | +54% | +31% | −30% |
Three weightings, and what the price implies. Every profile shows the cases under three sets of weights. The standard set, 25 / 50 / 25, and the stress set, 10 / 40 / 50, are the same for every company; the best guess is set for each company from the evidence and can sit above or below the standard. The best guess drives the target, the rating and the two chips at the top of the page.
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $190.86 | +21% | 3.8 to 1 |
| Best guess: 15 / 70 / 15 | $196.75 | +25% | 6.5 to 1 |
| Stress: 10 / 40 / 50 | $161.37 | +3% | 1.2 to 1 |
| What the price implies: 0 / 50 / 50 | $157.27 | 0% | 1.0 to 1 |
The weights are a judgement. All values are estimates from the rebuilt model.
Why the best guess narrows both tails. The best case needs the margin to recover to 28%, above the 27.7% peak of 2021, which was reached before the business became more defense-weighted. Defense and Space went from 37% of sales in 2023 to 41% in 2025, partly through the CAES acquisition, and it earns less than the commercial aftermarket; nobody intends to shrink it. The growth half of the best case is plausible, since supply is improving and management expects 2027 to “look very different”, but the margin half works against the mix, so the best case gets 15%. The worst case is an aerospace downturn of the 2020 kind starting in 2027. Downturns that deep came three times in about 25 years (2001, 2009 and 2020); the backlog is up 9%, orders run ahead of sales with book-to-bill above 1.1, and 41% of sales go to defense, which does not fall with air traffic. It also gets 15%. The base case, the published case, takes 70%. Evidence that would raise the worst case: a cut to guidance or a fall in book-to-bill below 1 in the third-quarter results on October 28, 2026.
What the price implies. Holding the base case at its 70% weight cannot reproduce $157.27: even with no weight on the best case, 70% base and 30% worst is worth $176.84. With the best case at zero, the price is matched by the base and worst split that solves
base weight × $205.58 + (100% − base weight) × $109.79 = $157.27
which gives a base weight of ($157.27 − $109.79) ÷ ($205.58 − $109.79) = 50%, and so 50% on the worst case. The market is pricing no recovery beyond the base case and treating a 2020-style downturn as about as likely as the published case. The same reverse calculation on single assumptions gives the base growth path with the margin recovering only to about 19.8% instead of 26%, or the base case at a 10.3% discount rate instead of 9.0%.
The asymmetry on the best guess:
| Measure | At $157.27 | What it means |
|---|---|---|
| Expected return (header chip) | +25% | The probability-weighted value, $196.75, against the price |
| Gain to loss (header chip) | 6.5 to 1 | +$46.60 of probability-weighted gain against −$7.12 of loss |
| Expected base-case gain ÷ expected worst-case loss | 4.7 to 1 | +$33.82 against −$7.12: the likely outcome pays for the bad one without the best case |
| Best-case gain ÷ worst-case loss | 1.8 to 1 | +$85.20 against −$47.48 |
| Base-case gain ÷ worst-case loss | 1.0 to 1 | +$48.31 against −$47.48 |
How the measures are calculated. Gain = case value − price; loss = price − case value. Weights are the best guess: 15% best, 70% base, 15% worst.
| Measure | Formula | At $157.27 |
|---|---|---|
| Expected return | (15% × best + 70% × base + 15% × worst) ÷ price − 1 | ($36.37 + $143.91 + $16.47) ÷ $157.27 − 1 = +25% |
| Gain to loss | (15% × best gain + 70% × base gain) ÷ (15% × worst loss) | ($12.78 + $33.82) ÷ $7.12 = 6.5 |
| Expected base ÷ expected worst | (70% × base gain) ÷ (15% × worst loss) | $33.82 ÷ $7.12 = 4.7 |
| Best ÷ worst | best gain ÷ worst loss | $85.20 ÷ $47.48 = 1.8 |
| Base ÷ worst | base gain ÷ worst loss | $48.31 ÷ $47.48 = 1.0 |
| Price-implied base weight, best at zero | (price − worst) ÷ (base − worst) | ($157.27 − $109.79) ÷ $95.79 = 50% |
The header chips are green at +25% or more and 3 to 1 or better, blue at +10–25% and 2–3 to 1, orange at 0–10% and 1–2 to 1, and red below zero and below 1 to 1. The two turn red together, since expected return is below zero exactly when gain to loss is below 1 to 1. On the best guess, expected return is green below $157.40, blue up to $178.86 and orange up to $196.75; gain to loss is green below $176.68, blue up to $185.40 and orange up to $196.75. Both are red above $196.75. At $157.27 expected return is green by 13 cents.
| Change to the base case, one at a time | Value | Change |
|---|---|---|
| A 2027 downturn (revenue −15%, margin 19%), then the base path | $139.34 | −$66.24 |
| Guidance-anchored growth (7% at peak) | $182.79 | −$22.79 |
| Discount rate 9.5% | $185.01 | −$20.56 |
| Discount rate 9.25% | $194.89 | −$10.69 |
| Terminal margin 25% | $197.80 | −$7.78 |
| Environmental cleanup at 2.5 times the accrual | $201.66 | −$3.92 |
| Terminal margin 27% | $213.35 | +$7.78 |
| Record-anchored growth (10% at peak) | $225.54 | +$19.97 |
A downturn is the risk that matters most: a single bad year in 2027 takes $66 off the base case, because revenue resets lower and the margin recovery starts again from a lower base. The environmental liability, for all its size, moves the value by about $4 a share.
Short interest and volatility
The tables below show how much of the stock is sold short and how much the price moves. They are inputs to the weights above, and the tables update with the nightly data.
| Report | Settled | Short | % float | % outst. | Days to cover |
|---|---|---|---|---|---|
| First after the spin | Jun 30, 2026 | 10.57M | 3.3% | 3.3% | 5.9 |
| Three months earlier | Jul 15, 2026 | 8.21M | 2.6% | 2.6% | 2.0 |
| Lowest since the spin | Aug 31, 2026 | 4.74M | 1.5% | 1.5% | 1.3 |
| At the valuation | Oct 15, 2026 | 7.50M | 2.4% | 2.4% | 3.4 |
| Latest | Oct 30, 2026 | 8.73M | 2.8% | 2.8% | 2.3 |
The latest share of float is higher than 7 of the 8 earlier reports since the spin. Short interest in shares, with its share of the float and of shares outstanding. FINRA settlement dates; figures are published about eight business days later. Days to cover is short interest divided by average daily volume, as reported by FINRA. Float and shares outstanding on or before each date, from this site's daily share records and the company's filings.
Short interest is low, and it rose late in September 2026. It started at 3.3% of the float at the spin, when much of it was hedging around the distribution, fell to 1.5% at the end of August 2026, then rose to 2.7% at September 30, 2026, an addition of about 3.3 million shares in the second half of the month. Days to cover is 1.9. Three and a half months after the spin, part of the short interest may still be hedges against Honeywell or Solstice shares, so it is a weak signal for now. At under 3% of the float it is well below the levels at which short interest usually weighs on a stock, and it does not change the 15% weight on the worst case. The figure to watch is October 15, 2026, published in late October 2026, which will show whether the September build continued into the results.
| Volatility, annualized | Last 20 sessions | Last 60 sessions | Since the spin |
|---|---|---|---|
| To November 13, 2026 | 59% | 45% | 66% |
At the last 60 sessions' volatility, one standard deviation over a month is about ±14%, or $144.81 to $188.03 from the $165.01 close; about two months in three end inside that range if volatility holds. The median daily move since the spin is 2.2%.
| Results day | Released | Close before | Close after | Move | Times a median day |
|---|---|---|---|---|---|
| August 5, 2026 | After the close | $203.64 | $156.47 | -23.2% | 10.5× |
| October 28, 2026 | After the close | $177.03 | $160.04 | -9.6% | 4.4× |
Average move on a results day: 16.4% either way, against a median day's 2.2%. The move is measured from the close before the release to the close of the first session after it.
There has been one results day since the spin, and it fell 23%. The second-quarter release on August 5, 2026, after the close, cut the year’s growth guidance, and the shares fell from $203.64 to $156.47 the next day, about ten times a median day’s move. That single day accounts for much of the measured volatility: excluding it, the volatility since the spin is about 48% a year against 68% including it, so the one-month range above overstates a typical month. One observation is not a pattern, and the third-quarter results on October 28, 2026 are the first test of the reset guidance rather than a new cut. As an illustration, a 10% move either way would take the price to about $141.50, where both chips stay green, or to about $173, where expected return turns blue at $157.40 and gain to loss stays green below $176.68. A repeat of August’s fall would take the price to about $121, still above the worst case of $109.79.
Where Honeywell Aerospace is
About 120 facilities, by the Form 10: about 35 owned and 85 leased, in about 34 countries, with about 36,000 employees (not counting about 20,000 people at the Department of Energy sites it runs).
| Facilities (Form 10, 2026) | Americas | Asia Pacific | Europe, Middle East, Africa | Total |
|---|---|---|---|---|
| Manufacturing | 38 | 9 | 14 | 61 |
| Research and development | 17 | 7 | 8 | 32 |
| Corporate and offices | 14 | 4 | 9 | 27 |
| Total | 69 | 20 | 31 | 120 |
The filings name only a few sites. The maps below place the 47 that could be sourced individually; several are located only to the city, and eleven whose current status could not be confirmed, or that have closed, are left off.
Where it makes and services things
The filings name only a few sites; the rest are sourced individually and several are located only to the city. Sites reported closed, or whose current status could not be confirmed, are left off. Click a point for details. Map data © OpenStreetMap contributors. Source: the Form 10/A of June 8, 2026 (headquarters, the Phoenix Engines campus, the Department of Energy sites and the count of about 120 facilities) and, for the other sites, company pages, press releases, Foreign-Trade Zone records and job postings; coordinates from OpenStreetMap. As of October 13, 2026.
Phoenix is the center: the headquarters, the engines campus (F124 engine assembly from 2027) and the Deer Valley avionics campus, about 9,000 people in the area by press reports. The other large U.S. plants are Olathe, Kansas (avionics and flight controls, 560,000 square feet), Clearwater, Florida (navigation), Plymouth, Minnesota (inertial sensors), South Bend, Indiana (wheels and brakes) and Redmond, Washington. The largest repair shops outside the United States are Raunheim, Germany and Singapore.
Outside the United States: tariff and supply exposure
Sites outside the United States, coloured by country group. The filing lists manufacturing in Mexico, India, China, Canada, the UK, the Czech Republic, Germany and Malaysia among about 120 facilities. Click a point for details. Map data © OpenStreetMap contributors. Source: the Form 10/A of June 8, 2026 (headquarters, the Phoenix Engines campus, the Department of Energy sites and the count of about 120 facilities) and, for the other sites, company pages, press releases, Foreign-Trade Zone records and job postings; coordinates from OpenStreetMap. As of October 13, 2026.
Mexico and Europe carry most of the foreign manufacturing. Chihuahua is the largest machining site, with more than 1,300 machines, and Mexicali an electronics engineering center; Europe has plants in the Czech Republic, the UK and Italy (Civitanavi, acquired in 2024) and engineering in Brno and Kraków; India has three engineering centers with about 2,100 aerospace engineers. China appears only as a regional base in Shanghai on the sources found. The company names castings, forgings, complex machining and bearings as its supply bottlenecks and has second-sourced about 50 suppliers in 2026. It reports tariff costs but not their size.
| 2025 | Revenue | Share | Plant and equipment |
|---|---|---|---|
| United States | $12,739M | 73% | $1,625M |
| Switzerland | $2,652M | 15% | $0 |
| Rest of Europe, Middle East and Africa | $399M | 2% | $143M |
| Other international | $1,614M | 9% | $333M |
By country of the selling entity. U.S. revenue includes $4,665M of exports; including them, 54% of sales go abroad. Switzerland books 15% of revenue with no plant and equipment, which suggests a sales entity there (an inference; the filing does not say). Source: information statement, Note 20.
Government and defense
The Department of Energy sites are government-owned and run by Honeywell Federal Solutions under contract (about 20,000 people there are not counted among Honeywell Aerospace employees). Defense plants shown are those reported as making defense products; most sites serve both markets. Click a point for details. Map data © OpenStreetMap contributors. Source: the Form 10/A of June 8, 2026 (headquarters, the Phoenix Engines campus, the Department of Energy sites and the count of about 120 facilities) and, for the other sites, company pages, press releases, Foreign-Trade Zone records and job postings; coordinates from OpenStreetMap. As of October 13, 2026.
The defense business is spread across ordinary plants and a few special sites. Through Honeywell Federal Solutions it runs four Department of Energy sites it does not own, including the Kansas City National Security Campus and Sandia National Laboratories, for a mainly fee-based return. The 2024 purchase of CAES added defense electronics plants across the United States, shown as reported before the acquisition. Abroad, licensed partners service its military engines: ITP Aero in Spain for the F124, and WZL-1 in Poland, planned for 2028, for the Abrams tank engine.
The environmental liabilities cannot be mapped: the filings give the total and the number of sites, about 327, but name none.
Notes on earlier sections
- There is no term loan. The August 26, 2026 analysis said “scheduled amortization is 1% of original principal — $24M a year through 2030”. All $16.0 billion is notes, and none amortizes. The $6.0 billion term loan in the separation belonged to Honeywell, which retired it with the 2046, 2056 and 2066 notes Honeywell Aerospace issued to it. Data correction.
- The revolvers are $4.0 billion. The same section described “the $1.25B revolver… with only $12M of letters of credit against it”. The facilities are a $3.0 billion five-year revolver and a $1.0 billion 364-day revolver, both undrawn; no source for the letters of credit was found. Data correction.
- The 2029 maturity is $1,250 million at 4.00% fixed plus $500 million floating at SOFR plus 0.63%, $1,750 million in total, as the August 26, 2026 table’s total showed. Clarification.
None of the three changes net debt, interest or the valuation.
What it means for the rating
BUY, target $195 → $197. The target is the best-guess value, $196.75, which confirms the $195 of August 26 and October 6, 2026. Both chips read green at $157.27: an expected return of 25% and $6.50 of probability-weighted gain for each $1 of loss. Even on the stress weighting, with the worst case at 50%, the shares are worth slightly more than the price. The BUY holds below about $178.86, where expected return falls to 10%; above $196.75 the price assumes more than the evidence supports. A 2027 aerospace downturn remains the risk to watch, since a single bad year takes $66 off the base case. The debt is long, fixed and covenant-free, and the business can repay everything due before 2034 from its own cash. The two costs outside adjusted profit, the trademark licence and environmental cleanup, together take about $375 million a year of cash, roughly $2 per $100 of revenue; they are already in the free cash flow above, and the environmental estimate is the larger uncertainty. The third-quarter results on October 28, 2026 remain the test: second-half free cash flow against the $1.0–1.5 billion guidance, the start of the buyback, and any change in the environmental accrual.
Update — October 6, 2026: BUY, target $195 maintained
Written against the October 5 close of $155.74. Sources: Honeywell Aerospace’s remarks at the Jefferies Industrials Conference on September 9 (transcript) and a Morgan Stanley conference on September 15 (summary), the Q2 Form 10-Q, and the news linked below. The August 26 analysis is left as published; this section brings it up to date and corrects one sentence in it.
The one-line version
Nothing since August 26 changes the business case, and the early signs on supply are better. Management reaffirmed its 2030 targets, reported the first output gains at its constrained suppliers, and moved buybacks to the bottom of its capital priorities. Against that, one analyst has called a slowdown in the commercial aftermarket, and a securities class action has been filed.
What has changed is the discount rate. Treasury yields are about half a point higher than when the analysis was written, and HONA’s value is unusually sensitive to them: each quarter point is worth about $10 a share. At the 9.0% base the target is $195, 25% above the price. At 9.5% the value is $184.
The third-quarter results on October 28 decide it.
Rating: BUY, maintained · Target $195 · Grade: B+ (3.20)
What happened since August 26
| Date | Event | Read |
|---|---|---|
| Sep 1 | Department of Justice settlement. Honeywell Aerospace agreed to pay a little over $2 million to settle False Claims Act allegations that it failed to meet cybersecurity requirements on a Department of Defense contract (Shumaker). The stock fell 2.5% that day | Immaterial in money; a governance flag |
| Sep 8 | GE Aerospace agreed to buy Consolidated Precision Products, a major castings maker, for $11.75 billion, closing in the second half of 2027 (CNBC). HONA’s management called it positive for castings supply over time | Long-term positive for supply, no help before 2028; and a competitor will own a supplier |
| Sep 9 | Jefferies conference (below) | Consistent with the thesis |
| Sep 14 | Melius Research downgraded HONA to Hold, with GE Aerospace, HEICO, TransDigm and Woodward, expecting the commercial aftermarket to slow after “several years of robust” growth (MarketBeat) | A risk to the 2027 aftermarket recovery the case relies on |
| Sep 15 | Morgan Stanley conference (below) | Supply relief beginning; buybacks moved down the list |
| Sep 17 | Susquehanna initiated at Positive | — |
| Sep 21 | Removed from the S&P 100; remains in the S&P 500 | One-off index selling |
| Sep 29 | Securities class action filed for buyers between June 29 and September 1. It alleges the company did not disclose that a small number of suppliers had a “disproportionate impact” on sales, or that it was under investigation under the False Claims Act (Robbins Geller). Lead-plaintiff deadline November 23 | Common after a 23% one-day fall; no financial effect yet |
Honeywell Aerospace filed no 8-K in the period and disclosed no share repurchases. Analysts’ average target is about $207–219, between $174 and $256 (stockanalysis.com), above ours.
What management said
- On supply. The constraint is narrow: of more than 3,000 suppliers, about 70 are critical or constrained and about 10 severely so, in castings, forgings, bearings and complex machining. The company has put more than $1 billion into its supply base since 2023 and expects to spend about as much again over the next couple of years, faster. The first gains are showing: complex-machining output up roughly 20–30% year on year in the previous month or so, and about 35% of the year’s bearing demand delivered in a single quarter.
- On the year. The CEO called the August guidance revision “the most negative thing that has happened since the separation” and 2026 a reset year. Guidance was not changed again. Backlog is up more than 9% and book-to-bill above 1.1.
- On 2027 and beyond. “2027 is going to look very different than 2026”, with the supply unlock showing up “meaningfully” next year and the aftermarket recovering. The 2030 targets stand: 6–8% annual growth from 2026 to 2030.
- On capital allocation, in order: investment in the supply base, called “the highest-return use of capital”; a dividend in line with aerospace and defense peers; bolt-on acquisitions; and share repurchases fourth.
The last point answers the August analysis’s main worry. It questioned a $3.5 billion buyback authorized at 3.08× net leverage, and said aggressive use before the casting constraint cleared would be “the single clearest negative signal management could send”. Ranking buybacks fourth is the opposite signal. The new item is the dividend: the August analysis said there was none and that, given the leverage, that was correct. A peer-level dividend from a company at about 3× leverage is affordable only if second-half cash arrives, which makes October 28 the test of that too.
Interest rates
The cash flow barely moves. Of the $16.0 billion of debt, only $500 million floats (the SOFR plus 0.63% notes due 2029). The other $15.5 billion is fixed at a weighted 4.96%, with nothing due before 2028. A one-point rise in rates costs about $5 million a year.
The discount rate is another matter. The 9.0% was set on August 26, with the 10-year Treasury yield near 4.8%. It is now 5.31%. With equity about 77% of the capital, a full pass-through would put the cost of capital near 9.4–9.5%:
| Discount rate (terminal growth 2.75%) | Value per share | vs $155.74 |
|---|---|---|
| 9.0% (base) | $205 | +32% |
| 9.25% | $194 | +25% |
| 9.5% | $184 | +18% |
| 10.0% | $167 | +7% |
Base-case growth and a 26% terminal margin throughout. The changes are measured on a rebuild of the model that reproduces the August grid to within a few dollars.
Each quarter point is worth about $10 a share, about 5%, because roughly half the value sits beyond 2040. We keep 9.0% as the base, since a discount rate should reflect long-run conditions rather than a month’s move in yields. But at today’s yields the case for a BUY holds only at the 9.0–9.25% end of the range, and that should be said plainly.
The valuation at a glance
At $155.74: market capitalization $49.4 billion on 317.1 million shares, net debt $14.8 billion, enterprise value $64.2 billion.
| Measure | At $155.74 | At $163.35 (August 26) |
|---|---|---|
| Price / 2026 guided adjusted EPS ($7.75) | 20.1× | 21.1× |
| EV / 2026 guided adjusted EBIT ($4.40B) | 14.6× | 15.1× |
| EV / 2027 estimated adjusted EBIT ($4.69B) | 13.7× | 14.2× |
| Net debt / adjusted EBITDA | 3.08× | 3.08× |
Price target: $195 · range $163–224 · BUY, maintained
$195 is 25% above the October 5 close. The methods and weights are those of the August 26 analysis, unchanged. The BUY rests on three things: the discounted cash flow value at a 9.0% rate, a business-case evidence base that has improved slightly since August, and a third-quarter print that can confirm the supply recovery. A second guidance cut on October 28, or second-half free cash flow below $1.0 billion, would end it.
Correction to the August 26 analysis
One sentence contradicted the rating. The earnings-based valuation ends by calling its finding the one “that makes this a HOLD rather than either a BUY or an avoid”, while the target box beneath it, the scorecard and the summary all say BUY. It was a leftover from an earlier draft. A dated note now sits beside the sentence. The rating was and is BUY.
What the third-quarter results (October 28) must show
| Line | The test |
|---|---|
| Guidance | No second cut. Reaffirmation of the 4–5% organic growth |
| Second-half free cash flow | On track for the step-up the full-year guide requires; below $1.0 billion would end the BUY |
| Supply | Output at the ten constrained suppliers continuing to improve; any sign of castings easing |
| Segment margin | Stabilizing year on year, toward the recovery the 26% terminal margin assumes |
| Aftermarket | Growth holding against the industry slowdown Melius expects |
| Capital allocation | The size of any repurchases; the timing and size of the dividend |
Detailed Post-Spin Analysis — August 26, 2026
Written against the August 26 close of $163.35. Primary sources: the Q2 2026 Form 10-Q (filed 2026-08-05), the Q2 results release, and Honeywell International’s FY2025 and FY2022 Forms 10-K for the Aerospace segment’s pre-separation record.
This is the complete standing analysis of Honeywell Aerospace, consolidating the post-separation work to date into one document. It supersedes the interim Q2 earnings note. The initial August 5 assessment and all pre-separation analyses remain below, exactly as published — where this report reaches a different conclusion from one of them, it says so at the point of difference. There are four such places, and each is flagged inline.
The one-line version
The margin decline is not a casting shortage. It started two years before one — and it is a deliberate trade, not a deterioration.
Honeywell reported this business as a segment for six years before spinning it. That record shows segment margin peaking at 27.7% in 2021, holding 27.6% in 2023, then falling to 25.8% in 2024, 24.5% in 2025 and 23.6% in the first half of 2026 — four consecutive periods of decline, 405 basis points, most of it before precision castings were ever mentioned.
The cause is mix. Defense and Space went from 36.6% of sales in 2023 to 41.2% in 2025, growing 18–22% a year while the higher-margin commercial aftermarket grew 9–15%. Honeywell paid $1.9B for CAES ten months before separating the segment.
But read that as strategy rather than decay. HONA holds an estimated 65–80% of the commercial APU market — a ceiling, not an engine. Defense is a far larger market where it is a participant with share to win. Absolute segment profit grew $1.2B, or 40%, between 2021 and 2025. Trading margin rate for a bigger opportunity set is the right move from a dominant position in a mature niche. The risk is not that the earnings are worse; it is that the market pays ~20x for defense-weighted aerospace and 32–38x for aftermarket-weighted aerospace, so the multiple can fall further than the earnings rise.
On the balance sheet, the first-order read overstates the problem too. Net debt is $14.8B — 22% of enterprise value at a 4.96% coupon, 5.5x interest coverage, nothing due before 2028. That is not aggressive. The negative book equity is an accounting artifact of distributing $15.1B to a parent, not a statement about economic net worth. What the leverage costs is optionality, not solvency.
The valuation is the surprise. At a 26% terminal margin, a 9.0% discount rate and an explicit period running to 2040, the model returns $205 against a $163 share price. The bear case — margin flat at 23.5% forever, discounted at 9.5% — is $163, which is exactly where it trades. You are being asked to pay for none of the recovery, on a business whose backlog is up 9% and orders up 8%.
It is also the cheapest name in aerospace on forward earnings, at 17.9x against a peer group at 25–50x. Much of that discount is deserved. Not all of it.
Rating BUY, maintained. Target $195, up from $185. Proposed grade A (4.05) → B+ (3.20) — a weaker business than the pre-spin grade assumed, at a price that more than compensates.
What the business actually is
The largest pure-play aerospace supplier in the market: $17.5B of 2025 revenue, a $18.2B order backlog growing 9%, and an installed base measured in decades. Three reporting segments:
| Segment | Q2 2026 sales | Q2 segment profit | Margin | What it is | |
|---|---|---|---|---|---|
| Electronic Solutions | $1,774M | +8% | $459M | 25.9% | Avionics, sensors, navigation — a top-three global franchise |
| Engines & Power Systems | $1,406M | +1% | $174M | 12.4% | APUs, turboprops, business-jet engines. The APU franchise holds an estimated 65–80% share of the commercial airliner market with sole-source positions |
| Control Systems | $1,342M | +7% | $389M | 29.0% | Flight controls, environmental and mechanical systems |
| Corporate | — | $(27)M | |||
| Total | $4,522M | +5% | $995M | 22.0% |
But the segment view is the wrong cut for understanding this business. The disclosure that matters is the end-market split, which Honeywell reported for three years:
| ($M) | 2023 | 2024 | 2025 | 2025 share |
|---|---|---|---|---|
| Commercial Aviation Original Equipment | 2,397 | 2,223 | 2,513 | 14.4% |
| Commercial Aviation Aftermarket | 6,241 | 7,144 | 7,777 | 44.4% |
| Defense and Space | 4,986 | 6,091 | 7,220 | 41.2% |
| Total | 13,624 | 15,458 | 17,510 |
Honeywell Aerospace is 41% a defense business, and that is the single most under-discussed fact about it. The framing everywhere — including in the earlier analyses on this page — is “the largest pure-play aerospace supplier,” which invites comparison with GE Aerospace and its commercial engine aftermarket. The revenue mix invites comparison with RTX, and as the peer section shows, the market has already made that comparison.
Management Team
| Role | Name | Background |
|---|---|---|
| CEO | Jim Currier | Appointed November 2025. A career Honeywell aerospace executive — he has run this business from inside, and the segment record below is substantially his |
| CFO | Josh Jepsen | Appointed January 2026. Former CFO of Deere & Company — a large, cyclical, dealer-and-aftermarket industrial. An outside hire with genuine scale experience |
| Chairman | Craig Arnold | Appointed November 2025. Former CEO of Eaton Corporation, which he ran through a major portfolio reshaping. Non-executive |
This is a stronger team than the market is crediting, and the Chairman appointment in particular is not a courtesy: Arnold ran Eaton through exactly the kind of portfolio transition — divesting the lower-multiple businesses, buying into the higher-multiple ones — that HONA’s defense-versus-aftermarket mix question will eventually require.
The thing to hold against them is the one thing they have done so far, which is the capital-allocation decision covered below.
Deviation from the earlier analysis. The pre-spin sections below list the same three names with one-line descriptions. Nothing there is wrong. What is added here is that Currier’s tenure overlaps the margin decline — he has run aerospace inside Honeywell through the period in which segment margin fell from 27.6% to 24.5%. That is not an accusation; the mix shift was a Honeywell corporate decision and CAES was a Honeywell acquisition. But it does mean the “new management will fix it” argument has less room than it usually does at a spinoff, because the management is not new to the problem.
The financial record — six years by segment
This is the section the page did not previously have, and it changes the reading of the August guidance cut more than anything else in this report.
| ($M) | 2020 | 2021 | 2022 | 2023 | 2024 | 2025 | 1H 2026 |
|---|---|---|---|---|---|---|---|
| Net sales | 11,544 | 11,026 | 11,827 | 13,624 | 15,458 | 17,510 | 8,874 |
| YoY | −4% | +7% | +15% | +13% | +13% | +6% | |
| Segment profit | 2,904 | 3,051 | 3,228 | 3,760 | 3,988 | 4,284 | 2,090 |
| Segment margin | 25.2% | 27.7% | 27.3% | 27.6% | 25.8% | 24.5% | 23.6% |
2020–2022 from Honeywell’s FY2022 Form 10-K (“Aerospace”); 2023–2025 from the FY2025 Form 10-K (“Aerospace Technologies”); 1H 2026 from HONA’s own 10-Q. See the basis note below.
Demand is not the issue, and the order book says so. Backlog reached $18.2B in Q2 2026, up 9%, on trailing-twelve-month orders up 8%, with $15B of new wins year to date — including the largest new-aircraft equipment win in company history, IndiGo’s 810 A320neo-family aircraft. A supply-constrained business still growing its backlog faster than its sales is accumulating deferred revenue, not losing customers. That makes the problem a timing problem rather than a franchise problem, and it is why the right response to the guidance cut is a lower multiple rather than a lower thesis.
Revenue grew 59% from 2021 to 2025. Segment profit grew 40%. Margin peaked in 2021 at 27.7%, held 27.6% in 2023, and has fallen in every period since — 25.8%, 24.5%, 23.6%. That is 405 basis points over four consecutive periods, and the first two of those periods ended before the precision-casting shortage appeared in any company communication.
A note on comparability, because the two halves of that table come from different filings. The 2020–2025 figures are Honeywell’s segment profit, which excludes parent corporate cost. The 1H 2026 figure is HONA’s own total segment profit, which already nets a Corporate line of $(50)M for the half. Those are not automatically the same measure, and a series that quietly splices two bases is worse than no series at all.
The arithmetic says the gap is immaterial here. Honeywell’s 2025 segment profit was $4,284M. HONA guides FY2026 pro-forma standalone adjusted EBIT of $4.35–4.45B and describes it as flat to +3% year over year, which implies a 2025 standalone base of roughly $4.22–4.45B — bracketing Honeywell’s reported $4,284M. The standalone corporate load is therefore already substantially inside the segment figure, so the series can be read as continuous.
Why the margin is falling, and why it is not the castings
The August release attributes the problem to a precision-casting shortage that routes scarce parts to Boeing and Airbus production lines and starves the higher-margin aftermarket. That is real, and it is well evidenced in the Q2 segment detail. It is also, on the six-year record, not sufficient — because the decline began in 2024 and the constraint became material in 2026.
The mix explains more of it:
| Share of net sales | 2023 | 2024 | 2025 | Change |
|---|---|---|---|---|
| Commercial Aviation Aftermarket | 45.8% | 46.2% | 44.4% | −140bp |
| Defense and Space | 36.6% | 39.4% | 41.2% | +460bp |
| Commercial Aviation OE | 17.6% | 14.4% | 14.4% | −320bp |
Defense and Space grew 22% in 2024 and 19% in 2025. Commercial aftermarket grew 14% then 9%. Defense aerospace earns structurally less than commercial aftermarket — it is cost-plus or fixed-price work against a single sophisticated customer, without the installed-base pricing power that makes spare parts the best business in aviation.
And the shift was bought, not suffered. On August 30, 2024 Honeywell acquired CAES Systems for $1,935 million, a defense and space radio-frequency business, and folded it into this segment. CAES plus Civitanavi contributed $485M of inorganic sales in 2025. Honeywell deliberately made the business it was about to spin off more defense-weighted, ten months before separating it.
This is the deviation that matters most. The analyses below treat the margin problem as a supply constraint with a 2027 fix. The six-year record says a meaningful part of it is a mix shift with no fix, because nobody intends to shrink defense — it is the fastest-growing line, it carries the backlog, and the company just paid $1.9B to have more of it.
Both can be true, and the split matters enormously for the terminal value. If the decline is 100% castings, margin returns to 27%+. If half of it is mix, the ceiling is closer to 26%. This report takes the second view and the valuation section prices it — but see the second-order section immediately below, which argues the mix shift is a rational trade rather than a loss.
The second-order view — where the two objections above get smaller
Everything above is a fair reading of the numbers, and both of its conclusions — that the margin is falling and that the balance sheet is levered — are correct. Neither is as damaging as the first-order presentation makes it look, and the report would be misleading without saying so.
On the margin: percentage is the wrong scoreboard for a business enlarging its market.
| 2021 | 2025 | Change | |
|---|---|---|---|
| Net sales | $11,026M | $17,510M | +59% |
| Segment profit | $3,051M | $4,284M | +40%, or +$1,233M |
| Segment margin | 27.7% | 24.5% | −320bp |
Absolute profit grew by $1.2 billion. A company that adds that much earnings in four years has not been mismanaged, whatever happened to the ratio.
And the strategic logic behind the mix shift is better than the margin line suggests. HONA holds an estimated 65–80% of the commercial airliner APU market. That is a ceiling, not an engine. In a niche you already dominate, growth is limited to fleet expansion and price — you cannot take share you already have. Defense and Space is a far larger addressable market in which HONA is a participant rather than a leader, which means there is share to win. Trading a lower margin rate for a much larger opportunity set is what a management team with a dominant position in a mature niche ought to do, and paying $1.9B for CAES to accelerate it is a coherent decision rather than a value-destroying one.
The honest tension is not strategic, it is about the multiple. Even if defense growth is value-accretive at the earnings line — and the evidence says it is — the market pays roughly 20x for defense-weighted aerospace and 32–38x for aftermarket-weighted aerospace. A shift that adds earnings can still subtract share price if the multiple moves further than the earnings do. That is a real risk, but it is a very different criticism from “the business is deteriorating,” and this report should not conflate them.
On the debt: it is a constraint on optionality, not a question about solvency.
| Net debt | $14.8B |
| Market capitalization | $51.8B |
| Net debt as a share of enterprise value | 22.2% |
| Weighted average coupon | 4.96% |
| Cash interest / adjusted EBIT | 18% — coverage of about 5.5x |
| First maturity | 2028; $6.0B termed out past 2046 |
Twenty-two percent of enterprise value in debt, at a sub-5% fixed coupon, with nothing due for two years, is not an aggressive capital structure by any general standard. It looks aggressive only against the aerospace peer group, which is unusually unlevered — Heico, GE and TransDigm all run lighter — and against a 3.08x EBITDA multiple that is elevated precisely because EBITDA is currently depressed by the casting constraint.
And the negative book equity means less than this report first implied. It is a mechanical consequence of distributing $15.1B of cash to a parent while carrying assets at historical cost. It is an accounting artifact of how the spinoff was structured, not a statement about economic net worth, and a business generating $4.4B of adjusted EBIT is not impaired by it.
What the leverage actually costs is choice. At 3.08x on a currently depressed EBITDA base, HONA cannot make a large cash acquisition, cannot lean hard into the $3.5B repurchase authorization without raising leverage on a depressed EBITDA base, and has less room to absorb a second guidance cut than an unlevered peer. That is a real limitation and it is why the discount rate below is 9.0% rather than 8.5% — but it is a limit on flexibility, not a threat to the franchise.
The half-year detail complicates the quarterly story
| ($M) | 1H 2026 | 1H 2025 | |
|---|---|---|---|
| Electronic Solutions | 969 | 885 | +9.5% |
| Engines & Power Systems | 455 | 449 | +1.3% |
| Control Systems | 716 | 808 | −11.4% |
| Corporate | (50) | (36) | |
| Total segment profit | 2,090 | 2,106 | −0.8% |
On the half, total segment profit was flat on 6% more revenue — and the largest decline was Control Systems, not Engines & Power Systems. The Q2-only view in the August update identified Engines & Power (−32% in the quarter) as where the damage lands. Over the half, Engines & Power is roughly flat and Control Systems is down 11.4%, which implies a poor first quarter there (Q1 profit of $327M against $447M).
That is a genuine complication rather than a contradiction. A single-quarter read attributed the problem to one segment; two quarters say the profit pressure is spread across the portfolio, which is more consistent with a mix and cost story than with a single component shortage.
The quarter, the cut, and why the market took it so badly
| ($M) | Q2'26 | Q2'25 | |
|---|---|---|---|
| Backlog | 18,154 | 16,600 | +9% |
| Sales | 4,522 | 4,289 | +5% |
| Adjusted EBIT | 995 | 1,066 | −7% |
| Net income | 256 | 852 | −70% |
| Adjusted EPS | 1.87 | 2.75 | −32% |
Sales grew 5% organic and adjusted EBIT fell 7%, including roughly $100M of separation costs and inventory obsolescence. Ignore the net income line. As with any first standalone print the GAAP comparison is against carve-out accounting — $200M of interest in the quarter against zero a year earlier — so the −70% carries no information about the business.
The guidance was the problem:
| Previous | Current | |
|---|---|---|
| Organic growth | 7–9% | 4–5% |
| Pro forma standalone adj. EBIT | $4.65–4.75B | $4.35–4.45B |
| Year-over-year growth | 7–10% | Flat – 3% |
| Pro forma standalone adj. EPS | — | $7.60–7.90 |
| 2H free cash flow | $1.0–1.5B | $1.0–1.5B (held) |
Organic growth guidance was roughly halved. The new EPS range came in against a $8.86 consensus — a 12.5% shortfall on a number the company had never previously guided.
The mechanism is a precision-casting shortage, and the detail is what makes it serious. Scarce castings are being routed to Boeing and Airbus production lines to protect OE delivery schedules, which starves the aftermarket — the higher-margin half of the business. The company is qualifying 50+ new suppliers with 50 more planned, raising supplier tooling spend 20% half-on-half and doubling it from 2025 to 2027, with ~70% going to castings. Management is explicit that this is a 2027 story.
In the quarter it lands on Engines & Power Systems — EBIT down 32% on sales up 1%, per the segment table above. That is not a volume problem, it is a mix problem: OE units shipping while aftermarket spares are rationed. Over the full half the picture is broader, as the record section shows.
Why a 6% EBIT cut produced a 23% share move. The market did not simply re-earn the number — it re-rated the multiple. On consensus, the stock was at 23.0x before the print. After, on the new guide, it was at 20.2x. A cut read as timing compresses earnings; a cut read as structural compresses the multiple. The market chose the second reading, and management’s own “not until 2027” language supports it.
The $37B backlog figure, reconciled
Every prior section of this page cites a $37B order backlog, and the pre-spin case rested on it — “the $37B backlog and embedded installed base provide significant downside protection.”
The company reports backlog of $18.2B. Tracing the figure back resolves it completely:
| Honeywell International, total company, 31-Dec-2025 | $37.5B |
| Aerospace Technologies segment, 30-Sep-2025 | $17.5B |
| Honeywell Aerospace standalone, Q2 2026 | $18.2B (+9%) |
The $37B was the parent’s consolidated backlog across every segment — Aerospace, Building Automation, Energy and Sustainability Solutions and the rest. Honeywell reported it as a company record in its Q4 2025 release, and it entered this site’s March 2, 2026 report attributed to the aerospace business alone. The aerospace segment’s own backlog was always ~$17–18B, and today’s $18.2B is entirely consistent with that history.
So the number was real, and attached to the wrong entity. Nothing has deteriorated: backlog grew 9% year over year and orders 8%. What was wrong was the coverage ratio. The downside-protection argument implied roughly 2.1 years of revenue in backlog; the actual figure is about 1.0 year.
Per the corrections rule the prose above is left as published. But any conclusion in it that leans on backlog depth — including the “significant downside protection” claim — should be read at half the coverage it assumed.
Attaching a parent-level metric to a spinco is an easy error to make and a hard one to notice. Mobility Global’s ≈60% margin claim was the same class of mistake, and it is now a standing pre-spin check: confirm every headline metric is segment-level, not consolidated.
Where HONA sits in the aerospace value chain
In aerospace, two things confer pricing power: owning the installed base, and owning the bottleneck. HONA has the first and is currently on the wrong side of the second.
The installed base is real. The APU franchise holds an estimated 65–80% share of commercial airliners with sole-source positions on major platforms. An APU installed on an aircraft delivered today generates spares and overhaul revenue for twenty-five years, and the operator cannot switch it. This is the best asset in the company and it is why backlog grew 9% while margin fell.
The bottleneck is the problem, and it belongs to someone else. The constraint management named is precision castings; HONA does not name its suppliers, but the dominant merchant supplier of aerospace precision castings in the industry is Howmet Aerospace. The market’s treatment of the two companies is the clearest possible statement about where power sits:
| EV / LTM EBITDA | Forward P/E | |
|---|---|---|
| Howmet — makes the castings | 39.2x | 41.9x |
| Honeywell Aerospace — cannot get the castings | 18.6x | 17.9x |
The company holding the physical bottleneck trades at more than twice the multiple of the company constrained by it. HONA’s response — qualifying 50+ new suppliers with 50 more planned, raising supplier tooling spend 20% half-on-half and doubling it from 2025 to 2027, ~70% to castings — is the correct response and also an admission: it is spending capital to buy its way out of someone else’s pricing power, and management has put the payoff in 2027.
The second structural point is the one the mix analysis surfaced. Within aerospace, multiples track aftermarket intensity, because the aftermarket is the annuity:
- GE Aerospace, overwhelmingly commercial engines and aftermarket — 32.5x
- Heico, aftermarket parts — 37.9x
- RTX, roughly half defense — 19.9x
- HONA, 44% aftermarket and 41% defense — 18.6x
Deviation from the earlier analyses. The sections below describe HONA as “the largest pure-play aerospace supplier” and set the expectation of a commercial-aerospace multiple. The end-market disclosure does not support that comparison. At 41% defense, HONA is priced with RTX rather than with GE, and on the revenue mix that is correct — which changes what a fair multiple looks like, not whether the business is good.
HONA is priced with RTX, not with GE, and on the revenue mix that is correct. Recognizing that removes most of the apparent discount — and it means the path to a higher multiple runs through aftermarket growth outpacing defense, which is the opposite of what the last three years delivered.
In depth: competitive dynamics
HONA competes in three largely separate contests, and its position differs sharply across them.
| Where | Against | Position |
|---|---|---|
| APUs | Pratt & Whitney Canada (RTX), Safran | Dominant — an estimated 65–80% of commercial airliners, with sole-source positions won at aircraft design. The franchise of the company |
| Avionics and flight management | Collins (RTX), Thales, Garmin, GE Aerospace | Top three, in a genuine contest. Increasingly software-defined, which cuts both ways |
| Flight controls, environmental, mechanical | Collins, Safran, Liebherr, Moog | Strong but not dominant, and the most commoditizable of the three |
| Defense and space electronics | RTX, L3Harris, Northrop, BAE | A participant, not a leader — and this is now 41% of revenue |
The moat is narrower than “largest pure-play aerospace supplier” suggests. It is concentrated in APUs and, to a lesser degree, in the cross-selling advantage of being on the same airframe with multiple systems. Outside those, HONA competes on merit against companies of equal or greater scale, and in defense electronics it competes against primes several times its size.
What protects the economics is the installed base, not the technology. Once an APU is on a platform, the operator buys HONA spares and HONA overhauls for the life of the airframe, and switching is a certification exercise nobody undertakes. That is why backlog can grow 9% while margin falls: demand is locked, and the constraint is the company’s ability to convert it.
The competitive risk that matters is therefore not share loss. It is platform-level: sole-source positions are re-competed only when a new airframe is designed, which is rare and decisive. A next-generation single-aisle program awarding its APU elsewhere would not show in revenue for years and would show in the terminal value immediately.
The item the market may be under-weighting
Free cash flow in the first half was $86M against $791M a year earlier. Some of that is separation cost and interest. But the 10-Q discloses two working capital mechanisms that deserve attention:
| ($M) | 1H 2026 | 1H 2025 |
|---|---|---|
| Net cash from operating activities | 346 | 1,025 |
| Trade receivables sold (factoring) | 344 | — |
| Supply-chain financing within accounts payable | 453 | 521 (at Dec-25) |
The company sold $344M of receivables in the first half against zero in the prior year. Operating cash flow for the half was $346M. Those two numbers being almost identical is the point: on a like-for-like basis with 2025, first-half operating cash flow was close to nothing.
Meanwhile supply-chain financing inside accounts payable fell from $521M to $453M — a further use of cash as that program unwound.
None of this is improper and all of it is disclosed. But it sets up the number that matters most in the second half:
2H free cash flow guidance is $1.0–1.5B against $86M delivered in 1H. That is roughly a 15x step-up, and it was the one line management chose not to cut. Aerospace working capital is genuinely second-half weighted — inventory built for deliveries converts late — so a large step-up is normal. A step-up of this size, on a business whose output is supply-constrained and whose first-half cash came from factoring, is the single most checkable claim in the release.
What it means on three horizons.
Fundamentals — this does not change the business. Factoring receivables is a financing choice, not an operating outcome, and a company facing $794M of new annual interest and $100M of separation costs would reasonably reach for it. But it does mean the first half told us almost nothing about standalone cash conversion, which is precisely what a first standalone print is supposed to reveal.
Valuation — it argues for anchoring on EBIT rather than free cash flow for now, which is what the DCF below does. A free-cash-flow multiple built on 1H annualised would be meaningless, and one built on the 2H guide would be built on a promise. The earnings power is observable; the cash conversion is not yet.
Investment — it raises the value of waiting. There is no informational disadvantage to seeing the Q3 print before committing, because the two things that would change the thesis in either direction — casting supply and cash conversion — both become visible in November and neither is visible now.
What to watch, in order of information value:
- 2H free cash flow against the $1.0–1.5B guide. Below $1.0B and net leverage rises on a shrinking base; the balance sheet moves from a constraint to a problem.
- Whether factoring continues, and at what scale. A rising balance means reported cash flow is being borrowed from future periods; receivables sold once cannot be sold again.
- Engines & Power Systems margin. Recovery toward 15%+ is the earliest hard evidence that castings are reaching the aftermarket.
- Aftermarket growth versus OE growth. The moment aftermarket reaccelerates past OE, the rationing has ended — and that shows up in the revenue mix a quarter before it shows up in margin.
Capital allocation — and the decision that should be questioned
The separation was, in cash terms, a $15 billion extraction.
| ($M) | 1H 2026 | 1H 2025 |
|---|---|---|
| Net cash from operating activities | 346 | 1,025 |
| Capital expenditures | (260) | (234) |
| Free cash flow | 86 | 791 |
| Proceeds from issuance of long-term debt | 15,843 | — |
| Net transfers to Parent | (15,087) | (602) |
| Cash at period end | 1,057 | 419 |
HONA borrowed $15.8B and sent $15.1B of it to Honeywell. That is the same structure seen at FedEx Freight ($4.1B) and Qnity ($4.1B), at roughly four times the scale, and it is the origin of the $16.0B of debt and the negative $5.7B of book equity the company now carries.
Capital spending is at least being funded. Capex of $260M in the half against depreciation and amortization of $233M — capex is running above D&A, which is what a supply-constrained business qualifying 50+ new suppliers should be doing, and it is a favorable contrast with FedEx Freight running at 84% of D&A.
The $3.5 billion buyback
On July 23, 2026 the Board authorized the repurchase of up to $3.5 billion of common stock. No repurchases had been made as of the 10-Q. That is 6.8% of today’s market capitalization, at a company carrying 3.08x net leverage and negative book equity, authorized twenty-four months earlier and three and a half times larger than the analyses below predicted.
This is the largest deviation from the pre-spin case on this page. The sections below forecast “debt reduction priority in years 1–2 … buybacks once leverage normalizes below 2.5x” and sized an eventual authorization at "$1B+," reasoning by analogy to Solstice. The actual authorization arrived within four weeks of separation, at $3.5B, with leverage at 3.08x rather than below 2.5x.
Two readings, and the timing decides between them. The authorization is dated July 23 — thirteen days before the August 5 guidance cut that took the stock down 23%. Either the board authorized a buyback without knowing the guide was about to be halved, which is a governance question, or it knew and judged the shares cheap into the print, which is a conviction signal.
Neither reading is comfortable given the balance sheet. A company with negative book equity, $794M of annual cash interest, first-half free cash flow of $86M and a second-half guide requiring a fifteen-fold step-up has better uses for $3.5B than its own shares — and if the 2H cash guide is missed, buying stock while leverage rises on a shrinking EBITDA base is precisely the wrong sequence.
What to watch is whether they actually use it. An authorization is not a commitment, and the most likely outcome — repurchasing only enough to offset equity-compensation dilution, which the disclosure explicitly names as a purpose — would be sensible. Aggressive use before the casting constraint clears would be the single clearest negative signal management could send.
The debt, tranche by tranche
Nine tranches, $16.0B face, weighted coupon 4.96%, roughly $794M of annual cash interest — and a maturity ladder that is genuinely well built:
| Due | $M | Coupon |
|---|---|---|
| 2028 | 1,250 | 3.90% |
| 2029 | 1,750 | 4.00% / SOFR+0.63% |
| 2031 | 2,000 | 4.30% |
| 2033 | 1,750 | 4.60% |
| 2036 | 3,250 | 4.95% |
| 2046–2066 | 6,000 | 5.62–5.85% |
Nothing matures before 2028, and $6.0B is termed out past 2046. Net debt is $14.8B against roughly $4.8B of adjusted EBITDA — 3.08x — with book equity of negative $5.7B. That leverage was survivable on 7–9% growth. On 4–5% it is tighter, and it is why the guidance cut matters more here than the same cut would at an unlevered peer. Scheduled amortization is 1% of original principal — $24M a year through 2030 — the $1.25B revolver is undrawn with only $12M of letters of credit against it, and the notes trade above par. Cash interest consumes roughly 18% of adjusted EBIT. On the debt itself, as distinct from the amount of it, there is nothing to worry about.
There is no dividend
None declared, and none in the cash flow statement beyond payments to noncontrolling interests. Given the leverage, that is correct.
Valuation
At $163.35: market capitalization $51.8B on 317.1M shares, net debt $14.8B, enterprise value $66.6B.
| At $163.35 | |
|---|---|
| EV / FY2026 guided adjusted EBIT ($4.40B midpoint) | 15.1x |
| P/E on FY2026 guided adjusted EPS ($7.75 midpoint) | 21.1x |
| EV / LTM EBITDA | 18.6x |
| Net debt / adjusted EBITDA | 3.08x |
| Book equity | −$5.7B |
Discounted cash flow
Rebuilt from stated assumptions. Explicit period 2027–2040, perpetuity thereafter; capex 3.1% of sales; depreciation and amortization 2.2%; tax 25%; working capital 1.0% of incremental sales.
Why the explicit period runs to 2040. A shorter model does not work for this business. HONA sells onto airframes with 25-to-40-year service lives and earns its best margin on spares across that whole span, and it is currently in a supply-constrained trough that management expects to clear in 2027. Ending the explicit period in the early 2030s forces the perpetuity to begin while the company is still recovering, which capitalizes a depressed cash flow forever. Running to 2040 puts terminal value at about half of enterprise value rather than roughly two-thirds — a better-conditioned model, and one that reflects how long this company’s revenue is actually contracted for.
Two assumptions are load-bearing — growth and terminal margin — so both are shown rather than asserted.
On growth, the two defensible paths bracket the answer, and they disagree because they anchor on different evidence:
| Peak growth | 2040E revenue | 14-year CAGR | Anchored on | |
|---|---|---|---|---|
| A — guide-anchored | 7.0% | $38.7B | 5.5% | FY2026 organic guidance of 4–5% |
| Base — blended | 8.5% | $43.5B | 6.4% | Both, with the constraint clearing in 2027 |
| B — record-anchored | 10.0% | $47.5B | 7.1% | Reported growth of 15% / 13% / 13% in 2023–25 |
Path B has the better recent evidence and Path A the better current evidence. The three-year record includes a post-COVID aftermarket catch-up and the CAES acquisition, neither of which repeats; the FY2026 guide reflects a supply constraint that is not permanent. We carry the blended path.
Value per share on the blended growth path:
| Terminal segment margin | WACC 8.5% / g 3.0% | WACC 9.0% / g 2.75% | WACC 9.5% / g 2.5% |
|---|---|---|---|
| 28.0% — the prior assumption | $255 | $221 | $195 |
| 27.0% | $246 | $213 | $188 |
| 26.0% — our estimate | $237 | $205 | $181 |
| 25.0% | $227 | $197 | $174 |
| 23.5% — flat at 1H 2026 | $214 | $185 | $163 |
Each 100 basis points of terminal margin is worth about $8 a share. Terminal value is roughly 50% of enterprise value across the grid.
On the growth path, holding margin at 26% and the rate at 9.0%: Path A gives $183, the blend $205, Path B $224.
Why 26%, and why 9.0%
The margin. A recovery to 28% requires the casting constraint to clear and the defense mix shift to reverse. The first is management’s stated plan for 2027 and is credible. The second is not happening, and — per the second-order section above — probably should not. 26% credits the aftermarket recovery in full while respecting a mix shift that is permanent and, on the TAM argument, deliberate.
The discount rate. There is no single right rate for every business. The relevant inputs are capital structure, scale, maturity and how predictable the cash flows are, and for a company like this one the defensible range is roughly 8% to 10%.
| Argues lower | Argues higher |
|---|---|
| $51.8B market capitalization, deep liquidity | 3.08x net leverage, and no room for a second shock |
| A backlog covering roughly a year of revenue | Guidance halved within ten weeks of listing |
| Aftermarket annuity on a 25-year installed base | Three months of standalone operating history |
| Defense revenue is contractually stable | A supply constraint management cannot itself fix |
| Debt is only 22% of enterprise value at a 4.96% coupon |
9.0% is the honest middle — half a point above the prior 8.5% for the leverage and the absence of a track record, and well below the top of the band because the franchise quality genuinely argues against it.
Base case $205.
Earnings-based valuation
HONA’s 10-Q presents combined financial statements and therefore carries no earnings-per-share line at all, which makes a reported P/E impossible to compute for any pre-separation period. Normalizing the six-year segment record to the standalone capital structure — full $794M of annual cash interest, 25% tax, less noncontrolling interests — gives the like-for-like series:
| 2021 | 2022 | 2023 | 2024 | 2025 | 2026E | |
|---|---|---|---|---|---|---|
| Segment profit ($M) | 3,051 | 3,228 | 3,760 | 3,988 | 4,284 | 4,400 (guide) |
| Normalized EPS | $5.25 | $5.66 | $6.91 | $7.45 | $8.14 | $7.75 |
| P/E at $163.35 | 31.1x | 28.8x | 23.6x | 21.9x | 20.1x | 21.1x |
2026 is the first down year in the series. Normalized earnings compounded 11.6% a year from 2021 to 2025 and the guide takes them down 4.8%. That is the clean statement of what the August cut did: it did not break the business, it ended a four-year compounding run.
And it puts the multiple in context. At 21.1x forward earnings on a year that declines, against a peer group at 25–50x on years that grow, the market is applying roughly the discount the situation warrants — which is the finding that makes this a HOLD rather than either a BUY or an avoid.
Correction (October 6, 2026): the rating on this page is BUY, as the price target box below and the Investment Scorecard state. The sentence above is a leftover from an earlier draft. What it should say is that on earnings alone the discount looks roughly deserved, which is why the case for a BUY rests on the cash-flow valuation, not on the multiple. See the October 6 update at the top of this page.
Price target: $195 · range $163–224 · BUY
Method Value DCF — blended growth, 26% terminal margin, 9.0% WACC $205 DCF — guide-anchored growth (Path A), same margin and rate $183 DCF — record-anchored growth (Path B), same margin and rate $224 DCF — 25% margin at 9.5% $174 DCF — margin flat at 23.5%, 9.5% $163 (bear — today’s price) FY2027E adjusted EBIT $4.69B at 16x $190 FY2027E adjusted EBIT $4.69B at 17x $205 Sell-side, for reference — Evercore ISI post-cut $210
Analyst targets clustered at $255–260 before the August 5 print; Evercore ISI cut to $210 afterward. We are below the surviving sell-side number.
Base $195 is +19% to the August 26 close of $163.35.
Recommendation: BUY.
What this most resembles
Matching on structure rather than end-market — a very large business separated whole from a diversified industrial parent, loaded with debt on the way out, index membership secured at the spin — the universe offers a tight set:
| Company | Parent | Spun |
|---|---|---|
| Rockwell Collins | Rockwell Automation | July 2001 |
| Baker Hughes | General Electric | July 2017 |
| Wabtec | General Electric | February 2019 |
| Otis Worldwide | United Technologies / RTX | April 2020 |
| Carrier Global | United Technologies / RTX | April 2020 |
| GE HealthCare | General Electric | January 2023 |
| GE Vernova | General Electric | April 2024 |
As with Mobility Global, return comparisons are omitted deliberately. Otis and Carrier separated on April 3, 2020 — into the deepest week of the COVID drawdown — so their first-year figures measure a pandemic, not a separation. Rockwell Collins spun two months before September 2001. The macro window overwhelms the signal, and showing the numbers would imply a pattern that is not there.
What the group does show is a structural point specific to this one.
In the other two great industrial breakups of the era, aerospace was the piece the parent kept:
Parent Spun off Aerospace United Technologies → RTX Otis, Carrier (2020) retained General Electric GE HealthCare (2023), GE Vernova (2024) retained Honeywell Solstice, Honeywell Aerospace (2026) spun Honeywell separated its largest and most durable franchise and kept automation. That is the opposite of what RTX and GE concluded about where the durable value sat, and it is a question worth holding open rather than resolving now. The $15.8B of debt loaded onto the spinco on the way out is at least a data point on how the transaction was structured relative to whose balance sheet benefited.
And note what §355(e) does to the whole family. The two-year presumption applies to an acquisition of “the distributing corporation or any controlled corporation” — so it is not only Honeywell Aerospace that cannot be bought until July 2028. Honeywell Technologies and Solstice are equally locked. A conglomerate breakup freezes every piece of itself at once, which is a materially different situation from a single spinoff and is not something a name-by-name profile can show.
The one that rhymes on business model is Rockwell Collins — a pure-play avionics supplier spun from an industrial parent in 2001, with the same aftermarket-annuity economics and the same dependence on OEM build rates. It was acquired by United Technologies in 2018, seventeen years later — a reminder that the pure-play takeout thesis, when it works at all, can take a very long time. And under §355(e) it could not have happened for the first two years regardless.
Three further parallels
The section above matches HONA on structure. These three match it on theme, and each is specific to this company.
The levered separation, at four times the scale
Three large US industrial separations in fourteen months have used the same structure, and the pattern is unmistakable:
| Debt raised | Paid to parent | Leverage at spin | |
|---|---|---|---|
| Honeywell Aerospace | $15.8B | $15.1B | 3.08x |
| FedEx Freight | $4.3B | $4.1B | 2.62x (3.80x with leases) |
| Qnity | $4.1B | $4.1B | 1.80x |
The tell is not the leverage, it is what the leverage buys the parent. In all three the spinco’s debt capacity was monetized on the way out, and in all three the spinco entered independence with no retained cash and a cyclical position it did not choose. HONA is the most levered of the three and the only one with negative book equity.
The margin measured from the wrong base
A spinco’s own filings routinely begin after the best years have passed, and three recent separations show it. Qnity’s record started at a destocking trough; FedEx Freight’s mid-cycle was calibrated on a post-Yellow anomaly; Solstice’s margin decline turned out to be three years old rather than two quarters. HONA is the mirror image of the first three: its own filings begin after a peak, not at a trough, so the direction of the error is reversed but the cause is the same — two periods of disclosure is not a record.
The constrained supplier in a re-rated chain
The closest analog is not in aerospace at all. It is Qnity, also a 2025–26 separation, and the parallel is exact enough to be useful: a good business, well positioned with its customers, that does not control the physical input its own output depends on. Qnity gives back 1–2% of price a year to TSMC and Samsung; HONA is spending 20% more on supplier tooling to buy its way around Howmet.
In both cases the layer holding the bottleneck earns the multiple — Howmet at 39.2x against HONA at 18.6x is the same relationship as Lam at 45.4x against Qnity at 20.3x. Being essential is not the same as being scarce.
Price and volume: an inverted flush
The Initial Assessment of August 5, further below, was published hours before the first standalone print and called the day-24 trough “the textbook signal.” It was wrong, and by a wide margin. The stock fell 23.2% the next session and set its actual low 20% below the level that assessment had identified as the bottom.
Correcting the August 5 call
That note said HONA “ran that script almost to the day” — index selling exhausting at a day-24 trough of $195.87. What followed:
Called bottom (day 24, July 23) $195.87 Actual closing low (day 28, Aug 6) $156.47 Error −20.1% The forced-selling model identified when the mechanical seller finished. It said nothing about what the business was worth, and one earnings print relocated the floor by a fifth. This is the second name in a row where the two troughs were different events — see Flush and earnings below.
Why Mobility Global appears throughout this update
The two businesses are unrelated — aerospace components and automotive data share nothing but a listing venue. They are compared here because they form an unusually clean natural experiment, and are the only pair we have:
Honeywell Aerospace Mobility Global Spun 2026-06-29 2026-07-01 First standalone print Aug 5 Aug 6 Day-1 volume vs baseline 2.6x 22.8x Two days apart at separation and one day apart at reporting, so they faced the same market window — the same rate environment, the same appetite for newly distributed securities, the same tape. Anything they did differently is therefore about the companies, not the moment.
And they are maximally different on the one dimension that matters here: HONA had almost no forced-selling flush, MBGL had one of the most violent observed. That is what makes their shared outcome informative rather than coincidental — see Flush and earnings at the foot of this section.
They are also the only two first standalone earnings prints observed in real time so far. As more accumulate, this comparison should be replaced by a cohort.
Honeywell Aerospace is the mirror image of the textbook forced-selling pattern, and the contrast with Mobility Global is the most instructive thing here.
| HONA | MBGL | |
|---|---|---|
| Day-1 volume vs baseline | 2.6x | 22.8x |
| Direction in week 1 | +12% to $247.15 | −9% to $19.26 |
| Earnings-day reaction | −23.2% on 6.3x volume | −5.0% on 2.6x volume |
| Turnover since spin | 52% of shares | 119% of shares |
| Realized volatility | 89% | 55% |
HONA barely had a flush. Day-1 volume was 2.6x baseline against a 24-name median near 10x, and the stock rose 12% in its first four sessions to $247.15 before drifting. Index membership was secured before the spin, which removed the mechanical seller almost entirely.
Then the earnings print did in one session what the flush never did: −23.2% on 6.3x volume, setting the closing low of $156.47 on the day of the reaction and an intraday low of $150.03.
The weekly decay tells the same story as Mobility Global’s, with one difference at the end:
| Sessions | Window | vs baseline |
|---|---|---|
| 1–5 | spin | 2.00x |
| 11–15 | 0.89x | |
| 16–20 | 0.83x | |
| 21–25 | pre-earnings | 0.68x |
| 26–30 | earnings week | 1.48x |
| 31–35 | 1.10x | |
| 36–38 | most recent | 1.45x |
Both names bottomed at exactly 0.68x baseline the week before their print — the quiet before an event-driven cohort arrives. But where Mobility Global faded back to 0.61x afterwards, HONA is still running at 1.45x eleven sessions later. Its register has not finished repricing.
Turnover is the other half of the contrast: 52% of shares in 38 sessions against Mobility Global’s 119%. HONA’s shareholder base has churned far less — which is consistent with the mild flush, and also means fewer of the original holders have yet made a decision about the new guidance.
Trading commentary. The pattern here is a stock that never de-risked mechanically and de-risked violently on fundamentals instead. The $156–160 zone has been tested three times since August 6 and held each time; that is the level where risk/reward improves, and where a scaled entry makes sense. Below $150 — the intraday low — the market would be pricing a second cut, at which point the leverage becomes the story rather than the multiple.
The next catalyst is Q3 in early November, and it is the more important print of the two: the first read on whether supplier qualifications are converting into output, and the first quarter where the 2H free cash flow guide can be checked against actuals.
Flush and earnings — an inverse relationship?
Two names, opposite entry profiles, the same conclusion:
| Flush | Where the low was actually set | |
|---|---|---|
| Mobility Global | violent — 22.8x day-1 volume | earnings, 5 weeks later |
| Honeywell Aerospace | mild — 2.6x day-1 volume | earnings, 4 days later |
MBGL’s flush was among the most violent in the sample and HONA’s among the mildest, and in both cases the fundamental trough came from the first standalone print rather than the forced seller. That is two observations in which the forced-selling signal — the day-1 low, or the day-24 trough — pointed at the wrong event.
It also suggests the flush and the earnings reaction may be inversely related: a name that never had mechanical selling has a shareholder base that never turned over, which leaves more holders to be surprised. One pair is not a pattern. It is a single observation, and it is recorded here as one rather than dressed up as a rule.
In depth: valuation against peers
Prices at the August 26, 2026 close. Enterprise value and LTM EBITDA on a consistent basis across names.
| Company | Character | Price | EV | LTM EBITDA | EV/EBITDA | Fwd P/E |
|---|---|---|---|---|---|---|
| Heico | Aftermarket parts | $345.58 | $52.0B | $1.37B | 37.9x | 49.8x |
| Howmet | Castings — the bottleneck | $268.86 | $109.4B | $2.79B | 39.2x | 41.9x |
| GE Aerospace | Commercial engines + aftermarket | $353.68 | $373.2B | $11.48B | 32.5x | 39.0x |
| Curtiss-Wright | Defense + industrial | $619.24 | $23.2B | $0.84B | 27.5x | 36.1x |
| Woodward | Fuel and motion control | $345.86 | $21.0B | $0.80B | 26.1x | 32.2x |
| Moog | Flight controls | $380.54 | $13.0B | $0.63B | 20.6x | 32.2x |
| RTX | ~Half defense | $211.18 | $315.7B | $15.90B | 19.9x | 26.9x |
| TransDigm | Proprietary aftermarket | $1,199.14 | $96.7B | $5.10B | 19.0x | 24.8x |
| Honeywell Aerospace | 44% aftermarket, 41% defense | $163.35 | $66.6B | $3.54B | 18.6x | 17.9x |
Read the HONA row with care. Its LTM EBITDA is depressed by carve-out accounting and $411M of first-half separation costs, so 18.6x overstates the multiple. On FY2026 guided adjusted EBITDA of roughly $4.87B the enterprise value is 13.7x — but peers are shown on trailing EBITDA, and comparing HONA forward against peers trailing would overstate the discount in the other direction. The forward P/E column is the cleaner comparison, since every name in it is on the same basis.
HONA is the cheapest name in aerospace on both measures, and the gap is not subtle — 17.9x forward earnings against a peer range of 24.8x to 49.8x.
Most of that discount is explained rather than free:
- The mix. Multiples in this sector track aftermarket intensity. The three most aftermarket-levered names — Heico, GE, Howmet — carry 32–39x. The two most defense-weighted — RTX and HONA — carry 19–20x. HONA is priced where its revenue mix says it should be.
- The leverage. 3.08x net debt to EBITDA and negative book equity, against a peer group that is mostly under 2x.
- The visibility. Three months of standalone reporting, one of which contained a halved guide.
What is not explained is the forward P/E gap specifically. At 17.9x against RTX’s 26.9x — a company with a similar defense weighting, similar scale and a better balance sheet — HONA trades at a third less on earnings for reasons the mix argument does not cover. That is the strongest quantitative point the bull case has, and it is why the target sits above the DCF rather than on it.
In depth: is Honeywell Aerospace an acquisition target?
No, and the reason is arithmetic rather than strategy. At a $66.6B enterprise value HONA is too large for any plausible buyer, and the overlap with the two who could contemplate it — GE Aerospace and RTX — is exactly where regulators would object: avionics, engines and controls on the same airframes.
Section 355(e) blocks a change of control until June 29, 2028 in any case, and the same rule binds HONA as an acquirer: a large stock-funded acquisition inside the two-year window could itself cost the separation its tax-free status. Cash deals are unaffected, but with 3.08x leverage and negative book equity there is no capacity for one.
The realistic corporate actions are the reverse of a takeover:
| Action | Assessment |
|---|---|
| Divesting the defense electronics business | The genuine possibility. CAES was bought for $1.9B in 2024; defense electronics assets trade well and a sale would raise the aftermarket share of revenue, which is what the multiple keys off. This is the single highest-value corporate action available |
| Selling a non-core product line to fund deleveraging | Plausible in 2027–28 once the casting constraint clears |
| Being acquired | Blocked to June 2028, and implausible after |
The un-obvious point. The mix analysis says HONA’s multiple is held down by its defense weighting. The company has an asset it could sell to fix that, and it bought that asset less than two years ago. A management team that understood why its stock trades at 18.6x while GE trades at 32.5x would at least be modeling it — and Craig Arnold ran exactly this playbook at Eaton.
Tail scenarios
Low probability, high magnitude, short of black swan. The DCF grid above converts most of them: each 100 basis points of terminal margin is worth about $8 a share.
Upside tails
1. The castings clear early and the aftermarket snaps back. Management has put the fix in 2027 and is qualifying 50+ new suppliers with 50 more planned. If that lands in 2H 2027 rather than 2028, and margin returns to 27%, the DCF at 9.0% gives $213 and at 8.5% $246 — 30% to 50% above spot. This is the company’s own case and it is not implausible; it simply is not the base case, because it requires the mix drag to be smaller than the last three years suggest.
2. Defense gets sold, and the multiple re-rates rather than the earnings. Divesting CAES and the adjacent defense electronics would lift the aftermarket share of revenue from 44% toward 55%. On this peer group that is worth more than the earnings it removes: HONA at RTX’s 19.9x is $190, at Woodward’s 26.1x it is far higher. The re-rating is the prize, not the sale proceeds — and it is the tail with the largest magnitude on this page.
3. The buyback is used well. $3.5B is 6.8% of the market capitalization. Used at $160–170 during a casting-driven trough, it is straightforwardly accretive and signals a board that knows what the business is worth. The same authorization is a downside tail if used at $200.
4. Aerospace aftermarket demand is structurally under-supplied. Global fleet utilization is high, new deliveries remain behind schedule industry-wide, and older aircraft are being kept in service longer than planned. Every year an airframe stays in service is another year of HONA spares revenue on a twenty-five-year installed base. Delivery delays at Boeing and Airbus hurt the 14% of revenue that is OE and help the 44% that is aftermarket.
Downside tails
1. A second guidance cut. The first took the stock down 23% in a session. The company has three months of standalone history and has already missed once; the 2H free cash flow guide of $1.0–1.5B against $86M delivered in 1H is a fifteen-fold step-up on a business whose first-half cash came substantially from $344M of receivables sold against zero a year earlier. A miss there takes leverage above 3.3x on a shrinking base, and the DCF at 23.5% flat margin discounted at 9.5% gives $163 — today’s price. A second cut takes the bear case below it.
2. The mix shift continues. Defense grew 22% then 19% while aftermarket grew 14% then 9%. If that persists, defense passes aftermarket to become the largest line in the business within two years — and HONA becomes a defense company with an aerospace aftermarket attached, which is a materially lower multiple. This is the tail that is already happening; the question is only whether it continues.
3. The buyback is used badly. $3.5B at 3.08x leverage with negative book equity and $794M of annual interest. Repurchasing aggressively before the casting constraint clears would consume the deleveraging capacity the balance sheet needs, and would do it at prices set by a market that has not yet seen whether the 2H cash guide holds.
4. An APU platform loss. The 65–80% share is the franchise, and it is held through sole-source positions won at aircraft design. Those positions are re-competed only when a new airframe is designed — rarely, but decisively, and a loss would not appear in revenue for years while appearing in the terminal value immediately. There is no disclosure that lets an investor monitor this, which makes it the largest un-observable risk here.
5. Defense budget normalization. 41% of revenue now sits in Defense and Space, grown 22% and 19% in consecutive years against a backdrop of elevated global defense spending. That growth rate is not a baseline, and a reversion to mid-single digits removes the line that has been carrying the top line while commercial aftermarket was rationed.
What would change this view
| Direction | Trigger |
|---|---|
| Better | Aftermarket growth reaccelerating past defense growth — visible in the revenue mix a quarter before it reaches margin · Engines & Power Systems margin recovering toward 15% · segment margin turning up on a year-over-year basis for two consecutive quarters · a defense divestiture |
| Worse | A second guidance cut · 2H free cash flow below $1.0B · rising receivables factoring, which borrows reported cash from future periods · defense growing past 45% of sales · aggressive buyback execution above $190 |
| Dated, next 6 months | Q3 2026 print (November) — settles both the cash conversion question and whether the casting constraint is easing · the exchange offer closing in Q3 2026 · first disclosure of actual repurchases under the July authorization |
| Thesis-breaking | Loss of a sole-source APU position on a major platform · a covenant or ratings event that forces equity issuance at these prices |
Investment Scorecard
Scored on the five weighted dimensions set out in our methodology.
| Dimension | Weight | Score | Rationale |
|---|---|---|---|
| Financial Profile | 25% | 3.0 | $17.5B of revenue, a 24.5% segment margin still top-quartile in industrials, backlog up 9%, capex running above depreciation, and absolute segment profit up $1.2B, or 40%, since 2021. The balance sheet is sound rather than stretched: net debt is 22% of enterprise value at a 4.96% coupon, interest coverage is about 5.5x, and nothing matures before 2028. Held below 3.5 by the trend rather than the structure — segment margin has fallen in four consecutive periods, and first-half free cash flow of $86M, flattered by $344M of receivables sold, leaves little cushion before the November print |
| Competitive Position | 25% | 4.0 | The APU franchise at an estimated 65–80% share with sole-source positions is a genuine moat on a 25-year installed base, avionics is top-three, and backlog growing faster than sales says demand is intact. Held below 4.5 because the constraint on this business is held by a supplier it does not control, and because the revenue mix is shifting toward the structurally lower-margin end |
| Strategic Rationale | 20% | 3.5 | Separating the largest pure-play aerospace franchise from a diversified parent is sound, and the business is coherent standalone. Discounted for the $15.1B of debt-funded cash paid to Honeywell and for the parent reshaping the segment toward defense — via the $1.9B CAES acquisition — ten months before spinning it |
| Management & Governance | 20% | 3.0 | A credible team: a career aerospace CEO, a Deere CFO, and a chairman who ran Eaton through a portfolio transition. Held down by two things — the CEO ran this business through the margin decline, so this is not new management inheriting an old problem, and a $3.5B buyback authorized thirteen days before halving guidance, at 3.08x leverage with negative book equity |
| Acquisition Potential | 10% | 1.5 | Effectively zero. Too large at $66.6B, blocked by §355(e) until June 2028, and overlapping with the only two plausible buyers exactly where antitrust would object |
| Weighted Score | 3.20 | ||
| Investment Grade | B+ · Solid Opportunity |
Proposed grade change: A (4.05) → B+ (3.20)
A two-notch downgrade. It is driven by evidence that was always available in Honeywell’s segment filings and had not previously been examined, rather than by anything that happened after the August guidance cut.
- Financial Profile 3.5 → 3.0. The six-year record shows margin declining in four consecutive periods, and first-half free cash flow of $86M — flattered by $344M of receivables sold — leaves little cushion before November. The markdown is for the trend, not for the balance sheet, which at 22% of enterprise value and 5.5x interest coverage is unremarkable.
- Competitive Position 4.5 → 4.0. The APU moat is real and unchanged. What changed is the recognition that the binding constraint belongs to Howmet, and that the revenue mix is moving toward the part of aerospace that earns less.
- Management & Governance 4.0 → 3.0, on the buyback timing and on the CEO’s tenure spanning the decline.
- Acquisition Potential 2.0 → 1.5, on the §355(e) window and scale.
- Strategic Rationale is deliberately unchanged at 3.5. The $15.1B extraction is already charged to Financial Profile, and charging it twice would double-count one objection.
The band moves, and it should. Every other revision in this pass moved the score without moving the band; this one moves two. The reason is that the prior grade was set before separation, on a Form 10 and a $37B backlog figure that belonged to the parent — it was never tested against six years of segment data or a standalone balance sheet.
The standing A (4.05) remains our published grade until the next report carries the change.
What would earn the grade back: two quarters of margin stabilization, 2H free cash flow at the top of the guided range, and evidence that the aftermarket is reaccelerating past defense.
The grade and the rating point opposite ways here, and that is deliberate. A two-notch grade downgrade sits alongside a BUY because they measure different things. The grade says this is a weaker business than the pre-spin A assumed — more defense-weighted, more levered, with a margin trend that was never tested against six years of data. The rating says the price already reflects more than that. A B+ business at a C+ price is a buy, and the bear case being today’s quote is what makes it one.
Initial Assessment — August 5, 2026
Written August 5, 2026, against prices as of the July 31, 2026 close. This is a point-in-time assessment and is not updated as the price moves — see Current Stats above for the latest figures.
What happened
Honeywell Aerospace began trading June 29, 2026 as the second and largest leg of Honeywell’s three-way breakup — Solstice Advanced Materials first, then HONA, leaving Honeywell Technologies as the automation RemainCo. It was 100% distributed with no retained stake and went straight into the S&P 500, roughly 317M shares at a ≈$65B market capitalization.
Then it did precisely what this site’s framework says a clean spinoff does. It slid for a month, bottomed at $195.87 on July 23 — day 24 — and has recovered +5.5% since, closing July at $206.74, or -6.1% against the $220.19 Day-1 close.
A day-24 trough is the textbook signal. Index funds and mandate-constrained holders sell a newly distributed security they did not choose to own; the selling exhausts; dedicated buyers arrive. HONA ran that script almost to the day, and it did so with index membership already secured, which usually shortens the window rather than lengthening it.
The comparison that flatters the wrong side
Parent Honeywell Technologies is +6.7% over the same window, against HONA’s -6.1% — a 13-point gap in the RemainCo’s favor. That reads as evidence against the spinoff thesis, and it is worth being precise about why it mostly is not.
The parent comparison here is unusually noisy. Honeywell executed a 1-for-2 reverse split on the same day as the separation, and the pre-breakup HON series is not comparable to the post-breakup one at all — this site marks it n/m and tracks HON only from its June 29 post-spin close. What the gap actually measures is one month of relative performance between a business that had a forced-selling overhang and one that did not. Ask again in a year.
What you are buying
The largest pure-play aerospace supplier in the market: ≈$17.4B of revenue, a $37B order backlog, ~25% EBIT margins, and an APU franchise holding 65-80% share — the kind of installed-base position that produces decades of high-margin aftermarket revenue. CEO Jim Currier came up through the division. Analyst price targets cluster at $255-260, well above the current quote.
The precedent within the same breakup is encouraging: Solstice was +68% post-spin at the time of the June report, and the parent has now demonstrated it can execute these separations cleanly.
The one thing to underwrite
The balance sheet. HONA carries ≈$15.8B of long-term debt and negative book equity as a result of the separation financing — the RemainCo’s capital structure was optimised at the SpinCo’s expense, which is a recurring pattern worth naming every time it appears.
Negative book equity is not by itself alarming for a business with this backlog and this margin profile; the aftermarket annuity supports leverage that would be reckless elsewhere. But it removes the cushion. This is a name where the interest burden and the backlog conversion rate matter more than the multiple, and where a downturn in aerospace demand would be felt in the financing costs before it showed up in the operating results.
What to watch
First standalone Q2 results, August 5, 2026 — the first look at margins, cash generation and interest expense as an independent company, and the first hard test of whether the $37B backlog converts at the rate the pre-spin analysis assumed.
Beyond that: whether the post-day-24 recovery holds, and whether the analyst target cluster at $255-260 survives contact with a standalone P&L. Grade A maintained; the rating stays STRONG BUY into the post-trough window.
All analysis below is pre-spinoff
Written before Honeywell Aerospace began trading June 29, 2026. Kept as published — figures, valuations and grades reflect what was known at the time, not today.
Executive Summary
Management Team
| Role | Name | Background |
|---|---|---|
| CEO | Jim Currier | Appointed November 2025; career Honeywell aerospace executive |
| Chairman | Craig Arnold | Appointed November 2025; former CEO of Eaton Corporation |
| CFO | Josh Jepsen | Appointed January 2026; former CFO of Deere & Company |
Business Analysis & Competitive Dynamics
Honeywell Aerospace is the aerospace technologies division of Honeywell International, producing engines, avionics, auxiliary power units (APUs), flight controls, environmental systems, and connectivity solutions. Upon separation, it will be the largest pure-play aerospace supplier globally with $17.4B in revenue and a $37B order backlog providing multi-year revenue visibility.
The business is organized into three operating segments: Electronic Solutions (avionics, sensors, navigation), Engines & Power Systems (APUs, turboprops, business jet engines), and Control Systems (flight controls, environmental, mechanical systems). It serves commercial aviation (airlines + business jets), defense, and space markets.
Honeywell Aerospace’s strongest competitive moat is its APU franchise — it holds an estimated 65-80% share of the commercial airliner APU market with sole-source positions on major aircraft platforms. APUs generate high-margin recurring aftermarket revenue over decades-long aircraft lifecycles. The avionics business is a top-3 global franchise, and the company has deep cross-selling advantages as a multi-system supplier (APU + avionics + controls on the same aircraft).
Key risks include $16B of debt loaded at separation (~3.0x EBITDA), aerospace cycle sensitivity, supply chain constraints, and competition from larger peers (GE Aerospace, RTX/Collins). However, the $37B backlog and embedded installed base provide significant downside protection.
Acquisition Analysis
Unlike Mobility Global, Honeywell Aerospace is unlikely to be acquired — at an implied enterprise value exceeding $100B, it is too large for any single strategic or financial buyer. The most realistic acquirer scenarios are:
| Scenario | Probability |
|---|---|
| Remains independent | ⚠️ 70%+ |
| Safran partial/structured deal | ⚠️ 15-20% (CFIUS risk, would need consortium) |
| RTX “merge then remedy” | ❓ 10-15% (antitrust overlap in avionics) |
| PE consortium (Blackstone/Apollo/KKR) | ❓ 5% (would be one of largest buyouts ever) |
The investment thesis is about standalone value creation (rerating, debt paydown, capital return) rather than acquisition premium.
Changes & Developments
| Date | Change |
|---|---|
| May 31, 2026 | Grade unchanged (A, 4.05). $16B senior notes priced March 10 (9 tranches; ~$10B new money + ~$6B exchange; closed ~Mar 16) — capital structure de-risked. Form 10 amended (10-12B/A); SEC effectiveness pending. Record/distribution dates still unannounced; Q3 2026 target intact. Investor Day June 3 in Phoenix confirmed (CEO Vimal Kapur: Aerospace “well-prepared to stand on its own”). Solstice (SOLS) post-spin performance now +68% (was +90% in prior report). |
| Apr 15, 2026 | Grade upgraded A- → A. Form 10 filed March 3 — confirmed $17.4B revenue, $4.3B EBIT. Ticker HONA (Nasdaq). $16B senior notes offering launched. Investor Day set June 3, 2026 in Phoenix. Scored 4.00/5.0. |
| Mar 2, 2026 | Grade unchanged (A). New segment reporting structure effective Jan 1, 2026 (Electronic Solutions, Engines & Power Systems, Control Systems). Form 10 filing pending. |
| Jan 29, 2026 | First dedicated section. Grade: A. Full leadership named: CEO Jim Currier, Chairman Craig Arnold, CFO Josh Jepsen. $37B backlog disclosed. Timeline accelerated to Q3 2026. |
| Oct 24, 2025 | Tracker table only. Revenue estimated $15B+. Listed as “Part 2 of 3-way Honeywell split.” H2 2026 target. No grade. |
| Oct 23, 2025 | Mentioned only as RemainCo context in Solstice (SOLS) section. Aerospace described as “higher quality” business retained temporarily. |
In Depth Analysis
April 30, 2026 deep-dive, with key facts refreshed for the May 31, 2026 report (notes priced, Solstice post-spin return updated to +68%).
Competitive Dynamics
1. Product segments and competitors
✅ Honeywell Aerospace competes across five major product categories, with varying competitive positions in each:
| Segment | Honeywell Position | Key Competitors | Competitive Assessment |
|---|---|---|---|
| APUs (Auxiliary Power Units) | ✅ Dominant (~65-80% market share) | Pratt & Whitney (RTX), Safran (emerging) | Near-duopoly with P&W. Honeywell is sole-source on Boeing 777 and other platforms. Winner-take-decades economics. |
| Avionics & Flight Deck | ✅ Top 3 globally | Collins Aerospace (RTX), Thales Group, Garmin | Collins is strongest head-to-head on large commercial. Garmin dominates light/business aviation. Thales stronger in Europe. |
| Engines (turboprop/bizjet) | ⚠️ Second-tier | GE Aerospace, Rolls-Royce, Pratt & Whitney, Safran | Honeywell participates in turboprops and business jets but is NOT a tier-1 commercial jet engine maker. |
| Connected Aircraft / Connectivity | ⚠️ Growing, competitive | Viasat, Iridium, Collins Aerospace | JetWave system is competitive but market is highly contested. Growth area. |
| Defense Systems / Navigation | ⚠️ Selective | Northrop Grumman, BAE Systems, L3Harris, Leonardo | Strong in specific niches (inertial navigation, sensors) but not a top-tier defense prime. |
2. Market concentration
✅ Concentrated (effective duopoly) in APUs: Honeywell (~65-80%) and Pratt & Whitney (~20-35%) split virtually the entire market. Platform selection locks in a supplier for the life of the aircraft program (20-30+ years). Safran is the only credible emerging entrant (Boeing JV).
⚠️ Oligopolistic in avionics and systems: A handful of major suppliers (Collins, Honeywell, Thales, Garmin) compete for aircraft programs. Moderate barriers to entry due to aerospace certification requirements (DO-178C, DO-254). Switching costs are high once selected.
⚠️ Oligopolistic in engines: Dominated by GE Aerospace, Rolls-Royce, Pratt & Whitney, and Safran in commercial. Honeywell participates selectively in smaller engine categories.
3. Moats and weak spots
✅ Strongest moat: APU installed base. 95,000+ APUs produced, 36,000+ still in active service. Each APU generates $2-6M+ in lifetime aftermarket revenue at 30-50%+ margins. Platform selection creates “winner-take-decades” economics — once an APU is selected for an aircraft type, Honeywell supplies parts and service for 25-30+ years.
✅ Strong moat: Aerospace certification barriers. FAA/EASA certification of avionics and safety-critical systems takes years and millions of dollars. Once certified, replacement is extremely costly and risky for airlines — creating natural lock-in.
✅ Strong moat: Multi-system cross-selling. Honeywell often supplies APU + avionics + flight controls + environmental systems on the same aircraft. This “content per aircraft” advantage creates bundled switching costs.
⚠️ Weak spot: Not a commercial jet engine leader. Unlike GE Aerospace or Rolls-Royce, Honeywell does not make engines for major commercial aircraft (737, A320, 787, etc.). This limits Honeywell’s share of the highest-value aftermarket segment.
❓ Emerging threat: More-electric aircraft. Boeing 787’s architecture reduces APU dependency by using electric systems for functions APUs traditionally handled. If this architecture becomes standard on next-generation narrowbodies, APU aftermarket growth could slow over a 10-15 year horizon.
4. Head-to-head vs closest competitor: Collins Aerospace (RTX)
⚠️ Collins Aerospace (a division of RTX Corporation) is Honeywell’s most direct competitor across the broadest range of products:
| Dimension | Honeywell Aerospace | Collins Aerospace (RTX) |
|---|---|---|
| Revenue | $17.4B | ~$28B+ (RTX segment) |
| EBIT margin | ~25% | ⚠️ ~16-18% (RTX blended) |
| APU | ✅ Dominant (65-80%) | Second place |
| Avionics | Top 3 | ✅ Slight edge (broader cockpit architecture) |
| Engines | Second-tier | ✅ Pratt & Whitney is tier-1 |
| Aftermarket | ✅ Higher quality (APU-driven) | Broader but lower margin |
| Defense | Selective/niche | ✅ Broader (Raytheon missiles, radar) |
| Business jet content | ✅ Higher margin mix | Wider platform |
⚠️ Key assessment: “Honeywell is probably the better business; Collins is probably the stronger platform.” Honeywell has higher margins and deeper moats in narrower niches (APUs). Collins has broader scale and wider aircraft integration.
5. Crown jewel: APU business
✅ The APU franchise is Honeywell Aerospace’s most valuable and defensible business — a textbook “razor and blade” model:
| Phase | Revenue per unit | Margin | Duration |
|---|---|---|---|
| Initial OEM sale | $500K–$1.5M | ⚠️ ~15-25% | One-time |
| Lifetime aftermarket | $2M–$6M+ | ⚠️ ~30-50%+ | 25-30 years |
- ✅ 95,000+ APUs produced historically; 36,000+ still in active service
- ✅ Sole-source on Boeing 777 and parts of Airbus narrowbody family
- ✅ Installed base = locked-in future cash flow (more important than shipments)
- ⚠️ APUs have higher runtime in business aviation (remote airports, private terminals, less ground infrastructure) — making business jet APUs particularly profitable
Competitive moat depth: A new entrant would need: (1) billions in R&D, (2) 5-10 years of certification, (3) an aircraft OEM willing to risk a new supplier on a safety-critical system, (4) decades to build an aftermarket base. This effectively makes the APU market a closed duopoly.
6. Total addressable market
⚠️ Global aerospace supplier market estimated at ~$200-250B annually, including:
| Market segment | Size | Growth | Honeywell’s position |
|---|---|---|---|
| Commercial aviation aftermarket | ~$70-80B | 5-7% | ✅ Strong (APU, avionics, systems) |
| Commercial OE | ~$50-60B | 3-5% | ⚠️ Moderate (not in large engines) |
| Defense | ~$50-60B | 4-6% | ⚠️ Selective niches |
| Business aviation (total) | ~$20-21B → ~$29-30B by 2030s | 5-8% | ✅ Strong multi-system supplier |
| Connectivity/data | ~$5-10B | 10-15% | ⚠️ Growing (JetWave) |
⚠️ Honeywell’s estimated share of the business jet market: 25-30% of revenue, 30-40% of segment profit — the highest-quality slice of the aerospace market.
7. Geographic and end-customer competitive map
✅ Commercial aviation (airlines): Collins and Honeywell contest most programs. Honeywell dominates APUs; Collins has broader avionics integration. Thales is stronger with European airlines/Airbus programs.
✅ Business aviation: Honeywell is deeply embedded with Gulfstream and Bombardier (multi-system supplier). Garmin is stronger in Textron light jets. Collins contests large-cabin avionics.
⚠️ Defense: Honeywell is a niche player (navigation, sensors, guidance). Not a prime contractor. Competes against Northrop Grumman, L3Harris, BAE Systems in specific subsystems.
⚠️ Geography: Revenue split roughly 55% Americas, 25% EMEA, 20% Asia-Pacific. Defense revenue is predominantly US-based (ITAR restrictions limit international sales for some products).
Financials & Valuation
1. Operating margins vs peers
✅ Honeywell Aerospace’s margins position it as a premium aerospace business, below TransDigm but meaningfully above RTX and Safran:
| Company | EBIT Margin | Business Type | Why Margin Differs |
|---|---|---|---|
| TransDigm (TDG) | ✅ ~46-47% | Sole-source aerospace parts | Monopoly pricing, no OE exposure |
| Honeywell Aerospace (HONA) | ✅ ~25% | Premium systems + APU aftermarket | APU/avionics aftermarket mix drives premium |
| GE Aerospace (GE) | ~21-22% | Engine aftermarket dominant | Massive installed base but engine OE dilutes margin |
| RTX Corporation (RTX) | ~16-18% | Broadest platform (engines + systems + defense) | OE manufacturing, structures, interiors dilute |
| Safran (SAF.PA) | ~16-17% | Engine-focused, improving | CFM56/LEAP engine cycle maturing |
⚠️ Key insight: “Every 5 points of sustainable margin can add ~3-5 turns of EV/EBIT multiple in aerospace.” Honeywell’s margin premium over RTX/Safran should command a valuation premium.
⚠️ Quality-adjusted ranking: TransDigm > Honeywell > GE > Safran > RTX for business quality. GE > Honeywell > Safran > RTX > TransDigm for installed base durability.
2. Peer financial comparison
| Metric | Honeywell Aerospace | GE Aerospace | RTX Corp | TransDigm | Safran |
|---|---|---|---|---|---|
| Revenue | $17.4B | ⚠️ ~$38B | ⚠️ ~$80B | ⚠️ ~$7.5B | ⚠️ ~$27B |
| EBIT Margin | ~25% | ~21-22% | ~16-18% | ~46-47% | ~16-17% |
| Debt/EBITDA | ⚠️ ~3.0-3.2x (at spin) | ⚠️ ~1-2x | ⚠️ ~2-3x | ⚠️ ~5-7x | ⚠️ ~1-2x |
| Interest Coverage | ⚠️ ~5-5.5x | High | High | ~4-5x | High |
| EV/EBIT | ❓ TBD (not yet trading) | ⚠️ ~24-27x | ⚠️ ~17-20x | ⚠️ ~25-28x | ⚠️ ~18-21x |
| Forward P/E | ❓ TBD | ⚠️ ~32-35x | ⚠️ ~22-25x | ⚠️ ~33-36x | ⚠️ ~24-27x |
⚠️ Note: TransDigm’s high leverage (5-7x) is by design — its sole-source pricing power supports aggressive capital structure. Honeywell’s 3.0x is moderate for aerospace but high vs GE/Safran.
3. Implied standalone valuation
⚠️ Based on peer multiples and margin profile:
| Scenario | Multiple | EBIT | Enterprise Value | Equity Value (less $16B debt) |
|---|---|---|---|---|
| Conservative (RTX/Safran level) | 18x EBIT | $4.3B | $77B | ~$61B |
| Base case | 22x EBIT | $4.3B | $95B | ~$79B |
| Bull case (mini-TransDigm premium) | 25x EBIT | $4.3B | $108B | ~$92B |
⚠️ Key thesis: “Honeywell Aerospace probably has the biggest gap between perceived quality and actual quality” among aerospace peers. If market recognizes APU moat quality and margin sustainability, re-rating from RTX-level to GE-level multiples is the base case.
4. Debt structure
✅ $16B total debt priced March 10, 2026 (closed ~March 16) via senior notes offering — 9 tranches, ~$10B new money + ~$6B exchange:
| Maturity | Amount | Notes |
|---|---|---|
| 2028 | $1.25B | Near-term |
| 2029 | $1.25B + $0.5B floating | |
| 2031 | $2.0B | |
| 2033 | $1.75B | |
| 2036 | $3.25B | Core |
| 2046 | $1.0B | Long-duration |
| 2056 | $3.5B | Long-duration |
| 2066 | $1.5B | Long-duration |
Plus $3B 5-year and $1B 364-day revolving credit facilities.
⚠️ Leverage: ~3.0-3.2x EBITDA (estimated EBITDA $5.0-5.4B). Weighted average coupon estimated ~4.8-5.2%, annual interest ~$770-830M.
⚠️ Debt quality assessment: Long-duration fixed-rate debt is smart for aerospace — stable aftermarket cash flows match well with long-dated bonds. The 40-year tranche ($1.5B at 2066) signals confidence in business durability.
5. Post-interest free cash flow
⚠️ Estimated FCF framework:
- EBITDA: ~$5.0-5.4B
- Less capex: ~$500-700M (aerospace is more capital-intensive than data businesses)
- Less interest: ~$770-830M
- Pre-tax FCF: ~$3.5-3.9B
- Post-interest FCF to equity: ~$2.0-2.6B
⚠️ FCF yield at base case equity value ($79B): ~2.5-3.3% — “not cheap” but reflects quality.
6. Valuation framework
⚠️ Framework for assessing Honeywell Aerospace once trading:
- Attractive: Below 16x EBIT equity equivalent. Possible during post-spin forced selling.
- Fair: 18-22x EBIT. Reflects premium margins but offset by leverage.
- Expensive: Above 24x EBIT. Would need clear evidence of TransDigm-like pricing power.
7. Dividend strategy
❓ No dividend guidance yet. Expected framework based on Solstice precedent and aerospace peer practices:
⚠️ Likely sequence: (1) Debt reduction priority in years 1-2, (2) Modest dividend initiation within 6-12 months post-spin, (3) Buybacks once leverage normalizes below 2.5x, (4) M&A after 2+ years.
⚠️ Solstice precedent: Honeywell’s first spinoff (SOLS) initiated an early dividend and authorized a $1B buyback within the first year, while carrying only 1.5x leverage. Aerospace’s 3.0x leverage suggests a more conservative initial approach.
Spinoff Deep Dive
1. Comparison to prior spins from same parent: Solstice (SOLS)
✅ Solstice Advanced Materials spun off October 30, 2025 — the first of Honeywell’s 3-way split:
| Dimension | Solstice (SOLS) | Aerospace (HONA) |
|---|---|---|
| Revenue | ~$3.9B | $17.4B |
| EBITDA | ~$957M | ~$5.0-5.4B (est) |
| EBITDA margin | ~24.6% | ~29-31% (est) |
| Debt at spin | $1B | $16B |
| Leverage | ~1.5x | ~3.0x |
| Post-spin performance | ✅ +68% (as of May 29, 2026) | TBD |
| Capital return | Early dividend + $1B buyback | ❓ TBD |
⚠️ Key takeaway: Solstice’s strong performance validates Honeywell’s execution as a spin operator. However, Aerospace carries 2x the leverage, which limits near-term capital aggressiveness.
⚠️ Two interpretations of the debt difference:
- ⚠️ Parent optimizes own value first (70% probability) — S&P Global and Honeywell both load debt onto SpinCo to maximize cash returned to parent. This is standard practice.
- ⚠️ Leverage calibrated to business durability (30%) — Aerospace’s $37B backlog and recurring aftermarket can support higher debt.
2. Parent motives and capital allocation
✅ Honeywell’s 3-way split is a comprehensive value-unlock strategy:
- Phase 1: Spin off Solstice (Advanced Materials) — completed Oct 2025
- Phase 2: Spin off Aerospace — Q3 2026
- Phase 3: RemainCo becomes Honeywell Automation
⚠️ Pattern: Spin high-quality assets → use spin-related debt to recapitalize parent → parent becomes M&A platform for automation consolidation.
3. RemainCo (Honeywell Automation)
⚠️ Post-spin parent retains:
- Building Automation: Sticky installed base, service contracts, mid-to-high teens margins
- Process Automation / UOP: Cyclical (refining, chemicals, energy), mid-to-high teens margins
- Industrial Automation: Weakest bucket, actively pruning (sold Warehouse and Workflow Solutions)
⚠️ Pro forma RemainCo: ~$16.1B revenue, ~$2.5-3.0B EBIT, 15-18% margins.
⚠️ Quality comparison: Aerospace is the crown jewel (FAA-certified, replacement demand, APU lock-in). RemainCo is more project-based, macro-sensitive, lower switching costs. Aerospace = compounder. RemainCo = restructuring/M&A story.
4. Potential acquirers
⚠️ Unlike Mobility Global, acquisition is unlikely due to sheer size (>$100B EV). Detailed assessment:
| Acquirer | Strategic Fit | Financial Ability | Regulatory Risk | Probability |
|---|---|---|---|---|
| Safran | ✅ 9/10 | ⚠️ 8/10 (would need $35-40B stock + $20-25B debt) | ❓ 3/10 (CFIUS, defense sensitivity) | ⚠️ 15-20% |
| RTX | ✅ 10/10 | ✅ 9/10 | ❓ 3/10 (massive antitrust overlap in avionics) | ⚠️ 10-15% |
| PE consortium | 6/10 | 7/10 | 8/10 | ❓ 5% |
| Remains independent | — | — | — | ⚠️ 60-70% |
⚠️ Most realistic acquirer path: Safran partial/structured deal — Safran acquires avionics + APU divisions, PE buys remaining assets. Or RTX “merge then remedy” strategy (acquire whole, divest overlapping avionics to Safran, retain APUs + systems).
5. Acquisition probability and premium
⚠️ Low probability of full acquisition (20-30%) within 3 years. If it happens, expected premium 25-40% over standalone trading price. CFIUS review would be the primary obstacle for any foreign acquirer (Safran is French).
6. SpinCo as acquirer
⚠️ Honeywell Aerospace is more likely to be the acquirer than be acquired. Expected M&A timeline:
| Phase | Timeline | Target Type | Deal Size |
|---|---|---|---|
| Phase 1: Debt focus | 0-2 years | No major deals | — |
| Phase 2: Bolt-ons | 2-4 years | Avionics software, defense electronics, connectivity | $500M-$5B |
| Phase 3: Platform | 4+ years | Major aerospace software, autonomy, connected aircraft | $5B+ |
⚠️ Top 5 most realistic acquisition targets:
- Mercury Systems (defense electronics — distressed, good fit)
- Astronics Corporation (avionics software/power)
- Viasat aviation assets (connectivity)
- Curtiss-Wright select assets (defense sensors)
- Vertical Aerospace (eVTOL — existing strategic ties)
7. Structural features
✅ Tax-free spinoff for US federal tax purposes (100% distribution) ✅ Nasdaq listing under ticker HONA ✅ Form 10 filed March 3, 2026 ✅ Part 2 of 3-way split (Solstice completed, Automation becomes RemainCo) ⚠️ $16B debt at separation — highest among recent major aerospace spins ❓ Distribution ratio: TBD ❓ TSAs with Honeywell Automation: Likely for shared services during transition ❓ Insider lockup periods: Unknown
Investment Thesis
1. Bull case
Honeywell Aerospace is a generational pure-play aerospace franchise disguised by years of conglomerate embedding. The APU monopoly (65-80% share, 36,000+ installed base, 30-50% aftermarket margins) is TransDigm-quality economics in a $17B revenue platform. As a standalone, the market re-rates Aerospace from conglomerate-discount to premium aerospace multiples (22-25x EBIT), unlocking 50-100% upside over 3 years. Solstice’s +68% post-spin performance proves Honeywell executes spins well. Defense spending tailwinds and a $37B backlog provide a strong floor.
2. Bear case
$16B of debt at separation (~3.0x EBITDA) limits capital flexibility and suppresses equity returns in years 1-2. Post-interest FCF yield of 2.5-3.3% on a $79B equity value is not cheap. This is the most anticipated spin of 2026 — institutional investors are already positioned, limiting the “forced selling” discount typical of smaller spins. More-electric aircraft architecture (Boeing 787 model) gradually reduces APU dependency over 10-15 years. Aerospace cycle turns down, and $37B backlog doesn’t protect against margin pressure from supply chain inflation.
3. Top 3 catalysts (next 12 months)
- ✅ June 3, 2026 — Investor Day: Detailed financial model, growth strategy, capital allocation framework, dividend policy. The single most important near-term event.
- ⚠️ Q3 2026 — Distribution and first trading day: Forced selling by index funds and conglomerate investors creates potential buying opportunity. First 30-60 days of independent trading will set the market’s initial valuation.
- ⚠️ Q4 2026 — First standalone earnings report: First quarter of independent financial reporting. Sets the narrative for growth, margins, and management credibility.
4. Top 3 risks
- ⚠️ Debt overhang: $16B debt with ~$770-830M annual interest. If aerospace cycle weakens, high fixed costs amplify earnings decline. Interest coverage ~5-5.5x is adequate but not generous.
- ⚠️ Valuation expectations already elevated: Unlike a surprise spin or small-cap separation, Honeywell Aerospace is widely followed. The “hidden value” thesis may already be partially priced in. Less upside from forced-selling dynamics.
- ❓ Long-term APU structural risk: More-electric aircraft reduce APU dependency. Safran-Boeing JV targeting APU market share. Not imminent but a 10-15 year structural question for the crown jewel business.
5. Capital return framework
⚠️ Expected sequence based on Solstice precedent and leverage profile:
- Debt management (years 0-2): Maintain investment-grade rating. Target reducing leverage from 3.0x to ~2.0-2.5x through EBITDA growth and modest debt paydown.
- Dividend (months 6-12): Likely a modest initial dividend. Solstice set the precedent but carried half the leverage.
- Buybacks (years 2-3): Once leverage normalizes, expect authorization similar to Solstice ($1B+).
- M&A (years 3-5): Bolt-on acquisitions in avionics software, defense electronics, connectivity once debt permits.
⚠️ Value creation scenarios:
- Scenario A “Solstice-like rerating” (+50-100%): 30% probability
- Scenario B “Steady compounder” (+40-80% over 3 years): 50% probability (base case)
- Scenario C “Debt-boxed” (flat 1-2 years): 20% probability
Report-by-Report Analysis
Analysis — May 31, 2026
Summary — largely confirmatory: $16B notes now priced (vs launched), Form 10 amended, and record/distribution dates still pending. The June 3 Investor Day is the next gating catalyst.
- Company: Honeywell International (HON) — Current Price: ~$237.86 (May 29, 2026)
- SpinCo: Honeywell Aerospace (ticker HONA, Nasdaq)
- Investment Grade: A (Strong Buy) — score 4.05
- Key Thesis: Largest pure-play aerospace supplier on separation. $17.4B revenue, $4.3B pro forma EBIT, $37B backlog. $16B senior notes priced March 10. Investor Day June 3, 2026 in Phoenix is the next catalyst — and likely the venue for record-date/exchange-ratio disclosure.
Financial Structure (from Form 10)
| Metric | Honeywell Aerospace (SpinCo) |
|---|---|
| 2025 Net Sales | $17.4B |
| Pro forma Net Income | $1.5B |
| Pro forma Adjusted EBIT | $4.3B (per prior disclosure) |
| Order Backlog | $37B (per prior disclosure) |
| New Debt | $16B senior notes priced March 10 (9 tranches; ~$10B new money + ~$6B exchange) |
Key Developments Since Last Report
- March 10, 2026: $16B senior notes priced (closed ~March 16); new-money proceeds fund a cash distribution to Honeywell ahead of the spin
- Form 10 amended (10-12B/A); SEC effectiveness not yet declared
- Record and distribution dates NOT yet announced; exchange ratio undisclosed
- June 3, 2026 Investor Day confirmed in Phoenix; CEO Vimal Kapur: Aerospace is “well-prepared to stand on its own”
- Q3 2026 completion target intact
- Solstice (SOLS) — Honeywell’s first spin — now trading +68% post-spin (down from +90% cited in the April report, but still validating Honeywell’s spin execution)
Management Team
| Role | Name |
|---|---|
| CEO (Aerospace) | Jim Currier |
| Chairman | Craig Arnold |
| CFO | Josh Jepsen |
Transaction Timeline
- February 2025: 3-way split announced
- October 2025: Solstice spinoff completed (SOLS)
- March 3, 2026: Form 10 filed; March 10: $16B notes priced ✅
- June 3, 2026: Investor Day 📅
- Q3 2026: Expected distribution; record date TBD ⚠️
Investment Scorecard
| Dimension | Weight | Score | Rationale |
|---|---|---|---|
| Financial Profile | 25% | 4 | $17.4B rev, ~25% EBIT margin, high post-spin debt |
| Competitive Position | 25% | 5 | Largest pure-play aerospace supplier, $37B backlog |
| Strategic Rationale | 20% | 4 | Clear focus-unlock; Honeywell proven execution (SOLS +68%) |
| Management & Governance | 20% | 4 | Full C-suite from prior Honeywell leadership |
| Acquisition Potential | 10% | 2 | Too large (>$100B) for most acquirers |
| Weighted Score | 4.05 | ||
| Investment Grade | A | Strong Buy |
Grade Change: Unchanged (A). Notes pricing de-risks the capital structure; record-date disclosure (likely at/after June 3) is the next gating item.
Analysis — April 15, 2026
Full section — Form 10 filed, $17.4B revenue confirmed, $16B debt disclosed, ticker assigned. Most substantive report.
- Company: Honeywell International (HON) — Current Price: ~$229.04 (April 15, 2026)
- SpinCo: Honeywell Aerospace (ticker HONA, Nasdaq)
- Investment Grade: A (Strong Opportunity) — UPGRADED from A-
- Key Thesis: Form 10 filed March 3. 2025 net sales $17.4B, pro forma EBIT $4.3B. $16B senior notes offering. Investor Day June 3, 2026.
Financial Structure (from Form 10)
| Metric | Honeywell Aerospace (SpinCo) |
|---|---|
| 2025 Net Sales | $17.4B |
| Pro forma Net Income | $1.5B |
| Pro forma Adjusted EBIT | $4.3B |
| Order Backlog | $37B |
| Operating Segments | Electronic Solutions; Engines & Power Systems; Control Systems |
Key Developments Since Last Report
- March 3, 2026: Form 10 filed. Ticker: HONA (Nasdaq).
- March 2026: $16B senior notes offering launched. $3B + $1B revolving credit facilities.
- June 3, 2026: Investor Day confirmed in Phoenix.
Investment Scorecard
| Dimension | Weight | Score | Rationale |
|---|---|---|---|
| Financial Profile | 25% | 4 | $17.4B rev, 25% EBIT margin, high debt post-spin |
| Competitive Position | 25% | 5 | Largest pure-play aerospace supplier, $37B backlog |
| Strategic Rationale | 20% | 4 | Clear focus-unlock; Honeywell proven execution |
| Management & Governance | 20% | 4 | Full C-suite from prior Honeywell leadership |
| Acquisition Potential | 10% | 2 | Too large (>$100B) for most acquirers |
| Weighted Score | 4.00 | ||
| Investment Grade | A | Strong Buy |
Grade Change: Upgraded A- → A after Form 10 disclosure confirmed $17.4B revenue and $4.3B EBIT.
Analysis — March 2, 2026
Summary — no major new data vs January. Segment restructuring and timeline confirmation.
- Investment Grade: A (unchanged)
- New segment reporting structure effective January 1, 2026 (Aerospace Technologies → Electronic Solutions, Engines & Power Systems, Control Systems)
- Timeline confirmed: Q3 2026 (accelerated from generic H2 2026)
- Form 10 filing pending (prerequisite for separation)
- Management team unchanged (Currier/Arnold/Jepsen)
- Financial estimates unchanged ($15B+ revenue, $37B backlog)
- Same strengths/risks/catalysts as January report
Analysis — January 29, 2026
Full section — first dedicated Aerospace analysis with leadership team and $37B backlog.
- Investment Grade: A (Strong Opportunity) — first formal grade
- Key Thesis: Part 2 of Honeywell’s 3-way split. Creates largest pure-play aerospace supplier. $37B order backlog. Full leadership team named.
Management Team (Fully Announced)
| Role | Name | Appointed |
|---|---|---|
| CEO | Jim Currier | November 2025 |
| Chairman | Craig Arnold | November 2025 |
| CFO | Josh Jepsen | January 2026 |
Financial Highlights
| Metric | Aerospace (SpinCo) |
|---|---|
| Revenue | $15B+ (est) |
| Order Backlog | $37B |
Investment Analysis
Strengths: $37B backlog, largest pure-play aerospace supplier, experienced leadership, tax-free. Risks: Aerospace cycle uncertainty, supply chain constraints, competition from GE Aerospace and RTX. Catalysts: Defense spending increases, commercial aviation recovery, portfolio optimization.
Recommendation: BUY — Monitor for record date announcement in Q2 2026.
Analysis — October 24, 2025
Summary — tracker table entry only. No dedicated section.
- No grade assigned
- Revenue estimated $15B+ (est)
- Listed as “Part 2 of 3-way Honeywell split”
- Expected H2 2026
- Noted as largest spinoff by revenue among tracked companies
Analysis — October 23, 2025
Summary — mentioned only in Solstice section context. No dedicated analysis.
- Aerospace described as “higher quality” business retained temporarily alongside Automation
- Part of the planned 2026 Automation/Aerospace split
- No financial details or analysis