Mobility Global MBGL
-10.8%vs Day 1Spinoff of S&P Global (SPGI) · Classic Spinoff · Spun Jul 1, 2026
Expected return (11/13/2026): +26% Gain to loss: 4.0 : 1Monopoly automotive data platform with iconic CARFAX brand, 40.6% adjusted EBITDA margins and 65% FCF conversion, near-impossible-to-replicate data moat, and high acquisition probability for the CARFAX data asset
Current Stats
Post-Spinoff Performance
| Timeline | |
| Spinoff date | July 1, 2026 · NYSE |
| Days since spinoff | 136 days |
| Structure | Classic Spinoff |
| §355(e) window closes statutory; a tax matters agreement may bar more, and for longer | July 1, 2028 |
| Parent | S&P Global (SPGI) |
| Day-1 reaction | |
| Day 1 open | $20.30 |
| Day 1 return (open→close) | +4.4% |
| Day 1 price (close) | $21.19 |
| Day 1 range | $18.10 – $21.50 +18.8% spread |
| Day 1 low held? | Breached after 2 sessions to -6.4% below |
| Price levels | |
| Post-spin low (closing) | $17.15 on Sep 30, 2026 · 91 days post-spin |
| Lowest traded | $16.95 on Oct 1, 2026 · 92 days post-spin |
| Current price (Nov 13, 2026) | $23.28 |
| Returns | |
| Return vs Day 1 (close) | +10.1% |
| — range by day 1 entry theoretical bounds | +8.6% to +29.0% |
| Return vs post-spin low | +35.7% |
| First-quarter return (≈90d) | -15.7% |
| Versus benchmarks | |
| S&P 500 over same window | +1.4% |
| Shares & ownership | |
| Shares outstanding Jun 30, 2026 | 294,821,320 |
| Diluted average shares the EPS denominator | 294,444,444 |
| Free float | 294,735,500 100% of shares outstanding |
| Held by institutions | 62% insiders 0.7% |
| Share count trend Mar 2026 → Jun 2026 | -0.1% broadly flat |
| Volume & liquidity | |
| Traded per day 20-session median | $59M |
| Normal volume baseline | 3,502,300 shares · now 0.86x |
| Day 1 volume | 27.9x normal · first week 11.4x |
| Decay | half in 2 sessions · normal by 14 |
Computed from split-adjusted closing prices. Returns are total return — (end price + dividends received − start price) ÷ start price — with no reinvestment assumed.
Price History
Closing price, split-adjusted, with volume below. The Price line excludes dividends; Price + dividends adds the cash paid out, with no reinvestment assumed. Individual payments are listed in the table below. Source: Yahoo Finance. Data through Nov 14, 2026.
Raw daily price & volume data · dividends marked
| Date | Open | High | Low | Close | Volume | Float | Turnover | Market cap | Dividend | Split |
|---|---|---|---|---|---|---|---|---|---|---|
| 2026-11-13 | $23.17 | $23.31 | $22.66 | $23.28 | 5,772,100 | 294,735,500 | 1.96% | $6.86B | — | — |
| 2026-11-12 | $21.12 | $23.31 | $21.09 | $23.13 | 7,288,200 | 294,735,500 | 2.47% | $6.82B | — | — |
| 2026-11-11 | $19.98 | $19.98 | $19.60 | $19.92 | 3,028,000 | 294,735,500 | 1.03% | $5.87B | — | — |
| 2026-11-10 | $19.66 | $20.03 | $19.40 | $19.93 | 3,127,400 | 294,735,500 | 1.06% | $5.88B | — | — |
| 2026-11-09 | $19.63 | $19.87 | $19.25 | $19.86 | 2,797,800 | 294,735,500 | 0.95% | $5.86B | — | — |
| 2026-11-06 | $19.35 | $19.98 | $19.25 | $19.64 | 2,853,600 | 294,732,551 | 0.97% | $5.79B | — | — |
| 2026-11-05 | $19.90 | $20.18 | $19.71 | $19.86 | 4,215,800 | 294,709,288 | 1.43% | $5.86B | — | — |
| 2026-11-04 | $19.15 | $20.00 | $19.15 | $19.79 | 4,776,600 | 294,709,288 | 1.62% | $5.83B | — | — |
| 2026-11-03 | $19.25 | $19.65 | $19.11 | $19.32 | 3,662,000 | 294,709,288 | 1.24% | $5.70B | — | — |
| 2026-11-02 | $18.91 | $19.77 | $18.72 | $19.60 | 2,935,200 | 294,709,288 | 1.00% | $5.78B | — | — |
| 2026-10-30 | $18.96 | $19.28 | $18.76 | $18.91 | 6,233,300 | 294,709,288 | 2.11% | $5.58B | — | — |
| 2026-10-29 | $18.33 | $19.01 | $18.26 | $18.92 | 9,318,200 | 294,709,288 | 3.16% | $5.58B | — | — |
| 2026-10-28 | $18.21 | $18.36 | $18.01 | $18.33 | 2,963,500 | 294,709,288 | 1.01% | $5.40B | — | — |
| 2026-10-27 | $18.71 | $18.77 | $18.14 | $18.20 | 3,378,300 | 294,709,288 | 1.15% | $5.37B | — | — |
| 2026-10-26 | $18.61 | $18.94 | $18.61 | $18.68 | 2,737,500 | 294,709,288 | 0.93% | $5.51B | — | — |
| 2026-10-23 | $19.13 | $19.29 | $18.65 | $18.76 | 3,012,300 | 294,709,288 | 1.02% | $5.53B | — | — |
| 2026-10-22 | $18.64 | $19.37 | $18.50 | $19.28 | 2,593,300 | 294,709,288 | 0.88% | $5.68B | — | — |
| 2026-10-21 | $18.57 | $18.71 | $18.43 | $18.52 | 2,383,000 | 294,709,288 | 0.81% | $5.46B | — | — |
| 2026-10-20 | $18.72 | $19.01 | $18.47 | $18.52 | 2,745,300 | 294,709,288 | 0.93% | $5.46B | — | — |
| 2026-10-19 | $18.55 | $18.73 | $18.25 | $18.43 | 2,714,700 | 294,709,288 | 0.92% | $5.43B | — | — |
| 2026-10-16 | $18.93 | $19.09 | $18.55 | $18.69 | 3,605,200 | 294,712,236 | 1.22% | $5.51B | — | — |
| 2026-10-15 | $18.02 | $18.93 | $18.02 | $18.72 | 4,638,400 | 294,712,236 | 1.57% | $5.52B | — | — |
| 2026-10-14 | $18.00 | $18.06 | $17.65 | $17.84 | 3,135,800 | 294,712,236 | 1.06% | $5.26B | — | — |
| 2026-10-13 | $18.14 | $18.37 | $17.99 | $18.11 | 2,595,100 | 294,712,236 | 0.88% | $5.34B | — | — |
| 2026-10-12 | $18.19 | $18.29 | $18.00 | $18.11 | 2,028,200 | 294,712,236 | 0.69% | $5.34B | — | — |
| 2026-10-09 | $18.02 | $18.31 | $18.02 | $18.22 | 2,215,300 | 294,712,236 | 0.75% | $5.37B | — | — |
| 2026-10-08 | $17.27 | $18.14 | $17.26 | $18.08 | 4,324,300 | 294,712,236 | 1.47% | $5.33B | — | — |
| 2026-10-07 | $17.53 | $17.74 | $17.26 | $17.37 | 2,710,600 | 294,712,236 | 0.92% | $5.12B | — | — |
| 2026-10-06 | $17.64 | $17.76 | $17.20 | $17.62 | 4,446,800 | 294,712,236 | 1.51% | $5.19B | — | — |
| 2026-10-05 | $17.31 | $17.72 | $17.09 | $17.59 | 8,118,100 | 294,712,236 | 2.75% | $5.19B | — | — |
| 2026-10-02 | $17.64 | $17.74 | $17.01 | $17.21 | 5,329,000 | 294,712,236 | 1.81% | $5.07B | — | — |
| 2026-10-01 | $17.22 | $17.74 | $16.95 | $17.71 | 3,688,100 | 294,712,236 | 1.25% | $5.22B | — | — |
| 2026-09-30 | $17.82 | $17.88 | $17.14 | $17.15 | 5,190,800 | 294,712,236 | 1.76% | $5.06B | — | — |
| 2026-09-29 | $17.72 | $17.86 | $17.36 | $17.80 | 4,548,100 | 294,712,236 | 1.54% | $5.25B | — | — |
| 2026-09-28 | $17.67 | $17.79 | $17.51 | $17.76 | 3,474,600 | 294,712,236 | 1.18% | $5.24B | — | — |
| 2026-09-25 | $18.17 | $18.42 | $17.80 | $17.87 | 5,493,500 | 294,712,236 | 1.86% | $5.27B | — | — |
| 2026-09-24 | $18.90 | $19.14 | $18.25 | $18.34 | 4,008,800 | 294,712,236 | 1.36% | $5.41B | — | — |
| 2026-09-23 | $19.00 | $19.21 | $18.77 | $18.88 | 2,910,400 | 294,712,236 | 0.99% | $5.57B | — | — |
| 2026-09-22 | $19.46 | $19.87 | $18.90 | $19.09 | 2,606,500 | 294,712,236 | 0.88% | $5.63B | — | — |
| 2026-09-21 | $19.49 | $19.60 | $18.92 | $19.20 | 4,201,300 | 294,712,236 | 1.43% | $5.66B | — | — |
| 2026-09-18 | $19.90 | $20.02 | $19.43 | $19.49 | 9,890,700 | 294,712,236 | 3.35% | $5.75B | — | — |
| 2026-09-17 | $19.90 | $20.16 | $19.85 | $20.05 | 3,181,800 | 294,712,236 | 1.08% | $5.91B | — | — |
| 2026-09-16 | $20.29 | $20.43 | $19.82 | $19.94 | 3,037,200 | 294,712,236 | 1.03% | $5.88B | — | — |
| 2026-09-15 | $20.15 | $20.52 | $20.04 | $20.34 | 3,378,500 | 294,712,236 | 1.15% | $6.00B | — | — |
| 2026-09-14 | $20.31 | $20.61 | $20.22 | $20.26 | 3,742,500 | 294,712,236 | 1.27% | $5.97B | — | — |
| 2026-09-11 | $20.23 | $20.36 | $19.91 | $20.16 | 2,754,400 | 294,712,236 | 0.93% | $5.94B | — | — |
| 2026-09-10 | $19.75 | $20.24 | $19.74 | $20.19 | 3,358,900 | 294,712,236 | 1.14% | $5.95B | — | — |
| 2026-09-09 | $20.45 | $20.53 | $19.75 | $19.76 | 3,906,300 | 294,712,236 | 1.32% | $5.83B | — | — |
| 2026-09-08 | $20.60 | $20.90 | $19.97 | $20.52 | 4,588,900 | 294,712,236 | 1.56% | $6.05B | — | — |
| 2026-09-04 | $20.33 | $20.62 | $20.21 | $20.58 | 3,365,400 | 294,712,236 | 1.14% | $6.07B | — | — |
| 2026-09-03 | $20.73 | $20.90 | $20.26 | $20.46 | 3,626,600 | 294,712,236 | 1.23% | $6.03B | — | — |
| 2026-09-02 | $19.90 | $20.83 | $19.76 | $20.38 | 3,782,100 | 294,712,236 | 1.28% | $6.01B | — | — |
| 2026-09-01 | $20.12 | $20.19 | $19.70 | $19.83 | 3,485,500 | 294,712,236 | 1.18% | $5.85B | — | — |
| 2026-08-31 | $20.04 | $20.58 | $20.04 | $20.30 | 4,365,800 | 294,729,925 | 1.48% | $5.98B | — | — |
| 2026-08-28 | $20.36 | $20.51 | $19.97 | $20.24 | 3,055,100 | 294,729,925 | 1.04% | $5.97B | — | — |
| 2026-08-27 | $20.42 | $20.80 | $20.25 | $20.27 | 3,945,600 | 294,729,925 | 1.34% | $5.98B | $0.06 | — |
| 2026-08-26 | $20.16 | $20.98 | $20.16 | $20.55 | 2,855,700 | 294,729,925 | 0.97% | $6.06B | — | — |
| 2026-08-25 | $19.78 | $20.36 | $19.70 | $20.26 | 3,450,100 | 294,729,925 | 1.17% | $5.97B | — | — |
| 2026-08-24 | $19.85 | $20.22 | $19.54 | $19.70 | 4,663,300 | 294,729,925 | 1.58% | $5.81B | — | — |
| 2026-08-21 | $20.30 | $20.45 | $19.72 | $19.85 | 2,902,400 | 294,729,925 | 0.98% | $5.85B | — | — |
| 2026-08-20 | $20.82 | $20.83 | $20.03 | $20.20 | 2,616,700 | 294,729,925 | 0.89% | $5.96B | — | — |
| 2026-08-19 | $19.94 | $21.13 | $19.94 | $20.69 | 6,031,500 | 294,729,925 | 2.05% | $6.10B | — | — |
| 2026-08-18 | $19.68 | $20.22 | $19.38 | $19.82 | 5,744,600 | 294,729,925 | 1.95% | $5.84B | — | — |
| 2026-08-17 | $20.22 | $20.34 | $19.63 | $19.72 | 3,776,800 | 294,729,925 | 1.28% | $5.81B | — | — |
| 2026-08-14 | $20.82 | $21.14 | $19.89 | $20.34 | 3,655,300 | 294,729,925 | 1.24% | $6.00B | — | — |
| 2026-08-13 | $19.75 | $20.00 | $19.55 | $19.83 | 3,758,800 | — | 1.27% | $5.85B | — | — |
| 2026-08-12 | $19.25 | $19.73 | $19.10 | $19.62 | 4,563,500 | — | 1.55% | $5.78B | — | — |
| 2026-08-11 | $18.73 | $19.80 | $18.73 | $19.37 | 4,880,500 | — | 1.66% | $5.71B | — | — |
| 2026-08-10 | $19.21 | $19.70 | $18.68 | $19.00 | 4,390,800 | — | 1.49% | $5.60B | — | — |
| 2026-08-07 | $20.37 | $20.70 | $18.72 | $19.70 | 10,921,200 | — | 3.70% | $5.81B | — | — |
| 2026-08-06 | $21.02 | $21.26 | $20.40 | $20.73 | 3,519,100 | — | 1.19% | $6.11B | — | — |
| 2026-08-05 | $21.06 | $21.57 | $20.91 | $21.26 | 3,331,700 | — | 1.13% | $6.27B | — | — |
| 2026-08-04 | $20.75 | $21.32 | $20.75 | $21.21 | 3,327,400 | — | 1.13% | $6.25B | — | — |
| 2026-08-03 | $20.27 | $21.31 | $20.27 | $21.30 | 2,612,600 | — | 0.89% | $6.28B | — | — |
| 2026-07-31 | $20.10 | $20.46 | $19.91 | $20.38 | 2,924,700 | — | 0.99% | $6.01B | — | — |
| 2026-07-30 | $21.24 | $21.26 | $20.11 | $20.48 | 2,852,900 | — | 0.97% | $6.04B | — | — |
| 2026-07-29 | $21.48 | $21.99 | $21.26 | $21.47 | 3,845,500 | — | 1.30% | $6.33B | — | — |
| 2026-07-28 | $20.00 | $22.00 | $19.91 | $21.72 | 6,184,000 | — | 2.10% | $6.40B | — | — |
| 2026-07-27 | $20.30 | $21.10 | $20.30 | $20.62 | 2,889,700 | — | 0.98% | $6.08B | — | — |
| 2026-07-24 | $20.67 | $21.34 | $20.38 | $20.55 | 4,174,800 | — | 1.42% | $6.06B | — | — |
| 2026-07-23 | $19.81 | $20.73 | $19.80 | $20.70 | 4,398,900 | — | 1.49% | $6.10B | — | — |
| 2026-07-22 | $19.85 | $20.44 | $19.76 | $20.38 | 4,829,300 | — | 1.64% | $6.01B | — | — |
| 2026-07-21 | $19.91 | $20.08 | $19.45 | $19.86 | 5,170,300 | — | 1.75% | $5.86B | — | — |
| 2026-07-20 | $20.40 | $20.63 | $19.88 | $20.12 | 4,715,400 | — | 1.60% | $5.93B | — | — |
| 2026-07-17 | $20.21 | $20.78 | $19.89 | $20.11 | 6,113,100 | — | 2.07% | $5.93B | — | — |
| 2026-07-16 | $21.24 | $21.37 | $20.13 | $20.66 | 5,457,000 | — | 1.85% | $6.09B | — | — |
| 2026-07-15 | $20.36 | $21.40 | $20.26 | $21.00 | 6,074,100 | — | 2.06% | $6.19B | — | — |
| 2026-07-14 | $20.38 | $21.29 | $20.21 | $20.57 | 6,641,800 | — | 2.25% | $6.06B | — | — |
| 2026-07-13 | $20.05 | $21.05 | $20.00 | $20.26 | 5,462,200 | — | 1.85% | $5.97B | — | — |
| 2026-07-10 | $21.53 | $21.72 | $20.75 | $20.80 | 5,922,000 | — | 2.01% | $6.13B | — | — |
| 2026-07-09 | $21.19 | $22.33 | $20.82 | $22.26 | 9,072,700 | — | 3.08% | $6.56B | — | — |
| 2026-07-08 | $20.72 | $21.97 | $19.91 | $21.50 | 17,409,500 | — | 5.91% | $6.34B | — | — |
| 2026-07-07 | $19.25 | $21.42 | $19.25 | $21.20 | 21,719,200 | — | 7.37% | $6.25B | — | — |
| 2026-07-06 | $18.85 | $19.46 | $17.67 | $19.26 | 35,850,600 | — | 12.16% | $5.68B | — | — |
| 2026-07-02 | $20.95 | $20.95 | $19.80 | $19.80 | 26,967,900 | — | 9.15% | $5.84B | — | — |
| 2026-07-01 | $20.30 | $21.50 | $18.10 | $21.19 | 97,846,400 | — | 33.19% | $6.25B | — | — |
Close is split-adjusted to current shares. It is not dividend-adjusted: dividends are listed separately, so total return is (end price + dividends received − start price) ÷ start price, checkable by hand. Volume is as-traded.
Momentum: MACD and RSI
Top: MACD (navy) and its signal line (gold); bars show the gap between them, teal when MACD is above.
Bottom: RSI over 14 days; above 70 is usually read as overbought and below 30 as oversold.
The lines start late because MACD needs 26 trading days of prices and RSI 14 before the first value.
The colored strip under the charts shows the state label day by day; hover for the state and the reason.
Both measure momentum in the price and say nothing about value. Hover for each day's arithmetic.
Source: closing prices from this site's daily price archive (Yahoo Finance), not adjusted for dividends. Data through Nov 14, 2026.
How these are calculated
Short Selling
Bars: shares sold short each day in trades reported to FINRA (off-exchange
trades, roughly half of all volume).
Line: the short share of that volume, averaged over 20 sessions.
Gold points: short interest, the shares sold short and not yet bought back,
reported twice a month, also shown as a percentage of the free float and of
shares outstanding.
Daily short volume includes market makers' routine hedging, so a change in the
share is more informative than its level. Hover for each day's figures.
Sources: FINRA; float from this site's daily share records; shares outstanding
from the company's latest quarterly filing. Data through Nov 13, 2026.
Index-Fund Holdings
Daily positions of State Street's SPDR index funds, by the fund's file date.
These are the index funds whose daily holdings can be collected; iShares and
Vanguard funds, often larger holders, publish holdings that cannot be
collected automatically and appear in the written analysis from their
quarterly filings.
Collection began on October 11, 2026. A fund that drops the stock shows as an
exit.
Source: State Street Global Advisors. Data through
Nov 12, 2026.
Update — November 12, 2026: third-quarter results and the scenarios re-struck — BUY, target $27 → $29
Rated at the November 12, 2026 close of $23.13 (Yahoo Finance; this site’s price archive adds the day overnight). Sources: the third-quarter results release (before the open on November 12, 2026), the third-quarter 10-Q (the same day), and a published transcript of the call of November 12, 2026. Earlier sections are left as published. This section grades the quarter against the tests set on October 5 and 14, 2026, re-strikes the three cases on the September 30, 2026 balance sheet and the new guidance, and resets the weights.
Overview Summary
The quarter passed the tests set for it, and the growth was mostly price. Revenue rose 7.4% to $478 million, CARFAX 8% (its third quarter in a row of faster growth in the United States) and B2B 6%; adjusted EBITDA was $195 million, a 41% margin, and 2026 EBITDA guidance was raised to $750–760 million. Of the $33 million of revenue growth, about $22 million came from price increases to existing customers, two-thirds, against 56% in the first half: CARFAX’s pricing is holding, and new business is still the smaller part. A board-approved $800 million buyback starts before the end of 2026, with $350–450 million planned by the end of 2027. The stock rose 16.1% on the day, while data and auto-marketplace peers fell. The cases move up about 50 cents each, to $41.09, $31.43 and $13.42 on lower net debt; with the weight on the worst case cut from 30% to 20%, the value is $29.28 and the target moves from $27 to $29. At $23.13 the expected return is +26.6% with gain to loss of 4.2 to 1, just inside BUY.
Rating: BUY below $23.42 · ACCUMULATE $23.42–26.62 · HOLD $26.62–32.53 · TRIM $32.53–39.04 · SELL above $39.04 · Target $29
The quarter
| $M | Q3 2026 | Q3 2025 | Change | Nine months 2026 | Nine months 2025 | Change |
|---|---|---|---|---|---|---|
| Revenue | 478 | 445 | +7.4% (organic, constant currency +7.6%) | 1,401 | 1,304 | +7% |
| CARFAX | 313 | 291 | +8% (organic +7.9%) | 923 | 855 | +8% |
| B2B | 164 | 154 | +6% (organic +6.5%) | 477 | 449 | +6% |
| Subscription revenue | 389 | 362 | +7% | 1,144 | 1,063 | +8% |
| Adjusted EBITDA (margin) | 195 (41%) | 191 (43%) | +2% | 581 (41%) | 548 (42%) | +6% |
| CARFAX adjusted EBITDA (margin) | 153 (49%) | 146 (50%) | +5% | 446 (48%) | 418 (49%) | +7% |
| B2B adjusted EBITDA (margin) | 45 (27%) | 52 (34%) | −13% | 147 (31%) | 145 (32%) | +1% |
| Net income | 42 | 71 | −41% | 150 | 194 | −23% |
| Adjusted earnings per share | $0.40 | $0.44 | −9% | $1.29 | $1.27 | +2% |
| Free cash flow | 186 | 136 | +37% | 363 | 361 | +1% |
As reported; adjusted EBITDA and free cash flow are the company’s definitions. 2025 figures are carved out of S&P Global; the third quarter of 2026 is the first full quarter as a standalone company.
- Price carried the growth. The 10-Q attributes about $22 million of the $33 million rise in revenue to “pricing actions”, the change in what existing customers pay, and the rest to net new business, which is new customers and wider use less customers lost. In the first half it was about $36 million of $64 million. CARFAX’s growth was “primarily attributable to pricing actions and growth in non-subscription revenue”; B2B’s was mostly price this quarter and mostly new business over nine months.
- The fall in net income is the cost of independence. Interest on the $2.0 billion of notes added about $22 million, selling and general costs rose $68 million (including $13 million of separation costs and the first full quarter of public-company costs), and B2B’s margin fell 7 points on compensation and investment.
- Free cash flow is flattered by timing. The notes pay interest each June 15 and December 15, starting December 15, 2026, so no interest was paid in the quarter; the first coupon, about $60 million for six and a half months, is due in the fourth quarter (an estimate from the coupons).
- Stock compensation was $9 million, about 1.9% of revenue, below the 3% the base case assumes.
- No shares were bought back in the quarter; the program was authorized in October 2026.
The tests set on October 5 and 14, 2026:
| Test | Needed | Result |
|---|---|---|
| CARFAX subscription growth | Near 8% | ✓ CARFAX revenue +8%; total subscription revenue +7% |
| CARFAX new sales | Shorter sales cycles since the June 2026 reversal of the bundle | ✓ Unit sales of all four main dealer products rose from the second quarter (management) |
| Adjusted EBITDA margin | At or above 38.4% in the second half | ✓ 41% in the third quarter; guidance implies about 36.5% in the fourth (an estimate) |
| CARFAX price against volume | New business recovering, not only price | ✗ About two-thirds of total growth was price, up from 56% |
| 2027 pricing | Any sign the 2026 increases return in 2027 | Not discussed |
| Marketplaces | Any further loss of listing-site tie-ins | None announced; not discussed on the call |
| Stock compensation | Run-rate against the 3–4% reported | ✓ 1.9% of revenue |
| Capital returns | Buybacks from early 2027 | ✓ Earlier: from before the end of 2026, $350–450 million by the end of 2027 |
What management said on November 12, 2026
From a published transcript of the call, which names some analysts inconsistently; the substance is used here.
- CARFAX sales: the bundles sold in 2025 have been dropped in favor of selling products one by one, and unit sales of Advantage, Listings, Service Loyalty and Showroom all rose from the second quarter. Service Loyalty and Listings are growing at double-digit rates among the largest dealer groups. Management expects “modest acceleration” in CARFAX’s growth in the fourth quarter as the units sold turn into revenue.
- Where the growth comes from: the Investor Day framework of 5–7% from the core, 1–2% from new products and 1–2% from outside the United States still stands. Canada “arguably got sequentially worse” from the second quarter; Europe grew at double digits with Germany in its first full quarter, which management called very early.
- Competition: the call did not discuss AutoCheck, the listing sites, prices or customer losses, and no analyst asked. Management said CARFAX Listings is “the only marketplace that provides a CARFAX report with every vehicle”, that CARFAX was the most-cited automotive site in AI chat tools among its competitors, and that traffic from AI agents is “still minimal”; its approach is to license data to AI tools on terms that keep the CARFAX name on the output.
- B2B: growth was about 5% without a one-off true-up, and some deals moved into 2027; fourth-quarter growth will be lower than the third.
- Costs and capital: public-company costs take about 1.5 points off the 2027 margin against the 2025 carve-out; about $100 million of one-time separation costs runs through 2027; cash taxes exceed the book charge by $80–90 million a year for about twelve years (a known item from the separation). Net leverage fell from 2.4 to 2.2 times; the dividend is $0.06 a quarter.
Why the stock moved
| Price return | October 13 to November 11, 2026 | November 12, 2026 | October 13 to November 12, 2026 |
|---|---|---|---|
| Mobility Global | +10.0% | +16.1% | +27.7% |
| Data and analytics peers | +15.7% | −1.0% | +14.5% |
| Auto marketplaces and dealers | +21.0% | −3.3% | +17.0% |
| Russell 2000 (IWM) | +2.3% | −1.6% | +0.6% |
| S&P 500 (SPY) | −2.3% | −0.4% | −2.7% |
Baskets equal-weighted, as in the October 9, 2026 update: S&P Global, Verisk, Moody’s, FactSet, MSCI, CoStar, TransUnion and Equifax; CarGurus, Cars.com, CarMax, Carvana and AutoNation. Closes from Yahoo Finance.
- Before the results the stock lagged its peers. From the October 14, 2026 update to the day before the results it rose 10.0%, against 15.7% for the data companies and 21.0% for the auto marketplaces.
- The results day was Mobility Global’s own. It rose 16.1% on 7.3 million shares, about 2.4 times the previous day’s volume, while both peer groups fell. The reasons were the step-up in growth, the raised EBITDA guidance and the size and timing of the buyback.
- Short sellers had been building. Short interest rose from 7.46 million shares at September 30, 2026 to 12.65 million at October 30, 2026, about 4.3% of the shares and 3.3 days of trading. Some of the rise on November 12, 2026 was probably short covering (inference; the November 13, 2026 figure is published about November 24, 2026).
| Report | Settled | Short | % float | % outst. | Days to cover |
|---|---|---|---|---|---|
| First after the spin | Jul 15, 2026 | 5.54M | 1.9% | 1.9% | 1.0 |
| Lowest since the spin | Jul 31, 2026 | 5.06M | 1.7% | 1.7% | 1.1 |
| Latest | Oct 30, 2026 | 12.65M | 4.3% | 4.3% | 3.3 |
The latest share of float is higher than 7 of the 7 earlier reports since the spin. Short interest in shares, with its share of the float and of shares outstanding. FINRA settlement dates; figures are published about eight business days later. Days to cover is short interest divided by average daily volume, as reported by FINRA. Float and shares outstanding on or before each date, from this site's daily share records and the company's filings.
The scenarios and the asymmetry
The method is the October 14, 2026 one, unchanged: the cases built line by line and valued at an 8.5% discount rate and 2.75% long-run growth (2.0% in the worst case). Two inputs change: net debt at September 30, 2026 of $1,649 million ($2,000 million of notes less $351 million of cash), against $1,795 million at June 30, 2026, and 2026 adjusted EBITDA guidance of $750–760 million, against $745–760 million. The case definitions are unchanged.
| Case | Published October 14, 2026 | Now | Change | Against $23.13 | What it needs |
|---|---|---|---|---|---|
| Best | $40.59 | $41.09 | +$0.50 | +78% | CARFAX growth back to 10–11%, margins widening |
| Base | $30.94 | $31.43 | +$0.49 | +36% | CARFAX 7–8%, B2B 4.5–5%, margins steady |
| Worst | $12.92 | $13.42 | +$0.50 | −42% | A 2027 used-car recession, then CARFAX loses its pricing power |
Estimates; the model is unchanged apart from the two inputs. The worst case is the combined stress test of October 14, 2026.
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $29.34 | +26.9% | 3.6 to 1 |
| October 14, 2026: 15 / 55 / 30 | $27.48 | +18.8% | 2.5 to 1 |
| Best guess: 15 / 65 / 20 | $29.28 | +26.6% | 4.2 to 1 |
| Stress: 10 / 40 / 50 | $23.39 | +1.1% | 1.05 to 1 |
| What the price implies, best held at 15%: 15 / 31 / 54 | $23.13 | 0% | — |
The weights are a judgment: the odds of each path over the next two to three years, revisited at each results update. All values are estimates from the model.
- Why the worst case falls from 30% to 20%. The worst case is two events in sequence, a used-car recession and then a loss of pricing power, and the quarter is evidence against the second. Customers paid about $22 million more for the same products, the largest price gain so far this year, while CARFAX’s growth sped up and unit sales of all four dealer products rose. Leverage is falling, and the buyback gives the shares a steady buyer from December 2026.
- Why it stays at 20% and not lower. The quarter says nothing about the first event. A rise of 0.25% in the federal funds rate on December 9, 2026 was priced at 91% on November 10, 2026 (CME FedWatch), which raises the cost of car loans into the spring selling season; Canada weakened during the quarter; and management assumes no improvement in the economy. On pricing itself the evidence is one-sided: no one on the call discussed AutoCheck or the listing sites, and growth that is two-thirds price depends on dealers continuing to accept increases.
- Why 15% on the best case. It needs CARFAX growth of 10–11%, which requires new business, the smaller part of this quarter’s growth, to pick up. The step-up in unit sales is the first sign of it.
- What the price implies: with the best case held at 15%, a 54% chance of the worst case, against 20% in the best guess.
| Measure | At $23.13 | Formula |
|---|---|---|
| Expected return (header chip) | +26.6% | (15% × $41.09 + 65% × $31.43 + 20% × $13.42) ÷ $23.13 − 1 = ($6.16 + $20.43 + $2.68) ÷ $23.13 − 1 |
| Gain to loss (header chip) | 4.2 to 1 | (15% × $17.96 + 65% × $8.30) ÷ (20% × $9.71) = ($2.69 + $5.40) ÷ $1.94 |
| Expected base gain ÷ expected worst loss | 2.8 to 1 | $5.40 ÷ $1.94 |
| Best gain ÷ worst loss | 1.8 to 1 | $17.96 ÷ $9.71 |
| Price-implied weights, best held at 15% | 15 / 31 / 54 | base weight = ($23.13 − 15% × $41.09 − 85% × $13.42) ÷ ($31.43 − $13.42) |
Both header chips take the color of the rating band the price is in: BUY green (an expected return of +25% or more with gain to loss of 3 to 1 or better), ACCUMULATE blue (+10% to +25%), HOLD gold (−10% to +10%), TRIM orange (−25% to −10%) and SELL red (below −25%). On the best guess they are green below $23.42 (gain to loss is 3.9 to 1 there, and reaches 3 to 1 only at $24.75), blue up to $26.62, gold up to $32.53, orange up to $39.04 and red above. At $23.13 both are green, 1.3% below the edge of the BUY band; the header rounds gain to loss down to one decimal, 4.1 to 1 for 4.17.
| Volatility, annualized | Last 20 sessions | Last 60 sessions | Since the spin |
|---|---|---|---|
| To November 13, 2026 | 59% | 44% | 48% |
At the last 60 sessions' volatility, one standard deviation over a month is about ±13%, or $20.52 to $26.42 from the $23.28 close; about two months in three end inside that range if volatility holds. The median daily move since the spin is 1.5%.
| Results day | Released | Close before | Close after | Move | Times a median day |
|---|---|---|---|---|---|
| August 7, 2026 | Before the open | $20.73 | $19.70 | -5.0% | 3.3× |
| November 12, 2026 | Before the open | $19.92 | $23.13 | +16.1% | 10.7× |
Average move on a results day: 10.5% either way, against a median day's 1.5%. The move is measured from the close before the release to the close of the first session after it.
The debt and the cash
- Net debt fell to $1,649 million at September 30, 2026: $2.0 billion of fixed-rate notes (5.05% due 2029, 5.45% due 2031, 6.05% due 2036) less $351 million of cash. Nothing is due before 2029, and there is no floating-rate debt outstanding, so the December 2026 rate decision does not change the interest bill.
- The cash plan for the next fourteen months (estimates):
| Amount | |
|---|---|
| Cash at September 30, 2026 | ~$0.35B |
| Free cash flow, October 2026 to December 2027, base case, after interest | + ~$0.48B |
| Dividends at $0.24 a year | − ~$0.09B |
| Buybacks, the planned range | − ~$0.35B to − ~$0.45B |
| Cash left at the end of 2027 | = ~$0.29B to = ~$0.39B |
Free cash flow from the base case: about $0.04 billion in the fourth quarter of 2026, after the first coupon ($0.36 billion of the year’s $0.40 billion came in the first nine months), and $0.44 billion in 2027 (estimates). The buyback is funded from cash flow without borrowing.
- The S-4 filed on November 12, 2026 registers notes identical to the existing ones, so that holders can swap the privately placed notes for registered ones; it changes neither the amount nor the cost of the debt.
Notes on earlier sections
- The worst-case weight is cut from 30% to 20% and the base raised from 55% to 65%, for the reasons above; the case definitions and the method are unchanged. A change of judgment on new evidence.
- The tests table of October 5, 2026 asked for “buybacks still on track to begin in early 2027”; the program begins before the end of 2026. A business change.
- Stock compensation was reported as 3–4% of revenue on October 14, 2026, from the carve-out years; as a standalone company it ran at 1.9% in the third quarter. The model keeps 3% in the base case until a full year is reported.
- The rating scale changed on October 29, 2026 (BUY now needs an expected return of 25% or more and gain to loss of 3 to 1); the October 14, 2026 bands above used the earlier definitions.
The rating and what to watch
BUY, target $27 → $29. The target is the best-guess value, $29.28. At $23.13 the expected return is +26.6%, just above the +25% that BUY requires, and gain to loss is 4.2 to 1. It is BUY rather than ACCUMULATE because the quarter met every test it was set except new business, and the price still implies a 54% chance of the worst case. The call is at the edge: above $23.42 it becomes ACCUMULATE, with the same target. The worst case keeps 20% because growth that is two-thirds price is exposed to a cheaper rival report and to a car market facing higher rates.
| Action | Level | Reason |
|---|---|---|
| Buy | Below about $23.42 | Expected return 25% or more with gain to loss of 3 to 1 or better |
| Accumulate | $23.42–26.62 | Expected return 10–25% |
| Hold | $26.62–32.53 | Expected return −10% to +10%, around the $29 target |
| Trim | $32.53–39.04 | Expected return −10% to −25% |
| Sell | Above about $39.04 | Expected return below −25% |
| Move the bands up | New business carrying half or more of CARFAX’s growth, 2027 guidance near 8% growth with the margin held, or price increases accepted again for 2027 | The best case’s weight rises |
| Move the bands down | CARFAX growth below 6%, a listing site or large dealer group dropping CARFAX, price concessions to dealers, or used-car sales falling sharply after the December 2026 rate rise | The worst case’s weight rises |
What the fourth-quarter results and the 2027 guidance (about February 2027, date not announced) must show:
| Item | Why it matters | The base case needs |
|---|---|---|
| CARFAX growth, price and new business | Two-thirds of the third quarter’s growth was price | Growth near 8%, with net new business a larger share |
| 2027 guidance | The first full year as a standalone company | Revenue growth near 7%, adjusted EBITDA margin near 40% less about 1.5 points of public-company cost |
| Fourth-quarter margin | Guidance implies about 36.5% | At or above it |
| Free cash flow | The first coupon, about $60 million, is paid on December 15, 2026 | Full-year free cash flow in line with the guidance after interest |
| Buybacks | $350–450 million planned by the end of 2027 | Started before the end of 2026 |
| Used-car market and rates | A rate rise is expected on December 9, 2026 | No sharp fall in used-car retail sales |
| Short interest | 12.65 million shares at October 30, 2026 | Falling after the results |
Update — October 14, 2026: the scenarios, the asymmetry, the money, the debt and where Mobility Global is — BUY, target $27
Written against the October 13, 2026 close of $18.11. Sources: the information statement, the second-quarter 2026 10-Q with the indenture and the credit agreement, the second-quarter results, S&P Global’s Investor Day of May 12, 2026 and IHS Markit’s 10-Ks for the segment’s record in 2020, Cox Automotive and Manheim for used-car sales, and company pages, press reports and job postings for the offices. The analyses below are left as published. This section adds a line-by-line scenario valuation built on October 8, 2026, with a worst case rebuilt today, and the three standard views of the money, the debt and the physical footprint. The rating is unchanged; the target moves from $25 to $27.
The one-line version
At $18.11 the market is pricing something close to a used-car recession followed by CARFAX losing its pricing power, a case worth about $12.92 a share. Built line by line, the base case, CARFAX at 7–8% growth and margins steady, is worth $30.94, and the best case $40.59. Weighted 15% best, 55% base and 30% worst, the shares are worth about $27, an expected return of 49% with $6.70 of probability-weighted gain for each $1 of loss; the price implies a 71% chance of the worst case. A recession alone has not hurt CARFAX much: revenue fell 2% in 2020 and did not slow when used-car sales fell 10% in 2022. The real risk is pricing: about 4 of CARFAX’s 7.4 points of growth this year came from price increases, and Cox has made Experian’s AutoCheck the featured report on Autotrader and Kelley Blue Book. The debt is light and long: $2.0 billion of fixed-rate notes with nothing due before June 2029, and leverage stays under 2.2 times even in the worst case.
How the money moves
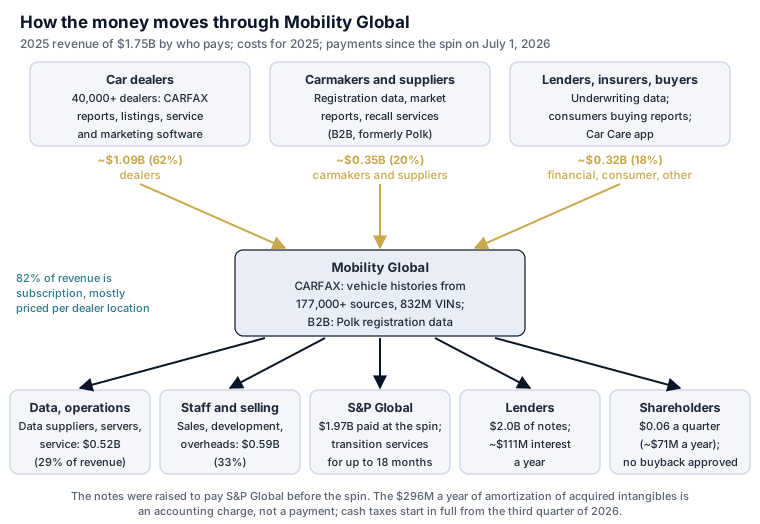
Dealers pay for most of it. About 62% of 2025’s $1.75 billion came from car dealers, mostly as monthly subscriptions priced per dealer location for CARFAX reports, listings and service tools; 20% from carmakers and their suppliers, mainly for the Polk registration data; and 18% from lenders, insurers and consumers. 82% of revenue is subscription. On the cost side the business is mostly people and data: there are no plants, capital spending is about $24 million a year, and the largest non-cash charge, $296 million a year of amortization of intangibles acquired by IHS Markit and S&P Global, is not a payment to anyone.
No single customer matters much; channels do:
- No customer reached 10% of revenue in 2023, 2024 or 2025, and the company gives no top-customer figures. Its risk factors put about 60% of revenue with dealers and 10% with carmakers.
- The dealer base is spread out. CARFAX has more than 40,000 dealer customers; the largest public dealer groups, with a few hundred stores each, are a small share.
- Most large buyers of used cars show CARFAX.
- Dealer groups: AutoNation, Penske, Hendrick, Sonic’s EchoPark and Group 1 stores.
- Carmakers’ certified pre-owned programs: Ford, GM, Toyota, Stellantis, Hyundai and Volkswagen.
- Carvana, on every car.
- Some show AutoCheck instead: CarMax, and the certified programs of Honda, Mazda and Porsche.
- The listing sites have moved to AutoCheck. Autotrader, Cars.com, Kelley Blue Book, CarGurus, TrueCar and Edmunds once displayed CARFAX reports for dealers who subscribed; most now feature AutoCheck. The filings do not mention the change; management said on the August 7, 2026 call that consumers get most reports from dealers' own sites and from carfax.com.
Where each $100 of revenue went, 2025, as if standalone (2025 carve-out results with standalone interest and taxes; estimates marked in the text). The add-back line reverses transaction costs, severance and stock compensation, as the company’s adjusted EBITDA does; depreciation and the $296M of amortization of acquired intangibles are left out because neither is a cash cost. In the first half of 2026 free cash flow was about $19 per $100, with almost no interest yet and taxes settled through S&P Global; the full coupon starts in the third quarter. Source: the information statement and the second-quarter 2026 10-Q; per-$100 figures are calculations.
As a standalone company, about $22.60 of each $100 of revenue becomes free cash flow (an estimate), after interest on the notes and full cash taxes. The first half of 2026 showed about $19, with almost no interest and with taxes still settled through S&P Global; the full coupon and standalone taxes arrive from the third quarter.
The debt, tranche by tranche
All of the debt was raised to pay S&P Global: $2.0 billion of notes issued on May 29, 2026 funded a $1.97 billion payment to S&P Global before the spin.
| Tranche | Amount ($M) | Rate | Matures | Repaying early | Security | Notes |
|---|---|---|---|---|---|---|
| 5.050% notes | 650 | 5.050% fixed | June 15, 2029 | Make-whole (Treasuries + 0.15%); par from May 15, 2029 | Senior unsecured | |
| 5.450% notes | 650 | 5.450% fixed | June 15, 2031 | Make-whole (T + 0.20%); par from May 15, 2031 | Senior unsecured | |
| 6.050% notes | 700 | 6.050% fixed | June 15, 2036 | Make-whole (T + 0.25%); par from March 15, 2036 | Senior unsecured | |
| Total drawn | 2,000 | 5.53% (all fixed) | ||||
| Five-year revolving credit | $500M (plus a $250M accordion) | SOFR + 1.000–1.625% by rating; 0.08–0.20% on the unused amount | July 1, 2031 (two one-year extensions possible) | Senior unsecured | Undrawn at June 30, 2026 |
All three tranches are senior unsecured notes issued on May 29, 2026; none amortizes. The $2.0 billion they raised went to S&P Global as a special cash payment of $1.97 billion before the spin. Interest is paid each June 15 and December 15, the first on December 15, 2026. No interest-rate swaps are disclosed. Source: the second-quarter 2026 10-Q, Note 4, the first supplemental indenture and the credit agreement of May 6, 2026. As of June 30, 2026.
Principal due by year, including scheduled amortization. Nothing is due before June 2029; the three maturities are spread over seven years.
Mobility Global can repay the two nearer maturities from its own cash, even in the worst case. Comparing the cash available by June 2031 with the notes due in 2029 and 2031 (estimates):
| Base case | Worst case | |
|---|---|---|
| Free cash flow, July 2026–June 2031 | $2.58B | $1.84B |
| Dividends at $0.06 a quarter | − ~$0.36B | − ~$0.36B |
| Cash at June 30, 2026 | + ~$0.19B | + ~$0.19B |
| Available to repay debt | = ~$2.41B | = ~$1.67B |
| Notes due June 2029 and June 2031 | − $1.30B | − $1.30B |
| Cash left after repaying them | = ~$1.11B | = ~$0.37B |
In the base case the cash left by mid-2031 also covers the $0.70 billion due in 2036, before any buybacks. In the worst case it covers about half, with five more years to find the rest. The tax agreement with S&P Global limits buybacks to open-market purchases below 20% of the shares until July 1, 2028, and no buyback has been authorized.
Interest expense, 2026–2031
All the debt is fixed-rate, so interest is set until the first maturity. There are no swaps and the revolver is undrawn (all figures estimates, $ millions):
| $ millions | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 |
|---|---|---|---|---|---|---|
| 5.050% notes, June 2029 | $19 | $33 | $33 | $15 | ||
| 5.450% notes, June 2031 | + $21 | + $35 | + $35 | + $35 | + $35 | + $16 |
| 6.050% notes, June 2036 | + $25 | + $42 | + $42 | + $42 | + $42 | + $42 |
| Revolver fee (0.20% on $500M undrawn) | + $1 | + $1 | + $1 | + $1 | + $1 | + $1 |
| Issuance costs written off over the term (non-cash) | + $2 | + $3 | + $3 | + $3 | + $3 | + $3 |
| Interest expense, maturities repaid from cash | = ~$67 | = ~$114 | = ~$114 | = ~$97 | = ~$82 | = ~$62 |
2026 runs from the May 29, 2026 issue date. Source: model in the site’s analysis files, from the indenture and the credit agreement.
What refinancing would cost instead (interest expense, $ millions, with the 2029 and 2031 notes refinanced at maturity):
| Refinancing rate | 2029 | 2030 | 2031 | 2027–2031 | Change against repaying |
|---|---|---|---|---|---|
| Repaid from cash | $97 | $82 | $62 | $469 | |
| 5% | $114 | $114 | $112 | $569 | + $100 |
| 6% | $118 | $121 | $122 | $589 | + $120 |
| 7% | $121 | $127 | $132 | $609 | + $140 |
| 8% | $125 | $134 | $142 | $629 | + $160 |
Rates do not matter before 2029. After that, refinancing both tranches at 8% instead of 5% would cost about $30 million a year by 2031, about $0.08 a share after tax.
| Covenant | Limit | Now | Room | Protects |
|---|---|---|---|---|
| Total net leverage (net debt, with all unrestricted cash netted, over the last four quarters’ EBITDA as the agreement defines it) | 3.50× at each quarter end from September 30, 2026; 4.00× for four quarters after an acquisition of $500M or more | ~2.45× at June 30, 2026 (an estimate; first test September 30, 2026) | EBITDA could fall ~30%, or net debt rise ~$780M | Revolver only |
| Interest coverage | None | — | — | — |
| Secured debt and sale-leasebacks | Secured and sale-leaseback debt capped at 7.5% of total assets unless the notes are secured equally | No secured debt | Wide | Notes |
| Change of control | Notes: 101% repurchase only if control changes and the rating falls below investment grade at every agency. Revolver: default if anyone acquires 35% of the votes | — | — | Notes; revolver |
| Buybacks and mergers (tax matters agreement with S&P Global, not the debt) | For two years after July 1, 2026: buybacks only in the open market and below 20% of the shares in total; limits on mergers and share issues | No buyback authorized; dividend of $0.06 a quarter (~$71M a year) | Restrictions end July 1, 2028 | Shares |
No credit ratings are disclosed in the filings; the revolver margin steps with the Moody’s and Fitch ratings. Neither the notes nor the revolver restrict dividends.
The one covenant has wide room in every case. Net debt has to stay under 3.50 times EBITDA from September 30, 2026. On the scenarios, with free cash flow after dividends kept as cash, leverage peaks at about 2.2 times at the end of 2026 and 2027 in the worst case, when EBITDA falls to about $625 million, and is about 1.0 times by 2028 in the base case. It would take EBITDA about 30% below today’s to breach it before any debt is repaid.
Where Mobility Global is
Physically, Mobility Global is a set of leased offices and one data centre. The filings name only the leased headquarters in Centreville, Virginia, and say the company leases offices in six U.S. locations and abroad; the sites below come from company pages, press reports and its job postings. Its about 3,500 employees are 68% in the U.S. and Canada, 17% in Asia, 13% in Europe and 2% in Latin America; 83% of revenue is from the U.S.
North America: the headquarters in Virginia, the CARFAX technology centre in Missouri where the company was founded, CARFAX Canada in London, Ontario, and the B2B offices in Michigan and New York. Click a point for details. Map data © OpenStreetMap contributors. Source: the information statement (the leased Centreville headquarters and employees by region) and, for the other sites, company pages, press reports and the company’s job board; coordinates from OpenStreetMap. As of October 14, 2026.
All sites are leased offices; the filings give no addresses beyond the headquarters. Several sites are located only to the city, from the company’s job postings; B2B staff abroad may still sit in S&P Global offices under the transition agreement. Click a point for details. Map data © OpenStreetMap contributors. Source: the information statement (the leased Centreville headquarters and employees by region) and, for the other sites, company pages, press reports and the company’s job board; coordinates from OpenStreetMap. As of October 14, 2026.
The asset is the data, and it is gathered from everywhere. CARFAX draws on more than 177,000 sources, among them 92,000 dealers and service shops, 6,300 police agencies, state motor-vehicle departments and 36 carmakers' certified pre-owned programs, and holds 38 billion records on 832 million vehicles. Abroad, CARFAX is established in Canada and has launched in Spain and Italy, with Germany and France next; the B2B segment reports on vehicle markets in about 100 countries. The physical footprint is small and cheap to move, so the risks to the business are in its data supply and its distribution, discussed below.
The scenarios and the asymmetry
The scenarios were built line by line on October 8, 2026, from CARFAX and B2B revenue through margins, stock compensation, cash taxes and free cash flow, and valued on the August 27, 2026 method (an 8.5% discount rate and 2.75% long-run growth). They were held back until the third-quarter results; they are published now because the price sits near the old worst case, which has been rebuilt.
| Best | Base | Worst | |
|---|---|---|---|
| What has to happen | CARFAX growth returns to 10–11%, margins widen | CARFAX grows 7–8%, B2B 4.5–5%, margins steady | A 2027 used-car recession, then CARFAX loses its pricing power |
| CARFAX growth, 2027–2030 | 9–11% a year | 7–8% | −4% in 2027, then 2–3% |
| B2B growth, 2027–2030 | 6% | 4.5–5% | −6% in 2027, then 2–3% |
| Adjusted EBITDA margin, 2030 | 42% | 40% | 34% |
| Stock compensation | 2% of revenue | 3% | 4% |
| Long-run growth | 2.75% | 2.75% | 2.0% |
| Value per share | $40.59 | $30.94 | $12.92 |
| vs $18.11 | +124% | +71% | −29% |
The worst case was rebuilt as a stress test. The October 8, 2026 worst case, slower growth with margins slipping, was worth $19.12, above today’s price, so it could not explain the price. Four stresses were run (estimates):
| Stress | What it assumes | Value | vs $18.11 | EV / 2026 EBITDA |
|---|---|---|---|---|
| October 8 worst case | CARFAX ~4% and B2B 2% growth, margins down 0.5 point a year | $19.12 | +6% | 10.0× |
| Used-car recession | 2027: CARFAX −3%, B2B −6%, margins down 1–2 points; recovery from 2028 | $21.64 | +19% | 11.0× |
| CARFAX loses its pricing power | Both segments grow 3% a year; margin down about 5 points by 2030; long-run growth 2% | $15.81 | −13% | 8.7× |
| Both (the worst case) | The 2027 recession, then the loss of pricing power | $12.92 | −29% | 7.5× |
A used-car recession alone does little lasting damage. U.S. used-vehicle sales fell about 20% from 2005 to 2009, 34% at the worst of April 2020 and 10% in 2022. The business that is now Mobility Global grew in 2022, and in 2020 its revenue fell only 2% for the year and 18% in the worst quarter, when dealers were given temporary price relief and some cancelled; its margin rose that year. About 80% of CARFAX revenue is subscriptions priced per dealer location, so dealer closures and price concessions matter more than the number of cars sold; franchised dealers fell about 15% from 2008 to 2010.
The loss of pricing power is the case with evidence behind it now. In the first half of 2026 about $36 million of the $64 million of revenue growth came from price increases and about $20 million from new business, so roughly 4 of the 7.4 points of growth were price. In June 2025 Cox Automotive made Experian’s AutoCheck the featured history report on Autotrader and Kelley Blue Book, and other marketplaces have since dropped CARFAX tie-ins; cheap reports built on the federal title database sell for $3–10 against CARFAX’s $44.99. The CARFAX bundle launched in late 2025 lengthened sales cycles and was reversed, and 2026 revenue guidance was cut in August. Against this, the data set is unmatched, renewals held through 2020, and no carmaker or dealer-software company has been found building a rival history product. The combined worst case, at 7.5 times EBITDA, sits at the low end of the one published bear case, $12–14 at 7–8.5 times.
How CARFAX reaches the buyer, and how much the lost listing sites matter:
- Listing sites are where people shop, but dealers are where CARFAX reaches them.
- 77% of used-car buyers used a listing site while shopping, and 60% visited dealers’ websites (Cox Automotive, 2025). No independent figure shows the share of sales that start on a listing site.
- Dealers show CARFAX reports about 28 million times a month, online and in showrooms, against 23 million monthly visitors to carfax.com and its app (company figures). Carvana shows CARFAX on every car.
- The listing sites’ switch to AutoCheck cost CARFAX free exposure to shoppers; the sites were not paying customers.
- Search still favours the brand.
- About 1.5 million Google searches a month are for “carfax”, against tens of thousands for AutoCheck.
- carfax.com had about 52 million visits in September 2026, more than any listing site; about half are report lookups.
- Google ended its free car listings, which carried a history-report link, in November 2025, for every report brand.
- AI assistants are small so far.
- 12–19% of buyers used an AI tool while shopping in 2025; AI referrals are under 1% of Cars.com’s traffic.
- No published study shows which report brand the assistants recommend.
- Cheap reports for screening, CARFAX for the sale: partly.
- For: dealers describe AutoCheck, free at the Manheim and OPENLANE auctions, as the tool for buying inventory and CARFAX as the report shown to retail buyers; Experian sells AutoCheck to dealers as a second report alongside CARFAX, and its survey found 90% of buyers want more than one.
- Against: no lender, insurer or law requires CARFAX (California requires a federal-database report); dealers that dropped CARFAX in 2012–2014 reported few customers asking for it.
- In the numbers so far, nothing has moved. CARFAX’s non-subscription revenue, which includes reports bought by consumers, grew about 10% in 2025 and in the first half of 2026, after Autotrader and Kelley Blue Book switched. The risk is that dealers find they can drop or bargain down a subscription without losing sales.
The largest used-car sellers, and the report each shows buyers:
| Seller | Used retail units, 2025* | Latest quarter | Share of US used retail, 2025 | Average price | Market value, Oct 13, 2026 | Report shown |
|---|---|---|---|---|---|---|
| CarMax | 780,684 | 227,391 (Jun–Aug 2026) | 3.8% | $26,121 | $7.2B | AutoCheck |
| Carvana (fully online) | 596,641 | 197,325 (Apr–Jun 2026) | 2.9% | $24,365 | ~$62B | CARFAX |
| Lithia and Driveway (incl. UK, Canada) | 425,381 | 106,114 | 2.1% (U.S. ~1.6%) | $28,118 | $6.3B | CARFAX |
| AutoNation | 263,284 | 63,428 | 1.3% | $27,609 | $5.1B | CARFAX |
| Group 1 (incl. UK) | 234,906 | 53,469 | U.S. ~0.8% | $30,657 | $2.8B | Not confirmed |
| Penske (incl. UK) | 226,301 | 59,070 | U.S. ~0.7% | $39,510 | $12.9B | CARFAX (CarShop) |
| Asbury | 143,126 | 33,098 | 0.7% | $31,788 | $3.0B | Not found |
| Sonic: franchised + EchoPark | 104,202 + 67,636 | 26,444 + 19,601 | 0.8% | ~$28,000 | $1.9B | CARFAX at EchoPark |
| DriveTime (private) | ~70,000–75,000 (estimate) | ~0.35% | private | AutoCheck | ||
| Vroom; Shift | Left online retail in January 2024; bankrupt in October 2023 | 0% |
*CarMax’s year ends in February 2026. Units, revenue and prices from the companies’ earnings releases; shares are calculations against about 20.4 million U.S. used retail sales in 2025, an estimate from Cox Automotive’s forecast; market values are calculations from share counts and the October 13, 2026 closes. Several report choices rest on older partnership announcements or CARFAX’s dealer pages.
- The largest sellers are a small part of the market, and they split between the two reports.
- The nine largest public sellers sold about 2.1 million of the 20.4 million cars, roughly 10%.
- Those showing AutoCheck, CarMax and DriveTime, sold about 0.85 million; the public sellers showing CARFAX sold about 1.35 million. Hertz and Enterprise also show CARFAX.
- CARFAX has the fastest-growing seller. Carvana is the largest fully online seller: its retail units rose 38% in the second quarter of 2026, against 14% at CarMax, where 13% of sales are fully online. On market value Carvana is worth more than CarMax and the dealer groups in the table combined.
- Amazon Autos, which began listing used and certified cars in August 2025, shows AutoCheck; its volumes are not disclosed.
- Independent dealers are the battleground. They retailed about 9.8 million cars in 2025, nearly half the market (National Independent Automobile Dealers Association). They are the most price-sensitive buyers of a subscription that costs hundreds to a few thousand dollars a month, and the chief executive described them on the August 7, 2026 call as CARFAX’s main opportunity; with AutoCheck cheaper, they are also where pricing pressure would show first.
Three weightings, and what the price implies. The standard set, 25 / 50 / 25, and the stress set, 10 / 40 / 50, are the same for every company; the best guess is set from the evidence and drives the target and the two chips at the top of the page.
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $28.85 | +59% | 9.3 to 1 |
| Best guess: 15 / 55 / 30 | $26.98 | +49% | 6.7 to 1 |
| Stress: 10 / 40 / 50 | $22.90 | +26% | 2.8 to 1 |
| What the price implies: 0 / 29 / 71 | $18.11 | 0% | 1.0 to 1 |
The weights are a judgement. All values are estimates from the model.
Why the best guess. The best case needs CARFAX growth to return to 10–11%, and the evidence runs the other way: growth led by price, AutoCheck gaining distribution, and the guidance cut, so it gets 15%, below the standard. The worst case gets 30%, above the standard: the distribution losses have already happened and price is carrying the growth, though the recession half of the case has historically been mild. The base case, CARFAX at 7–8% with renewals intact, takes the remaining 55%. Evidence that would move the weights: CARFAX subscription growth below 6% or a cut to 2027 price increases (worst case up); subscription growth held near 8% with new sales recovering (worst case down).
What the price implies. Holding the base case at its 55% weight cannot reproduce $18.11: even with no weight on the best case, 55% base and 45% worst is worth $22.83. With the best case at zero, the price is matched by the base and worst split that solves
base weight × $30.94 + (100% − base weight) × $12.92 = $18.11
which gives a base weight of ($18.11 − $12.92) ÷ ($30.94 − $12.92) = 29%, and so 71% on the worst case. On single assumptions, the price lies between the October 8 worst case ($19.12) and the loss of pricing power on its own ($15.81): growth near 3–4% with margins falling, permanently.
The asymmetry on the best guess:
| Measure | At $18.11 | What it means |
|---|---|---|
| Expected return (header chip) | +49% | The probability-weighted value, $26.98, against the price |
| Gain to loss (header chip) | 6.7 to 1 | +$10.43 of probability-weighted gain against −$1.56 of loss |
| Expected base-case gain ÷ expected worst-case loss | 4.5 to 1 | +$7.06 against −$1.56: the likely outcome pays for the bad one without the best case |
| Best-case gain ÷ worst-case loss | 4.3 to 1 | +$22.48 against −$5.19 |
| Base-case gain ÷ worst-case loss | 2.5 to 1 | +$12.83 against −$5.19 |
How the measures are calculated. Gain = case value − price; loss = price − case value. Weights are the best guess: 15% best, 55% base, 30% worst.
| Measure | Formula | At $18.11 |
|---|---|---|
| Expected return | (15% × best + 55% × base + 30% × worst) ÷ price − 1 | ($6.09 + $17.02 + $3.88) ÷ $18.11 − 1 = +49% |
| Gain to loss | (15% × best gain + 55% × base gain) ÷ (30% × worst loss) | ($3.37 + $7.06) ÷ $1.56 = 6.7 |
| Expected base ÷ expected worst | (55% × base gain) ÷ (30% × worst loss) | $7.06 ÷ $1.56 = 4.5 |
| Best ÷ worst | best gain ÷ worst loss | $22.48 ÷ $5.19 = 4.3 |
| Base ÷ worst | base gain ÷ worst loss | $12.83 ÷ $5.19 = 2.5 |
| Price-implied base weight, best at zero | (price − worst) ÷ (base − worst) | ($18.11 − $12.92) ÷ $18.02 = 29% |
The header chips are green at +25% or more and 3 to 1 or better, blue at +10–25% and 2–3 to 1, orange at 0–10% and 1–2 to 1, and red below zero and below 1 to 1. On the best guess, expected return is green below $21.59, blue up to $24.53 and orange up to $26.98; gain to loss is green below $21.71, blue up to $23.74 and orange up to $26.98. Both are red above $26.98.
| Change to the base case, one at a time | Value | Change |
|---|---|---|
| A 2027 used-car recession, then the base path | $26.12 | −$4.82 |
| Discount rate 9.0% | $27.81 | −$3.13 |
| Segment margins falling 0.5 point a year | $28.24 | −$2.69 |
| Long-run growth fading to 2.5% | $28.40 | −$2.54 |
| Terminal growth 2.0% | $28.67 | −$2.26 |
| CARFAX growth 2 points lower each year to 2030 | $28.77 | −$2.17 |
| Stock compensation 4% of revenue | $29.92 | −$1.02 |
| CARFAX growth 2 points higher each year to 2030 | $33.22 | +$2.28 |
| Discount rate 8.0% | $34.67 | +$3.73 |
No single change takes the base case near the price. The largest, a 2027 recession, costs about $5 a share; reaching $18 takes several of these together, which is what the worst case does.
Short interest and volatility
The tables below show how much of the stock is sold short and how much the price moves. They are inputs to the weights above, and the tables update with the nightly data.
| Report | Settled | Short | % float | % outst. | Days to cover |
|---|---|---|---|---|---|
| First after the spin | Jul 15, 2026 | 5.54M | 1.9% | 1.9% | 1.0 |
| Lowest since the spin | Jul 31, 2026 | 5.06M | 1.7% | 1.7% | 1.1 |
| Latest | Oct 30, 2026 | 12.65M | 4.3% | 4.3% | 3.3 |
The latest share of float is higher than 7 of the 7 earlier reports since the spin. Short interest in shares, with its share of the float and of shares outstanding. FINRA settlement dates; figures are published about eight business days later. Days to cover is short interest divided by average daily volume, as reported by FINRA. Float and shares outstanding on or before each date, from this site's daily share records and the company's filings.
Short interest is low and rose at the end of September 2026, to 7.46 million shares, about 2.5% of the float, from 5.70 million two weeks earlier; days to cover is 1.7. Three and a half months after the spin some of it may still be hedging against S&P Global shares. It is too small to weigh on the stock or to change the weights; the October 15, 2026 figure, published in late October 2026, will show whether the late-September build continued.
| Volatility, annualized | Last 20 sessions | Last 60 sessions | Since the spin |
|---|---|---|---|
| To November 13, 2026 | 59% | 44% | 48% |
At the last 60 sessions' volatility, one standard deviation over a month is about ±13%, or $20.52 to $26.42 from the $23.28 close; about two months in three end inside that range if volatility holds. The median daily move since the spin is 1.5%.
| Results day | Released | Close before | Close after | Move | Times a median day |
|---|---|---|---|---|---|
| August 7, 2026 | Before the open | $20.73 | $19.70 | -5.0% | 3.3× |
| November 12, 2026 | Before the open | $19.92 | $23.13 | +16.1% | 10.7× |
Average move on a results day: 10.5% either way, against a median day's 1.5%. The move is measured from the close before the release to the close of the first session after it.
There has been one results day: the August 7, 2026 release cut the year’s revenue guidance and the stock fell 5.0%, about three times a median day’s move. The November 12, 2026 results are the first full quarter as a standalone company, with full interest and taxes, and the first test of whether CARFAX’s new sales have recovered since the bundle was reversed.
What it means for the rating
BUY, target $25 → $27. The target is the best-guess value, $26.98. The October 5, 2026 target of $25 rested on a single valuation; the scenarios put the base case at $30.94, and the target sits below it because 30% of the weight is on the worst case. Both chips are green at $18.11, and even the stress weighting, half the weight on the worst case, gives an expected return of 26%. The rating is BUY and not higher conviction because the risk to CARFAX’s pricing is real and current, and the third-quarter results are the first chance to see whether it is showing up in subscriptions.
| Action | Level | Reason |
|---|---|---|
| Buy | Below about $21.60 | Both chips green: expected return above 25% and gain to loss above 3 to 1 |
| Hold | $21.60–27 | Below the target, with a smaller margin for the worst case |
| Trim | Above $27 | The target; beyond it the price assumes less weight on the worst case than the evidence supports |
| Move to HOLD | CARFAX subscription growth below 6%, or a cut to 2027 price increases | The worst case’s pricing path |
| Move to higher conviction | Subscription growth near 8% with new sales recovering, and the margin at or above 38.4% in the second half |
The table of what the third-quarter results must show, in the October 5, 2026 update below, stands; the new items are CARFAX price against volume in the growth, any further marketplace changes, and the first full quarter of interest and cash taxes.
Update — October 9, 2026: who has been trading Mobility Global, and why it fell in September 2026
Written against the October 8, 2026 close of $18.08. Sources: Mobility Global’s SEC filings since the spin, including the Schedule 13G filed by BlackRock and a director’s Form 4; S&P Dow Jones Indices’ June 26, 2026 and September 4, 2026 index announcements; FINRA short-interest and off-exchange volume data; managers' Forms 13F for June 30, 2026 and funds’ Forms N-PORT; and closing prices for the stock and its peers. The analyses below are left as published. The rating and target are unchanged; this section is about the trading, not the valuation.
The one-line version
Most of September 2026’s fall was the sector, not the company. Mobility Global held steady through mid-September 2026 while data stocks sold off, then fell 15.7% in the second half of the month alongside auto retailers and online car marketplaces, which fell 12.2%. No company news, index change, block trade or rise in short selling explains it.
Who sold cannot yet be named. Every route that would identify a seller quickly comes up empty: insiders bought, short interest was flat, and no index forced a trade. That leaves holders who do not have to report until the quarterly filings arrive in mid-November 2026. The forced selling that a spinoff usually suffers came in July 2026, and it is over.
What the price did
| Aug 31 – Sep 15, 2026 | Sep 15 – Sep 30, 2026 | Sep 30 – Oct 8, 2026 | |
|---|---|---|---|
| Mobility Global | +0.2% | −15.7% | +5.4% |
| Information services (S&P Global, Verisk, Moody’s, FactSet, MSCI) | −7.2% | −3.5% | +3.6% |
| Auto retail and marketplaces (CarGurus, Cars.com, CarMax, Carvana, AutoNation) | −2.2% | −12.2% | −2.6% |
| Credit bureaus (TransUnion, Equifax) | −10.5% | −19.3% | +5.9% |
| Russell 2000 | −3.0% | −2.5% | −0.1% |
| S&P 500 | −1.3% | +0.7% | +1.5% |
Closing prices rebased to August 31 = 100. Baskets are equal-weighted: information services (S&P Global, Verisk, Moody's, FactSet, MSCI); auto retail and marketplaces (CarGurus, Cars.com, CarMax, Carvana, AutoNation); credit bureaus (TransUnion, Equifax); Russell 2000 and S&P 500 through their ETFs (IWM, SPY). Source: Yahoo Finance closes.
For the whole of September 2026, the stock fell 15.5%, against 10.5% for the information-services group, 14.3% for auto retail and marketplaces, and 27.7% for the credit bureaus. Mobility Global sits between the two businesses it combines, and it moved with the auto side. The S&P 500 was flat; the 10-year Treasury yield rose from 4.72% to 5.29%.
The two halves of the month had different causes:
- Early September 2026 was a data-stock selloff that skipped Mobility Global. On September 4, 2026 the director of the Federal Housing Finance Agency accused the credit bureaus of “overcharging Americans”, and FICO fell 21%. On September 10, 2026 reports of a finance-focused ChatGPT sent FactSet down 5% and the information-services group with it. Mobility Global rose 2.3% that day.
- Late September 2026 was an auto selloff, and Mobility Global went with it:
| Date | Event | Mobility Global that day |
|---|---|---|
| Sep 17, 2026 | AutoNation warns of weaker affordability and lower third-quarter profit per vehicle; it falls about 10% | +0.6% |
| Sep 18, 2026 | Quarterly options expiry and index share updates; the heaviest volume since August 2026 | −2.8% |
| Sep 21, 2026 | Mobility Global’s own forecast: U.S. vehicle sales will not regain pre-pandemic levels this decade | −1.5% |
| Sep 23, 2026 | Meta’s AI shopping agent hits online marketplaces: CarGurus −5%, Cars.com −6% | −1.1% |
| Sep 24–25, 2026 | Follow-through | −2.9%, −2.6% |
| Sep 28, 2026 | JPMorgan initiates at Neutral, $21 | −0.6% |
| Sep 30, 2026 | CarMax cuts prices to move cars; the Manheim used-car index falls faster than is usual for September 2026 | −3.7% |
Nothing the company said in September 2026 was negative beyond its own industry forecast. At Goldman Sachs’ conference on September 10, 2026 management repeated its medium-term organic growth target of 7.5–10% and its plans for the CARFAX sales reset, buybacks from early 2027 and standalone costs. Since then, Morgan Stanley initiated on October 9, 2026 at Equal-weight with a $19 target, citing margins below peers after stock-based compensation and the failed CARFAX sales change.
Turnover since the spin
Daily volume (bars) and cumulative volume as a share of the 294.8 million shares outstanding (line). Gold bars mark days with a notable event; hover over one to see what happened. Source: this site's daily price archive (Yahoo Finance), through Oct 8, 2026.
| Average daily volume | Share of the company traded | Close | |
|---|---|---|---|
| First three sessions (July 1–6, 2026) | 53.6M | 54.5% | $21.19 → $19.26 |
| July 2026 | 13.0M | 97.2% | $20.38 |
| August 2026 | 4.2M | 30.0% | $20.30 |
| September 2026 | 4.0M | 28.7% | $17.15 |
| October 2026 to the 8th | 4.8M | 9.7% | $18.08 |
| Since the spin | 165.5% |
The forced selling came on the first day, and it was an index trade. S&P Dow Jones Indices announced on June 26, 2026 that Mobility Global would leave the S&P 500, where S&P Global’s holders received it, and join the S&P SmallCap 600 before the open on July 2, 2026. S&P 500 index funds had to sell and small-cap index funds had to buy at the July 1, 2026 close, and 97.8 million shares traded that day. More than half the company changed hands in three sessions.
September 2026’s volume was ordinary. Days of 2.6–5.5 million shares, against about 4 million in August 2026, is the pattern of steady selling, not of one large holder leaving in blocks. The exception, September 18, 2026 at 9.9 million, was the quarterly options-expiry and index share-update day, and only 20% of it traded away from the exchanges, which points to the closing auction rather than a negotiated block. Mobility Global was not on the S&P quarterly change list announced September 4, 2026, nor among MSCI’s August 2026 index changes.
Who has been buying and selling
What the public record rules out:
| Possible seller | The evidence | Verdict |
|---|---|---|
| Insiders | No open-market sales. Director Mark Peek bought 50,000 shares on August 11–13, 2026 at $19.50–19.87, not under a pre-arranged plan. The other Forms 4 are award grants and one tax withholding | Buying, not selling |
| Short sellers | Short interest 5.5 million shares (1.9%) on July 15, 2026, 5.9 million (2.0%) on August 31, 2026, 5.7 million (1.9%) on September 15, 2026; about 1.6 days of volume. The September 30, 2026 figure is not yet published | Flat into the fall |
| Index funds | No index addition or deletion since July 2, 2026 in the S&P or MSCI families | No forced trade |
| A block seller | No reported block trade, secondary offering or Form 144 | None visible |
| A new 5% holder | One Schedule 13G since the spin: BlackRock, 11.3% on July 31, 2026, built largely by its small-cap index funds | A buyer |
What is left is holders who do not have to report yet. Institutions disclose quarter-end positions on Form 13F within 45 days, so September 30, 2026 holdings arrive by about November 16, 2026. Holders between 5% and 10% file a Schedule 13G on the same timetable. Until then the seller can be narrowed but not named.
The likeliest sellers are the holders who received a stock their mandate does not cover. S&P Global is a large-cap financial stock. Mobility Global is a $5 billion company classified by S&P as an industrial, sitting in a small-cap index. Large-cap, financials-sector and growth funds that held S&P Global received it without choosing it, and some are selling over months rather than days. Dividend-growth index funds are another candidate: Vanguard’s Dividend Appreciation fund held 1.7 million shares on July 31, 2026, and Mobility Global has paid a dividend only since August 2026.
Who held it on day one
Holders of S&P Global on June 30, 2026 received one Mobility Global share for each share they held, so their 13F positions are Mobility Global’s opening shareholder list. The largest, from a review of about 55 managers’ filings (not a complete ranking):
| Holder | Shares received | Of the company | Since then |
|---|---|---|---|
| Vanguard | 25.6M | 8.7% | Not yet disclosed |
| BlackRock | 24.0M | 8.1% | 33.6M (11.3%) on July 31, 2026: a buyer, through small-cap index funds |
| State Street | 14.5M | 4.9% | Its S&P 600 fund held 2.7M on October 8, 2026 |
| TCI Fund Management | 14.1M | 4.8% | Not yet disclosed |
| Morgan Stanley | 7.3M | 2.5% | Not yet disclosed |
| Geode | 6.9M | 2.3% | Not yet disclosed |
| Wellington | 5.3M | 1.8% | Not yet disclosed |
| Capital Group | 4.1M | 1.4% | Not yet disclosed |
| Norges Bank | 3.9M | 1.3% | Not yet disclosed |
| Northern Trust | 3.0M | 1.0% | Not yet disclosed |
| Fidelity | 2.7M | 0.9% | Not yet disclosed |
| Goldman Sachs | 2.6M | 0.9% | Not yet disclosed |
| Charles Schwab | 2.4M | 0.8% | Not yet disclosed |
| Wells Fargo | 2.4M | 0.8% | Not yet disclosed |
| Invesco | 2.3M | 0.8% | Its spinoff ETF held 0.4M on July 31, 2026 |
The one active holder to watch is TCI, the largest non-index holder on day one. It runs a concentrated portfolio of large companies, and a position of about $280 million in a small-cap stock is an awkward fit. That is a question, not an inference that it sold: below 5% it has no obligation to report until its third-quarter 13F.
What the mid-November 2026 filings will settle
- Each large holder’s September 30, 2026 position, set against the day-one table above
- Whether anyone has crossed 5%, in either direction
- Short interest on September 30, 2026, due from FINRA within days
The table above will be updated when they arrive.
Which indexes hold it, and which it could join
The largest index-fund holders found are iShares’ S&P SmallCap 600 fund (18.5 million shares, 6.3% of the company, on August 31, 2026), Vanguard’s total-market fund (9.2 million) and Vanguard’s small-cap fund (6.6 million). Which indexes the company is in, and which it moves into, decides when funds like these have to trade.
Where it is now
| Index family | Index | Member | How it is known |
|---|---|---|---|
| S&P Dow Jones | S&P SmallCap 600, since July 2, 2026 | Yes | S&P’s June 26, 2026 announcement; State Street’s S&P 600 fund holdings, October 8, 2026 |
| S&P Dow Jones | S&P SmallCap 600 Value and Growth (S&P splits its weight between the two), S&P Composite 1500, S&P Total Market and Completion, Dow Jones U.S. Total Stock Market | Yes | Fund holdings files and fund filings, July 31 to October 8, 2026 |
| S&P Dow Jones | S&P U.S. Spin-Off Index | Yes | Invesco’s spinoff fund held 0.36 million shares (3.3% of the fund) on July 31, 2026 |
| S&P Dow Jones | S&P 500, S&P MidCap 400 | No | |
| FTSE Russell | Russell 1000 and Russell 3000 | Yes | Russell 1000 index funds hold it (Fidelity’s large-cap value index funds, iShares’ US technology fund); full Russell 2000 replication funds did not on October 8, 2026 |
| FTSE Russell | Russell Top 200 | Probably | Russell adds a spinoff to every index its parent is in, and S&P Global is a Top 200 company; not confirmed from a fund file |
| MSCI | MSCI USA IMI (the all-size index) | Yes | State Street’s MSCI ACWI IMI fund and Fidelity’s MSCI Industrials fund |
| MSCI | MSCI USA Small Cap (the large- and mid-cap MSCI USA is the alternative) | Probably | At $5.1 billion on September 30, 2026 it was below the smallest MSCI USA member ($6.2 billion, MSCI USA fact sheet); MSCI’s August 2026 review made no change |
| FTSE | FTSE Global All Cap / All-World | Yes | Vanguard’s total world fund, July 31, 2026 |
| Morningstar (formerly CRSP) | US Small Cap and Small Cap Value; US Total Market | Yes | Vanguard’s small-cap, small-cap value and total-market funds, August 31, 2026 |
| Dividend growth | S&P U.S. Dividend Growers (Vanguard Dividend Appreciation) | Held 1.7 million shares on July 31, 2026, received from S&P Global | The index requires a long record of rising dividends, and Mobility Global’s first was paid on September 10, 2026; whether the fund still holds it is not yet disclosed |
S&P and MSCI classify it as an industrial; FTSE Russell classifies it as technology, which is why it sits in the iShares US technology fund. The S&P sector funds (XLK, XLI) hold only S&P 500 companies and do not own it.
What could change, and when
The price thresholds below use 294.8 million shares and the close of $18.08 on October 8, 2026 (a market value of $5.33 billion). Average daily volume over the past three months was about 4.3 million shares.
| Index move | The rule | Where Mobility Global stands | Next dates | Likelihood (judgement) |
|---|---|---|---|---|
| Russell Top 200 → Russell Midcap | Spinoffs keep the parent’s indexes until the next reconstitution, then are ranked on their own size (FTSE Russell) | Far below the Top 200; it stays in the Russell 1000 | Size measured October 30, 2026; preliminary list November 13, 2026; effective after the close December 11, 2026 (schedule) | High, if it is in the Top 200 now |
| Russell 1000 → Russell 2000 | Existing members stay in the Russell 1000 within a band around the breakpoint, which was $5.7 billion in June 2026; the smallest Russell 1000 member after banding was $2.7 billion (June 2026 summary) | $5.3 billion, inside the band; the June 2026 lower edge is equivalent to about $9 a share | December 11, 2026; June 2027 | Low: needs the price to roughly halve |
| S&P SmallCap 600 → S&P MidCap 400 | A member migrates when it meets the MidCap 400 size range, $8.0 billion to $22.7 billion (S&P, July 2025), at the committee’s discretion; it does not need to re-pass the profit and liquidity tests | 67% of the minimum; eligible at about $27.10 a share, 50% above the price | Quarterly rebalances effective after the third Friday of December 2026, March 2026, June and September 2027, announced about two weeks before; or at any time to fill a MidCap 400 vacancy left by an acquisition | Low within a year (an estimated 15–20%): the price needs to hold above about $27 |
| S&P SmallCap 600 → S&P 500 | $22.7 billion and up | Equivalent to about $77 a share | Remote | |
| MSCI USA Small Cap → MSCI USA | Moves up when above about 1.5 times MSCI’s US size cutoff, which MSCI does not publish | An estimated $13–14 billion, about $45–47 a share | Review effective December 1, 2026 (announced November 11, 2026); March 2027 | Remote |
| FTSE All-World → FTSE Global Small Cap | FTSE re-ranks a spinoff at the first review after three months of trading; a mid-cap member needs at least 0.04% of the regional index (ground rules) | About 0.01% of the US index | December 2026 review, effective after the close December 18, 2026 | Likely; timing not confirmed |
| Morningstar US Small Cap → Mid Cap | Breakpoint at the 85th percentile of the market, about $30 billion in June 2026 | Equivalent to about $100 a share | Quarterly | Remote |
| Factor and dividend indexes (low volatility, momentum, dividend growth) | Most need 12 months of price history or years of dividend increases | First eligible for the price-based indexes after July 2027 | Not before mid-2027 |
What the moves would mean for trading
These are estimates. The Russell move in December 2026 is the one that is close to certain, and it is small: Russell Midcap and Russell 2500 funds buy, a few Top 200 funds sell, and the net is estimated at 1–1.5% of the shares, about one day of volume, crossed at the December 11, 2026 close. A migration to the S&P MidCap 400 would be a larger trade but a balanced one: S&P 600 funds would sell an estimated 30–40 million shares, seven to nine days of volume, and S&P 400 funds would buy about the same at the same close. FTSE’s move to the small-cap index would mean small net selling, an estimated 0.1–0.3% of the shares.
Which way the December 2026 trades go. December 11, 2026 should be net buying, provided Mobility Global is in the Russell Top 200 now: Russell Midcap funds (iShares’ alone manages about $49 billion), the institutional accounts benchmarked to that index and any Russell 2500 funds buy, against smaller Top 200 funds selling, while funds that track the Russell 1000 itself do not trade. If Russell placed it in the Midcap from the start, little trades that day; the preliminary list on November 13, 2026 will show which. December 18, 2026 tilts slightly toward selling: FTSE’s large- and mid-cap All-World funds sell and its small-cap funds buy, for a small net sale, while the largest FTSE holder, Vanguard’s total world fund, tracks the all-cap index and does not trade. The same day carries S&P’s quarterly share and float update, close to nil for this stock, and the quarterly options expiry, which adds volume without a direction (September 18, 2026, the last expiry, was the heaviest day since August 2026, with no seller found behind it).
The price effect of index buying usually comes before the effective date: traders buy expected additions once the preliminary list is out and sell to the index funds at the close on the day, and the price can drift back afterward. For Mobility Global that window runs from November 13 to December 11, 2026, which overlaps the third-quarter results on November 12, 2026. This is the general pattern for index additions and has not been measured for this stock.
For the rating this changes nothing. A rise toward the $25–28 range would bring the S&P MidCap 400 into view as a further source of demand.
Two notes on earlier sections
- The index treatment. The June 30, 2026 entry said S&P 500 index treatment would follow the distribution. S&P Dow Jones Indices had announced on June 26, 2026 that Mobility Global would join the S&P SmallCap 600, not stay in the S&P 500, effective July 2, 2026, and it classified the company as an industrial rather than a financial. That was the forced trade of the first day.
- What moved the stock in September 2026. The October 5, 2026 update attributed the fall to the three analyst initiations and to “a broader decline in small companies as Treasury yields rose”. Both happened, but the larger cause was an auto-sector selloff in the second half of the month: Mobility Global fell 15.7% from September 15, 2026 while the Russell 2000 fell 2.5% and auto retail and marketplaces fell 12.2%.
What it means for the rating
Nothing in the trading changes the case: BUY, target $25, unchanged. A fall that tracks auto stocks during an auto selloff, with no company news, no new short position and a director buying at $19.50, is the market repricing the sector the stock trades with, not information about CARFAX. It does mean the stock now trades as an auto name, and will keep doing so until it reports results that look like a data business. The third-quarter results on November 12, 2026 are the first chance.
Update — October 5, 2026: BUY, target $28 → $25
Written against the October 5 close of $17.59. Sources: the second-quarter earnings call (August 7), the Q2 Form 10-Q, Mobility Global’s SEC filings since August 20 (insider Forms 4 only), and the three analyst initiations linked below. The August 27 analysis is left as published; this section adds what it left out and re-runs the valuation.
The one-line version
Nothing has happened to the business since August 27, but the valuation needs two corrections, and both cut the target. The August analysis did not report that CARFAX’s bundled-sales strategy had failed and been reversed, or that 2026 revenue guidance had been lowered because of it. And it valued the company on free cash flow without deducting stock-based compensation, which management is reported to be raising toward 3–4% of revenue.
Re-run with stock-based compensation counted as the cost it is, the base case falls from $29.20 to $25. At $17.59 that is still 42% upside, the stock now trades inside our own bear-case range, and the third-quarter results in November are the test of which one is right.
Rating: BUY, maintained · Target $25 (from $28) · range $21–28 · Grade: A (4.35)
What moved the stock
Mobility Global has said and filed nothing material since August 27. Its only SEC filings are Forms 4 dated September 1: annual stock grants to the CEO and eight directors and one tax withholding by the chief legal officer, with no open-market purchase or sale. Its press releases were product news and its own auto-industry forecast.
What arrived instead was coverage. Three banks initiated after the post-spin quiet period, all neutral, all below our target:
| Date | Firm | Rating | Target | The argument |
|---|---|---|---|---|
| Sep 1 | Barclays | Equal-weight | $23 | Execution. CARFAX should grow high-single to low-double digits, B2B mid-single digits with lower recall activity. Margin expansion above 50 basis points “not expected to begin until 2028”. Values the company at 11× 2027 adjusted EBITDA less stock-based compensation |
| Sep 9 | Evercore ISI | In Line | $22 | CARFAX “missed the 2026 pricing window” while cheaper AI tools spread. Expects about 8% organic growth in 2027, roughly 4 points of it from price |
| Sep 28 | JPMorgan | Neutral | $21 | A near-term margin reset as $20–25 million of public-company costs arrive. Stock-based compensation rising toward about 3–4% of revenue |
The common thread is not a disagreement about the asset. None disputes it: the reports cite the 71% gross margin, revenue about 80% on subscription, and (JPMorgan) CARFAX’s place as the system of record for vehicle history. They want evidence of standalone execution first. The stock fell from $20.30 at the end of August to a low of $17.15 on September 30, through all three initiations and a broader decline in small companies as Treasury yields rose.
What the August 27 analysis left out
1. CARFAX’s go-to-market change failed, and was reversed. Late in 2025 CARFAX stopped selling its three core dealer products (Advantage, Listings and Service Loyalty) separately and began selling them together as a “lifetime dealer package”. On the August 7 call, management said the bundle had lengthened sales cycles and slowed adoption, that the change had not delivered the benefits expected, and that from June CARFAX had gone back to selling the products individually, letting dealers build to the full package over time. The same call lowered 2026 revenue guidance to $1,870–1,885 million, +6.9–7.7%. The August analysis quoted that range without saying it was a cut, and said nothing in the quarter argued against CARFAX’s 8% growth. It should have reported the reset: it is the most direct risk to that 8%.
What it means. CARFAX subscription revenue still grew about 8% in the second quarter, so the damage so far is to new sales, not to the installed base. Evercore’s reading is that the transition also cost CARFAX its usual 2026 price increase. That is the analyst’s interpretation, not a management statement. If it is right, 2027 gets that price back, about 4 points of growth on Evercore’s estimate, which would make 2026 a pause rather than a trend.
2. Stock-based compensation was not deducted. The August valuation treated free cash flow as “the only honest measure”, and free cash flow adds stock-based compensation back as a non-cash item. It was small: $9 million in the first half, about 1% of revenue. JPMorgan reports that management is raising it toward 3–4% of revenue, about $56–75 million a year. That figure does not yet appear in a company filing. Either way it is a real cost to shareholders, paid in dilution rather than cash, and a valuation built on free cash flow has to deduct it. Barclays values the company on EBITDA less stock-based compensation for the same reason.
The valuation at a glance
At $17.59: market capitalization $5.19 billion on 294.8 million shares, net debt $1.80 billion at June 30, enterprise value $6.98 billion.
| Measure | Basis | Multiple | Yield | At $20.55 (August 26) |
|---|---|---|---|---|
| EV / adjusted EBITDA | 2026 guidance midpoint ($752.5M) | 9.3× | 10.4× | |
| 2025 actual ($711M) | 9.8× | |||
| 2027 estimate ($790M) | 8.8× | |||
| 2026, less stock-based compensation at 3% of revenue | 10.0× | |||
| Price / free cash flow | 2025 free cash flow ($461M) | 11.3× | 8.9% | 13.1× (7.6%) |
| less stock-based compensation at 3% (≈$53M) | 12.7× | 7.9% | ||
| Price / earnings | GAAP, normalized for standalone interest (≈$0.52) | 33.8× | 39.5× | |
| Cash earnings: GAAP plus after-tax amortization of acquired intangibles (≈$1.27) | 13.8× |
- About 9.3× EBITDA is cheap for this kind of business. The information-services median is about 14.5×. The three September initiations value it near 11× 2027 EBITDA less stock-based compensation, which gives $21–23, and the stock trades below that.
- Free cash flow is the measure that counts here, and an 8.9% yield (7.9% after stock-based compensation) is high for a business with 82% subscription revenue. Use 2025 as the run-rate, not 2026. First-half 2026 free cash flow was $177 million, down 21%, carrying about $50 million of one-time separation costs and the standalone cost load as it arrives.
- The GAAP multiple of 34× is an accounting artifact. It is struck after $296 million a year of amortization on intangibles from S&P Global’s purchase of IHS Markit, which costs no cash and is not replaced. Add it back, after tax, and the stock trades at about 14× cash earnings, in line with its free cash flow multiple. The cash-earnings figure is our calculation; Mobility Global does not publish one.
Every multiple has compressed since August, and all of it is price. Expected EBITDA and free cash flow have not moved: the stock has fallen 14%.
The valuation, re-run
The model is unchanged (explicit period 2027–2040, revenue growth easing from 6.5% to 3.5%, a 39.0% margin in 2027 recovering to 40.5%, 62% conversion of adjusted EBITDA to free cash flow), except that stock-based compensation is now deducted at 3% of revenue, the low end of JPMorgan’s range.
Value per share, at 62% conversion, stock-based compensation at 3% of revenue:
| Terminal adj. EBITDA margin | WACC 8.0% / g 3.0% | WACC 8.5% / g 2.75% | WACC 9.0% / g 2.5% |
|---|---|---|---|
| 42.0% | $30.21 | $25.99 | $22.71 |
| 40.5% — our estimate | $29.04 | $24.98 (was $29.20) | $21.83 |
| 39.0% | $27.86 | $23.97 | $20.94 |
| 37.5% | $26.69 | $22.96 | $20.06 |
| Sensitivity, at 40.5% margin and 8.5% | Value per share |
|---|---|
| Stock-based compensation at 1% of revenue (today’s level) | $27.79 |
| at 3% (base) | $24.98 |
| at 4% | $23.57 |
| Conversion of 58%, at 3% | $22.70 |
| Conversion of 66%, at 3% | $27.26 |
Each point of revenue paid in stock is worth about $1.40 a share. Even at today’s 1%, the August base case was about $1.40 too high.
Cross-checks, on adjusted EBITDA less stock-based compensation: 2027E $790 million less about $60 million at 3% of revenue: 12× gives $23.63, 13× $26.10. The information-services median of about 14.5× on 2026 gives $28.15.
Price target: $25 · range $21–28 · BUY, maintained
$25 is 42% above the October 5 close of $17.59. The range runs from the 9% discount rate case ($21.83) to the peer median ($28.15).
Interest rates
Rates reach this valuation through the discount rate only. The model values the whole business before interest and then subtracts net debt, and all three of Mobility Global’s debt tranches carry fixed rates with nothing due before 2029. So higher interest rates do not change its cash flows. They change what those cash flows are worth today.
And the discount rate has moved. The 8.5% was set on August 27, with the 10-year Treasury yield near 4.8%. It is now 5.31%, about half a point higher. Equity is about three-quarters of the company’s capital and the existing debt is fixed, so a full pass-through would put the cost of capital at about 8.9–9.0%:
| Discount rate (terminal growth) | Value per share | Upside vs $17.59 |
|---|---|---|
| 8.5% (2.75%), base | $24.98 | +42% |
| 8.75% (2.75%) | $23.60 | +34% |
| 9.0% (2.75%) | $22.32 | +27% |
| 9.0% (2.5%) | $21.78 | +24% |
| 9.5% (2.75%) | $20.07 | +14% |
Each quarter point on the discount rate is worth about $1.30 a share, about 5%, because half the value sits in the terminal value. We keep 8.5% as the base: a discount rate should reflect long-run conditions rather than a month’s move in Treasury yields. But the table matters. If yields stay half a point higher, the upside narrows from about 42% to about 25%, and the investment case rests more heavily on the business delivering than on the price.
The bear case, revisited
The August analysis put the thesis-failure value at $18–20: organic growth below 5%, or a 2027 margin below 38%, compressing the multiple to 9–10×. On the same basis with stock-based compensation deducted, that range is $16–19 (9× gives $16.20, 10× gives $18.67). The stock at $17.59 sits inside it. The market is pricing the thesis as already failing, on no data that says it has: the only evidence so far is one quarter of slower new sales at CARFAX, which management has a stated fix for.
That is why the rating stays BUY, and also why conviction is lower than in August. The case now rests on the third quarter showing that the reset worked.
What the third-quarter results (early November) must show
| Line | The test |
|---|---|
| CARFAX subscription revenue | Growth holding near 8%: the installed base is intact |
| CARFAX new sales | Any comment that sales cycles have shortened since the June reversal |
| Adjusted EBITDA margin | At or above the 38.4% the full-year guidance implies for the second half |
| 2027 pricing | Any sign the 2026 price increase returns in 2027 |
| Stock-based compensation | The actual run-rate, against the 3–4% reported |
| Capital returns | Buybacks still on track to begin in early 2027, as promised on August 7 |
What would cut the rating: CARFAX subscription growth below 6%, or a margin below 38% with no sign of the standalone cost load leveling off.
Detailed Post-Spin Analysis — August 27, 2026
Written against the August 26 close of $20.55. Primary sources: the Q2 2026 Form 10-Q (filed 2026-08-07), the Q2 results release, and S&P Global’s FY2025 and FY2023 Forms 10-K for the Mobility segment’s pre-separation record.
This is the complete standing analysis of Mobility Global, consolidating the post-separation work to date into one document. It supersedes the interim Q2 earnings note. The initial assessment of July 31 / August 5 and all pre-separation analyses remain below, exactly as published.
The one-line version
The question is not the multiple. It is whether CARFAX’s 8% growth is durable, and nothing in the first standalone quarter argues against it.
Q2 delivered revenue +7%, adjusted EBITDA +7%, margin held at 43%, and 82% of revenue on subscription. The guidance is where the thesis moves: full-year adjusted EBITDA margin of ~40.1% against 41.8% delivered in the first half implies a second half at 38.4% — disclosed, not a stumble, and almost entirely the standalone cost load arriving.
Four years of segment history say the business is getting better, not worse. S&P Global reported Mobility as a segment from 2022, and the numbers reconcile to Mobility Global’s own within $3M. Revenue went $1,142M → $1,484M → $1,609M → $1,747M, and segment operating profit grew 77% against revenue up 53%. The longer record supports the story here rather than undercutting it, which is not what a pre-separation growth claim usually survives.
The valuation is unusual in a specific way: GAAP earnings are close to meaningless here. Amortization of acquired intangibles runs $296M a year — 16% of revenue — against capital expenditure of about $25M. Free cash flow is the only honest measure, and at 13.1x free cash flow, a 7.6% yield, the market is paying less for this than for any comparable information-services business.
Rating BUY, unchanged. Target $28, from $27.
What the business actually is
Two segments, one of which is the company:
| Segment | Q2 2026 | 1H 2026 | What it is | ||
|---|---|---|---|---|---|
| CARFAX | $312M | +8% | $610M | +8% | Vehicle-history reports, 53M+ car-care users, 40,000+ dealer customers, 100% of the top-40 OEMs. A 40-year data set nobody else holds |
| B2B | $156M | +4% | $313M | +6% | Dealer and financial solutions — underwriting data, dealer software, market intelligence |
| Total | $468M | +7% | $923M | +7% | |
| of which subscription | $383M | +7% | $755M | +8% | 82% of revenue |
| Adjusted EBITDA | $202M | +7% | $386M | +8% | |
| margin | 43% | 41.8% | |||
| Free cash flow | $129M | −21% | $177M | −21% | first-half timing and standalone costs |
CARFAX is two-thirds of revenue and the entire investment case. It grew 8% in both the quarter and the half. B2B grew 4% in the quarter, of which roughly $1M of recall revenue simply moved to the second half.
Ignore the reported EPS line entirely. The prior-year comparative is carve-out accounting with no standalone costs and almost no interest, and the current period carries $148M of intangible amortization per half. The valuation section deals with this properly; for now the point is that neither GAAP earnings nor the year-over-year EPS change tells you anything about this business.
Management Team
| Role | Name | Background |
|---|---|---|
| CEO | Bill Eager | A CARFAX lifer. More than 20 years there, including CEO of CARFAX from 2021 and 17 years running its Dealer Business, before becoming President of S&P Global Mobility in August 2025. Earlier at The Cobalt Group, an automotive digital-retailing company. Villanova; George Mason MBA |
| CFO | Matt Calderone | CFO of Booz Allen Hamilton from October 2022 to January 2025 — a listed company of roughly $11B in revenue. Fifteen years at Booz Allen before that, including Chief Strategy Officer, running strategic finance, FP&A and corporate development. Boston Consulting Group 2007–2010. Maryland; Yale MBA |
| Chief Accounting Officer | Renato Negro | CAO of ESAB Corporation from 2021 to 2026 — itself a 2022 spinoff — so he has closed the books through a separation before. Previously VP, Controller and CAO at Avanos Medical |
| President, CARFAX | Scott Fredericks | At CARFAX since 1997, joining as VP of Marketing and serving as COO from 2022. A US Air Force communications director for a decade before that |
| President, Business Solutions | Joe LaFeir | President of Automotive Insights 2016–2025; before that CIO of R.L. Polk, the automotive-data business that became part of this company. Ernst & Young, then Capgemini consulting |
| Chief Legal Officer | Tasha Matharu | Deputy General Counsel of S&P Global from 2020 and its Corporate Secretary from 2017; earlier an associate at Shearman & Sterling |
This is a deeper bench than the “spun-out division” framing suggests, and one correction is worth making explicitly: the public-company experience is not thin. Calderone ran finance at a listed company several times this one’s size. Negro has taken a company through a separation in exactly this seat. And Eager is not a divisional president who inherited CARFAX — he ran CARFAX itself for four years and worked there for two decades before that.
What the team is short of is a shared track record as a listed company, which is a different and smaller problem, and one the board is well constructed to cover.
The board
Eight directors, and the composition looks deliberately assembled to supply what the management team lacks.
| Director | Background |
|---|---|
| Joseph R. Hinrichs (59) — Chairman | CEO of CSX Corporation 2022–2025, and before that President of Ford’s global automotive business, having run Ford China, Ford Canada and the Americas. Also on Goodyear’s board. A recent large-cap CEO whose career is the automotive industry this company sells into |
| Mark S. Peek (68) | CFO of Workday, before that CFO and Co-President of VMware, and before that Chief Accounting Officer of Amazon. Nineteen years at Deloitte, ten as a partner. Boards of SentinelOne and Trimble. A subscription-software CFO of the first rank — the single most relevant director for a business whose valuation turns on recurring revenue and cash conversion |
| Heather Lavallee (56) | CEO of Voya Financial since 2023, having run its Retirement business. A sitting public-company CEO |
| Monique F. Leroux (71) | Chair and CEO of Desjardins Group 2008–2016 and its CFO before that; an audit partner at Ernst & Young earlier. Boards of Michelin, BCE and Alimentation Couche-Tard. Served on S&P Global’s board 2016–2022 |
| Eric W. Aboaf (61) | Chief Financial Officer of S&P Global — the former parent — since 2025. Previously CFO and Vice Chairman of State Street, and CFO of Citizens Financial |
| Shilpa Ranganathan (48) | Chief Product Officer of Expedia since 2025; sixteen years at Microsoft, latterly Corporate VP of Windows. Consumer product and AI |
| Alexander Taussig (43) | Partner at Lightspeed Venture Partners, formerly co-head of its consumer practice; board of United Rentals |
| William W. Eager | CEO |
Three current or recent chief executives of listed companies, and three former public-company CFOs. For a first-time public-company management team, that is the right shape — and the Chairman’s background is an unusually precise fit: an automotive-industry operator who has also run a listed transport company through a full reporting cycle.
Two directors carry S&P Global connections — Aboaf is the parent’s sitting CFO, and Leroux sat on its board until 2022. That matters less than it would at a separation where the parent kept a stake, because S&P Global distributed 100% and retains none. There is no block of stock to place and no ongoing economic interest to reconcile. The counterpoint is that the parent’s CFO sitting on the board of a company the parent no longer owns is a relationship worth noting even where it is benign.
The financial record — four years by segment
Mobility Global’s own filings show three years. S&P Global reported Mobility as a segment from 2022, which adds a fourth — and, more usefully, a check on whether the two bases describe the same business.
| ($M) | 2022* | 2023 | 2024 | 2025 |
|---|---|---|---|---|
| Revenue — S&P Global segment | 1,142 | 1,484 | 1,609 | 1,747 |
| Revenue — Mobility Global standalone | — | 1,485 | 1,613 | 1,750 |
| difference | $1M | $4M | $3M | |
| Segment operating profit | 213 | 260 | 312 | 378 |
| operating margin | 18.7% | 17.5% | 19.4% | 21.6% |
| Adjusted EBITDA (standalone basis) | — | 598 | 658 | 711 |
| adjusted EBITDA margin | 40.3% | 40.8% | 40.6% | |
| Free cash flow | — | 375 | 412 | 461 |
| FCF margin | 25.3% | 25.5% | 26.3% |
*2022 covers roughly ten months — S&P Global’s merger with IHS Markit closed at the end of February 2022, and the Mobility segment did not exist before it. Segment figures from S&P Global’s FY2023 and FY2025 Forms 10-K; standalone figures from Mobility Global’s own disclosure.
The two bases describe the same business. Revenue differs by $1M in 2023, $4M in 2024 and $3M in 2025 — a rounding difference from intersegment elimination. That is an unusually clean match, and it means the S&P Global segment history can be read as Mobility Global’s own history rather than as an approximation of it.
What four years show
Revenue grew 53% from 2022 to 2025. Segment operating profit grew 77%. Margin went 18.7% → 17.5% → 19.4% → 21.6% — a dip in 2023, then two years of expansion totalling 410 basis points.
It is worth saying plainly, because a longer record more often works against a spun-off business than for it: on four years of segment data, Mobility Global’s economics have been improving. The 2023 dip is consistent with IHS Markit integration costs washing through; everything after it goes the right way.
Adjusted EBITDA margin, by contrast, has been flat at ~40.5% across all three years it is reported. Those two facts together locate exactly where the improvement came from: not from operating leverage on cash costs, but from acquired-intangible amortization becoming a smaller share of a growing revenue base. That distinction matters, and the valuation section returns to it.
Free cash flow margin improved every year — 25.3% → 25.5% → 26.3% — on a business whose capital expenditure is about $25M a year against $1.75B of revenue. This is as asset-light as businesses get.
The one line that goes the wrong way, and it is disclosed
Full-year 2026 guidance is revenue $1,870–1,885M (+6.9–7.7%) and adjusted EBITDA $745–760M at ~40.1% margin.
The first half delivered 41.8%. Full-year guidance of ~40.1% therefore implies a second half at 38.4% — roughly 340 basis points below the half just reported.
That is not a stumble; it is the standalone cost load arriving on schedule. Incremental public-company costs carry a run-rate of roughly 150 basis points against the FY2025 base, and they phase in through the second half rather than appearing at once.
This also reframes the July restatement. That correction moved the reported margin from a fictional ≈60% to an actual 40.6%. The right forward number is lower again — roughly 39%, fully loaded — not because anything deteriorated, but because a standalone company pays for its own back office.
It does mean the margin question is genuinely open until the November print, which is the first quarter carrying a fuller standalone load. Whether ~39% is a floor or a waypoint is the single most important number this company will report this year, and no amount of history settles it — the four-year record was earned under a parent that absorbed these costs.
Where Mobility Global sits in the value chain
CARFAX’s moat is not technology, a brand, or a network effect in the usual sense. It is a forty-year accumulation of records that cannot be re-created at any price, fed by an ongoing flow from sources — DMVs, police reports, service shops, auctions, insurers — that took decades of individual relationships to assemble.
That produces an unusual power position:
| Against | Position |
|---|---|
| Consumers | Strong. A vehicle-history report is a small absolute cost at the moment of a large purchase, bought once, under time pressure. Price sensitivity is low |
| Dealers | Strong, and it is a marketing channel as much as a data one — 40,000+ dealers use CARFAX to sell cars, so it drives their revenue rather than only their cost |
| OEMs and insurers | Balanced. Large sophisticated buyers, but they need coverage no competitor matches |
| Data suppliers | The genuine vulnerability. CARFAX does not own the underlying events; it aggregates them. Its position depends on continuing to receive feeds it does not control |
The threat worth naming is disintermediation at the source, not competition at the product. A rival cannot rebuild forty years of history. But the vehicle itself is increasingly the record — connected cars generate service, mileage and incident data directly, and the OEM owns it. If manufacturers were to pool telematics into a shared history standard, the new flow would bypass CARFAX entirely while its archive kept ageing.
That is a slow risk, not a live one. It requires OEM cooperation against their own commercial interests, applies only to vehicles built recently, and the used-car market runs on a fleet with an average age above twelve years. But it is the reason to watch data-supply agreements more closely than competitor launches.
The contrast with a components supplier is instructive. A semiconductor- materials or aerospace-component business is qualified into its customers' processes but cannot raise price, because alternatives exist and the buyers are larger than the seller. Mobility Global is the inverse: its customers are numerous and small relative to it, and its product has no substitute. That is a genuinely better position, and it is why the pricing question here is about volume and mix rather than about defending price.
Where the growth actually comes from
A reasonable reading of this company is that CARFAX has saturated its market and B2B is the growth engine. The disclosure does not support either half of that.
B2B is not the growth engine — CARFAX is
| Q2 2026 | 1H 2026 | |
|---|---|---|
| CARFAX | +8% | +8% |
| B2B | +4% | +6% |
CARFAX is growing twice as fast as B2B and is two-thirds of the revenue. It also gets the investment: the company states it is putting targeted consumer brand advertising behind CARFAX to lift unaided awareness, and the named new products — Sell My Car (full-service cash offers) and digital advertising — are CARFAX products, not B2B ones.
B2B’s role is different and worth stating precisely. It is where the adjacent markets sit — dealer management systems, shop-management software, P&C claims and repair software, F&I marketing — and those are large. But they are described as “beyond our immediate roadmap”, and they put Mobility Global against CDK Global, Reynolds & Reynolds and Cox Automotive, where the competitive section above rates it a participant rather than a leader. A bigger pond, and a worse position in it.
CARFAX is not saturated, on the company’s own numbers
Mobility Global sizes its total addressable market at $75–81B for 2025, against $1.75B of revenue. That headline should be discounted heavily — it is the standard inflated framing, and two-thirds of it is “adjacencies” the company does not currently sell. The useful figure is the first tier:
| TAM tier | 2025 size | What it contains |
|---|---|---|
| Core — served now or within 12 months | $13–15B | The existing business |
| Extended core — planned products and geographies | +$25–27B | Sell My Car, digital advertising, Data Studio, international expansion |
| Adjacencies — beyond the roadmap | +$37–39B | DMS, shop management, P&C claims software, F&I marketing |
Even on the conservative tier, $1.75B of revenue against a $13–15B core implies roughly 12% penetration. That is not a saturated market. The saturation intuition is right about one thing — CARFAX’s position in the US used-car vehicle-history transaction specifically is close to fully penetrated — but that is a subset of the core, and the growth is coming from selling more per customer rather than from finding new ones: the 53M-member Car Care base, the subscription mix at 82%, and products layered onto an existing data asset.
International is the underrated part, and the numbers show it
| ($M) | 1H 2026 | 1H 2025 | |
|---|---|---|---|
| U.S. | 765 | 715 | +7.0% |
| International | 158 | 144 | +9.7% |
| Total | 923 | 859 | +7.4% |
International is 17% of revenue and growing faster than the US. And the expansion is only beginning: CARFAX Europe has proven a consumer-led model in Spain and Italy, and the company states it intends to enter Germany and France on the same playbook — the two largest used-car markets in Europe.
Why this matters more than it looks. CARFAX’s moat in the US took forty years to build because the data had to be accumulated. In a new market the company is not starting from zero on method — it knows which sources matter, what the product should look like, and how the consumer-led model works, because it has now run it twice. Europe also has structurally favorable conditions: high cross-border used-vehicle flow, which makes history opaque and a history report more valuable, and no incumbent with CARFAX’s brand.
The risk is that it is genuinely hard. Vehicle records in Europe are held by national registries, insurers and workshops under different rules in every country, with GDPR overlaying all of it. Spain and Italy took years. Germany and France will not be quick, and nothing in the current guidance depends on them — which is precisely why this is upside rather than base case.
One embedded option worth naming. The company holds approximately 25% of Data Analytics (DA), a Germany-based SaaS platform that embeds its planning data into supplier workflows, with a right of first refusal on the remaining 75%. That is a call option on a European B2B channel, already partly owned, and it does not appear in any valuation on this page.
In depth: competitive dynamics
The two segments face completely different contests, and conflating them overstates the risk to the company.
| Where | Against | Position |
|---|---|---|
| Vehicle history (CARFAX, ~two-thirds of revenue) | AutoCheck (Experian); NMVTIS, the federal title database | Dominant. AutoCheck is the only real alternative and is materially smaller in both coverage and consumer recognition. NMVTIS is free but carries title and salvage records only — no service history, no accident detail, no ownership narrative |
| Dealer software and marketing (B2B) | CDK Global, Reynolds & Reynolds, Cox Automotive | A participant. These are entrenched systems-of-record with their own switching costs. CARFAX sells alongside them rather than displacing them |
| Market and residual-value intelligence | J.D. Power, Kelley Blue Book (Cox), Black Book | Competitive. Real alternatives exist and buyers are sophisticated |
| Underwriting data (financial solutions) | Experian, TransUnion, LexisNexis | A participant with a differentiated input — vehicle history is predictive of risk in a way credit data is not, but the carriers buy from several sources |
The asymmetry is the point. CARFAX is close to unassailable and is two-thirds of revenue; B2B is genuinely contested and is one-third. The company’s average competitive position is much better than its weakest one, and the weakest one is the smaller and slower-growing part — B2B grew 4% in the quarter against CARFAX’s 8%.
Why the dominant position holds
It is not the brand, though the brand is real. It is that a vehicle-history report is worth having only if it is complete, and completeness compounds. Every additional data source makes the product more useful, which wins more consumers and dealers, which funds more sources. A competitor starting today would need both the archive and the ongoing feeds, and the archive cannot be bought.
That compounding is contractual rather than fragile — the records arrive daily under paid arrangements, often exclusive. What it does not protect against is a shift in which data determines a vehicle’s value, which is examined separately in Commentary: how the competitive structure could change below.
The demand side reinforces it. CARFAX is bought once, under time pressure, as a small fraction of a large purchase — the worst possible conditions for price comparison. And on the dealer side it functions as a marketing tool: dealers display CARFAX reports to sell cars faster, so it sits on the revenue side of their P&L rather than the cost side. Products that make customers money are harder to cancel than products that save them money.
What would actually threaten it
Not a better product — a change in who holds the data. That risk is set out in the value-chain section above: connected vehicles generate service and incident records that the manufacturer owns, and CARFAX’s position depends on feeds it does not control. The competitive threat and the structural threat are different things here, and only the second one matters.
The item the market may still be under-weighting
Buried in the guidance assumptions: cash taxes will run $80–90M above the GAAP provision.
That is not a one-time separation artifact. Mobility Global carries $8,845M of goodwill and $3,640M of intangibles — largely from the legacy IHS Markit merger — throwing off $310M of annual amortization that is substantially not deductible. Book income is suppressed by a charge the tax authorities do not recognize, so cash tax lands on a much larger base.
The practical effect is that EBITDA overstates this company’s cash generation by more than the usual amount, and any valuation anchored on an EBITDA multiple flatters it. My FY27 estimate:
| FY2027 estimate | $M |
|---|---|
| Adjusted EBITDA | 780 |
| Cash interest | (111) |
| Cash taxes | (224) |
| Capex | (32) |
| Equity free cash flow | ≈413 |
That is $1.40 per share — a 6.8% free-cash-flow yield at $20.55, or 14.7x. The business did not get worse; the tax disclosure got clearer.
⚠️ This is an estimate, and it is the least certain number here
The company guided a $80–90M cash-tax premium for 2026 and did not say whether it persists. I have assumed it is permanent, reasoning that non-deductible amortization of acquired intangibles is a structural feature of a company carrying $12.5B of goodwill and intangibles from the IHS Markit merger — not a separation artifact that unwinds.
That reasoning is inference from public filings, not disclosure. A tax position of this kind is exactly the sort of thing an outside investor cannot verify: the deductibility of the intangible base depends on the structure of a merger that closed years ago and on the terms of the tax matters agreement with S&P Global, neither of which is laid out in the 10-Q.
The error is one-sided, which is the useful part. If the premium is transitional, FY27 free cash flow is roughly $490M rather than $413M — a 5.8% coverage improvement that lifts the target about $3–4 per share. If I am right, the valuation above already reflects it. So the valuation is deliberately built on the conservative branch, and the surprise risk runs in the shareholder’s favor.
Capital allocation
Mobility Global separated with a defined capital-returns framework and has already begun executing it — unusual for a company two months old.
| ($M) | |
|---|---|
| Paid to S&P Global at separation | ≈1,900 |
| Notes issued to fund it | 2,000 |
| Cash at June 30, 2026 | 186 |
| Net debt | ≈1,795 |
| Net leverage on guided FY26 EBITDA | 2.39x (2.63x gross) |
| Revolver | $500M, undrawn |
Three tranches, all fixed, nothing due before 2029:
| Tranche | Coupon | Due |
|---|---|---|
| $650M | 5.050% | 2029 |
| $650M | 5.450% | 2031 |
| $700M | 6.050% | 2036 |
Weighted coupon 5.53%, about $111M of annual cash interest, and no floating-rate exposure at all. There is no refinancing wall to underwrite.
The framework as stated: 20–25% of GAAP net income as dividends, buybacks beginning in 2027, and 75%+ of free cash flow returned over time.
The dividend came in above expectation — $0.06 quarterly, $0.24 annualized, a 1.17% yield at today’s price.
The capital-returns arithmetic is the most interesting decision in front of management
At $20.55 the shares yield 7.6% on free cash flow. Retiring debt saves about 4.1% after tax. Buying stock is worth roughly 350 basis points more than repaying borrowings, and on a business with 82% subscription revenue and no maturity until 2029, the balance-sheet risk of preferring the former is modest.
Sustained repurchases at this valuation would retire roughly a quarter of the company over five years. That is the single largest lever on per-share value available here, larger than any plausible operating improvement — and buybacks are guided to begin in 2027, not now.
The thing to watch is whether they actually start. A management team that defers repurchases while the stock trades at 13x free cash flow, in order to reach a leverage target that the maturity schedule does not require it to reach, would be optimising the balance sheet at the expense of the owners. The 2027 start date is a commitment worth holding them to.
Capital expenditure is negligible — roughly $25M a year on $1.87B of revenue, about 1.3%. Nothing about this business requires reinvestment to sustain it, which is why the free-cash-flow conversion is what it is.
Valuation
At $20.55: market capitalization $6,059M on 294.8M shares, net debt $1,795M, enterprise value $7,854M.
| At $20.55 | |
|---|---|
| EV / FY2026 guided adjusted EBITDA ($752.5M) | 10.4x |
| Price / FY2025 free cash flow ($461M) | 13.1x |
| Free-cash-flow yield | 7.6% |
| Dividend yield | 1.17% |
| Net leverage | 2.39x |
Why free cash flow is the only honest measure here
Mobility Global carries $8,845M of goodwill and $3,640M of intangibles from S&P Global’s acquisition of IHS Markit. The consequences run in two directions at once, and they cancel in a way that makes both GAAP earnings and EBITDA misleading:
- Amortization of acquired intangibles is $148M per half — $296M a year, 16% of revenue — against capital expenditure of roughly $25M. It is a real charge against reported profit and almost entirely unrelated to what the business spends. GAAP earnings are therefore far below cash earnings.
- Cash taxes run $80–90M above the GAAP provision, for the reasons set out in the section above. The tax is real cash, and adjusted EBITDA ignores it entirely.
So EBITDA overstates and GAAP earnings understate, and the gap between them is enormous. Reported operating margin runs ~18%; adjusted EBITDA margin runs ~40%. Neither is the economics. Free cash flow — $461M in 2025, 26.3% of revenue — already absorbs the cash tax and the capital spending, and it is the number this page values.
Discounted cash flow
Unlevered free cash flow, explicit period 2027–2040, perpetuity thereafter. Revenue growth easing 6.5% → 3.5% across the window as CARFAX’s high-single- digit growth blends with a slower B2B; adjusted EBITDA margin stepping down to 39.0% in 2027 for the full standalone load, then recovering; free-cash-flow conversion of 62% of adjusted EBITDA, against 65% achieved in 2025 and lower now because of the cash-tax drag.
On the length of the explicit period. A shorter model puts too much of the answer in the terminal value: on a seven-year period, 71% of enterprise value sits beyond the forecast. Running to 2040 brings that to 50%. As it happens the two produce nearly the same number — $28.49 against $29.20 — which is itself worth knowing: the terminal-value concentration was a conditioning problem rather than a valuation error. For a subscription business with 82% recurring revenue and a stable margin there is no depressed cash flow being wrongly capitalized. The longer model is the better-built one; it is not the more generous one.
Value per share, at 62% conversion:
| Terminal adj. EBITDA margin | WACC 8.0% / g 3.0% | WACC 8.5% / g 2.75% | WACC 9.0% / g 2.5% |
|---|---|---|---|
| 42.0% | $34.99 | $30.21 | $26.50 |
| 40.5% — our estimate | $33.82 | $29.20 | $25.62 |
| 39.0% | $32.64 | $28.19 | $24.73 |
| 37.5% | $31.47 | $27.18 | $23.85 |
The load-bearing assumption is not the margin and not the horizon — it is free-cash-flow conversion, because the cash-tax drag is new and only one quarter of standalone data exists:
| Conversion of adjusted EBITDA | Value at 40.5% margin, 8.5% |
|---|---|
| 58% | $26.92 |
| 62% (base) | $29.20 |
| 66% | $31.48 |
Every four points of conversion is worth about $2.30 a share. That is where the November print matters most.
Base case $29.20.
Cross-checks
Multiple on FY2027E adjusted EBITDA of $790M: 11x → $23.39 · 12x → $26.07 · 13x → $28.75.
Against the peer group. At the information-services median of ~14.5x on guided FY2026 EBITDA, Mobility Global would be worth $30.92. The peer section below sets out why that gap is only partly deserved.
Price target: $28 · range $23–31 · BUY
Method Value DCF — 40.5% terminal margin, 62% conversion, 8.5% WACC $29.20 DCF — conversion at 58% $26.92 DCF — conversion at 66% $31.48 DCF — 37.5% terminal margin, 8.5% $27.18 DCF — 9.0% WACC, 40.5% margin $25.62 (bear) FY2027E adjusted EBITDA $790M at 12x $26.07 FY2027E adjusted EBITDA $790M at 13x $28.75 Peer median 14.5x on FY2026E EBITDA $30.92 Base $28 is +36% to the August 26 close of $20.55.
Recommendation: BUY, unchanged.
The harder bear case sits below the table. Organic growth falling below 5%, or a 2027 margin under 38%, would compress the multiple toward 9–10x and take the value to roughly $18–20 — at which point the shares are fairly valued rather than cheap. That is the level at which this thesis fails, and it is below today’s price rather than above it.
Earnings-based valuation
A conventional P/E on this company is close to uninformative, and it is worth showing why rather than asserting it.
| ($M except per share) | 1H 2026 | 1H 2025 |
|---|---|---|
| Revenue | 923 | 859 |
| Operating profit (GAAP) | 163 | 180 |
| of which amortization of intangibles | (148) | (148) |
| Interest expense, net | (10) | (7) |
| Provision for income taxes | (45) | (50) |
| Net income | 108 | 123 |
| Reported EPS | $0.37 | $0.42 |
The year-over-year decline is an artifact and should be ignored. The prior-year period is carve-out accounting: $7M of interest against a standalone run-rate of about $55M per half, and no standalone public-company costs in the $265M of selling and general expense against $335M this year.
Normalizing the current half to the standalone capital structure — full interest, same tax rate — gives roughly $0.26 of EPS for the half, about $0.52 annualized, which at $20.55 is 39x. On its face that looks expensive for a business growing 7%.
It is not expensive; the measure is broken. That $0.52 is struck after $296M of annual amortization on intangibles the company did not buy and does not replace — against $25M of actual capital spending. Free cash flow per share is roughly $1.56, three times the normalized earnings figure, and it is the number that pays dividends and funds buybacks.
13.1x free cash flow and 39x normalized GAAP earnings describe the same company. Anyone screening this business on a P/E will conclude it is expensive, and will be wrong for a reason that is disclosed in a single line of the income statement.
The amortization does eventually end. At $296M a year against $3,640M of intangibles, the charge runs down over roughly a decade. As it does, GAAP earnings converge upward toward cash earnings with no operational change whatsoever — and the cash-tax premium narrows with it.
What this most resembles
Matching on the characteristics that should drive the outcome — a subscription data business, spun whole from a larger information-services parent, high margin, levered on the way out, no retained stake — the universe offers seven reasonable analogs:
| Company | Parent | Spun |
|---|---|---|
| Broadridge Financial Solutions | ADP | April 2007 |
| Gartner | IMS Health | July 1999 |
| Fidelity National Information Services | Equifax | July 2001 |
| Teradata | NCR | October 2007 |
| Donnelley Financial Solutions | RR Donnelley | October 2016 |
| Consensus Cloud Solutions | Ziff Davis | October 2021 |
| Western Union | First Data | October 2006 |
Return comparisons are deliberately left out for now. The obvious cut — how each performed at 90 days, one year and three — turns out to say more about when they spun than about what they were. Broadridge separated in April 2007 and Gartner in July 1999; their first years ran straight into the financial crisis and the dot-com unwind respectively. Reading either as a spinoff outcome mistakes a macro window for a business signal.
What the group does support is narrower and more useful:
The early trajectory carries almost no information. Broadridge and Gartner were both below their day-1 price a year out and both went on to return more than 700%. Western Union was comfortably above its day-1 price at 90 days and has since lost roughly two thirds of its value.
The separation is where the outcomes diverge, and it is not about the spin. Western Union’s money-transfer moat was disintermediated; Consensus Cloud’s core product is cloud fax. Both were reasonable-looking businesses at separation with no growth problem visible in year one. Broadridge, Gartner and FIS sold into structurally expanding markets. Neither entry multiple nor opening leverage predicted which was which.
For Mobility Global that puts the burden of proof somewhere specific: not on the 10.3x multiple, and not on the 2.4x net leverage, but on whether CARFAX’s 8% growth is durable. The multiple is defensible either way; the growth is the whole question.
The closest business analog is one the table cannot show. CDK Global — automotive dealer software and data, spun from ADP in October 2014 — is nearer to Mobility Global’s B2B segment than anything else in the universe. It was taken private by Brookfield in 2022 for $8.3B, which is why it has no live profile here and also why it matters: the last comparable automotive-data asset to actually change hands cleared at roughly the enterprise value Mobility Global carries today. The pre-spin analysis’s $18–28B takeout range was never the right frame; $8B was.
Price and volume: where we are on the post-spin journey
The mechanical selling is done. Whether the artificial trading is done is a different question, and the data says no.
| Day-1 volume | 97.8M shares — 22.8x the eventual baseline |
| Baseline (post week 2) | 4.3M/day |
| Sessions to normalization | ~9 |
| Realized volatility | 55% annualized |
Index and mandate selling compressed into the first two weeks and decayed fast. But three things argue against calling the register settled.
The float is still churning at an extraordinary rate. Cumulative volume since the spin is 119% of shares outstanding in 36 sessions — 85% of it excluding day 1. The last ten sessions alone traded 17% of the company, which annualises to roughly 430% turnover. That is not the profile of a shareholder base that has found its owners.
Volume re-elevated into earnings, then faded. Weekly medians against the baseline:
| Sessions | Window | vs baseline |
|---|---|---|
| 1–5 | spin flush | 6.30x |
| 16–20 | 0.97x | |
| 21–25 | pre-earnings | 0.68x |
| 26–30 | earnings week | 1.07x |
| 31–35 | 0.88x | |
| 36 | 0.61x |
Volume bottomed at 0.68x the week before the print, jumped 57% through earnings week, and receded again. That is the signature of a cohort that arrives for a catalyst and leaves after it — event-driven money positioning on the direction of a first standalone quarter, not long-term holders building.
And the 2.6x earnings-day spike is not, on its own, evidence of anything. Measured across 118 tickers with enough history, 20.8% of all sessions after volume normalization run at 2x baseline or higher — a 2x day is roughly a weekly event for a typical name. A 2.6x session is therefore not, on its own, evidence of anything. What is notable is the shape around it: a quiet trough, a spike, a fade.
Where the low was set matters more than either. The day-1 intraday low of $18.10 broke on session 3, and the flush bottomed at $17.67 on July 6 — that intraday floor has never been revisited. But the closing low is $19.00 on August 10, three days after earnings.
The forced-selling trough and the fundamental trough were two different events, five weeks apart. The spin flush set the intraday floor; the guidance set the closing floor. A framework that assumes the post-spin low arrives with the forced seller would have called the bottom on July 6 and been early by a month.
Trading commentary. The stock has cleared its mechanical de-risking but is not yet held by the people who will hold it. With the float turning over at this rate and an identifiable event-driven cohort trading the print, the next two earnings dates are more likely to set the range than the spin ever was — and that argues for treating quarterly results as the risk events here, not the separation.
For a position, the structure argues for scaling rather than a single entry. The $19.00–19.30 area has now been defended twice, once by the flush and once post-earnings, and is where risk/reward materially improves. Below $18.50 the thesis needs re-underwriting, since that would take out the post-earnings base on what would have to be new information. I would expect the November Q3 print — the first quarter carrying a fuller standalone cost load, and the first clean read on whether ~39% is a floor or a trend — to produce another volume event, and would rather be sized before it than after.
In depth: valuation against peers
Prices at the August 26, 2026 close, on a consistent basis.
| Company | Character | Price | EV | LTM EBITDA | EV/EBITDA | Fwd P/E |
|---|---|---|---|---|---|---|
| FICO | Scores and decisioning | $1,133.70 | $29.8B | $1.26B | 23.6x | 21.4x |
| Verisk | Insurance data and analytics | $187.87 | $28.5B | $1.52B | 18.8x | 21.6x |
| S&P Global | the former parent | $436.49 | $145.4B | $8.14B | 17.9x | 21.6x |
| Equifax | Consumer credit data | $190.56 | $27.8B | $1.92B | 14.5x | 18.8x |
| TransUnion | Consumer credit data | $84.50 | $21.2B | $1.53B | 13.9x | 15.1x |
| Morningstar | Investment data | $212.44 | $9.4B | $0.68B | 13.7x | 15.2x |
| Peer median | ~16.2x | ~20.1x | ||||
| Mobility Global | Vehicle-history data | $20.55 | $7.9B | $0.72B | 10.9x | 12.5x |
| on FY2026 guidance | $0.75B | 10.4x |
Mobility Global is the cheapest name in information services on both measures, and the gap is wide — 10.4x against a median of 16.2x, and 12.5x forward earnings against ~20x.
Three reasons the discount is partly deserved:
- Two months of listed history and a restated margin. The figure this business was marketed on was wrong by nearly twenty points, corrected weeks after listing. That earns a discount until a few clean quarters exist.
- Leverage. 2.39x net against a peer group that mostly runs lower, and a register that has not settled.
- End-market concentration. Every peer above sells into multiple verticals. Mobility Global sells into one — automotive — and two-thirds of it into the used-car transaction specifically.
Two reasons it is not. Growth of 7% sits mid-pack, not at the bottom; and free-cash-flow conversion at 26% of revenue is at the top of this group, on capital expenditure of 1.3% of sales. On the measure that actually pays shareholders, Mobility Global screens better than most of the names trading at 50% higher multiples.
The closest comparisons are TransUnion at 13.9x and Morningstar at 13.7x — single-vertical-ish data businesses with strong but not unassailable positions. Closing even half the gap to them is worth roughly $5 a share.
In depth: is Mobility Global an acquisition target?
Yes, and more plausibly than most names this size — but not before July 2028.
Section 355(e) presumes a taxable distribution if control changes within two years of the spin, which blocks an acquisition until July 1, 2028. The same rule constrains Mobility Global as an acquirer: a large stock-funded deal inside the window could itself cost the separation its tax-free treatment. Cash deals are unaffected, but at 2.39x leverage the capacity for a meaningful one is limited.
Beyond that date the asset is unusually buyable. It is a clean single-asset data business with no retained parent stake, contracted revenue, minimal capital intensity and an owner base that has not settled. The natural buyers:
| Buyer | Logic |
|---|---|
| Private equity | The most likely. Predictable subscription cash flow, 26% FCF margin, low capex — textbook LBO collateral, and precedent exists |
| Information-services strategics (Verisk, TransUnion, Equifax) | Adjacent data assets, plausible cost and cross-sell synergies. Antitrust risk is low — none of them holds vehicle history |
| Insurance carriers or a consortium | CARFAX data feeds underwriting directly |
The precedent that matters is not in the universe table. CDK Global — automotive dealer software and data, spun from ADP in October 2014 — was taken private by Brookfield in 2022 for $8.3B. That is the closest comparable automotive-data asset to actually change hands, and it cleared at roughly the enterprise value Mobility Global carries today.
The pre-separation analysis on this page framed a takeout at $18–28B. That was never the right frame. $8B was — and the fact that today’s enterprise value is $7.9B says the market is currently pricing this asset at about what the last one actually fetched, which is neither a bargain nor a stretch.
Commentary: how the competitive structure could change
The section above describes the competitive field as it stands. This one asks how it could be rearranged — by Mobility Global’s own acquisitions, by consolidation among others, and by electric vehicles moving where the data lives. Some of what follows is reasoning rather than disclosure, and it is separated for that reason. External figures are sourced at the foot of the section.
First, what the moat actually is
CARFAX holds more than 38 billion vehicle-history records from over 177,000 sources — 92,000+ dealers and service shops, 6,300+ police agencies, and 36 OEM certified pre-owned programs. The company calls these “symbiotic data partnerships,” and states they secure access “often on an exclusive basis, to critical purchase, incident and service data.”
That construction compounds, and it does so passively. The records arrive daily under standing commercial arrangements in which the supplier is paid. Nothing is re-won each year. A competitor would have to reconstruct 177,000 relationships against an incumbent that already pays those suppliers and, in places, holds exclusivity. This is a stronger and more durable position than a simple archive, because the archive keeps filling itself.
Where it is vulnerable is narrower than it first appears. Not the relationships — those are contractual and paid. Not the records already held. The exposure is to a change in which categories of data matter. If value migrates to a record type generated by an entity with no commercial relationship to CARFAX and no need for one, the existing 177,000 sources keep delivering faithfully while becoming less sufficient. That is the risk the third question below examines, and it is the only one of the three already visible in the market.
If Mobility Global is the acquirer
Section 355(e) is a weaker constraint than it sounds. At a ~$6.1B market capitalization, a stock-funded target of roughly $4–5B could be absorbed before the seller’s holders neared 50% of the combined company, and cash deals are unconstrained. At 2.39x leverage the balance sheet binds long before the tax rule does, and the restriction lapses in July 2028 regardless.
What they buy matters far more than whether they can.
| Direction | Effect on pricing power |
|---|---|
| Software where records are created — shop management, service lane, collision estimating | Tailwind, and the largest available. Converts sourcing from an arrangement into an asset: stop paying for service records, start generating them. The company names precisely these categories among its stated inorganic priorities |
| International incumbents — a European vehicle-history player | Tailwind. Buys a position rather than altering US dynamics, and accelerates the clearly under-exploited growth vector |
| Distribution — listings marketplaces, consumer retail | Headwind. Puts CARFAX into competition with the 40,000 dealers who are the reason the product sells. Today it sits on the revenue side of a dealer’s P&L; owning a marketplace makes that adversarial |
| AutoCheck (Experian) | Blocked, and arguably not desirable. Two-to-one in consumer vehicle history invites the antitrust attention CARFAX’s pricing has so far avoided. A weak second competitor is strategically useful |
The channel conflict is forming without any acquisition. Sell My Car — the full-service cash-offer product named in the growth plan — puts CARFAX into buying vehicles from consumers, competing with its own dealer customers and with CarMax and Carvana. Immaterial as revenue today; worth watching as positioning.
Every deal here carries an unusually high opportunity cost. At 13x free cash flow, the buyback is the largest per-share lever available, and an acquisition has to clear that hurdle.
If competitors combine
Two data companies merging does not produce a rival — adding two partial archives does not yield 38 billion records or 177,000 sources. A data company merging with a touchpoint owner might.
The combination that would matter most is Cox Automotive acquiring AutoCheck. Cox already owns Manheim — roughly 7 to 8 million vehicles a year across 111 auction locations, serving more than 80,000 dealers — plus Kelley Blue Book, Autotrader, Dealertrack and vAuto. What it lacks is vehicle history. Manheim physically handles and inspects vehicles at a scale nobody else does: condition data generated at source, of a type CARFAX does not hold. Attaching the number-two history product to that would create the first competitor built on a flow CARFAX does not touch.
A CDK–Reynolds & Reynolds combination is the other: joint control of the dealer system of record, where service data originates, and therefore leverage over CARFAX’s inputs. Antitrust would be difficult.
Internationally the risk is cheaper and nearer. Europe is fragmented across national players. A European roll-up would cost a fraction of a US deal and could pre-empt the Germany and France expansion before CARFAX arrives. Of everything here, this is the one that could happen quietly and soon.
What electric vehicles do to the data — and this one is not hypothetical
Two things happen at once. The traditional record thins: no oil changes, no transmission service, no exhaust, far less brake wear under regenerative braking — and independent shops, a major feed, largely do not service EVs. And the data that matters most moves: for a used electric vehicle the dominant question is battery state of health, which lives in the battery management system and telemeters to the manufacturer. It appears in no title record, police report or independent shop invoice.
This has already happened at the largest used-car retailer in America. CarMax provides battery-health information on its own site through a partnership with Recurrent — a battery range score on EVs in inventory, clicking through to a full Recurrent report. Not through CARFAX. Recurrent’s chief executive frames the ambition plainly: “Battery health is the new odometer for electric vehicles.”
Mobility Global’s own filings describe no CARFAX product addressing used-EV battery condition. Electric vehicles appear throughout the document as a B2B forecasting theme — battery supply chains, EV and software-defined-vehicle player forecasts — and not once as a CARFAX data gap. A competitor has taken the EV data layer at the largest retail buyer, and the disclosure does not acknowledge it.
Four things blunt this, and together they are substantial:
- Scale and timing. Used EVs reached a record 2.8% of the US used market in April 2026, against a fleet whose average age is about 13 years. New EV sales fell 28% year on year in Q1 2026, so the used pipeline is filling more slowly than previously assumed. The market CARFAX serves stays overwhelmingly internal-combustion well into the 2030s.
- It is cheaply buyable, and CARFAX has the distribution a specialist lacks. This is the same “own the source” logic as the acquisition question above.
- The OEM relationship already exists. CARFAX takes feeds from 36 OEM certified pre-owned programs. The premise that manufacturers will not share data is weaker than it looks — they already do, where it suits them.
- Battery degradation is proving mild. Recurrent’s data has EVs retaining roughly 97% of range after three years and showing a 0.3% replacement rate — which limits how much value the missing datapoint actually withholds.
One counterweight we would not lean on: regulation. Only Massachusetts and Maine have strong telematics access laws; the Massachusetts case remained pending as of early 2026 with manufacturers citing it to defer compliance, and the federal REPAIR Act has been before Congress since 2025 without passing. Mandated access may come, but nothing in the current record supports treating it as likely or near.
The version of this risk that concerns us most is none of the above. If the manufacturer holds the data, the manufacturer can become the substitute — a certified-used program with a battery-health guarantee replaces third-party information with a factory warranty. That is already how certified pre-owned works, and electric vehicles push more of the used market toward it, a channel where a history report matters less regardless of who owns the data.
The structural summary. CARFAX’s sourcing compounds and is contractually secure; the archive is not the fragile part. What is exposed is the mix of data that determines a used vehicle’s value. Electric vehicles are less mechanical and more vertically integrated, so the categories CARFAX dominates matter less on those cars — from a 2.8% base, over a horizon measured in decades. A real risk with a slow fuse, which is the hardest kind to price and the easiest to ignore.
External sources for this section. Manheim scale: Cox Automotive. Used-EV share and new-EV sales decline: Electrek, March 2026. Battery degradation data and the CarMax partnership: Recurrent, CarMax, Green Car Reports. Telematics right-to-repair status: Nelson Mullins, Auto Care Association. All Mobility Global figures are from its own filings.
Tail scenarios
Low probability, high magnitude, short of black swan.
Upside tails
1. The buyback starts early and is used properly. At a 7.6% free-cash-flow yield against a 4.1% after-tax cost of debt, sustained repurchases would retire roughly a quarter of the company over five years. Management has guided this to begin in 2027. Pulling it forward, or sizing it at the top of the 75%-of-FCF framework, is worth more to per-share value than any operating improvement available here — and it is entirely within management’s control.
2. The register settles and the multiple re-rates. Cumulative volume since the spin is 119% of shares outstanding in 36 sessions, and the last ten alone traded 17% of the company. This is not yet held by the people who will hold it. Closing half the gap to TransUnion and Morningstar — the closest comparable businesses — is worth about $5 a share, and requires nothing from the company except two or three uneventful quarters.
3. Adjacencies CARFAX has the right to win. The data set supports products it does not yet sell at scale: insurance underwriting and claims (vehicle history is directly predictive of risk), service-lifecycle marketing to the 53M+ car-care user base, residual-value and lease-return analytics for lenders and OEMs, and fleet and commercial-vehicle history, which is structurally similar and largely unaddressed. Each uses an asset already paid for — the marginal cost of a new product on an existing data set is close to zero, which is why incremental margin in this business can exceed the average.
4. It gets bought after July 2028. See above. Precedent at $8.3B, and a buyer set that is broad rather than narrow.
Downside tails
1. The second-half margin is a trend, not a floor. Guidance implies 38.4% in the second half against 41.8% delivered in the first. If standalone costs settle materially below 39% rather than at it, the DCF at 37.5% terminal margin gives $27.18 — and a genuine deterioration below that compounds, because it would signal the standalone cost base was underestimated rather than simply phased.
2. Cash conversion disappoints. The cash-tax premium of $80–90M above the GAAP provision is new, disclosed, and structural for as long as the intangible amortization runs. If conversion settles at 58% rather than 62%, that is $2.30 a share. One quarter of standalone data is not enough to know.
3. OEM telematics bypasses the archive. The slow, real risk set out in the value-chain section: connected vehicles generate service and incident data that the manufacturer owns. CARFAX’s position depends on receiving feeds it does not control. Nothing here changes inside three years, and it does not touch the existing twelve-year-average fleet — but it is the one development that would attack the moat at its source rather than at its product.
4. The used-car cycle turns. Two-thirds of revenue is tied to used-vehicle transactions. Volumes are cyclical and this business has never reported through a downturn as a standalone company. Subscription revenue at 82% cushions it, but it does not immunize it — dealers cut subscriptions when they sell fewer cars.
5. An acquisition inside the 355(e) window. Management has an unlevered-ish balance sheet by data-business standards and a stated growth ambition. Paper-funded M&A before July 2028 risks the tax-free status of the separation, and cash-funded M&A at 2.39x leverage would consume the capacity that makes the buyback case work. Either would be a worse use of capital than the shares.
What would change this view
| Direction | Trigger |
|---|---|
| Better | Second-half margin holding at or above 39% · buybacks beginning ahead of the 2027 guide · CARFAX growth sustaining at 8%+ · free-cash-flow conversion above 62% · volume normalizing and the float turning over less |
| Worse | Second-half margin below 38% · CARFAX growth decelerating below 6% · cash-tax premium widening beyond $90M · a paper-funded acquisition before July 2028 · B2B transactional weakness persisting past the recall timing effect |
| Dated, next 6 months | The Q3 print in November — the first quarter carrying a fuller standalone cost load and the first clean read on whether ~39% is a floor or a trend |
| Thesis-breaking | A material data-supply agreement lost or renegotiated adversely · an OEM consortium establishing a shared vehicle-history standard |
Investment Scorecard
Scored on the five weighted dimensions set out in our methodology.
| Dimension | Weight | Score | Rationale |
|---|---|---|---|
| Financial Profile | 25% | 4.0 | 40.6% adjusted EBITDA and 26.3% free-cash-flow margins, capital expenditure of 1.3% of sales, four years of segment history showing operating profit up 77% on revenue up 53%, three fixed-rate tranches with nothing due before 2029, and no floating exposure. Held below 4.5 by 2.39x net leverage, a second-half margin guided 340bp below the first, and a cash-tax premium of $80–90M that is structural rather than transitional |
| Competitive Position | 25% | 5.0 | A forty-year vehicle-history data set that cannot be re-created at any price, 53M+ car-care users, 40,000+ dealer customers, 100% of the top-40 OEMs, and 82% subscription revenue. Its customers are numerous and small relative to it and its product has no substitute |
| Strategic Rationale | 20% | 4.0 | A clean 100% distribution with no retained stake, releasing a focused data business from a diversified parent. Discounted for the ≈$1.9B debt-funded payment to S&P Global on the way out |
| Management & Governance | 20% | 4.0 | Raised from 3.5 once the biographies were read. The CEO ran CARFAX itself from 2021 after two decades there; the CFO was CFO of Booz Allen Hamilton, a listed company several times this one’s size; the Chief Accounting Officer closed the books through ESAB’s own spinoff. The board carries three current or recent listed-company CEOs and three former public-company CFOs, chaired by a recent CEO of CSX who ran Ford’s global automotive business. A capital-returns framework defined, delivered on time, and above expectation on the dividend. Held below 4.5 by a reported margin restated within a month of listing, and by two directors carrying former-parent ties |
| Acquisition Potential | 10% | 5.0 | A clean single-asset data business with no retained stake, blocked only until July 2028. Credible private-equity and strategic buyers, low antitrust risk, and a direct precedent at $8.3B |
| Weighted Score | 4.35 | ||
| Investment Grade | A · Strong Opportunity |
Grade: A (4.35), unchanged
The July 31 regrade took this from A+ (4.60) to A (4.35) on the margin correction. Four years of segment history and a first standalone quarter do not change that conclusion, which is worth stating plainly, because a longer record usually revises a spinco’s story downward rather than confirming it.
The adjustments net out exactly. Financial Profile 4.0 held — the four-year record is better than the three-year one, but the cash-tax premium and the second-half margin step are new negatives. Competitive Position 5.0 held. Management & Governance 4.0 held, on a fuller reading than the pre-spin grade had: the executive and board biographies are materially stronger than a “spun-out division” reading assumes, which offsets the restated margin rather than being outweighed by it.
The longer record here confirms the story rather than revising it, and the grade reflects that.
What would take it to A+: two quarters at or above 39% margin with buybacks underway. What would take it down: evidence that the standalone cost base was underestimated rather than merely phased.
Initial Assessment — August 5, 2026
Consolidates the July 31, 2026 monthly report and the August 5, 2026 assessment — both written against the July 31 close. This is a point-in-time record and is not updated as the price moves — see Current Stats above for the latest figures.
What happened
Mobility Global separated from S&P Global on July 1, 2026 in the cleanest structure this site tracks: a 1-for-1 distribution, 100% distributed with S&P Global retaining nothing, 294,821,318 shares, NYSE-listed. No retained stake means no overhang on either side, and the price action showed it — a shallow, fast dip to $19.26 on day 5, then a grind back to $20.38 by month-end. That is -3.8% against the $21.19 Day-1 close and +5.8% off the low.
For a separation this large, that is an unremarkable debut — which is itself the point. The forced-selling trough the framework predicts arrived early and was mild. Parent SPGI is -0.7% over the same window; neither side was punished.
The number that changed the thesis
The substantive event of this month was not the price. It was the discovery that the margin figure this profile had carried since October 2025 was wrong — “≈60% EBITDA margins” against an actual 40.6%. The full restatement is in the correction notice at the top of this page.
What matters for the forward view is that the error ran in one direction and touched everything downstream. The valuation ladder, the peer comparison against Verisk, the acquisition price range and the bull case were all built on a margin the company does not earn. The grade fell A+ (4.60) → A (4.35) as a result — a data correction, not a business deterioration.
The business is unchanged. CARFAX is still a near-monopoly with 40 years of irreplaceable data, 53M+ car-care users, 40,000+ dealer customers and 100% of the top-40 OEMs. Revenue grew 8.5% in FY2025. What changed is the price we think it deserves, and the honest answer is a good business at a reasonable multiple rather than a great business at an extraordinary discount.
What the market is actually paying
At $20.38 the market cap is $6.01B; with ≈$1.8B of net debt that is an enterprise value of ≈$7.81B, or 11.0x adjusted EBITDA, 13.0x free cash flow and a 7.7% FCF yield.
Two things follow. First, the stock trades below the 18x “conservative” floor the pre-spin ladder assumed, on an EBITDA base a quarter smaller than that ladder used — the mispricing the A+ implied simply is not there, but neither is the stock expensive. Second, the capital-return story is more interesting than the valuation. Management has committed to returning 75%+ of free cash flow, of which roughly six-sevenths is repurchases; the headline dividend will yield only 0.6-0.9% because it is set against a GAAP net income that $310M of intangible amortization suppresses. Total shareholder yield is 6.2-6.3%.
Discounting total distributions rather than dividends alone implies $24-42 per share. The current quote sits below every cell in that grid.
The one thing to underwrite
The balance sheet starts offside its own target. ≈$2B of notes — raised to fund a ≈$1.9B payment to S&P Global on the way out the door — is 2.81x gross leverage against a stated <2.5x ceiling. It self-cures at the guided growth rate (2.57x in 2026, 2.35x in 2027) without repaying a dollar, and having committed 75%+ of FCF to shareholders, management has structurally chosen to grow into the target rather than pay down principal.
That is the right call while the shares trade at a 7.7% FCF yield against a ≈4.1% after-tax cost of debt — buying stock earns more than retiring debt. It is worth naming plainly all the same: this is a SpinCo that was levered up to write its parent a cheque, and the leverage math only works if the growth shows up.
What to watch
First standalone results land August 7, 2026 — before market open, with a call at 8:00am ET. That print replaces the estimates this analysis rests on with actuals: real standalone margins, the actual interest expense on the new notes, the stand-up cost run-rate, and possibly the first dividend declaration. Everything above should be re-read against it.
Beyond that: whether the buyback actually begins in 2027 as guided, and whether the acquisition interest the pre-spin analysis assumed materialises now that a public price exists. At ≈$7.81B, a takeout is a far smaller cheque than the $18-28B the earlier work imagined.
From the July 31 report
First report after the July 1 separation. The margin correction lands here, and with it the regrade. Prices as of the July 31, 2026 close.
Trading since the spin
| Metric | Value |
|---|---|
| Day-1 close (Jul 1) | $21.19 |
| Post-spin low | $19.26 on Jul 6 (day 5) |
| Jul 31 close | $20.38 |
| Return vs Day 1 | -3.8% |
| Return vs low | +5.8% |
| Parent SPGI | -0.7% since the spin |
The anticipated forced-selling window did materialise, but it was shallow and brief — a 9% drawdown over five sessions, then a grind back. The clean, zero-retained-stake structure meant no overhang on either side.
The correction
FY2025 revenue $1,750M, adjusted EBITDA $711M (40.6% margin), free cash flow $461M (26.3% margin, 65% conversion), GAAP net income $220M. The ≈60% margin this profile had carried since October 2025 is not supported by the Investor Day financials; the ≈$1.6B revenue figure was FY2024’s $1,613M. Revenue growth was 8.6% in 2024 and 8.5% in 2025 — the one figure the earlier analysis had right. The full restatement, including the net-income bridge, is in the correction notice at the top of this page.
Valuation on the corrected figures
Market cap $6.01B on 294,821,318 shares; net debt ≈$1.8B; enterprise value ≈$7.81B. That is 11.0x EV/adjusted EBITDA, 12.0x EV/GAAP EBITDA, 13.0x P/FCF and a 7.7% FCF yield. Pro-forma standalone earnings are lower than the $220M carve-out figure suggests: that number carried only $13M of net interest, whereas ≈$2B of notes at an investment-grade 5.0-6.0% coupon implies $100-120M annually. On FY2025 EBIT of $339M at the guided 25-27% tax rate, pro-forma net income is roughly $162-177M ($0.55-0.60 EPS) — before $75-100M of one-time stand-up costs over 12-18 months.
Capital returns
Management’s framework is 20-25% of GAAP net income as dividends, buybacks beginning in 2027, and 75%+ of free cash flow returned annually. The dividend will be small — a 0.6-0.9% yield — because a payout set against net income distributes only about a tenth of the cash this business generates while $310M of amortization suppresses reported earnings. Total distributions run ≈$1.26-1.29 per share, a 6.2-6.3% total shareholder yield, roughly six-sevenths of it repurchases. A dividend discount model values only the dividend and returns $2.44-5.50 per share — 12-27% of the price — which is a verdict on the instrument, not the security. Discounting total distributions implies $24-42 per share, with the current quote below every cell in that grid.
Sustained repurchases at 13.0x FCF earn 7.7% against ≈4.1% after-tax for retiring debt, and would retire roughly 24% of the share count over five years (295M → ≈223M). Heavier deleveraging produces lower per-share value while the stock trades below intrinsic value.
Grade change: A+ (4.60) → A (4.35)
| Dimension | Weight | Score | Rationale |
|---|---|---|---|
| Financial Profile | 25% | 4 ⬇️ | 40.6% adj. EBITDA and 26.3% FCF margins are strong, but growth is guided 7.5-10% (not double-digit) and the ≈$2B of notes funding a ≈$1.9B payment to the parent left MBGL at 2.81x gross leverage on day one, above its own <2.5x target (was 5, on an erroneous ≈60% margin) |
| Competitive Position | 25% | 5 | CARFAX near-monopoly; 53M+ car-care users, 40K+ dealer customers, 100% of top-40 OEMs |
| Strategic Rationale | 20% | 4 | Clear focus-unlock for both entities; clean 100% distribution |
| Management & Governance | 20% | 4 | Full C-suite named; Investor Day delivered with detailed multi-year targets |
| Acquisition Potential | 10% | 5 | High-value data asset; credible PE and strategic acquirers |
| Weighted Score | 4.35 | ||
| Investment Grade | A | Strong Buy |
Grade Change: A+ (4.60) → A (4.35). The trigger is the data correction. At 40.6% the business still clears the methodology’s “30%+ margins” test for a 5, but it fails the “double-digit growth” test and starts levered near its own target — squarely the 4 band. Nothing about the competitive position, management or acquisition appeal changed.
Recommendation: ⭐⭐⭐⭐ BUY. The regrade lowers the label, not the conclusion. It is a reasonably priced compounder rather than the extraordinary mispricing the A+ implied.
Next catalyst
⚠️ First standalone quarterly results, August 7, 2026 (before market open; 8:00am ET call with CEO Bill Eager and CFO Matt Calderone). First hard data on standalone margins, actual interest expense on the new notes, stand-up cost run-rate, and any initial dividend declaration.
⚠️ Correction (July 31, 2026) — read before the analysis below
Every section of this page written before July 31, 2026 describes Mobility Global as having “≈60% EBITDA margins” on “$1.6B of revenue.” Both figures are wrong, and the valuation work built on them is therefore wrong. The company’s Investor Day financials (June 1, 2026 deck, slides 11 / 94 / 108–111) show FY2025 revenue of $1,750M and adjusted EBITDA of $711M — a 40.6% margin, not ≈60%. The ≈$1.6B revenue figure was FY2024’s $1,613M. The gap between a 40.6% EBITDA margin and a 12.6% net margin is $310M of D&A, largely amortization of intangibles from the legacy IHS Markit merger.
($M) FY2023 FY2024 FY2025 Total revenue 1,485 1,613 1,750 GAAP EBITDA 546 608 649 (37.1% margin) Adjusted EBITDA 598 658 711 — 40.6% margin Free cash flow 375 412 461 (26.3% margin) GAAP net income — — 220 Consequences: the grade was downgraded A+ (4.60) → A (4.35) on the data correction — not on any business deterioration — and the implied-valuation ladder in Financials & Valuation below (18x/22x/28x on a $960M EBITDA estimate → $17B/$21B/$27B EV) is void. Actual enterprise value at the July 31 close is ≈$7.81B, or 11.0x EV/adjusted EBITDA. The recommendation remains BUY.
Corrections on this site are additive: the prose below is left exactly as published, because it is the record of what each report said at the time. Read it with this correction in hand. The restated analysis is in Analysis — July 31, 2026 at the foot of this page and in the July 31, 2026 report.
All analysis below is pre-spinoff
Written before Mobility Global began trading July 1, 2026. Kept as published — figures, valuations and grades reflect what was known at the time, not today.
Executive Summary
Management Team
| Role | Name | Background |
|---|---|---|
| CEO | Bill Eager | President of S&P Global Mobility; led division through separation planning |
| CFO-designate | Matt Calderone | Named March 2026; prior role undisclosed |
| Chief Accounting Officer | Renato Negro | Effective April 6, 2026; reports to CFO-designate |
| President, CARFAX | Scott Fredericks | Promoted from COO of CARFAX |
| President, Business Solutions | Joe Lafeir | Former President of Automotive Insights |
| Chief Legal Officer | Tasha Matharu | Deputy General Counsel of S&P Global |
| Chief Information Officer | Joedy Lenz | Former CTO of CARFAX |
| Chief People Officer | Larissa Cerqueira | Former CHRO at Fluence Energy |
Business Analysis & Competitive Dynamics
Mobility Global is the automotive data and technology division of S&P Global, anchored by its crown jewel brand CARFAX — the dominant player in used-vehicle history reports with a near-monopoly position built on decades of proprietary vehicle data that is virtually impossible to replicate. The business also includes automotiveMastermind (dealer marketing), Polk Automotive Solutions (registration and loyalty analytics), and Market Scan (real-time payment and incentive data).
The company operates in a $30B+ total addressable market across used vehicle data, new vehicle sales tools, and strategic planning analytics. Core competitive advantages include the CARFAX data moat (the largest vehicle history database in North America), deeply embedded dealer workflows, and high switching costs — dealers and consumers rely on CARFAX as the standard for vehicle transparency.
Financial profile is exceptional: 60% EBITDA margins rank among the highest in the data/analytics sector, with 8% revenue growth in a mature automotive market. The EV transition creates new growth vectors — battery health data, charging history, and EV-specific valuation models — that extend the CARFAX franchise into new revenue streams. International expansion (CARFAX is primarily US/Canada today) represents another untapped growth lever.
Key risks include cyclical automotive market exposure, the potential for large dealer groups and OEMs to build competing data platforms, and smaller standalone scale ($1.6B revenue) which may limit bargaining power with large customers. However, the data moat and brand strength substantially mitigate these risks.
Correction (July 31, 2026): the “60% EBITDA margins” and “$1.6B revenue” in the two paragraphs above are wrong — actual FY2025 figures are $1,750M of revenue at a 40.6% adjusted EBITDA margin. See the correction notice at the top of this page. The qualitative business analysis — the CARFAX moat, the $30B+ TAM, the EV and international growth vectors — is unaffected; 8% revenue growth was accurate (8.5% in FY2025).
Acquisition Analysis
Mobility Global is widely viewed as a highly attractive acquisition target, with a high probability of takeout within 12-24 months post-spinoff. Standalone valuation is estimated at 15-20x EBITDA ($14-19B), with a 30-50% acquisition premium implying a $18-28B+ takeout price.
Correction (July 31, 2026): the dollar valuations in the paragraph above were derived from the erroneous ≈60% margin and are void. On the actual $711M of FY2025 adjusted EBITDA, 15-20x implies $10.7-14.2B of enterprise value, not $14-19B — and the market has priced it far lower still, at ≈$7.81B (11.0x) as of the July 31 close. A 30-50% premium to the current EV implies a $10.2-11.7B takeout, not $18-28B+. The qualitative acquisition appeal is unchanged.
Correction (May 31, 2026): Prior reports cited Cox Automotive as the most likely acquirer. That specific speculation is unsubstantiated — it appears to stem from name confusion with Cox’s own internal “Mobility” division. The underlying acquisition appeal of the CARFAX data asset is unchanged; the most credible buyers are now PE data specialists and large dealer groups.
Potential Acquirers:
| Acquirer | Strategic Logic |
|---|---|
| Private Equity (Vista, Thoma Bravo, Silver Lake) | High-margin, recurring-revenue data businesses are core PE playbook. ~60% EBITDA margins are exceptional. Most credible acquirer path. |
| Auto dealer groups (AutoNation, Lithia, CarMax) | Want to own CARFAX data rather than paying for it. Vertical integration play. |
| Data / AI platforms | Automotive data for AI training, autonomous vehicle services, and connected car platforms. |
Changes & Developments
| Date | Change |
|---|---|
| Jul 31, 2026 | ⬇️ Downgraded A+ (4.60) → A (4.35) on a data correction, not a business deterioration. The ≈60% EBITDA margin carried since October 2025 is wrong: FY2025 revenue $1,750M, adjusted EBITDA $711M (40.6% margin), FCF $461M, GAAP net income $220M. Spun July 1 as planned — 1:1, 100% distributed, 294,821,318 shares, NYSE. Day-1 close $21.19; post-spin low $19.26 on day 5; $20.38 at the July 31 close (-3.8% vs Day 1, +5.8% off the low). Parent SPGI -0.7%. At $20.38: ≈$7.81B EV, 11.0x EV/adj. EBITDA, 13.0x P/FCF, 7.7% FCF yield, 2.81x gross leverage (above its own <2.5x target). Rating stays BUY. Next catalyst: first standalone results August 7. |
| Jun 30, 2026 | Grade unchanged (A+, 4.60), retained as TOP PICK. Distribution confirmed on track for July 1; record date June 15 passed; when-issued (MBGL WI) traded June 26-30. Nothing in June contradicted the thesis as then understood — the margin error had not yet been caught. Fully de-risked on timing. |
| May 31, 2026 | Grade unchanged (A+, 4.60). Form 10 publicly filed May 7. Investor Day held May 12 in NYC — medium-term framework: 7.5-10% organic revenue growth, 8-11% adj. EBITDA growth, +50bps/yr margin, 75%+ FCF return, dividend 20-25% of GAAP net income. Ticker MBGL (NYSE); record date June 15; distribution July 1 (1:1, S&P retains 0%); when-issued June 26-30. ~$2B senior notes fund a one-time ~$1.95B payment to S&P; capital structure <2.5x gross leverage, ~$150M cash, $500M revolver. Cox Automotive acquirer speculation retracted as unsubstantiated (name confusion). |
| Apr 15, 2026 | Grade unchanged (A+). Investor Day confirmed May 12, 2026 in NYC. Renato Negro named CAO effective April 6. Matt Calderone named CFO-designate. Investment Scorecard: 4.65/5.0. |
| Mar 2, 2026 | Rebranded from “S&P Mobility” to “Mobility Global, Inc.” (Feb 3). SPGI stock dropped 10% on rebrand news. Confidential Form 10 filed with SEC. Targeting investment-grade credit rating. |
| Jan 29, 2026 | Full C-suite announced: CEO Bill Eager, President CARFAX Scott Fredericks, President Business Solutions Joe Lafeir, CLO Tasha Matharu, CIO Joedy Lenz, CPO Larissa Cerqueira. Timeline tightened to Q2 2026. |
| Oct 24, 2025 | Promoted to #1 ranking and A+ (TOP PICK). Timeline narrowed to Q2-Q3 2026. Acquisition likelihood rated “Very High (90%+).” Valuation range: $14-28B+. |
| Oct 23, 2025 | First appearance. No formal grade (described as “highly attractive”). Listed as #7. Revenue $1.6B, 60% EBITDA margins. S&P Global Investor Day Nov 13 noted as key upcoming event. |
In Depth Analysis
April 28, 2026 deep-dive, with key facts refreshed for the May 31, 2026 report (debt structure, catalysts, and the Cox acquirer retraction).
Competitive Dynamics
1. Product segments and competitors
✅ Mobility Global operates across four product lines, each with a distinct competitive landscape:
| Segment | What it does | Revenue contribution | Key competitors |
|---|---|---|---|
| CARFAX (Used Vehicle) | Vehicle history reports, dealer inventory tools | Largest segment (~50%+) | AutoCheck (Experian), dealer proprietary data |
| automotiveMastermind | Dealer marketing, customer targeting, conquest campaigns | Significant | DealerSocket (Solera), DealerInspire (Cars.com), Urban Science |
| Polk Automotive Solutions | Registration data, loyalty analytics, market forecasting | Moderate | IHS Markit (now internal to S&P — will transfer or license post-spin), J.D. Power, Wards Intelligence |
| Market Scan | Real-time payment quoting, incentive data, F&I tools | Moderate | RouteOne, DealerTrack (Cox Auto), MaximTrak |
2. Market concentration
✅ Concentrated (near-monopoly) in core CARFAX business. CARFAX dominates consumer-facing vehicle history reports with estimated 80-90%+ market share in the US. Experian’s AutoCheck is the only meaningful competitor but has never achieved comparable consumer brand recognition or dealer adoption.
⚠️ Oligopolistic in the broader automotive data market. Dealer marketing, analytics, and F&I tools are contested by a handful of major players (Cox Automotive, Solera, Cars.com, J.D. Power) but no single dominant winner. Mobility Global’s advantage is having multiple products that cross-sell within the same dealership.
⚠️ Fragmented in emerging areas. EV data (battery health, charging history), connected car analytics, and AI-powered valuation tools are nascent markets with no established leader yet — representing both opportunity and competitive uncertainty.
3. Moats and weak spots
✅ Strongest moat: CARFAX data moat. Decades of accumulated vehicle history records (accidents, service, ownership, recalls) from insurance companies, DMVs, service shops, and auctions. This dataset is effectively impossible to replicate from scratch — a new entrant would need 20+ years of data collection agreements.
✅ Strong moat: Dealer workflow embedding. CARFAX is deeply integrated into dealer management systems (DMS). Dealers use CARFAX reports as part of their standard vehicle appraisal and sales process. Switching costs are high because changing tools disrupts daily operations.
⚠️ Moderate moat: Polk data assets. Registration and loyalty data is valuable but faces competition from IHS Markit (which was part of S&P Global pre-merger — unclear how this data relationship works post-spin) and J.D. Power.
⚠️ Weak spot: Limited international presence. CARFAX operates primarily in the US and Canada. European and Asian vehicle history markets are served by different providers (e.g., HPI in the UK, Carvertical in Europe). International expansion is an opportunity but requires building new data relationships from scratch in each market.
❓ Weak spot: OEM direct data risk. As automakers build connected car platforms (GM OnStar, Ford SYNC, Tesla), they collect real-time vehicle data directly. Over time, OEMs could potentially bypass CARFAX by offering their own history/condition reports. However, CARFAX aggregates data across all brands — a single-OEM report can’t match cross-brand coverage.
4. Head-to-head vs closest competitor: Cox Automotive
⚠️ Cox Automotive is the most comparable company — a private automotive data/marketplace conglomerate owned by Cox Enterprises.
| Dimension | Mobility Global | Cox Automotive |
|---|---|---|
| Revenue | $1.6B | ~$8-10B (estimated, private) |
| Key brands | CARFAX, Polk, automotiveMastermind, Market Scan | Autotrader, Kelley Blue Book, Manheim, Dealertrack, VinSolutions |
| Core strength | Vehicle history data (CARFAX monopoly) | Marketplace/listings (Autotrader) + wholesale auctions (Manheim) |
| Dealer penetration | High (CARFAX used by ~90%+ of franchise dealers) | Very high (Autotrader + Manheim are industry standards) |
| Margin profile | ~60% EBITDA | ⚠️ Unknown (private), estimated 20-30% |
| Consumer brand | CARFAX is iconic, consumer-facing | Autotrader + KBB are consumer-facing |
| Data moat | Vehicle history = deepest moat | Pricing data (KBB) + auction data (Manheim) |
Key insight: These two companies are complementary, not directly competitive in most segments. CARFAX does vehicle history; Cox does marketplace/pricing/auctions. (Note: prior reports speculated that this complementarity made Cox a likely acquirer of Mobility Global; the May 31, 2026 report retracted that as unsubstantiated name-confusion. The competitive complementarity stands; the acquisition thesis does not.)
5. Crown jewel: CARFAX
✅ CARFAX is the crown jewel and the primary reason for the A+ rating.
- Data moat: Proprietary database of vehicle history records built over 40+ years (founded 1984)
- Source network: Data from 130,000+ sources including insurance companies, DMVs, service departments, auctions, fire departments, and fleet operators
- Consumer recognition: CARFAX is effectively a verb — “has it been CARFAX’d?” Brand awareness estimated at 90%+ among US car buyers
- Dealer standard: Used by virtually every franchise dealer in North America as part of standard vehicle appraisal and sales process
- Recurring revenue: Dealers pay subscription fees for unlimited reports; consumers pay per report or subscribe
- ⚠️ Network effects: More data sources → more accurate reports → more consumer trust → more dealer adoption → more data sources. This flywheel has been compounding for decades.
6. Total addressable market
✅ S&P Global has cited a $30B+ TAM for the automotive data market. This includes:
- Used vehicle data and transparency tools
- New vehicle sales tools and dealer marketing
- Automotive analytics, forecasting, and consulting
- F&I (finance and insurance) technology
- ⚠️ Emerging: EV battery data, connected car analytics, autonomous vehicle data services
⚠️ TAM growth rate estimated at 5-8% annually, driven by:
- Increasing used vehicle transaction volumes
- Digital transformation of dealership operations
- EV transition creating new data needs
- Growing consumer demand for vehicle transparency
7. Geographic competitive map
✅ North America: CARFAX is dominant. The US and Canada represent the vast majority of current revenue.
⚠️ Europe: Fragmented market. HPI (UK), Carvertical (pan-European), ADAC (Germany), and various national services compete. No single dominant player. CARFAX has limited presence.
⚠️ Asia-Pacific: Even more fragmented. Market for vehicle history data is less mature. OEMs and government registries play a larger role.
❓ International expansion potential: Significant long-term opportunity, but requires building data source networks country-by-country. Could accelerate via acquisition of local players.
Financials & Valuation
1. Operating margins vs peers
⚠️ Direct public peers are scarce — most automotive data companies are private divisions or were acquired. Closest comparisons are to other high-margin data/analytics businesses:
| Company | EBITDA Margin | Business type | Relevance |
|---|---|---|---|
| Mobility Global | ~60% | Automotive data monopoly | — |
| Verisk Analytics (VRSK) | ~55% | Insurance data/analytics | ✅ Similar data moat model, similar margins |
| CoStar Group (CSGP) | ~35% | Real estate data/marketplace | ✅ Similar “data + marketplace” structure |
| TransUnion (TRU) | ~35% | Consumer credit data | ⚠️ Data business, but lower margins |
| Cox Automotive (private) | ~20-30% est. | Auto marketplace/auctions | ⚠️ Most direct comp but private; lower margins due to physical auction operations |
| J.D. Power (private) | Unknown | Auto research/consulting | ⚠️ Competitor in analytics but much smaller |
Key insight: Mobility Global’s 60% EBITDA margin is exceptional even among premium data businesses. Verisk is the closest margin comp and trades at 25-30x EBITDA. The margin premium reflects CARFAX’s near-monopoly pricing power and asset-light model.
Correction (July 31, 2026): this comparison inverts on the corrected figure. At 40.6%, Mobility Global does not out-margin Verisk (~55%) — it sits below it, between Verisk and the ~35% cohort (CoStar, TransUnion). It is a strong margin, not an exceptional one, and it does not by itself justify a Verisk-like multiple. The “margin premium” premise of the peer tables in this section and the one below does not hold.
2. Peer financial comparison
⚠️ Limited by lack of direct public peers. Best available comparison using Verisk (VRSK) and CoStar (CSGP) as proxies for high-quality data businesses:
| Metric | Mobility Global | Verisk (VRSK) | CoStar (CSGP) |
|---|---|---|---|
| Revenue | $1.6B | ~$2.8B | ~$2.7B |
| EBITDA Margin | ~60% | ~55% | ~35% |
| Revenue Growth | 8% | ~7% | ~12% |
| Debt/EBITDA | ~2x (at spin) | ~2.5x | ~0.5x |
| ROIC | ❓ Unknown | ~20%+ | ~8% |
| EV/EBITDA | ❓ TBD (not yet trading) | ~25-30x | ~35-40x |
✅ Balance sheet: Now disclosed. Mobility Global’s Form 10 registration statement (the correct SEC form for a spinoff distribution, vs. an S-1 for a cash IPO) was filed publicly May 7, 2026. The company carries ~$2B senior notes (~2x EBITDA, <2.5x gross leverage target) with ~$150M cash and a $500M undrawn revolver — see the Debt structure section below.
❓ Capital efficiency (ROIC, asset turnover): Cannot assess until standalone financials are disclosed.
3. Implied standalone valuation
⚠️ Based on peer multiples and margin profile:
| Scenario | Multiple | EBITDA | Enterprise Value | Notes |
|---|---|---|---|---|
| Conservative | 18x EBITDA | $960M | $17B | RTX/Safran-level multiple (lower due to smaller scale) |
| Base | 22x EBITDA | $960M | $21B | Moderate premium for margin quality |
| Bull | 28x EBITDA | $960M | $27B | Verisk-like multiple for monopoly data assets |
| With acquisition premium | +30-50% | — | $22-40B | If takeout materializes within 12-24 months |
Correction (July 31, 2026) — this ladder is void. Every row rests on a $960M EBITDA estimate that came from applying the erroneous ≈60% margin to ≈$1.6B of revenue. Actual FY2025 adjusted EBITDA is $711M, 26% lower. The table is left standing as what was published; the restated valuation is:
Metric At the July 31, 2026 close ($20.38) Market capitalization $6.01B (294.8M shares) Net debt ≈$1.8B (≈$2B notes less ≈$200M cash) Enterprise value ≈$7.81B EV / Adj. EBITDA 11.0x EV / GAAP EBITDA 12.0x P / FCF 13.0x FCF yield 7.7% The market is valuing Mobility Global at 11.0x, less than the 18x “conservative” floor this ladder assumed — and against an EBITDA base a quarter smaller. The bull-case $27B EV is roughly 3.5x the company’s actual enterprise value. A separate caution on share count: an S-8 registers 46,000,000 shares (15.6% of shares issued) for employee incentive plans; if the full reserve were eventually issued, P/FCF would rise from 13.0x to 15.1x.
4. Debt structure
✅ Confirmed (Form 10 public May 7 + May 12 Investor Day). Mobility Global launched ~$2B senior unsecured notes, funding a one-time cash payment of up to ~$1.95B to S&P Global at separation. Target capital structure: under 2.5x gross leverage, ~$150M cash on hand, and a $500M undrawn revolver. Investment-grade credit rating targeted (confirmed).
⚠️ At ~$2B debt on ~$960M EBITDA, leverage of ~2x is moderate and sits within the stated <2.5x ceiling — leaving ample room for the 75%+ FCF return framework and bolt-on M&A. This is notably lighter than the ~3.0x Honeywell loaded onto Honeywell Aerospace.
Correction (July 31, 2026): on the actual $711M of adjusted EBITDA, $2B of notes is 2.81x gross leverage (2.53x net) — above the company’s own <2.5x target, not comfortably inside it. Mobility Global started life offside its stated ceiling. This is materially different from the “~2x, ample room” characterisation above, and it is one of the two reasons the Financial Profile score fell from 5 to 4. It does self-cure without any repayment: at the guided 8-11% adjusted EBITDA growth, gross leverage reaches 2.57x in 2026 and 2.35x in 2027. Having committed 75%+ of FCF to shareholders, management has structurally allocated cash away from deleveraging — expect the company to grow into the target rather than pay down principal.
5. Post-interest free cash flow
❓ Cannot calculate until debt structure is known. Framework for when Form 10 is public:
- EBITDA: ~$960M
- Less: estimated capex (~$50-100M for asset-light data business)
- Less: interest expense (depends on debt load)
- Less: taxes
- = Free cash flow to equity
⚠️ If debt is ~$2.5B at ~5% coupon: interest ~$125M, pre-tax FCF ~$735-810M. At a $21B equity value, FCF yield ~3.5-4.0%.
6. Valuation framework
⚠️ Given the unknowns, a simplified framework:
- Attractive: Below 18x EBITDA (~$17B EV). Unlikely unless market sells off post-spin (forced selling by index funds).
- Fair: 20-24x EBITDA ($19-23B EV). Reflects high margins but small scale and auto cyclicality.
- Expensive: Above 28x EBITDA ($27B+ EV). Only justified if acquisition is imminent.
7. Dividend strategy
❓ Unknown. No guidance on dividend policy. Possible scenarios:
- ⚠️ Likely: Modest initial dividend (1-2% yield) to attract income-oriented investors, with priority on debt paydown
- ⚠️ Possible: No dividend initially, prioritizing debt reduction and M&A optionality
- ❓ Unlikely: High dividend payout — would limit strategic flexibility and signal limited growth ambitions
Correction (July 31, 2026) — the ❓ items in §5, §6 and §7 above are now answered, and two of the answers differ from the guesses.
- §5 Post-interest FCF: no longer an estimate. FY2025 free cash flow was $461M (26.3% margin, 65% conversion) on capex of just $24M — 1.4% of revenue, well below the “$50-100M” assumed. The projected “$735-810M pre-tax FCF” was a function of the wrong EBITDA. At the actual $461M and a $6.01B market cap, the FCF yield is 7.7% — roughly double the “3.5-4.0%” the framework anticipated, because the equity is worth a third of what was assumed.
- §6 Valuation framework: the “attractive below 18x EBITDA” threshold is superseded. The stock trades at 11.0x.
- §7 Dividend: guidance is now explicit — 20-25% of GAAP net income, buybacks from 2027, 75%+ of FCF returned annually. The “modest 1-2% yield” guess was too high: because GAAP net income is suppressed by $310M of non-cash amortization, a payout set against net income distributes only ~10% of the cash generated, giving a 0.6-0.9% yield. The real capital return is the buyback — total distributions run ≈$1.26-1.29/share, a 6.2-6.3% total shareholder yield, roughly six-sevenths of it repurchases. The “priority on debt paydown” premise was also wrong; see the debt correction above.
Spinoff Deep Dive
1. Prior spins from same parent
✅ This is S&P Global’s first major spinoff. S&P Global was itself formed from the McGraw-Hill spin in 2013 (when McGraw-Hill Education was separated from McGraw-Hill Financial, which became S&P Global). However, the Mobility separation is structurally different — it’s a carve-out of a business unit, not a split of the whole company.
⚠️ The closest precedent is the IHS Markit merger (2022), where S&P Global acquired IHS Markit for $44B and has been integrating/rationalizing overlapping businesses. Spinning off Mobility may partly be about simplifying the post-merger portfolio.
2. Parent motives and capital allocation
✅ Primary motive: Sharpen S&P Global’s identity as a pure-play financial markets data company (ratings, indices, commodities, market intelligence). Mobility’s automotive focus is strategically distinct and dilutes the financial-data narrative.
⚠️ Secondary motive: Unlock conglomerate discount. S&P Global trades at ~25-28x EBITDA; if Mobility trades at a similar or higher multiple separately, total shareholder value increases.
⚠️ Capital allocation signal: The fact that S&P is spinning off (not selling) suggests they believe Mobility is worth more as a public standalone than in a private sale. A sale would have been faster and simpler if the goal was just to exit.
3. RemainCo (S&P Global post-spin)
✅ S&P Global retains its core financial markets businesses:
- S&P Global Ratings: One of the “Big Three” credit rating agencies (with Moody’s and Fitch). Regulatory moat, high margins.
- S&P Dow Jones Indices: Passive investing drives AUM-linked revenue (S&P 500 index licensing). Very high margins.
- S&P Global Commodity Insights (Platts): Energy/commodity pricing benchmarks. Regulatory quasi-moat.
- S&P Global Market Intelligence: Financial data terminals, analytics. Competes with Bloomberg, Refinitiv.
⚠️ RemainCo is arguably a higher-quality business than SpinCo in terms of regulatory moats (ratings) and secular growth (indices/passive investing). However, Mobility Global has higher EBITDA margins and a stronger near-monopoly position in its niche.
4. Potential acquirers (detailed)
✅ See Executive Summary for acquirer table. Additional detail:
Correction (May 31, 2026): The Cox Automotive thesis is retracted — the May 31 report flagged it as unsubstantiated name-confusion with Cox’s own “Mobility” division. The probability previously assigned to Cox is redistributed to the PE path and “remains independent.” The PE consortium is now the most credible acquirer.
| Acquirer | Strategic Fit | Financial Ability | Regulatory Risk | Probability |
|---|---|---|---|---|
| PE consortium (Vista/Thoma Bravo/Silver Lake) | 8/10 | 9/10 | 9/10 | ⚠️ 45% |
| Big Tech (Microsoft/Google) | 6/10 | 10/10 | ⚠️ 5/10 (tech antitrust scrutiny) | ❓ 10% |
| Dealer groups | 7/10 | 5/10 (most are too small) | 8/10 | ❓ 10% |
| Remains independent | — | — | — | ⚠️ 35% |
5. Acquisition probability and premium
⚠️ Estimated ~70-80% probability of takeout within 24 months post-spinoff. The May 31 report softened the headline likelihood from “very high (90%+)” to “high,” reflecting the retraction of the Cox thesis (the 90%+ figure was partly Cox-driven).
⚠️ Expected premium: 30-50% over standalone trading price. CARFAX’s brand value and data moat justify a strategic premium. PE buyers would pay 20-30%; a strategic data/dealer buyer would pay 30-50%.
6. SpinCo as acquirer
⚠️ If Mobility Global remains independent, likely M&A targets include:
- International vehicle history companies (Carvertical, HPI) to expand CARFAX globally
- EV data startups (battery health analytics, charging network data)
- Dealer technology platforms to deepen dealer workflow integration
- ⚠️ Timeline: 12-24 months post-spin minimum (debt paydown first), then bolt-on acquisitions in the $100M-$1B range
7. Structural features
✅ Tax-free spinoff for US federal tax purposes ✅ Targeting investment-grade credit rating ❓ Exchange ratio: TBD ❓ Distribution ratio: TBD ❓ TSA (transition service agreements) with S&P Global: Likely for IT, HR, finance functions during transition. Duration and cost unknown. ❓ Insider lockup periods: Unknown
Investment Thesis
1. Bull case
CARFAX is a generational franchise — a consumer-facing data monopoly with 60% margins, 40 years of irreplaceable data, and deep dealer embedding. As a standalone, Mobility Global re-rates to premium data-company multiples (25-30x EBITDA) and attracts acquisition interest within 12-24 months at a 30-50% premium. EV transition and international expansion provide multi-year growth runway beyond current 8% rate. Total return potential: 50-100% within 2 years.
Correction (July 31, 2026): the bull case above is built on 60% margins and a re-rating to 25-30x EBITDA. At a 40.6% margin, a 25-30x multiple is not the natural landing zone — Verisk earns that multiple on a higher margin and this business does not clear that bar. The bull case survives, but for a different reason than the one stated here. The stock trades at 11.0x EV/EBITDA and 13.0x FCF with a 7.7% FCF yield and a 6.2%+ total shareholder yield; a total-distribution discount model implies $24-42 per share against a $20.38 price. The upside is a cheap multiple on a good business plus a 24%-of-shares-outstanding buyback over five years — not a premium re-rating. The bear case below is essentially intact, and its “S&P Global loads significant debt onto SpinCo” concern proved correct at 2.81x.
2. Bear case
Standalone at $1.6B revenue, Mobility Global is a small-cap data company in a cyclical end-market. If auto sales decline meaningfully, dealer subscriptions churn and consumer report purchases fall. OEMs increasingly collect vehicle data directly via connected car platforms, slowly eroding CARFAX’s information advantage over a 5-10 year horizon. S&P Global loads significant debt onto SpinCo, limiting capital flexibility and suppressing equity returns. No acquisition materializes due to antitrust concerns or valuation disagreements with PE buyers. Total return: flat to -20% over 2 years.
3. Top 3 catalysts (next 12 months)
- ✅ May 7, 2026 — Public Form 10 (filed): Standalone financial statements, debt structure (~$2B notes, <2.5x leverage), and risk factors now public — resolved most ❓ items in this analysis.
- ✅ May 12, 2026 — Investor Day (delivered): Standalone framework laid out — 7.5-10% organic growth, 8-11% adj. EBITDA growth, +50bps/yr margin, 75%+ FCF return, dividend at 20-25% of GAAP net income.
- ⚠️ June 15 record date / July 1 distribution: Forced selling by index funds and investors avoiding automotive exposure could create a buying opportunity in the first 30-60 days of MBGL trading; index inclusion follows.
4. Top 3 risks
- ⚠️ Debt load at spin: If S&P Global assigns heavy debt ($3B+), equity value compression and limited strategic flexibility follow.
- ⚠️ Auto market cyclicality: A recession or meaningful decline in used vehicle transactions would directly impact CARFAX subscription revenue and report volumes.
- ❓ OEM disintermediation over time: Long-term risk that connected car data from OEMs erodes the value of third-party vehicle history reports. Not an imminent threat but a structural question for the 5-10 year thesis.
5. Capital return framework
❓ No guidance available. Expected sequence based on typical spinoff patterns and reported intent:
- Debt management (months 0-12): Prioritize maintaining investment-grade rating. Unlikely to aggressively pay down debt immediately, but will manage within rating agency expectations.
- Dividend initiation (months 0-6): ⚠️ Likely a modest initial dividend (1-2% yield) to broaden investor appeal.
- Buybacks (months 12-24): ⚠️ If trading at a discount to intrinsic value, management may authorize a buyback program.
- M&A (months 18-36): Bolt-on acquisitions once leverage normalizes and standalone operations are stabilized.
Report-by-Report Analysis
Analysis — June 30, 2026
Brief section — the final pre-distribution update. No new financial disclosure; the transaction was de-risked on timing and awaiting the July 1 distribution.
- Grade: A+ (4.60), unchanged. Retained as the report’s #1 ranked name and TOP PICK.
- Timing: record date June 15 passed; when-issued trading (MBGL WI / SPGI WI) ran June 26-30; distribution and first regular-way trading confirmed for July 1, with S&P 500 index treatment to follow. 1 MBGL per 1 SPGI, S&P Global retaining 0%.
- Thesis as stated at the time: “Exceptional ≈60% EBITDA margins, iconic CARFAX brand with near-monopoly in used-car data.” That margin figure was wrong — see the July 31 correction above. It was not caught until the post-spin review.
- Nothing in June contradicted the thesis as it was then understood. No new financials were filed between the May 12 Investor Day and the distribution.
Analysis — May 31, 2026
Full section — Form 10 made public, Investor Day delivered, and final terms (ticker, record/distribution dates) set. The transaction is now fully de-risked on timing.
- Company: S&P Global Inc. (SPGI) — Current Price: ~$424.00 (May 29, 2026)
- SpinCo: Mobility Global, Inc. (ticker MBGL, NYSE)
- Industry: Automotive Data & Technology
- Expected Completion: July 1, 2026
- Structure: Classic Spinoff
- Investment Grade: A+ (Top Pick) — score 4.60
Financial Structure
| Metric | Mobility Global (SpinCo) |
|---|---|
| Revenue | $1.6B |
| EBITDA Margin | ~60% |
| Revenue growth target | 7.5-10% organic |
| Adj. EBITDA growth target | 8-11% |
| Capital structure | ~$2B senior notes, <2.5x gross leverage, ~$150M cash, $500M revolver |
Key Developments Since Last Report
- May 7, 2026: Form 10 publicly filed (previously confidential)
- May 12, 2026: Investor Day in NYC — CEO Bill Eager and CFO-designate Matt Calderone laid out a medium-term framework: 7.5-10% organic revenue growth, 8-11% adj. EBITDA growth, +50bps/yr margin expansion, 75%+ of FCF returned annually, dividend at 20-25% of GAAP net income
- Terms announced: Ticker MBGL (NYSE); record date June 15, 2026; distribution July 1, 2026 (12:01am ET); 1 MBGL per 1 SPGI; S&P retains 0%; when-issued window June 26-30
- ~$2B senior unsecured notes launched to fund a one-time cash payment (up to ~$1.95B) to S&P Global
Management Team
| Role | Name | Notes |
|---|---|---|
| CEO | Bill Eager | President of S&P Global Mobility |
| CFO | Matt Calderone | CFO-designate |
| CAO | Renato Negro | Effective April 6, 2026 |
Transaction Timeline
- February 3, 2026: Rebranded as Mobility Global
- May 7, 2026: Form 10 publicly filed ✅
- May 12, 2026: Investor Day ✅
- June 15, 2026: Record date — deadline to own SPGI to qualify ⚠️
- June 26-30, 2026: When-issued trading
- July 1, 2026: Distribution & first regular-way MBGL trading 📅
Investment Scorecard
| Dimension | Weight | Score | Rationale |
|---|---|---|---|
| Financial Profile | 25% | 5 | ~60% EBITDA margins, 7.5-10% growth, high FCF |
| Competitive Position | 25% | 5 | CARFAX near-monopoly, data moat |
| Strategic Rationale | 20% | 4 | Clear focus-unlock for both entities |
| Management & Governance | 20% | 4 | Full C-suite named, Investor Day delivered |
| Acquisition Potential | 10% | 5 | High-value data asset; multiple credible PE/strategic acquirers |
| Weighted Score | 4.60 | ||
| Investment Grade | A+ | Top Pick |
Grade Change: Unchanged (A+). Form 10 publication, the delivered Investor Day, and a firm July 1 distribution date reinforce the thesis. Correction: prior “Cox Automotive most-likely-acquirer” framing retracted as unsubstantiated (name confusion with Cox’s own “Mobility” division); CARFAX’s underlying acquisition appeal is intact.
Acquisition Analysis
Potential Acquirers: PE data buyers (Vista, Thoma Bravo, Silver Lake); large auto dealer groups; data/AI platforms. Acquisition Likelihood: HIGH. Recommendation: ⭐⭐⭐⭐⭐ STRONG BUY — position before the June 15 record date.
Analysis — April 15, 2026
- Company: S&P Global Inc. (SPGI) — Current Price: ~$432.94 (April 15, 2026)
- SpinCo: Mobility Global, Inc.
- Industry: Automotive Data & Technology
- Expected Completion: Mid-2026
- Structure: Classic Spinoff
- Investment Grade: A+ (TOP PICK)
- Key Thesis: Exceptional 60% EBITDA margins, iconic CARFAX brand with near-monopoly in used car data, high acquisition potential. Investor Day confirmed for May 12, 2026 in New York City.
Transaction Overview
- Original Company: S&P Global — financial information and analytics leader
- SpinCo: Mobility Global, Inc. — CARFAX, automotiveMastermind, Polk, Market Scan ($1.6B revenue, 8% growth)
- RemainCo: S&P Global — ratings, indices, Platts, Market Intelligence
- Rationale: Sharpen RemainCo’s financial-markets focus while giving Mobility standalone autonomy in $30B+ automotive data market
Financial Structure
| Metric | Mobility Global (SpinCo) | S&P Global RemainCo |
|---|---|---|
| Revenue | $1.6B (8% growth YoY) | Majority of S&P |
| EBITDA | ~$960M (trailing 12 months) | Majority |
| EBITDA Margin | 60% | High |
Key Developments Since Last Report
- April 6, 2026: Renato Negro named CAO (reporting to CFO-designate Matt Calderone)
- March 25, 2026: Investor Day formally set for May 12, 2026 in NYC (was referenced as Q2)
- Form 10 remains confidentially filed; public filing expected shortly ahead of May 12 Investor Day
- Public debt offering, equity roadshow still expected Q2 2026
Management Team
| Role | Name | Notes |
|---|---|---|
| CEO | Bill Eager | President of S&P Global Mobility |
| CFO-designate | Matt Calderone | Named March 2026 |
| Chief Accounting Officer | Renato Negro | Effective April 6, 2026 |
| President, CARFAX | Scott Fredericks | Continuing |
| President, Business Solutions | Joe Lafeir | Continuing |
Transaction Timeline
- April 29, 2025: Spinoff announced
- November 13, 2025: S&P Global Investor Day
- February 3, 2026: Rebranded as Mobility Global
- April 6, 2026: CAO appointed
- May 12, 2026: Mobility Global Investor Day
- Mid-2026: Expected separation
- Record date: TBD (late Q2 2026)
Investment Analysis
SpinCo Strengths:
- 60% EBITDA margins — exceptional for data businesses
- CARFAX near-monopoly in used-vehicle history data
- Full C-suite in place — CEO, CFO, CAO, and business-unit presidents named
- 8% revenue growth in mature auto market
- EV transition opens new data opportunities (battery, charging)
- Targeting investment-grade credit rating
SpinCo Risks:
- Cyclical automotive market exposure
- Dealer/OEM building competing data platforms
- Smaller scale as standalone ($1.6B)
SpinCo Catalysts:
- May 12 Investor Day — major pricing-discovery event
- Form 10 public filing imminent
- Q2 public debt offering
- Acquisition potential remains very high
Investment Scorecard
| Dimension | Weight | Score | Rationale |
|---|---|---|---|
| Financial Profile | 25% | 5 | 60% EBITDA margins, 8% growth, high FCF |
| Competitive Position | 25% | 5 | CARFAX near-monopoly, data moat |
| Strategic Rationale | 20% | 4 | Clear focus-unlock for both entities |
| Management & Governance | 20% | 4 | Full C-suite named including CAO, equity comp expected |
| Acquisition Potential | 10% | 5 | Multiple high-probability acquirers (Cox, PE) |
| Weighted Score | 4.65 | ||
| Investment Grade | A+ | Top Pick |
Acquisition Analysis
Potential Acquirers:
- Cox Automotive: Autotrader, KBB, Manheim — obvious strategic combination with CARFAX
- Auto dealer groups (AutoNation, Lithia, CarMax): Want to own customer data
- Microsoft/Google: Automotive data for AI training
- Vista, Thoma Bravo, Silver Lake: High-margin data asset fit
Acquisition Likelihood: VERY HIGH (90%+)
Recommendation: STRONG BUY — Position before May 12 Investor Day and record date announcement.
Analysis — March 2, 2026
Full section — rebrand, Form 10 filing, and SPGI stock reaction are material new developments.
- Company: S&P Global Inc. (SPGI) — Current Price: ~$441.88
- SpinCo: Mobility Global, Inc. (formerly S&P Mobility)
- Investment Grade: A+ (TOP PICK)
Key Developments Since Last Report
- February 3, 2026: Rebranded as Mobility Global, Inc. — SPGI stock slid 10% on the news
- Form 10: Confidentially filed with SEC; public filing expected Q2 2026
- Q2 2026 Planned Events: Investor Day, equity roadshow, public debt offering (targeting investment-grade rating)
- Leadership: Bill Eager confirmed as designated CEO
Financial Structure
| Metric | Mobility Global (SpinCo) | S&P Global RemainCo |
|---|---|---|
| Revenue | $1.6B (8% growth YoY) | Majority of S&P |
| EBITDA | ~$960M (trailing 12 months) | Majority |
| EBITDA Margin | 60% | High |
Investment Analysis
SpinCo Strengths:
- Exceptional 60% EBITDA margins — among highest in data businesses
- CARFAX near-monopoly — iconic brand with decades of vehicle history data
- Data moat — proprietary vehicle history database impossible to replicate
- 8% revenue growth despite mature automotive market
- Full leadership team in place
- Targeting investment-grade credit rating (positive signal)
SpinCo Risks:
- Cyclical automotive market exposure
- Competition from dealers and OEMs building own data platforms
- Smaller scale as standalone ($1.6B revenue)
- SPGI dropped 10% on rebrand announcement — market concerned about losing the asset
SpinCo Catalysts:
- VERY HIGH acquisition potential — CARFAX is strategic asset
- EV transition driving new data/analytics demand
- International expansion (CARFAX primarily US/Canada)
- Q2 Investor Day will be a major catalyst for price discovery
Acquisition Analysis
Potential Acquirers:
- Cox Automotive: Owns Autotrader, Kelley Blue Book, Manheim — consolidate with CARFAX
- Auto dealer groups (AutoNation, Lithia, CarMax): Want to own CARFAX data
- Microsoft/Google: Automotive data for AI training
- Private Equity (Vista, Thoma Bravo, Silver Lake): Love high-margin data businesses
Acquisition Likelihood: VERY HIGH (90%+)
Recommendation: STRONG BUY — Monitor for Q2 2026 Investor Day and public Form 10 filing. Position before record date announcement.
Analysis — January 29, 2026
Full section — full management team announced for the first time, a material milestone.
- Company: S&P Global Inc. (SPGI)
- SpinCo: S&P Mobility
- Expected Completion: Q2 2026
- Investment Grade: A+ (TOP PICK)
Management Team (NEW — Fully Announced)
| Role | Name | Background |
|---|---|---|
| CEO (Designated) | Bill Eager | President of S&P Global Mobility |
| President, CARFAX | Scott Fredericks | Promoted from COO |
| President, Mobility Business Solutions | Joe Lafeir | Former President of Automotive Insights |
| Chief Legal Officer | Tasha Matharu | Deputy General Counsel of S&P Global |
| Chief Information Officer | Joedy Lenz | Former CTO of CARFAX |
| Chief People Officer | Larissa Cerqueira | Former CHRO at Fluence Energy |
POSITIVE SIGNAL: Full C-suite now in place, experienced leadership team assembled.
Financial Structure
| Metric | S&P Mobility (SpinCo) | S&P Global RemainCo |
|---|---|---|
| Revenue | $1.6B (8% growth YoY) | Majority of S&P |
| EBITDA | ~$960M (trailing 12 months) | Majority |
| EBITDA Margin | 60% (exceptional) | High |
Investment Analysis
SpinCo Strengths:
- Exceptional 60% EBITDA margins — among highest in data businesses
- CARFAX near-monopoly — iconic brand with decades of vehicle history data
- Data moat — proprietary vehicle history database impossible to replicate
- 8% revenue growth despite mature automotive market
- Full leadership team now in place
SpinCo Risks:
- Cyclical automotive market exposure
- Competition from dealers and OEMs building own data platforms
- Smaller scale as standalone ($1.6B revenue)
SpinCo Catalysts:
- VERY HIGH acquisition potential — CARFAX is strategic asset
- EV transition driving new data/analytics demand
- International expansion (CARFAX primarily US/Canada)
Acquisition Analysis
Potential Acquirers:
- Cox Automotive: Owns Autotrader, Kelley Blue Book, Manheim — consolidate with CARFAX
- Auto dealer groups (AutoNation, Lithia, CarMax): Want to own CARFAX data
- Microsoft/Google: Automotive data for AI training
- Private Equity (Vista, Thoma Bravo, Silver Lake): Love high-margin data businesses
Acquisition Likelihood: VERY HIGH (90%+)
Recommendation: STRONG BUY — Position for Q1-Q2 2026 record date.
Analysis — October 24, 2025
Summary — initial formal grading and detailed analysis. Core thesis established here; financials unchanged in later reports.
- Investment Grade: A+ (TOP PICK) — first formal grade assigned
- Promoted from #7 to #1 ranking across all tracked spinoffs
- Timeline: Q2-Q3 2026 (narrowed from “Late 2026”)
- Standalone valuation: 15-20x EBITDA = $14-19B market cap
- With acquisition premium (30-50%): $18-28B+ takeout value
- Cox Automotive identified as #1 potential acquirer (Autotrader + KBB + Manheim + CARFAX = automotive data monopoly)
- Silver Lake added to PE acquirer list
- Management team not yet announced (key pending catalyst)
- Full analysis established core thesis: CARFAX near-monopoly, 60% margins, data moat, very high acquisition probability
Analysis — October 23, 2025
Summary — first mention. Brief overview only, pre-grading system.
- Listed as spinoff #7 (not yet prioritized as top pick)
- No formal letter grade — described as “highly attractive” and “could be one of the best spinoff opportunities in 2026”
- Revenue $1.6B, 8% growth, ~$960M EBITDA, ~60% EBITDA margin
- Expected Late 2026 (12-18 months from April 2025 announcement)
- Management team not yet announced
- Acquisition likelihood rated “High” with 30-50% premium potential
- Six potential acquirer categories identified (Cox, dealer groups, big tech, OEMs, financial data cos, PE)
- S&P Global Investor Day November 13, 2025 flagged as key upcoming event