Octave Intelligence OCTV
+27.3%vs Day 1Spinoff of Hexagon (HXGBF) · Classic Spinoff · Dual-Listed · Spun May 28, 2026
Expected return (11/13/2026): -13% Gain to loss: 0.1 : 1Hexagon's software half (ALI, SIG, ETQ, Bricsys). Cases $24.49 / $19.24 / $13.90 on the September DCF; weighted 20/60/20 (proposed), $19.22, -10% at $21.29. The 16% rise since September 8 came with engineering software (PTC bought at a 42% premium). Managers bought $4.7M of stock; no debt due before 2030. Russell rank day October 30, 2026: on the Russell 1000/2000 line. HOLD, target $19.
Current Stats
Post-Spinoff Performance
| Timeline | |
| Spinoff date | May 28, 2026 · Nasdaq NY + STO SDR |
| Days since spinoff | 170 days |
| Structure | Classic Spinoff |
| §355(e) window closes statutory; a tax matters agreement may bar more, and for longer | May 28, 2028 |
| Parent | Hexagon (HXGBF) |
| Day-1 reaction | |
| Day 1 open | $17.45 |
| Day 1 return (open→close) | -2.3% |
| Day 1 price (close) | $17.05 reported $20.35 (unverified) |
| Day 1 range | $16.70 – $17.60 +5.4% spread |
| Day 1 low held? | Breached after 1 session to -7.7% below |
| Price levels | |
| Post-spin low (closing) | $15.50 on Jul 23, 2026 · 56 days post-spin |
| Current price (Nov 13, 2026) | $21.98 |
| Returns | |
| Return vs Day 1 (close) | +28.9% |
| — range by day 1 entry theoretical bounds | +24.9% to +31.6% |
| Return vs post-spin low | +41.8% |
| First-quarter return (≈90d) | +9.1% |
| Versus benchmarks | |
| S&P 500 over same window | +0.5% |
| Shares & ownership | |
| Shares outstanding Jun 30, 2026 | 268,437,788 |
| Diluted average shares the EPS denominator | 268,438,000 |
| Free float | 210,004,250 82% of shares outstanding |
| Held by institutions | 20% insiders 19.8% |
| Share count trend Mar 2026 → Jun 2026 | +0.0% broadly flat |
| Volume & liquidity | |
| Traded per day 20-session median | $35M |
| Normal volume baseline | 1,582,200 shares · now 1.05x |
| Day 1 volume | 1.6x normal · first week 1.6x |
| Decay | half in 20 sessions · normal by 5 |
Computed from split-adjusted closing prices. Returns are total return — (end price + dividends received − start price) ÷ start price — with no reinvestment assumed.
Price History
Closing price, split-adjusted, with volume below. No dividends have been paid, so price return and total return are the same. Source: Yahoo Finance. Data through Nov 14, 2026.
Raw daily price & volume data
| Date | Open | High | Low | Close | Volume | Float | Turnover | Market cap | Dividend | Split |
|---|---|---|---|---|---|---|---|---|---|---|
| 2026-11-13 | $21.35 | $22.02 | $20.96 | $21.98 | 1,938,800 | 210,004,250 | 0.72% | $5.90B | — | — |
| 2026-11-12 | $21.22 | $21.91 | $20.33 | $21.29 | 3,092,800 | 210,004,250 | 1.15% | $5.72B | — | — |
| 2026-11-11 | $21.00 | $21.28 | $20.64 | $21.23 | 1,663,100 | 210,004,250 | 0.62% | $5.70B | — | — |
| 2026-11-10 | $20.91 | $21.25 | $20.64 | $20.94 | 1,686,800 | 210,004,250 | 0.63% | $5.62B | — | — |
| 2026-11-09 | $21.11 | $21.18 | $20.64 | $21.06 | 2,497,800 | 210,004,250 | 0.93% | $5.65B | — | — |
| 2026-11-06 | $20.75 | $21.06 | $20.46 | $20.85 | 1,487,700 | 210,004,250 | 0.55% | $5.60B | — | — |
| 2026-11-05 | $21.32 | $21.32 | $20.75 | $20.98 | 1,692,200 | 210,004,250 | 0.63% | $5.63B | — | — |
| 2026-11-04 | $21.40 | $21.81 | $21.28 | $21.56 | 1,719,400 | 210,004,250 | 0.64% | $5.79B | — | — |
| 2026-11-03 | $20.73 | $21.30 | $20.44 | $21.28 | 1,209,000 | 210,004,250 | 0.45% | $5.71B | — | — |
| 2026-11-02 | $21.54 | $21.80 | $21.00 | $21.16 | 1,491,400 | 210,004,250 | 0.56% | $5.68B | — | — |
| 2026-10-30 | $21.59 | $21.97 | $21.34 | $21.71 | 1,150,600 | 210,004,250 | 0.43% | $5.83B | — | — |
| 2026-10-29 | $21.46 | $21.93 | $21.31 | $21.74 | 1,454,700 | 210,004,250 | 0.54% | $5.84B | — | — |
| 2026-10-28 | $21.51 | $22.17 | $21.50 | $22.11 | 2,373,100 | 210,004,250 | 0.88% | $5.94B | — | — |
| 2026-10-27 | $21.48 | $22.02 | $21.38 | $21.73 | 2,008,200 | 210,004,250 | 0.75% | $5.83B | — | — |
| 2026-10-26 | $21.24 | $21.57 | $20.86 | $21.51 | 1,646,500 | 210,004,250 | 0.61% | $5.77B | — | — |
| 2026-10-23 | $20.58 | $21.42 | $20.40 | $21.29 | 1,511,600 | 210,004,250 | 0.56% | $5.72B | — | — |
| 2026-10-22 | $21.11 | $21.39 | $20.85 | $21.08 | 1,252,600 | 210,004,250 | 0.47% | $5.66B | — | — |
| 2026-10-21 | $20.67 | $21.30 | $20.50 | $21.16 | 1,153,300 | 210,004,250 | 0.43% | $5.68B | — | — |
| 2026-10-20 | $20.26 | $20.55 | $20.14 | $20.49 | 1,585,800 | 210,004,250 | 0.59% | $5.50B | — | — |
| 2026-10-19 | $20.04 | $20.74 | $20.00 | $20.52 | 2,172,600 | 210,004,250 | 0.81% | $5.51B | — | — |
| 2026-10-16 | $20.61 | $20.64 | $19.90 | $20.04 | 1,383,000 | 210,004,250 | 0.52% | $5.38B | — | — |
| 2026-10-15 | $19.85 | $20.75 | $19.79 | $20.68 | 1,492,400 | 210,004,250 | 0.56% | $5.55B | — | — |
| 2026-10-14 | $19.81 | $20.00 | $19.64 | $19.83 | 1,029,300 | 210,004,250 | 0.38% | $5.32B | — | — |
| 2026-10-13 | $20.35 | $20.79 | $20.04 | $20.06 | 1,065,200 | 210,004,250 | 0.40% | $5.38B | — | — |
| 2026-10-12 | $20.55 | $20.87 | $20.45 | $20.53 | 1,532,000 | 210,004,250 | 0.57% | $5.51B | — | — |
| 2026-10-09 | $20.54 | $20.59 | $20.23 | $20.52 | 1,052,300 | 210,004,250 | 0.39% | $5.51B | — | — |
| 2026-10-08 | $19.72 | $20.15 | $19.72 | $20.04 | 1,704,700 | 210,004,250 | 0.64% | $5.38B | — | — |
| 2026-10-07 | $19.60 | $19.84 | $19.24 | $19.72 | 1,482,300 | 210,004,250 | 0.55% | $5.29B | — | — |
| 2026-10-06 | $20.10 | $20.31 | $19.68 | $19.72 | 1,329,600 | 210,004,250 | 0.50% | $5.29B | — | — |
| 2026-10-05 | $19.70 | $20.56 | $19.70 | $20.11 | 1,920,600 | 210,004,250 | 0.72% | $5.40B | — | — |
| 2026-10-02 | $19.00 | $19.11 | $18.74 | $19.03 | 1,409,300 | 210,004,250 | 0.53% | $5.11B | — | — |
| 2026-10-01 | $19.16 | $19.32 | $18.85 | $19.06 | 1,806,400 | 210,004,250 | 0.67% | $5.12B | — | — |
| 2026-09-30 | $18.70 | $19.40 | $18.70 | $18.89 | 1,982,000 | 210,004,250 | 0.74% | $5.07B | — | — |
| 2026-09-29 | $18.36 | $18.73 | $18.14 | $18.63 | 2,149,200 | 210,004,250 | 0.80% | $5.00B | — | — |
| 2026-09-28 | $18.37 | $18.69 | $18.15 | $18.58 | 1,976,000 | 210,004,250 | 0.74% | $4.99B | — | — |
| 2026-09-25 | $18.88 | $19.17 | $18.71 | $18.83 | 1,318,100 | 210,004,250 | 0.49% | $5.05B | — | — |
| 2026-09-24 | $19.50 | $19.53 | $18.86 | $19.05 | 1,958,500 | 210,004,250 | 0.73% | $5.11B | — | — |
| 2026-09-23 | $19.45 | $19.98 | $19.28 | $19.82 | 1,951,000 | 210,004,250 | 0.73% | $5.32B | — | — |
| 2026-09-22 | $19.48 | $19.55 | $18.80 | $19.37 | 2,229,200 | 210,004,250 | 0.83% | $5.20B | — | — |
| 2026-09-21 | $19.05 | $19.87 | $18.75 | $19.21 | 2,957,000 | 210,004,250 | 1.10% | $5.16B | — | — |
| 2026-09-18 | $18.57 | $19.03 | $18.06 | $18.82 | 19,200,800 | 210,004,250 | 7.15% | $5.05B | — | — |
| 2026-09-17 | $18.02 | $18.65 | $17.93 | $18.53 | 2,674,000 | 210,004,250 | 1.00% | $4.97B | — | — |
| 2026-09-16 | $18.40 | $18.58 | $18.13 | $18.27 | 2,474,700 | 210,004,250 | 0.92% | $4.90B | — | — |
| 2026-09-15 | $18.40 | $18.76 | $18.09 | $18.54 | 1,636,100 | 210,004,250 | 0.61% | $4.98B | — | — |
| 2026-09-14 | $18.16 | $19.12 | $18.16 | $18.82 | 2,525,900 | 210,004,250 | 0.94% | $5.05B | — | — |
| 2026-09-11 | $17.30 | $17.85 | $17.14 | $17.73 | 2,629,700 | 210,004,250 | 0.98% | $4.76B | — | — |
| 2026-09-10 | $17.81 | $17.89 | $17.04 | $17.25 | 3,206,300 | 210,004,250 | 1.19% | $4.63B | — | — |
| 2026-09-09 | $18.39 | $18.65 | $17.90 | $17.93 | 1,700,900 | 210,004,250 | 0.63% | $4.81B | — | — |
| 2026-09-08 | $19.18 | $19.18 | $18.33 | $18.39 | 3,155,500 | 210,004,250 | 1.18% | $4.94B | — | — |
| 2026-09-04 | $19.85 | $20.04 | $19.38 | $19.59 | 3,600,500 | 210,004,250 | 1.34% | $5.26B | — | — |
| 2026-09-03 | $19.76 | $20.16 | $19.29 | $19.98 | 2,574,300 | 210,004,250 | 0.96% | $5.36B | — | — |
| 2026-09-02 | $19.30 | $19.46 | $18.59 | $19.00 | 2,648,200 | 210,004,250 | 0.99% | $5.10B | — | — |
| 2026-09-01 | $19.70 | $19.80 | $19.25 | $19.50 | 2,540,500 | 210,004,250 | 0.95% | $5.23B | — | — |
| 2026-08-31 | $20.25 | $20.58 | $19.94 | $20.00 | 2,110,400 | 210,004,250 | 0.79% | $5.37B | — | — |
| 2026-08-28 | $19.07 | $19.89 | $19.07 | $19.85 | 2,990,500 | 210,004,250 | 1.11% | $5.33B | — | — |
| 2026-08-27 | $19.08 | $19.59 | $19.02 | $19.46 | 1,582,200 | 210,004,250 | 0.59% | $5.22B | — | — |
| 2026-08-26 | $17.88 | $18.65 | $17.88 | $18.60 | 1,738,900 | 210,004,250 | 0.65% | $4.99B | — | — |
| 2026-08-25 | $18.37 | $18.82 | $18.05 | $18.25 | 1,281,300 | 210,004,250 | 0.48% | $4.90B | — | — |
| 2026-08-24 | $18.08 | $18.48 | $17.66 | $18.32 | 1,224,500 | 210,004,250 | 0.46% | $4.92B | — | — |
| 2026-08-21 | $18.00 | $18.29 | $17.70 | $18.14 | 1,328,700 | 210,004,250 | 0.49% | $4.87B | — | — |
| 2026-08-20 | $18.21 | $18.34 | $17.92 | $18.14 | 2,710,800 | 210,004,250 | 1.01% | $4.87B | — | — |
| 2026-08-19 | $18.27 | $18.88 | $17.97 | $18.47 | 2,885,900 | 210,004,250 | 1.08% | $4.96B | — | — |
| 2026-08-18 | $17.92 | $18.68 | $17.78 | $18.63 | 2,336,200 | 210,004,250 | 0.87% | $5.00B | — | — |
| 2026-08-17 | $18.50 | $18.54 | $17.73 | $18.02 | 1,646,300 | 210,004,250 | 0.61% | $4.84B | — | — |
| 2026-08-14 | $19.40 | $19.65 | $18.75 | $18.91 | 2,818,600 | 210,004,250 | 1.05% | $5.08B | — | — |
| 2026-08-13 | $19.30 | $19.51 | $18.01 | $18.91 | 3,183,400 | — | 1.19% | $5.08B | — | — |
| 2026-08-12 | $16.66 | $19.62 | $16.66 | $19.08 | 7,793,500 | — | 2.90% | $5.12B | — | — |
| 2026-08-11 | $19.32 | $19.79 | $19.06 | $19.72 | 1,917,500 | — | 0.71% | $5.29B | — | — |
| 2026-08-10 | $19.36 | $19.66 | $19.30 | $19.43 | 2,238,200 | — | 0.83% | $5.22B | — | — |
| 2026-08-07 | $19.51 | $19.86 | $19.49 | $19.68 | 830,400 | — | 0.31% | $5.28B | — | — |
| 2026-08-06 | $19.48 | $19.53 | $19.05 | $19.42 | 818,900 | — | 0.31% | $5.21B | — | — |
| 2026-08-05 | $19.65 | $19.87 | $19.53 | $19.59 | 1,633,400 | — | 0.61% | $5.26B | — | — |
| 2026-08-04 | $19.18 | $19.71 | $19.16 | $19.65 | 1,528,100 | — | 0.57% | $5.27B | — | — |
| 2026-08-03 | $18.48 | $19.25 | $18.44 | $19.13 | 2,925,300 | — | 1.09% | $5.14B | — | — |
| 2026-07-31 | $17.85 | $18.39 | $17.78 | $18.24 | 859,700 | — | 0.32% | $4.90B | — | — |
| 2026-07-30 | $17.46 | $17.99 | $17.31 | $17.97 | 644,000 | — | 0.24% | $4.82B | — | — |
| 2026-07-29 | $17.31 | $17.88 | $17.31 | $17.55 | 936,000 | — | 0.35% | $4.71B | — | — |
| 2026-07-28 | $16.93 | $17.50 | $16.89 | $17.38 | 719,200 | — | 0.27% | $4.67B | — | — |
| 2026-07-27 | $16.72 | $17.00 | $16.64 | $16.99 | 779,600 | — | 0.29% | $4.56B | — | — |
| 2026-07-24 | $16.06 | $16.63 | $15.92 | $16.32 | 1,440,000 | — | 0.54% | $4.38B | — | — |
| 2026-07-23 | $15.55 | $15.84 | $15.41 | $15.50 | 745,200 | — | 0.28% | $4.16B | — | — |
| 2026-07-22 | $16.23 | $16.39 | $15.66 | $15.71 | 829,800 | — | 0.31% | $4.22B | — | — |
| 2026-07-21 | $15.85 | $16.29 | $15.83 | $16.13 | 684,200 | — | 0.25% | $4.33B | — | — |
| 2026-07-20 | $16.04 | $16.19 | $15.93 | $16.07 | 661,500 | — | 0.25% | $4.31B | — | — |
| 2026-07-17 | $16.71 | $16.85 | $16.42 | $16.45 | 1,007,100 | — | 0.38% | $4.42B | — | — |
| 2026-07-16 | $16.87 | $16.96 | $16.59 | $16.88 | 938,600 | — | 0.35% | $4.53B | — | — |
| 2026-07-15 | $16.66 | $17.02 | $16.61 | $17.01 | 540,400 | — | 0.20% | $4.57B | — | — |
| 2026-07-14 | $16.57 | $17.01 | $16.56 | $16.62 | 716,800 | — | 0.27% | $4.46B | — | — |
| 2026-07-13 | $16.66 | $17.03 | $16.51 | $16.95 | 977,900 | — | 0.36% | $4.55B | — | — |
| 2026-07-10 | $17.23 | $17.36 | $16.97 | $17.00 | 1,363,800 | — | 0.51% | $4.56B | — | — |
| 2026-07-09 | $16.72 | $17.25 | $16.69 | $17.23 | 1,106,300 | — | 0.41% | $4.63B | — | — |
| 2026-07-08 | $16.69 | $16.93 | $16.61 | $16.92 | 876,800 | — | 0.33% | $4.54B | — | — |
| 2026-07-07 | $18.15 | $18.23 | $17.23 | $17.40 | 966,700 | — | 0.36% | $4.67B | — | — |
| 2026-07-06 | $17.30 | $18.38 | $17.21 | $18.24 | 1,036,100 | — | 0.39% | $4.90B | — | — |
| 2026-07-02 | $17.23 | $17.66 | $17.17 | $17.40 | 661,200 | — | 0.25% | $4.67B | — | — |
| 2026-07-01 | $16.50 | $17.17 | $16.50 | $17.01 | 628,900 | — | 0.23% | $4.57B | — | — |
| 2026-06-30 | $16.22 | $16.35 | $15.87 | $16.30 | 502,500 | — | 0.19% | $4.38B | — | — |
| 2026-06-29 | $16.19 | $16.61 | $16.01 | $16.48 | 1,462,400 | — | 0.54% | $4.42B | — | — |
| 2026-06-26 | $16.09 | $16.29 | $15.86 | $16.28 | 815,400 | — | 0.30% | $4.37B | — | — |
| 2026-06-25 | $16.02 | $16.44 | $15.98 | $16.37 | 852,800 | — | 0.32% | $4.39B | — | — |
| 2026-06-24 | $16.40 | $16.50 | $15.68 | $16.02 | 1,036,400 | — | 0.39% | $4.30B | — | — |
| 2026-06-23 | $15.85 | $16.53 | $15.84 | $16.46 | 1,437,600 | — | 0.54% | $4.42B | — | — |
| 2026-06-22 | $16.08 | $16.13 | $15.61 | $15.65 | 1,634,600 | — | 0.61% | $4.20B | — | — |
| 2026-06-18 | $16.38 | $16.71 | $15.90 | $16.60 | 4,666,400 | — | 1.74% | $4.46B | — | — |
| 2026-06-17 | $17.05 | $17.06 | $16.53 | $16.54 | 1,419,400 | — | 0.53% | $4.44B | — | — |
| 2026-06-16 | $17.67 | $17.73 | $16.89 | $16.94 | 2,021,700 | — | 0.75% | $4.55B | — | — |
| 2026-06-15 | $17.90 | $18.26 | $17.67 | $18.00 | 1,081,300 | — | 0.40% | $4.83B | — | — |
| 2026-06-12 | $18.56 | $18.69 | $17.36 | $17.60 | 2,416,300 | — | 0.90% | $4.72B | — | — |
| 2026-06-11 | $19.01 | $19.25 | $18.33 | $18.33 | 3,392,400 | — | 1.26% | $4.92B | — | — |
| 2026-06-10 | $19.42 | $20.44 | $19.20 | $19.92 | 5,410,200 | — | 2.02% | $5.35B | — | — |
| 2026-06-09 | $20.44 | $20.73 | $19.57 | $19.81 | 1,796,500 | — | 0.67% | $5.32B | — | — |
| 2026-06-08 | $19.99 | $22.70 | $19.04 | $21.77 | 1,886,500 | — | 0.70% | $5.84B | — | — |
| 2026-06-05 | $19.62 | $19.63 | $18.05 | $18.71 | 1,300,000 | — | 0.48% | $5.02B | — | — |
| 2026-06-04 | $20.90 | $20.90 | $18.00 | $19.97 | 1,059,200 | — | 0.39% | $5.36B | — | — |
| 2026-06-03 | $25.06 | $27.39 | $18.88 | $19.74 | 1,978,500 | — | 0.74% | $5.30B | — | — |
| 2026-06-02 | $20.42 | $25.34 | $20.30 | $25.11 | 3,382,700 | — | 1.26% | $6.74B | — | — |
| 2026-06-01 | $17.23 | $20.86 | $17.23 | $20.02 | 1,975,500 | — | 0.74% | $5.37B | — | — |
| 2026-05-29 | $17.39 | $17.75 | $16.65 | $17.20 | 3,079,200 | — | 1.15% | $4.62B | — | — |
| 2026-05-28 | $17.45 | $17.60 | $16.70 | $17.05 | 2,552,100 | — | 0.95% | $4.58B | — | — |
Close is split-adjusted to current shares. It is not dividend-adjusted: dividends are listed separately, so total return is (end price + dividends received − start price) ÷ start price, checkable by hand. Volume is as-traded.
Momentum: MACD and RSI
Top: MACD (navy) and its signal line (gold); bars show the gap between them, teal when MACD is above.
Bottom: RSI over 14 days; above 70 is usually read as overbought and below 30 as oversold.
The lines start late because MACD needs 26 trading days of prices and RSI 14 before the first value.
The colored strip under the charts shows the state label day by day; hover for the state and the reason.
Both measure momentum in the price and say nothing about value. Hover for each day's arithmetic.
Source: closing prices from this site's daily price archive (Yahoo Finance), not adjusted for dividends. Data through Nov 14, 2026.
How these are calculated
Short Selling
Bars: shares sold short each day in trades reported to FINRA (off-exchange
trades, roughly half of all volume).
Line: the short share of that volume, averaged over 20 sessions.
Gold points: short interest, the shares sold short and not yet bought back,
reported twice a month, also shown as a percentage of the free float and of
shares outstanding.
Daily short volume includes market makers' routine hedging, so a change in the
share is more informative than its level. Hover for each day's figures.
Sources: FINRA; float from this site's daily share records; shares outstanding
from the company's latest quarterly filing. Data through Nov 13, 2026.
Update — October 26, 2026: the scenarios, the money, the debt and who is trading — HOLD, target $19.50 → $19
Written against the October 23, 2026 close of $21.29. Sources: the second-quarter 2026 10-Q and results release (August 12, 2026), the information statement, the credit agreement, the tax disaffiliation agreement with Hexagon, Octave’s notices of managers’ share dealings, the SEC’s 13F data sets, FINRA short interest, MSCI’s and FTSE Russell’s index notices, and the Q2 call transcript. Peer prices are Yahoo closes; Octave’s prices and volumes are from this site’s own archive (the Nasdaq line). The September 8 analysis below is left as published. This section turns its valuation into three scenarios with weights, and adds stress tests, the money, the debt, the sites, who has been trading, short interest and volatility. No results have been reported since; third-quarter results are due Thursday, November 12, 2026, before the open.
The one-line version
Octave is priced a little above what it is worth on the September method: about $19 a share, against $21.29. Weighted 20% best, 60% base and 20% worst (proposed), the scenarios are worth $19.22, an expected return of −10%, with 24 cents of probability-weighted gain for each dollar of loss. The price implies 40% on the best case and nothing on the worst.
The 16% rise since September 8 came with the sector. Engineering software rose 23% over the same weeks, helped by Schneider Electric’s agreement on October 5 to buy PTC for $22.6 billion in cash. Octave’s low, $17.25 on September 10, followed MSCI’s move of the stock from its standard Sweden index to Sweden Small Cap on August 31.
The swing factor is the discount rate. At 8.5% instead of 9.0% the base case is worth $20.97, about the price; the cases’ revenue and margin assumptions are unchanged since September.
The debt is small and floating: $646 million, almost none of it due before May 2030, one covenant at 3.5 times leverage against about 0.8 times today. Insiders have only bought: 255,140 shares for $4.7 million between June 5 and September 11. One data correction: the September analysis said a sale of Octave was constrained until May 22, 2028; nothing Octave has filed contains that restriction.
What happened since September 8
| Date | What happened | Stock that day | Read |
|---|---|---|---|
| Sep 10 | Closing low since the analysis, $17.25 | −3.8% | The tail of MSCI’s August 31 move of the Stockholm line from MSCI Sweden to MSCI Sweden Small Cap (deletions, additions): standard-index funds sold, small-cap funds bought fewer |
| Sep 10–11 | COO Scott Moore buys 15,000 shares at $17.43; a finance vice president 1,000 at $17.37 | −3.8%, +2.8% | Bought at the low; see Who has been trading |
| Sep 14 | Software rallies as money moves out of chip stocks | +6.1% | IGV +5.0% the same day |
| Sep 17 | Morgan Stanley starts at Equal-weight, $21 (report): the product lines are “only partially integrated” | +1.4% | Close to this page’s view |
| Sep 18 | S&P quarterly rebalance and options expiry; added to the S&P Total Market Index (reported by S&P Capital IQ) | +1.6% | 19.2 million shares, eleven times the period’s median |
| Oct 5 | Schneider Electric agrees to buy PTC for $22.6 billion in cash, about a 42% premium (report) | +5.7% | Engineering software rerated; a strategic buyer paid for an industrial software franchise growing slowly |
| Oct 6 | Third-quarter results set for November 12 | −1.9% | |
| Oct 15 | ARC Advisory names Octave a leader in asset management software | +4.3% | Autodesk +6.1% the same day |
| Oct 23 | Closing high since the analysis, $21.29 | +1.0% |
How the money moves
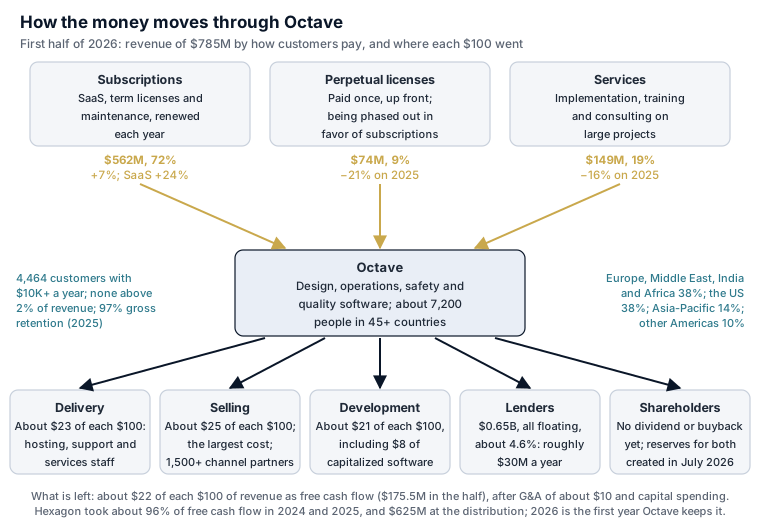
Who pays:
- Subscribers, 72% of first-half revenue ($562 million, +7%): SaaS (+24%), term licenses and maintenance, renewed each year. Gross retention was 97% and net retention 105% in 2025.
- Buyers of perpetual licenses, 9% ($74 million, −21%): the line being phased out in favor of subscriptions. Management said in August that large perpetual deals in public safety may slip into 2027, which is why it cut 2026 organic growth guidance to 0–2% from 3–4%.
- Services, 19% ($149 million, −16%): implementation and consulting on large projects.
- No customer is more than 2% of revenue. 4,464 customers pay $10,000 a year or more and 421 pay $500,000 or more; more than 1,500 channel partners resell. Europe, the Middle East, India and Africa were 38% of first-half revenue and grew 9%; the United States was 38% and fell 11%.
Where each $100 of revenue went, first half of 2026 (January 1 to June 30, 2026, as reported). About $22 of each $100 of revenue became free cash flow, the company’s own figure ($175.5M, 22%). Sales and marketing is the largest cost, as for most software companies selling to large customers. The company’s adjusted margin of about 30% leaves out the amortization of software it capitalizes; counted as cash spent, that software costs about $8 of each $100. In 2024 and 2025 Hexagon took about 96% of the business’s free cash flow; 2026 is the first year Octave keeps its own. Source: the second-quarter 2026 10-Q and results release; per-$100 figures are calculations.
About $22 of each $100 of revenue became free cash flow in the first half, the company’s own figure ($175.5 million). The company’s adjusted operating margin of about 30% leaves out the amortization of software it capitalizes; counted as cash when it is spent, that software costs about $8 of each $100. Hexagon took about 96% of the business’s free cash flow in 2024 and 2025 and $625 million at the distribution; 2026 is the first year Octave keeps its own.
The debt, tranche by tranche
All of the debt was raised to pay Hexagon $625 million at the distribution. It is unsecured, floating and unhedged, and none of it amortizes.
| Tranche | Amount ($M) | Rate | Matures | Repaying early | Security | Notes |
|---|---|---|---|---|---|---|
| U.S. dollar term loan | 350 | Term SOFR + 1.25% (1.25–1.75% by net leverage); 4.9% at June 30 | About May 22, 2030 (four years from closing) | At any time, without premium | Senior unsecured | No scheduled amortization |
| Euro term loan (€150M) | 171 | EURIBOR + 1.25% (1.25–1.75% by net leverage); 3.4% at June 30 | About May 22, 2030 | At any time, without premium | Senior unsecured | No scheduled amortization; the dollar amount moves with the exchange rate |
| Revolver borrowings (dollar and euro) | 102 | Term SOFR or EURIBOR + 1.25% | April 27, 2031 | At any time | Senior unsecured | $73.5M and $28.5M (euro) at June 30; about $57M repaid on July 1 from the headquarters sale |
| Other short-term borrowings | 23 | Not disclosed | Within a year | — | — | As listed in the 10-Q |
| Total drawn | 646 | about 4.6% (the 10-Q’s stated rates: 4.9% on dollar borrowings, 3.4% on euro borrowings); all floating, none hedged | ||||
| Revolving credit | $500M | Term SOFR, EURIBOR or SONIA + 1.25–1.75%; 0.15–0.25% on the unused amount, by net leverage | April 27, 2031, with two one-year extension options | Senior unsecured | $102M at June 30, 2026; about $45M after the July 1 repayment (an estimate) | |
| Incremental facility | $250M | To be agreed | — | Senior unsecured | Not drawn |
The debt was raised to pay Hexagon $625.0 million at the distribution on May 22, 2026: both term loans in full, plus about $120 million and €25 million of revolver borrowings. On July 1, 2026 Octave sold its Madison, Alabama headquarters for about $57.3 million, leased part of it back, and used the proceeds to repay revolver borrowings. No interest-rate or currency hedges are disclosed. Source: the credit agreement, the information statement and the second-quarter 2026 10-Q. As of June 30, 2026.
Principal due by year, including scheduled amortization. Apart from $23 million of short-term borrowings, nothing is due before May 2030: the term loans have no scheduled amortization and are repaid in one payment at maturity; the revolver runs to April 2031, with two one-year extension options.
Apart from $23 million of short-term borrowings, nothing is due before May 2030, and every case repays the debt from cash. Comparing the cash available with the debt due (estimates; free cash flow from the cases):
| Base case | Worst case | |
|---|---|---|
| Free cash flow, July 2026–May 2030 | ~$1.40B | ~$1.17B |
| Cash at June 30, 2026 | + ~$0.30B | + ~$0.30B |
| Headquarters sale, July 1, 2026 | + ~$0.06B | + ~$0.06B |
| Available by the term loans’ maturity | = ~$1.76B | = ~$1.53B |
| Term loans due about May 2030 | − ~$0.52B | − ~$0.52B |
| Revolver and other borrowings | − ~$0.13B | − ~$0.13B |
| Cash left after repaying everything | = ~$1.11B | = ~$0.88B |
No buyback, dividend or acquisition is assumed. Octave has none authorized, but the High Court of Ireland approved a $6.0 billion capital reduction on July 23, 2026, which creates the distributable reserves an Irish company needs before it can buy back shares or pay dividends.
Interest expense, 2027–2029
All of the debt floats, about two-thirds of it on SOFR. On the SOFR path priced in fed funds futures on October 9, 2026, as on the site’s other profiles, with euro rates held at the 10-Q’s 3.4% (all figures estimates, $ millions):
| $ millions | 2027 | 2028 | 2029 |
|---|---|---|---|
| SOFR, yearly average | ~4.40% | ~4.65% | ~4.65% |
| Dollar term loan, $350M at SOFR + 1.25% | $20 | $21 | $21 |
| Euro term loan, €150M at about 3.4% | + $6 | + $6 | + $6 |
| Revolver, about $45M drawn, and the unused fee | + $3 | + $3 | + $3 |
| Interest expense | = ~$29 | = ~$30 | = ~$30 |
Each point of SOFR costs about $4 million a year, about 1 cent a share after tax; the interest bill is about 8% of free cash flow.
| Covenant | Limit | Now | Room | Protects |
|---|---|---|---|---|
| Net leverage (net debt over EBITDA as the agreement defines it) | 3.50× at most; 4.00× for the quarter of an acquisition of $275M or more and the three quarters after, with two quarters between step-ups. Cash netted is capped at $200M | ~0.8× (an estimate: $339.9M of net debt at June 30 over about $440M of EBITDA) | EBITDA could fall by about three-quarters, or debt rise by about $1.2 billion, before 3.50× | All the bank debt |
| Interest coverage | None | — | — | — |
| Dividends and buybacks | Permitted by the credit agreement within its general baskets; under Irish law they need distributable reserves, created by a $6.0 billion capital reduction approved by the High Court on July 23, 2026 | None paid or authorized | — | Credit agreement; Irish company law |
| Mergers and buybacks (tax agreement with Hexagon) | None: the tax disaffiliation agreement filed with the closing 8-K contains no restriction on buybacks, mergers or share issues, and no restricted period | — | — | — |
The agreement’s EBITDA adds back items such as restructuring, so the reported ratio may be lower than this estimate. No credit ratings are disclosed in the filings.
The covenant does not bind in any case. Net leverage is about 0.8 times against 3.5 times; EBITDA could fall by three-quarters before it mattered. The covenant does shape acquisitions: it rises to 4.0 times for four quarters after a purchase of $275 million or more, room for about $1.4 billion of new debt on today’s EBITDA.
Where Octave is
Octave runs from Madison, Alabama, with development concentrated in the United States, India, Israel, the United Kingdom, Germany and Switzerland. The Form 10 names only the larger sites: leased sites in Hyderabad, Munich, Houston and Nesher, Israel, and owned or long-leased sites in Huntsville, Cobham, Swindon and Runcorn. The headquarters campus in Madison was sold on July 1, 2026 for about $57.3 million and part of it leased back. Other points come from Octave Federal’s contact page and news reports; ETQ’s and Bricsys’s addresses date from before the spin, and four Indian offices come from one magazine article, so those are shown as unconfirmed.
About 7,200 employees in more than 45 countries at December 31, 2025, about 2,200 of them in the United States and about 1,800 in India. Most sites are leased; the Form 10 names the larger ones. Development is concentrated in the United States, India, Israel, the United Kingdom, Germany and Switzerland (no Swiss site is named, so none is shown). Click a point for details. Map data © OpenStreetMap contributors. Source: the Form 10 information statement (Properties), the Q2 2026 10-Q, Octave Federal’s contact page and news reports; points geocoded with OpenStreetMap, or at the city centre where no address was found. As of October 26, 2026.
Europe, the Middle East, India and Africa together were 38.5% of first-half 2026 revenue ($302.0M) and the one region that grew (+9.5%). The United Kingdom sites carry the old Intergraph businesses; Nesher has been a development centre since 1999; Bricsys develops its design software in Ghent. Click a point for details. Map data © OpenStreetMap contributors. Source: the Form 10 information statement (Properties), the Q2 2026 10-Q, Octave Federal’s contact page and news reports; points geocoded with OpenStreetMap, or at the city centre where no address was found. As of October 26, 2026.
- About 7,200 employees in more than 45 countries at December 31, 2025, about 2,200 of them in the United States and 1,800 in India; about 2,300 work in research and development. The Hyderabad centre opened in August 2026, with a target of 2,000 engineers (news reports).
- Revenue by customer location, first half of 2026: Europe, the Middle East, India and Africa $302.0 million (38%, +9%), the United States $297.1 million (38%, −11%), Asia-Pacific $110.4 million (14%, −3%), other Americas $75.4 million (10%, +2%).
- Ireland is the legal home only: Octave is incorporated and tax-resident there, with no material operations, and it files in the United States as a foreign private issuer that chooses domestic forms.
The scenarios and the asymmetry
The cases. Each is valued on the September 8 method: revenue by line from 2025 (subscriptions, licenses, services), free cash flow as a margin of revenue moving to its 2030 level, a five-year cash-flow valuation at 9.0% with a terminal value, less June 30 net debt, on 268.4 million shares. The model reproduces the September base case ($19.24 against the published $19.27) and the published sensitivity tables to within four cents before anything changes.
| Case | What it assumes | 2030 revenue / FCF margin | Value | vs $21.29 |
|---|---|---|---|---|
| Best | Subscriptions grow 8.6% a year, their 2024–25 pace, and the free cash flow margin reaches 24%, above the best year on record (22.3%) and in line with management’s aim of a 3–4 point improvement; terminal growth 3.0% | $2,018M / 24.0% | $24.49 | +15% |
| Base | The September 8 base case, unchanged: subscriptions +7.5%, licenses −30%, services −2%; the margin at 21%, the middle of 2023–25 | $1,909M / 21.0% | $19.24 | −10% |
| Worst | The slowdown is lost share, as the September bear case put it: subscription growth fades from 6% to 3%, licenses −35%, services −5%; 2026 below the guidance; the margin at 18.5%; terminal growth 2.0% | $1,647M / 18.5% | $13.90 | −35% |
Stress tests, one change at a time on the base case (estimates):
| Change | Value | vs $21.29 |
|---|---|---|
| Discount rate 8.0% instead of 9.0% | $23.02 | +8% |
| Discount rate 8.5% | $20.97 | −2% |
| Between base and best: subscriptions +8%, margin 22.5% | $20.89 | −2% |
| Margin 22.3%, the best year (2024) | $20.35 | −4% |
| Subscriptions +8.6% a year, the 2024–25 pace | $20.02 | −6% |
| Licenses fall 45% a year (the run-off ends sooner) | $18.96 | −11% |
| The margin held at the guided 20% | $18.39 | −14% |
| Subscriptions +6.0% a year | $18.24 | −14% |
| Between base and worst: subscriptions fade to 5%, margin 19.5% (2025) | $17.06 | −20% |
| Discount rate 10.0% | $16.47 | −23% |
The largest single factor is the discount rate: one point moves the value by about $3.80. Engineering software rerated in September and October, which in this method shows as a lower rate; at 8.5% the base case and the price meet. A sale is the other route to more value: at PTC’s premium of about 42%, applied to the base case, the shares would be worth about $27.
Three weightings, and what the price implies. The standard set, 25 / 50 / 25, and the stress set, 10 / 40 / 50, are the same for every company; the best guess drives the target and the two chips at the top of the page.
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $19.22 | −10% | 0.28 to 1 |
| Best guess (proposed): 20 / 60 / 20 | $19.22 | −10% | 0.24 to 1 |
| Stress: 10 / 40 / 50 | $17.10 | −20% | 0.07 to 1 |
| What the price implies: 40 / 60 / 0 | $21.29 | 0% | 1.0 to 1 |
The weights are a judgement. All values are estimates from the model.
Why the best guess:
- The best case gets 20%, a little below the standard 25%. It needs subscriptions to hold their 2024–25 pace and a margin above any year on record at the same time. For it: management kept its medium-term targets in August (ARR growth above 10%, revenue growth of 6–8%, the free cash flow margin up 3–4 points), insiders bought $4.7 million of stock, and retention is high. Against it: revenue growth has slowed four years running (4.1%, 1.3%, guided 0–2%), and the guidance was cut in August.
- The base case takes 60%: first-half ARR grew 7%, inside the 6–8% guidance, and the guided 20% margin is the three-year record.
- The worst case takes 20%, below the standard 25%: 97% gross retention and no customer above 2% of revenue make a fast loss of the base unlikely. It stays at 20% because the slowdown predates the spin, the two material weaknesses in internal control are not yet remediated, and Melker Schörling AB can require Octave to register its shares for sale from May 2027.
- The price implies 40% on the best case and none on the worst. The gap from the best guess reflects the sector’s rerating; Octave has reported nothing new since August.
- Evidence that would move the weights at the November 12 results: third-quarter revenue at or above $405 million with organic growth of 2–4%, ARR on course for $1.19–1.21 billion, and a buyback authorized (best case up); revenue below the guide, ARR growth below 6%, or the public-safety deals slipping further (worst case up).
What the price implies. Holding the base case at its 60% weight, the price solves
best weight × $24.49 + 60% × $19.24 + (40% − best weight) × $13.90 = $21.29
for a best weight of ($21.29 − 60% × $19.24 − 40% × $13.90) ÷ ($24.49 − $13.90) = 40%, leaving 0% on the worst case.
The asymmetry on the best guess:
| Measure | At $21.29 | What it means |
|---|---|---|
| Expected return (header chip) | −10% | The probability-weighted value, $19.22, against the price |
| Gain to loss (header chip) | 0.24 to 1 | +$0.64 of probability-weighted gain against −$2.71 of loss |
| Expected base-case gain ÷ expected worst-case loss | 0 to 1 | The base case is itself a loss of $2.05 |
| Best-case gain ÷ worst-case loss | 0.43 to 1 | +$3.20 against −$7.39 |
| Base-case gain ÷ worst-case loss | −0.28 to 1 | −$2.05 against −$7.39 |
How the measures are calculated. Gain = case value − price; loss = price − case value. Weights are the best guess: 20% best, 60% base, 20% worst.
| Measure | Formula | At $21.29 |
|---|---|---|
| Expected return | (20% × best + 60% × base + 20% × worst) ÷ price − 1 | ($4.90 + $11.55 + $2.78) ÷ $21.29 − 1 = −10% |
| Gain to loss | (20% × best gain) ÷ (60% × base loss + 20% × worst loss) | $0.64 ÷ ($1.23 + $1.48) = 0.24 |
| Expected base ÷ expected worst | (60% × base gain) ÷ (20% × worst loss) | $0 ÷ $1.48 = 0 |
| Best ÷ worst | best gain ÷ worst loss | $3.20 ÷ $7.39 = 0.43 |
| Base ÷ worst | base gain ÷ worst loss | −$2.05 ÷ $7.39 = −0.28 |
| Price-implied best weight, base at 60% | (price − 60% × base − 40% × worst) ÷ (best − worst) | ($21.29 − $11.55 − $5.56) ÷ $10.59 = 40% |
The header chips are green at +25% or more and 3 to 1 or better, blue at +10–25% and 2–3 to 1, orange at 0–10% and 1–2 to 1, and red below zero and below 1 to 1. On the best guess, expected return is green below $15.38, blue up to $17.48 and orange up to $19.22; gain to loss is green below $17.70, blue up to $18.34 and orange up to $19.22. Both are red above $19.22, and so both are red at $21.29.
Who has been trading Octave
Since September 8 Octave rose with engineering software, by a little less. Rebased to the September 8 close:
Closing prices rebased to September 8 = 100. Baskets are equal-weighted, in local currency: engineering software (Bentley, Autodesk, PTC, Trimble, Nemetschek, Dassault Systèmes); Hexagon, the former parent; software and the S&P 500 through their ETFs (IGV, SPY). Frankfurt, Paris and Stockholm closes are carried to the New York session. Source: Yahoo Finance closes.
| From the close of | Octave | Engineering software | Hexagon | Software (IGV) | S&P 500 |
|---|---|---|---|---|---|
| September 8 to September 10 | −6.2% | −3.1% | −1.6% | −1.4% | −1.1% |
| September 10 to October 23 | +23.5% | +26.5% | +13.2% | +9.2% | +0.6% |
| September 8 to October 23 | +15.8% | +22.6% | +11.4% | +7.7% | −0.5% |
Equal-weighted baskets in local currency: engineering software is Bentley, Autodesk, PTC, Trimble, Nemetschek and Dassault Systèmes; Hexagon is the former parent. Frankfurt, Paris and Stockholm closes are carried to the New York session. Yahoo closes.
Octave moves with software more than with its former parent: its daily returns since September 8 correlate 0.70 with IGV’s, 0.50–0.62 with each engineering-software peer’s and 0.24 with Hexagon’s. PTC’s takeover accounts for much of the basket’s lead; without PTC the basket rose about 18%.
Daily volume (bars) and cumulative volume as a share of the 268.44 million shares outstanding (line). Gold bars mark days with a notable event; hover over one to see what happened. Source: this site's daily price archive (Yahoo Finance), through Oct 23, 2026.
29% of the shares traded on Nasdaq in 33 sessions (a median of 1.7 million a day), with the Stockholm line trading separately. The one heavy day was September 18, an index and options day.
Index flows have gone both ways, because the index providers disagree on where Octave belongs.
- FTSE treats it as American: it changed Octave’s nationality from Sweden to the United States and replaced the Stockholm line with the US line in its indexes from June 1, 2026 (notice).
- MSCI treats it as Swedish: it kept the Stockholm line in MSCI Sweden and moved it to Sweden Small Cap at the August 31 close, a net sale by index funds.
- S&P added it to its Total Market Index in September (reported); it is not in the S&P 500, 400 or 600, and the second-quarter impairment probably keeps it out of them under S&P’s earnings test until that quarter drops out.
- The next event is the Russell reconstitution. Rank day is Friday, October 30, 2026; preliminary lists follow on November 13 and the change takes effect after the close on December 11 (schedule). Octave was not listed at the June rank day, so it would enter as a new member. At about $5.7 billion it sits on the line between the Russell 1000 and the Russell 2000, which was about $5.7 billion in June (summary). A place in the Russell 2000 would bring several times the index buying of a place in the Russell 1000 (estimates: about $550–800 million against $135–225 million), because small-cap funds hold a larger share of each company. Its eligibility as a US company is an inference from FTSE’s classification, not yet announced.
Who holds it. Most Swedish holders own the Stockholm receipts, which 13F filings do not show, so the picture comes in two parts:
| Holder | Position | Source |
|---|---|---|
| Melker Schörling AB | 58.43M (21.8%; all the Class A shares, 42.9% of the votes) | Schedule 13D, June 1, 2026 |
| Swedbank Robur funds | 10.93M at June 30, against 17.08M implied by its Hexagon holding | Swedish fund-holdings filings, Q2 2026 |
| Handelsbanken funds | 9.81M, against 6.72M implied | Same |
| SEB funds | 6.98M, against 4.69M implied | Same |
| Carnegie funds (incl. Didner & Gerge) | 5.66M, against 3.27M implied | Same |
| Madison Avenue Partners | 4.22M | 13F, June 30 |
| Koch, Inc. | 3.00M | 13F, June 30 |
| Länsförsäkringar funds | 2.74M | 13F, June 30 |
Implied positions are Hexagon holdings at March 31, 2026 divided by ten. The third-quarter 13F filings arrive by about November 14, and the Swedish fund filings later.
- Swedish funds as a group bought: they held 50.1 million shares at June 30 against 48.7 million implied by their Hexagon holdings. Swedbank Robur sold about 6.1 million; Handelsbanken, SEB, Carnegie and Lannebo bought.
- Koch, Inc. held 3.0 million shares at June 30. Octave’s chair is the president of Koch Equity. Event-driven funds (Madison Avenue Partners, Newtyn) also appear among the largest 13F holders.
- Managers have bought 255,140 shares for about $4.73 million since the spin, at an average of $18.53, and no manager or director has sold: the chief executive 120,000 (including 100,000 at $18.54 on June 5), the chief operating officer 111,000, the chief legal officer 11,040, the chief people officer 2,500 and a finance vice president 10,600. Octave is a foreign private issuer, so these are reported under the EU’s market-abuse rules, not on Form 4.
- No buyback is authorized, and none was possible before the July capital reduction.
Short interest and volatility
The tables below show how much of the stock is sold short and how much the price moves. They are inputs to the weights above, and the tables update with the nightly data.
| Report | Settled | Short | % float | % outst. | Days to cover |
|---|---|---|---|---|---|
| First after the spin | May 29, 2026 | 1.81M | 0.9% | 0.7% | 2.4 |
| Lowest since the spin | Jun 30, 2026 | 0.73M | 0.3% | 0.3% | 1.0 |
| Three months earlier | Jul 15, 2026 | 1.04M | 0.5% | 0.4% | 1.2 |
| At the valuation | Oct 15, 2026 | 4.39M | 2.1% | 1.6% | 3.2 |
| Latest | Oct 30, 2026 | 3.16M | 1.5% | 1.2% | 2.0 |
The latest share of float is higher than 7 of the 10 earlier reports since the spin. Short interest in shares, with its share of the float and of shares outstanding. FINRA settlement dates; figures are published about eight business days later. Days to cover is short interest divided by average daily volume, as reported by FINRA. Float and shares outstanding on or before each date, from this site's daily share records and the company's filings.
Short interest rose fivefold after the second-quarter results, from 1.0 million shares on July 31 to 5.3 million (2.0% of the shares) on September 30, about one and a half days of average volume. The rises came around the results and the index changes (August 14, August 31, September 30), which is the pattern of hedging and of trading between the Stockholm and New York lines. No position appears in the Swedish regulator’s register of net short positions. The October 15 figure is due about October 27.
| Volatility, annualized | Last 20 sessions | Last 60 sessions | Since the spin |
|---|---|---|---|
| To November 13, 2026 | 26% | 38% | 73% |
At the last 60 sessions' volatility, one standard deviation over a month is about ±12%, or $19.68 to $24.55 from the $21.98 close; about two months in three end inside that range if volatility holds. The median daily move since the spin is 2.0%.
| Results day | Released | Close before | Close after | Move | Times a median day |
|---|---|---|---|---|---|
| August 12, 2026 | Before the open | $19.72 | $19.08 | -3.2% | 1.7× |
| November 12, 2026 | Before the open | $21.23 | $21.29 | +0.3% | 0.1× |
Average move on a results day: 1.8% either way, against a median day's 2.0%. The move is measured from the close before the release to the close of the first session after it.
The one results day so far fell 3.2%, on August 12, when the growth guidance was cut; the Stockholm line fell more. The November 12 results are the first test of the guided acceleration in the second half.
Notes on earlier sections
Data correction: the “§355(e) window”. The September 8 analysis said, in Is Octave an acquisition target?, in Tail scenarios and in What would change this view, that an acquisition of half or more of Octave before May 22, 2028 would make the distribution taxable to Hexagon, that a sale before mid-2028 was therefore unlikely, and that the constraint lifts on that date. Nothing Octave has filed contains such a restriction. The tax disaffiliation agreement with Hexagon allocates taxes between the two groups and has no restricted period and no limit on buybacks, mergers or share issues; the information statement describes the distribution as tax-free to US holders under Section 355 and, in Sweden, under the Lex-ASEA rules confirmed by the Swedish Tax Agency, and does not describe any limit on a later sale of Octave. Whether a sale could create a tax cost for Hexagon is not addressed in the filings. A data correction: the date and the constraint are withdrawn; the rest of those sections stands.
Omission: the managers’ share purchases. The September 8 analysis said there was “no officer share ownership” in the public record. By then the chief executive, the chief operating officer and three other managers had bought 239,140 shares on the open market (June 5 to September 2), disclosed in notices under the EU’s market-abuse rules, and the first equity grants had been made on August 13 (the chief executive 541,046 units). The full record is in Who has been trading above. An omission.
Omission: the material weaknesses. The information statement reported two material weaknesses in internal control over financial reporting at December 31, 2025, and the second-quarter 10-Q concluded that disclosure controls were not effective at June 30, 2026 for that reason, while stating that the financial statements are fairly presented. The September 8 analysis did not mention them. An omission.
What it means for the rating
HOLD, target $19.50 → $19 (proposed). The target is the best-guess value, $19.22. At $21.29 the stock is about 11% above the best-guess value and both chips are red; the price assumes either a lower discount rate than this page uses or a best case that is more likely than the evidence so far supports. It is HOLD rather than REDUCE because the gap is about half a point of discount rate, managers have been buying, the Russell reconstitution may bring index buying in December, and nothing in the filings stands in the way of a sale of the company. It is not ACCUMULATE because growth has slowed for four years and the next results must show the second-half acceleration the guidance needs.
| Action | Level | Reason |
|---|---|---|
| Buy | Below about $15.40 | Both chips green: expected return above 25% and gain to loss above 3 to 1 |
| Accumulate | $15.40–17.50 | Expected return 10–25% |
| Hold | $17.50–21.00 | |
| Trim | Above about $21 | The base case at an 8.5% discount rate ($20.97) |
| Move to ACCUMULATE | Third-quarter organic growth of 2–4% with ARR on course, and a buyback authorized | |
| Move to REDUCE | Revenue below the guide, ARR growth below 6%, or the public-safety deals slipping again |
What the November 12 results must show:
| Item | Why it matters | Base case needs |
|---|---|---|
| Third-quarter revenue against the guide ($400–410 million; organic growth 2–4%) | The 2026 guide requires second-half growth after a first half that fell | At or above $405 million |
| Recurring revenue ($285–290 million guided) and ARR ($1,185–1,205 million guided for the year) | The base case rests on subscriptions growing about 7.5% | ARR growth of 6–8% held |
| License revenue and the large public-safety deals | Their slippage was the reason for the August guidance cut | No further slippage |
| Adjusted operating margin (~27% guided) and free cash flow | The base case needs the 20% free cash flow margin | About 20% for the year |
| Capital allocation | The capital reduction makes a buyback possible; at this price a buyback adds little value | Stated either way |
| The material weaknesses | Remediation is a condition of credible numbers | Progress reported |
Detailed Post-Spin Analysis — September 8, 2026
Written against the September 8 close of $18.39. Primary sources: the Q2 2026 Form 10-Q (filed 2026-08-12), the Q2 2026 results release (8-K, 2026-08-12), the Form 10 information statement (10-12B/A, 2026-04-09), the Schedule 13D filed by Melker Schorling AB on 2026-06-01, Octave’s Q4-25 Supplemental Financial Information workbook, and the company’s leadership and board pages.
The one-line version
The $2.1 billion write-down is not information about the business. It is the accounting conceding a price the market had already set — and the market set it before Octave had filed a single standalone quarter.
Octave impaired $1,671M of goodwill in its first full quarter as a public company. The trigger, in the company’s own words, was that “Octave’s market capitalization remained below the Company’s carrying value” once regular trading began. A further $463.7M of trademarks was written off because the legacy brands are being retired for a single Octave brand. Combined: $2,134.7M of charges against $398.4M of quarterly revenue.
In the same quarter the business produced $93.5M of free cash flow, at a 23% margin. Not one dollar of the charge was cash. What was written down was Hexagon’s accumulated purchase price for a decade of acquisitions, and the only new fact was the market’s opinion of it.
The real question is underneath, and it is about mix, not impairment. Reported revenue fell 1% organically in Q2. Annual recurring revenue rose 7%, to $1,143M. Those move in opposite directions because the company is deliberately converting perpetual licenses into subscriptions: license revenue −23%, SaaS +23.8% over six months. A license books once and large; a subscription books monthly and small. The transition mechanically suppresses reported revenue while it is happening, and mechanically reverses when it is done.
The three-year record confirms the mix argument and undercuts the price argument at the same time. Subscriptions compounded 8.5% then 8.6% while licenses fell 33% in 2025 alone, and deferred revenue grew 20.7% in a year when reported revenue grew 1.3%. Billings are running well ahead of revenue, which is what this transition is supposed to look like.
But the same record shows the deceleration began before the separation. Revenue grew 4.1% in 2024, 1.3% in 2025, and is guided to roughly 0.7% in 2026. And free cash flow margin has run 19.6%, 22.3%, 19.5% — it has never reached the 24% that would make this obviously cheap.
On valuation the discount is real but no longer generous. At $18.39 Octave trades at 3.2x revenue and roughly 11.9x EBITDA, against a peer group at 4.0–7.1x and 12.3–24.2x. The nearest match on growth is Dassault Systèmes, compounding 2.2% at 4.0x and 14.7x — so Octave is roughly 20% cheaper than a peer growing about twice as fast. That is a discount, not a mispricing.
The argument against is our own data, and it is not weak. Octave’s float is 81.6%, because Melker Schorling AB holds 21.8% after the distribution. Across our universe, spinoffs in the 50–90% float band have a median total return of −4.4% and beat the S&P 12 times in 97. Full-float spinoffs return a median +105.6%. Section 8 argues why Octave sits in the more benign half of that bucket, but the argument is a judgment, not a measurement.
Rating: HOLD. Target $19.50. Grade: B. The base-case DCF is $19.27, 5% above the price, on a 21% terminal free cash flow margin — the mid-point of the three years actually delivered. At the 20% the company guides, the model returns $18.39, which is the price to the cent. That is the finding: the market is already paying for exactly what management says it will deliver, and the upside requires the margin to beat a three-year range it has never beaten. A good business at a fair price is a hold.
What the business actually is
Octave is the software half of Hexagon AB, separated on May 22, 2026 and trading regular-way on Nasdaq from May 28. It is incorporated in Ireland, files as a domestic US registrant, and is dual-listed — OCTV on Nasdaq New York and Swedish Depository Receipts on Nasdaq Stockholm.
It is not one business but four, combined for the first time at separation:
| Unit | What it sells |
|---|---|
| Asset Lifecycle Intelligence (ALI) | Software to design, construct and operate industrial facilities — the largest piece |
| Safety, Infrastructure & Geospatial (SIG) | Public safety, critical infrastructure and geospatial systems |
| ETQ | SaaS enterprise quality management — document control, training, audits |
| Bricsys | Computer-aided design for 3D modeling and construction |
The company reports revenue by activity rather than by unit. On fiscal 2025 revenue the split is approximately Design 40%, Operate 30%, Protect 20%, Build 10%.
Revenue by type, six months to June 30, 2026 — this is the cut that matters:
| H1 2026 | H1 2025 | change | |
|---|---|---|---|
| Subscriptions | $561,993k | $526,166k | +6.8% |
| Licenses | $74,229k | $93,622k | −20.7% |
| Services and other | $148,693k | $176,357k | −15.7% |
| Total | $784,915k | $796,145k | −1.4% |
Inside subscriptions, the same story runs one level deeper: SaaS $171,894k against $138,848k, +23.8%, while subscription licenses were flat at $144,911k and maintenance grew 2.4%. The growth is in the newest revenue line and the decline is in the oldest one.
Geography, same period: EMIA $302.0M (38.5%), United States $297.1M (37.8%), APAC $110.4M (14.1%), other Americas $75.4M (9.6%). No single region dominates, which is unusual for a US-listed software company and reflects the Hexagon inheritance.
Retention is the strongest number in the filings. Gross retention 97% and net retention 105%, both unchanged across 2024 and 2025, with gross retention of 99% among large customers. A 97% gross rate means the installed base is close to non-discretionary. Net revenue retention of 105% means existing customers expand modestly — enough to grow without new logos, not enough to grow quickly on its own.
No customer concentration is disclosed, which for a company selling into power generation, data centers, public works, process industries and public safety is more likely to mean genuine fragmentation than an undisclosed risk. It is not stated either way, so it is not evidence.
Management Team
Nine executives, seven of them from Hexagon, and all but the CEO appointed in September 2025 — eight months before the distribution. This is a team assembled for the separation rather than inherited with the assets.
| Role | Name | Came from |
|---|---|---|
| Chief Executive Officer | Mattias Stenberg | Hexagon — Chief Strategy Officer and Head of M&A |
| Chief Financial Officer | Benjamin Maslen | Hexagon Chief Strategy Officer; 19+ years in equity research at Morgan Stanley, BofA and Lehman Brothers |
| Chief Operating Officer | Scott Moore | Nearly 30 years at Hexagon; CFO and COO of the Asset Lifecycle division |
| Chief Technology Officer | Vivek Mokashi | Several SVP roles at Hexagon; 30+ years in pre-sales, product design and development |
| Chief Revenue Officer | Tamara Adams | Honeywell, Oracle, Dotmatics — 20+ years in sales and operations |
| Chief Product Officer | Jay Allardyce | Insight Software, Alphabet’s cloud division, GE, HP, Uptake |
| Chief Marketing Officer | David Cryer | SVP and CMO of Hexagon’s ALI division; Intergraph, Microsoft, Alcatel |
| Chief People Officer | Jennifer Kaplan | SVP Global HR at Hexagon |
| Chief Legal Officer | Tony Zana | Group General Counsel at Hexagon; 20+ years across Hexagon and Intergraph |
The top three seats divide the job unusually cleanly, and reading any two of them alone gives the wrong answer.
The CEO and CFO are both capital-markets people. Stenberg ran strategy and M&A at Hexagon; Maslen ran strategy after nineteen years in sell-side equity research at Morgan Stanley, BofA and Lehman. Neither is a line operator, and the CFO is not an accountant by training.
The COO is where the operating record sits, and it is deep. Scott Moore spent nearly thirty years at Hexagon and was both CFO and COO of the Asset Lifecycle Intelligence division — the largest of the four businesses, roughly 40% of revenue. He has run the finance function and the operations of the unit that matters most, which is a more complete operating grounding than most spinco COOs bring, and it fills the gap the CEO and CFO leave.
So the interesting question is the dynamic, not the gap. Three observations follow from the split:
The CFO seat has a shadow. Moore has done that job for the biggest unit; Maslen has never done it anywhere. That is not a criticism — an ex-analyst CFO is a genuine asset for a company whose story is complicated and whose stock trades at a discount, because the whole investment case rests on persuading the market that ARR matters more than reported revenue, and that is an investor-relations problem as much as a finance one. But it does mean the technical accounting depth in the executive team sits in the COO’s chair rather than the CFO’s.
The institutional memory is concentrated in one person. Two of the three joined the top table in September 2025; Moore has thirty years of it. If he leaves, the operating knowledge at the top goes with him, and there is no disclosed retention arrangement because there is no proxy yet.
Strategy sits above operations here, and the balance sheet is arranged to match. ~$330M of annual free cash flow, 0.77x leverage, no dividend, no buyback, and a credit agreement specifically permitting 4.0x in a quarter containing an acquisition. The people and the facility point the same way. The risk is the mirror image — a business growing 1% with a corporate-development team in the two senior seats is a business likely to try to buy its growth, and the 2023 record already shows $303M spent on acquisitions in a single year. The COO is the counterweight to that, which makes the working relationship between the three the thing to watch and the thing least visible from outside.
The board, six directors, five independent, with the chair separate from the CEO:
| Director | Background | |
|---|---|---|
| Brett D. Watson | Chair | President of Koch Equity, LLC, overseeing Koch-affiliated investment groups |
| Mattias Stenberg | CEO | Above |
| Jill D. Smith | Independent | Former chair of the board of AspenTech; 30+ years governing technology and data companies |
| David J. Hollister | Independent | Senior leadership at Bentley Systems |
| Magnus Ahlqvist | Independent | CEO of Securitas AB since 2018 |
| Meerah Rajavel | Independent | CIO of Palo Alto Networks |
This is a better board than the company’s growth rate would suggest, and two seats are unusually well matched. Jill Smith chaired AspenTech and David Hollister was a senior executive at Bentley Systems — the two closest comparables in the peer table below. Direct governance experience of the two businesses an investor would benchmark Octave against is not a common coincidence.
Koch Equity’s president in the chair is the fact to keep watching. Koch has been an investor in the Hexagon complex, and a chair drawn from a large private investor with a long holding period is a different animal from a career independent director. It says nothing on its own; it would say a great deal if a take-private were ever discussed after the §355(e) window closes in May 2028.
What is still missing: Octave has filed no DEF 14A — it separated in May 2026, so its first proxy is due in 2027. There is no compensation structure, no officer share ownership, and no committee composition in the public record. Until then, incentive alignment cannot be assessed at all.
The financial record — three years, and what the halves hide
Combined statements of operations, $ thousands. Octave reports no segments, so this is by revenue type — the only cut the company gives.
| 2023 | 2024 | 2025 | |
|---|---|---|---|
| Subscription licenses | 254,572 | 279,368 | 289,858 |
| SaaS | 211,487 | 253,249 | 296,198 |
| Maintenance subscription | 450,580 | 462,104 | 494,316 |
| Subscriptions | 916,639 | 994,721 | 1,080,372 |
| Licenses | 292,030 | 295,650 | 198,180 |
| Services and other | 343,821 | 326,134 | 359,346 |
| Total revenue | 1,552,490 | 1,616,505 | 1,637,898 |
| Total cost of revenue | 450,990 | 434,328 | 408,158 |
| Gross profit | 1,101,500 | 1,182,177 | 1,229,740 |
| Research and development | 145,774 | 157,352 | 182,864 |
| Sales and marketing | 352,014 | 361,613 | 389,308 |
| General and administrative | 134,030 | 139,313 | 169,356 |
| Amortization of intangibles | 115,977 | 127,411 | 155,498 |
| Income from operations | 324,035 | 395,492 | 336,850 |
| Net income | 245,653 | 311,207 | 248,104 |
| EPS (pro-forma 268.4M shares) | $0.92 | $1.16 | $0.92 |
The ratios are where the story is:
| 2023 | 2024 | 2025 | H1 2026 | |
|---|---|---|---|---|
| Revenue growth | — | +4.1% | +1.3% | −1.4% |
| Gross margin | 71.0% | 73.1% | 75.1% | 76.9% |
| GAAP operating margin | 20.9% | 24.5% | 20.6% | n/m |
| Adjusted operating margin | 31.5% | 33.2% | 30.9% | 29% (Q2) |
| Free cash flow | $304.2M | $360.2M | $319.7M | $175.5M |
| Free cash flow margin | 19.6% | 22.3% | 19.5% | 22% |
Four readings, and two of them cut against the investment case.
1. The deceleration predates the spin. +4.1%, +1.3%, guided ~+0.7%. Whatever is slowing this business, separation did not cause it and has not yet reversed it. This is the single most important thing the annual record adds, and it is the reason the rating on this page changed.
2. Free cash flow margin has never reached 24%. Three years at 19.6%, 22.3% and 19.5%, with 2025 the low, and guidance of ~20% for 2026. Any valuation that needs a structurally higher margin is assuming something that has not happened in the observable record.
3. But the mix shift is real, large, and going the right way. Licenses fell 33% in 2025 and are now 12.1% of revenue against 18.8% in 2023. Subscriptions compounded 8.5% then 8.6%, and SaaS inside them 19.7% then 17.0%. Gross margin has risen 600 basis points in three years, because subscription revenue carries a better margin than the license and services revenue it is replacing. A business whose gross margin rises every year for three years while revenue stalls is changing shape, not decaying.
4. Deferred revenue is the strongest single number in the filings. It grew 20.7% in 2025 — $315.3M to $380.6M — in a year when revenue grew 1.3%. Deferred revenue is cash billed and not yet recognized. Growing it sixteen times faster than reported revenue is what a license-to-subscription conversion looks like from the inside, and it is a forward indicator that the reported line is not.
What the half-year figure hides, and why H2 is the real test. Octave’s revenue is heavily fourth-quarter weighted — Q4 was 27.6% of 2024 revenue and 34.7% of 2024 licenses, the usual enterprise-software year-end close. So H1 2026 being down 1.4% says less than it appears to.
It also means guidance requires an acceleration. Full-year guidance of $1,635–1,665M against H1 of $784.9M implies second-half revenue of $850–880M, or +1.0% to +4.6% year over year — after a first half that fell 1.4%. Management is guiding to a swing of roughly 2 to 6 points between the halves. That is the number to check in November, and nothing else in the Q3 release matters as much.
Cash generation is the quality argument, and it survives everything above. Operating cash flow ran $436M, $502M and $466M across the three years, and $240.9M in H1 2026 against $248.5M a year earlier — down 3.1% through a period containing a $2.1B accounting loss and the entire cost of standing up a public company. Capitalised software runs ~$130M a year against capex of ~$9M: the investment is engineering payroll, and there is no factory to maintain.
The $2.1 billion write-down, and what it actually says
The mechanics are worth stating precisely, because the headline number invites the wrong conclusion.
| Goodwill, 31 Dec 2025 | $6,221.4M |
| Goodwill impairment, Q2 2026 | $(1,671.0)M |
| Goodwill, 30 Jun 2026 | $4,555.0M |
| Indefinite-life trademarks written off | $(463.7)M |
| Total charge | $2,134.7M |
The goodwill trigger was the share price itself. The company tested for impairment because its market capitalization sat below the carrying value of its own balance sheet once it started trading, then used discounted cash flow and market approaches to size the write-down. That is the standard procedure, and it has an uncomfortable circularity: the market marked the stock down, and the accounting then confirmed the mark by construction. It is not an independent second opinion.
The trademark charge is a different animal and is genuinely a management decision. Following shareholder approval on April 24, 2026, the legacy brands are being retired in favor of a single Octave brand, so trademarks carried as indefinite-life assets were reassessed as having two-year useful lives and written down on a relief-from-royalty basis. That is a real strategic choice with a real cost, and unlike the goodwill charge it says something about what management intends.
What the charge does not do is matter to cash, debt or covenants. Management states it plainly — the charges “did not result in any current cash expenditure and did not affect the Company’s cash flows or compliance”. Net debt is $339.9M against an EBITDA proxy of roughly $444M, or 0.77x, against a covenant ceiling of 3.5x.
The read that matters for the rest of this site. A spinoff writing off 27% of its goodwill in its first quarter, because its own share price fell below book, is the cleanest available demonstration that a parent’s carrying value and the market’s view of a business can differ by billions — and that the divergence surfaces the moment the business is priced separately. Hexagon carried these assets at $6.2B. Within eight weeks of trading, the market said $4.9B for the equity. The spin did not destroy $1.7B of value; it revealed a disagreement that a conglomerate structure had made unobservable.
The $625 million that left with Hexagon
On May 22, in connection with the distribution, Octave paid Hexagon $625.0 million in cash, funded from new credit facilities.
| Facility | Size | Drawn at 30 Jun | Maturity |
|---|---|---|---|
| USD term loan | $350M | $350M | 2030 |
| EUR term loan | €150M (~$171M) | €150M | 2030 |
| Revolving credit | $500M | $102M | 2031, two 1-year extensions |
| Total committed | ~$1,021M | ~$623M |
Covenant: maximum consolidated leverage of 3.5x net debt to EBITDA, rising to 4.0x in a quarter containing an acquisition. In compliance at June 30.
This is a levered separation, and the annual record shows the $625M was the end of a pattern rather than a one-off event. Hexagon’s net transfers out of this business were $332.3M in 2024 and $307.2M in 2025 — against free cash flow of $360.2M and $319.7M in those same years. Hexagon took approximately 96% of everything the business generated, in both years, before taking $625M more on the way out.
| 2024 | 2025 | At separation | Total | |
|---|---|---|---|---|
| Cash to Hexagon | $332.3M | $307.2M | $625.0M | $1,264.5M |
| Free cash flow generated | $360.2M | $319.7M | — | $679.9M |
$1.26 billion extracted against $680M generated. The gap is the debt. The category is familiar — the same structure as the Honeywell Aerospace and Mobility Global separations — but the multi-year view makes it sharper than the separation payment alone suggests: this business has not been allowed to accumulate cash in living memory, and 2026 is the first year it will.
But the scale is modest and that changes the conclusion. At 0.77x EBITDA, Octave’s leverage is not a constraint on anything: not on the dividend it does not pay, not on the buyback it has not announced, not on acquisitions. The facilities are senior unsecured with a covenant more than four times current leverage. Compare that with a separation levered at three or four times, where the debt dictates strategy for years. Here the debt is a fact about the past rather than a constraint on the future.
What it does establish is a capital allocation precedent: the first material use of Octave’s balance sheet was a payment to somebody else. There is no dividend and no announced buyback.
Price and volume: the spike that wasn’t a flush
Octave’s first fortnight does not look like the textbook forced-selling pattern, and the difference is instructive.
| Day 1 close (28 May) | $17.05 |
| Session 4 high (2 Jun) | $25.11, +47.3% |
| Session 5 (3 Jun) | $19.74, −21.4% in one day |
| Low (23 Jul, session 39) | $15.50, −9.1% from day 1 |
| Close, 8 Sep (session 71) | $18.39, +7.9% from day 1 |
| Recovery off the low | +18.6% |
A note on the day-1 basis. This site’s data previously recorded a day-1 price of $20.35 on an open basis. The committed price archive shows May 28 opening at $17.45 and closing at $17.05. This analysis uses $17.05, the day-1 close from the archive, on the owner’s instruction of 2026-09-09. Every return above is computed on that basis. The $20.35 figure appears to have come from the Stockholm SDR line or a when-issued print; the stored figure was corrected at the same time as this page.
The classic post-spin pattern is a day-1 volume flush that decays. Octave did not do that. Day-1 volume was 2,552,100 shares. The average over the most recent twenty sessions is 2,603,385 — 102% of day one. Volume did fall below half of day-1 by session 6, then came back and stayed.
Two candidate explanations, and they have different implications. The first is the dual listing: US volume is one of two venues, so the Nasdaq line can grow as US holders accumulate what Swedish holders sell, without total turnover changing at all. The second is that the register is still turning over four months in — Hexagon’s shareholder base is heavily Swedish and index-driven, and a US-listed successor is not a natural holding for all of it.
Neither explanation is testable from the US tape alone, and that is the finding: for a dual-listed spinoff, single-venue volume decay is not a usable measure of when forced selling ends. The metric that works for single-listed names silently fails here.
The +47% spike to $25.11 on session 4, then −21.4% the next day, is real price data, not an artefact — it survives inspection of the raw bars. A stock that can move a quarter in one direction and a fifth back in two sessions has very little price discovery in it. That is worth remembering when reading any valuation conclusion drawn from an eight-week average.
Capital allocation
| Dividend | None |
| Buyback | None announced |
| Cash to former parent at separation | $625.0M |
| Capex, H1 2026 | $5.1M |
| Capitalised software, H1 2026 | $60.3M |
| D&A, H1 2026 | $93.4M |
| Free cash flow, H1 2026 | $175.5M (22% margin) |
| Net debt / EBITDA | 0.77x (covenant 3.5x) |
Capitalised software runs at nearly twelve times capex. That is what an asset-light software company looks like: the investment is engineering payroll, capitalised. It also means D&A ($93.4M) meaningfully exceeds the cash cost of maintaining the asset base, so free cash flow will persistently exceed accounting earnings — which is exactly what the first two quarters show.
With ~$330M of free cash flow guided for 2026 and no dividend, no buyback and 0.77x leverage, Octave will accumulate roughly a fifth of its market capitalization in cash over three years if it does nothing. It will not do nothing — and note that it has never had the option before. Hexagon took ~96% of free cash flow in each of 2024 and 2025, so 2026 is the first year in the observable record in which this business retains its own cash. The credit agreement’s acquisition carve-out — leverage may rise to 4.0x in a quarter containing an acquisition — was negotiated by people who expect to use it. The unannounced capital allocation policy is the largest unpriced variable in this analysis, and the first real signal will be whatever the company does with 2027’s cash.
Valuation
At $18.39 on 268,437,788 shares:
| Market capitalization | $4,937M |
| Net debt (30 Jun) | $339.9M |
| Enterprise value | $5,276M |
| EV / FY26 guided revenue | 3.20x |
| EV / EBITDA proxy | 11.9x |
| EV / adjusted operating income | 10.7x |
| EV / ARR | 4.62x |
| Free cash flow yield | 6.7% |
The EBITDA proxy is GAAP operating income excluding the impairments, plus D&A, annualised from H1 — $444M. It is not the company’s own metric; Octave publishes “adjusted income from operations” and no EBITDA figure at all, so a like-for-like comparison against peers has to be constructed. The construction is stated so it can be disagreed with.
Discounted cash flow
Rebuilt on the three-year record. Every assumption, stated:
Revenue is modeled by line rather than as a single growth rate, because the whole question is what happens when a shrinking license book stops mattering:
| Input | Base case | Why |
|---|---|---|
| Subscriptions | 2025 base $1,080M, +7.5%/yr | Slightly below the 8.5% and 8.6% actually delivered in 2024 and 2025 |
| Licenses | 2025 base $198M, −30%/yr | 2025 alone was −33% |
| Services | 2025 base $359M, −2%/yr | Fell 5.1% in 2024, recovered 10.2% in 2025; assumed to drift |
| FCF margin | 20% → 21% by 2030 | The three-year range is 19.5%–22.3%. 21% is the mid-point |
| WACC | 9.0% | Asset-light software, 0.77x leverage, dual-listed |
| Terminal growth | 2.5% | Below subscription growth; assumes the franchise matures |
That calibration reproduces guidance, which is the test of whether the assumptions are honest: the model gives 2026 revenue of $1,652M against guidance of $1,635–1,665M.
| 2026 | 2027 | 2028 | 2029 | 2030 | |
|---|---|---|---|---|---|
| Subscriptions | 1,161 | 1,249 | 1,342 | 1,443 | 1,551 |
| Licenses | 139 | 97 | 68 | 48 | 33 |
| Services | 352 | 345 | 338 | 331 | 325 |
| Total | 1,652 | 1,691 | 1,748 | 1,822 | 1,909 |
| Growth | +0.9% | +2.3% | +3.4% | +4.2% | +4.8% |
| Licenses as % of revenue | 8.4% | 5.7% | 3.9% | 2.6% | 1.7% |
The mechanism is visible in that table. Reported growth accelerates from 0.9% to 4.8% without subscriptions ever growing faster than 7.5% — purely because the license drag shrinks from 8.4% of revenue to 1.7%. That is the bull case, and it is arithmetic rather than optimism. It is also slower and smaller than the first version of this page assumed.
Result: enterprise value $5,513M, equity $5,173M, $19.27 per share — 5% above the current price.
Sensitivity on the load-bearing input. The terminal free cash flow margin still moves the answer more than anything else:
| Terminal FCF margin | Value per share | vs price |
|---|---|---|
| 18.5% | $17.08 | −7% |
| 19.5% (2025 actual) | $17.96 | −2% |
| 20.0% (guided) | $18.39 | 0% |
| 21.0% (base case, mid of range) | $19.27 | +5% |
| 22.0% (2024 actual, the best year) | $20.15 | +10% |
| 23.5% | $21.46 | +17% |
This table is the whole analysis. At the margin the company guides, the model returns $18.39 — the market price to the cent. At the best margin the business has ever delivered, $20.15, or 10% upside. The market is pricing Octave at exactly management’s own guidance, and the entire bull case is a bet that a three-year range of 19.5%–22.3% is beaten and held.
Sensitivity on discount rate and terminal growth, at a 21% margin:
| WACC \ terminal g | 1.5% | 2.0% | 2.5% | 3.0% | 3.5% |
|---|---|---|---|---|---|
| 8.0% | $19.98 | $21.39 | $23.05 | $25.05 | $27.48 |
| 8.5% | $18.44 | $19.62 | $21.00 | $22.63 | $24.59 |
| 9.0% | $17.10 | $18.11 | $19.27 | $20.63 | $22.23 |
| 9.5% | $15.93 | $16.80 | $17.79 | $18.93 | $20.26 |
| 10.0% | $14.90 | $15.65 | $16.50 | $17.47 | $18.59 |
The price now sits in the middle of this grid rather than beneath it — which is what changed. On the earlier, unsupported margin assumption the stock was below every cell but one. On the actual record it is where it should be.
Earnings-based cross-check
GAAP earnings are meaningless this year, so the cross-check has to run through cash. At a 6.7% free cash flow yield, Octave is priced as though its cash generation will not grow. A software business with 97% gross retention, 105% net retention and 7% ARR growth is not a no-growth business — and the peer set is not priced as one, at 12.3x to 24.2x EBITDA against Octave’s 11.9x.
What this most resembles
Four cuts against our own universe of 559 separations. Each tests one characteristic, and two of the four are unfavorable.
1. Technology spinoffs — supportive. n=47, median total return +33.7%, 13 of 41 beat the S&P. Technology is among the better-performing sectors in the cohort.
2. Software spinoffs specifically — unsupportive. n=14, median total return +3.5%, 4 of 11 beat the S&P. Narrowing from technology to software cuts the median return by an order of magnitude. Software separations in our data have been mediocre, and this is the closest comparison available.
3. A positive first quarter — supportive, and it is the strongest cut here. Octave returned +9.1% in its first quarter, against a cohort median of 0.0%, placing it at the 64th percentile of 343 names. Splitting the cohort on that:
| First quarter | n | Median total return | Beat S&P |
|---|---|---|---|
| Positive | 172 | +76.5% | 45/164 (27%) |
| Negative | 170 | +26.8% | 36/165 (22%) |
Names that did not fall in their first quarter went on to return nearly three times as much at the median. Octave is in the better branch. This is also the finding that contradicts the intuitive forced-selling trade, and it is consistent across the whole cohort rather than particular to this name.
4. Float — unsupportive, and it needs an argument. Octave’s float is 81.6%, in the 50–90% band:
| Float band | n | Median total return | Beat S&P |
|---|---|---|---|
| Partial, 50–90% | 103 | −4.4% | 12/97 (12%) |
| Full, 90%+ | 167 | +105.6% | 48/159 (30%) |
That is the single most negative fact in this analysis and it should not be waved away. A 110-point gap in median return between float bands is larger than almost any other cut in the cohort.
The argument for why Octave sits in the benign half of that band — and it is a judgment, not a measurement. The partial-float bucket pools at least three different situations: staged distributions where the float is about to rise and the overhang is real; permanently constrained names where a strategic holder simply does not sell; and companies whose insiders hold stock because the business is small and closely held.
Octave is the second kind. Melker Schorling AB — the Schorling family vehicle that controls Hexagon — received its 21.8% in the pro-rata distribution on a 1-for-10 basis, holds all 11,025,000 Class A shares plus 47.4M Class B, and filed a Schedule 13D stating no current plans under Items 4(a)–(j). There is no undistributed block waiting to come to market, because the distribution is complete. Both share classes carry one vote per share, so this is not a control structure with entrenchment risk either; the dual class exists to mirror Hexagon’s own A/B structure across two listings.
Until Milestone 7A.4 separates those three populations, this cut cannot distinguish them, and the −4.4% median should be read as covering a mixture that includes situations materially worse than this one.
In depth: competitive dynamics
Octave competes in engineering and industrial software against larger, better capitalised and — in most cases — faster growing companies.
| Competitor | Overlap | Revenue growth |
|---|---|---|
| Bentley Systems | Infrastructure engineering — the closest single comparison | +12.8% |
| Autodesk | Design and construction; Bricsys competes directly with AutoCAD | +16.1% |
| PTC | CAD and PLM | −6.8% |
| Trimble | Geospatial and construction technology; overlaps SIG | +11.0% |
| Nemetschek | AEC software | +13.0% |
| Dassault Systèmes | Design and simulation | +2.2% |
| Hexagon AB | Former parent; retains the hardware and metrology businesses | +4.0% |
Octave is growing more slowly than five of these seven. Guided at 0–2% organic against a peer median near 12%, the gap is not marginal and it is the central bear argument. Only PTC, shrinking at 6.8%, and Dassault at 2.2% are in the same zone.
What Octave has instead of growth is stickiness and diversification. 97% gross retention across an installed base spread over power, data centers, public works, process industries and public safety is a genuinely defensive position. Bricsys competing with AutoCAD is the weakest position in the portfolio — it is a challenger to an entrenched standard — but at roughly 10% of revenue it is also the smallest.
The Hexagon relationship is worth watching rather than worrying about. Hexagon retains metrology and sensor hardware; Octave took the software. The two remain natural partners rather than competitors, but the transition services agreement runs for a defined period and Octave expects to replace those services “either internally or by third parties” with stand-up costs continuing through fiscal year 2027. Those costs are in the guided 30% margin; whether they end on schedule is a 2028 question.
In depth: valuation against peers
All multiples market data as of September 8, 2026, on a consistent enterprise value basis. Octave’s figures are computed above; peers are provider-sourced trailing figures.
| EV/Revenue | EV/EBITDA | Fwd P/E | Rev growth | |
|---|---|---|---|---|
| Bentley Systems | 7.1x | 24.2x | 20.5x | +12.8% |
| Nemetschek | 5.8x | 20.6x | 20.6x | +13.0% |
| Autodesk | 5.6x | 19.2x | 14.6x | +16.1% |
| PTC | 5.3x | 12.3x | 14.9x | −6.8% |
| Hexagon AB | 5.3x | 22.7x | 21.1x | +4.0% |
| Trimble | 4.0x | 17.0x | 14.1x | +11.0% |
| Dassault Systèmes | 4.0x | 14.7x | 14.5x | +2.2% |
| Octave | 3.20x | 11.9x | — | 0–2% |
Octave is the cheapest name in the set on both measures, and by a wide margin on revenue — 3.2x against a peer range of 4.0x to 7.1x, a 20% discount to the cheapest peer and 55% to the most expensive.
Two comparisons frame the case, and they point in opposite directions.
PTC is the flattering one. It trades at 5.3x revenue and 12.3x EBITDA while its revenue shrinks 6.8%. Octave trades at 3.2x and 11.9x with revenue flat to up 2%. On PTC’s revenue multiple Octave would be worth roughly $31 a share.
Dassault Systèmes is the fair one, and it is the better match. Dassault grows 2.2% — the closest growth rate in the set to Octave’s guided 0–2% — and trades at 4.0x revenue and 14.7x EBITDA. Octave at 3.2x and 11.9x is roughly 20% cheaper than a peer growing about twice as fast. That is a discount proportionate to the growth gap, not a mispricing.
This is where the three-year record changed the conclusion on this page. The first version of this analysis leaned on the PTC comparison and read the 20–55% peer discount as largely unearned. The annual statements show revenue growth decelerating 4.1% → 1.3% → ~0.7% across the separation, which makes Octave’s 0–2% look like a trend rather than a trough. Against Dassault — same growth zone, comparable margins — the discount is about right. A first-quarter $2.1B impairment, a four-month trading history, no proxy and no capital allocation policy justify the remainder.
In depth: is Octave an acquisition target?
The §355(e) constraint is the binding fact and it is dated. The distribution was structured as tax-free. Under §355(e), an acquisition of 50% or more of Octave within two years of May 22, 2026 would retroactively make the distribution taxable to Hexagon. That window closes on May 22, 2028. Until then a change of control is not impossible but is very expensive, and the practical effect is that a whole-company sale before mid-2028 is unlikely.
After that, the case is unusually clean. Octave is a sub-$5B software asset with 97% gross retention, a 22% free cash flow margin, and a valuation at a material discount to every strategic peer. Plausible acquirers:
- Private equity. The clearest fit. High retention, high cash conversion, low leverage and a depressed multiple is the standard target profile, and the business would support far more than 0.77x.
- A larger engineering software vendor — Autodesk, Bentley, Dassault — buying the ALI installed base. Antitrust exposure varies by unit and would likely force divestitures.
- Break-up. Four businesses combined for the first time at separation is a combination assembled by a seller, not by an operator. ETQ in particular is a clean standalone SaaS asset that would attract different buyers from the rest.
The 21.8% holder is the swing factor and cuts both ways. MSAB can block a deal it dislikes; equally, a single holder of that size makes a negotiated transaction far simpler than a fragmented register would. Its 13D reserves the right to change board composition — standard language, but it is there.
Read MSAB’s history before reading its stake as a countdown, though. The vehicle was formed in 1999 and has held the same six listed companies for decades. Octave’s board carries Magnus Ahlqvist, chief executive of Securitas — another MSAB holding — which is how a permanent owner staffs a board, not how a seller prepares one. The management configuration and the ownership history point in opposite directions, and that tension is worked through in Tail scenarios below rather than resolved here.
Tail scenarios
These are 2–3σ outcomes, not black swans, and each is sized.
Upside tails
The license transition completes faster than guided. License revenue is 9.5% of the total and falling 20%+ a year. Once it approaches zero, reported growth converges on ARR growth of 6–8% mechanically. If that happens by 2028 rather than 2030, the DCF’s growth path shifts forward two years — worth roughly $3–4 a share.
Capital allocation turns aggressive. ~$330M of annual free cash flow, no dividend, no buyback, 0.77x leverage and an acquisition carve-out to 4.0x. A buyback of 10% of the shares at current prices is affordable within two years of cash flow and would be accretive at a 6.7% free cash flow yield.
A private equity approach after May 2028. At a 30% premium to the base-case DCF, roughly $30.
The company may be configured for sale rather than for independence — and if so, that is the largest tail here. Five facts point the same way, and none of them is individually persuasive:
| CEO | Hexagon’s Head of M&A |
| CFO | Hexagon strategy, after 19 years in sell-side equity research |
| Chair | President of Koch Equity |
| Anchor holder | MSAB at 21.8%, filed a 13D rather than a 13G, holds all Class A |
| Credit agreement | Leverage may rise to 4.0x in a quarter containing an acquisition |
| §355(e) | Constraint lifts May 22, 2028 |
A CEO who ran M&A, a CFO who spent two decades valuing companies for institutions, and a chair drawn from a large private investor is not the team you assemble to grind out 2% organic growth for a decade. It is a team equipped to run a process. The credit agreement was negotiated by people who expected to transact, and the anchor holder has a blocking stake and a 13D that expressly reserves the right to change board composition.
But one part of the intuitive version of this argument is mechanically wrong, and it matters. Hexagon did not retain a stake in Octave — the distribution was 100% pro rata, one Octave share for every ten Hexagon shares. MSAB holds 21.8% of Octave because it holds roughly 22% of Hexagon. Nobody chose to keep a position; the register simply carried across. Any argument that begins “the parent kept 20% to capture the upside” is describing something that did not happen.
What MSAB did choose is not to sell — and to file a 13D rather than a passive 13G. That is a real signal, but a weaker one than a deliberate retention would have been.
And the counter-evidence is substantial. MSAB was formed in 1999 to consolidate Melker Schörling’s holdings and has held the same six listed companies for decades — Hexagon, Assa Abloy, Securitas, HEXPOL, AAK and Loomis. It is a perpetual owner, not a sponsor with a fund life. Octave’s board makes the point concretely: Magnus Ahlqvist sits on it as an independent director and is the chief executive of Securitas — another MSAB holding. Placing an executive from one portfolio company onto the board of another is what a long-term family owner does with an asset it means to keep.
So the configuration supports both readings, and the honest position is that it is not yet decidable. The discriminating evidence is behavior around May 22, 2028: whether MSAB adds to the position or trims it, whether the board gains transaction-experienced directors, and whether the acquisition carve-out is ever drawn. Sized as a tail rather than a base case: a negotiated sale at a 30–40% premium is $25–27.
Downside tails
0–2% growth is the ceiling, not the floor. The bear case is that the mix shift is cover for genuine share loss to Autodesk, Bentley and Trimble, all growing 11–16%. If ARR growth decays toward 3%, the DCF’s terminal value falls sharply — $14–15 a share, roughly 20% below today.
Stand-up costs do not end in 2027. Guidance assumes they roll off. If the transition from Hexagon’s shared services costs more or runs longer, the terminal margin never reaches 24%. The 20% row of the sensitivity table is this scenario: $19.44.
A second impairment. Goodwill remains $4,555M against a $4,937M market capitalization. The equity is worth barely more than the goodwill on its own balance sheet. If the share price falls materially again, the same test triggers the same conclusion — non-cash, but a second write-down in under a year would do real damage to the credibility of every forward number management gives.
What would change this view
Better:
- H2 2026 revenue landing at or above the guidance midpoint — the swing between the halves is the nearest test of whether the license drag is genuinely running off
- Free cash flow margin above 22% — above the three-year range, not inside it
- ARR growth sustained at the top of the 6–8% range, with license revenue below 5% of the total
- A capital allocation policy announced — buyback preferred at this multiple
- Adjusted operating margin back above 31%, showing the 200bp decline was transitional
Worse:
- ARR growth below 5%, which would say the recurring base is not compounding either
- Gross retention below 95%
- A second goodwill impairment
- Stand-up costs extended beyond fiscal 2027
Dated — the most useful row:
| Date | What |
|---|---|
| Q3 2026 results, ~Nov 2026 | The single most important date on this page. Guidance requires H2 revenue of $850–880M, or +1.0% to +4.6% year over year, after a first half that fell 1.4% — a swing of 2 to 6 points between the halves. Q3 is the first evidence on whether that happens. Also the second ARR data point and the first on whether margin recovers to 30% |
| FY2026 results, ~Feb 2027 | First full-year audited record as an independent company, and the first year in the observable record in which the business keeps its own cash rather than transferring ~96% of it to Hexagon |
| First DEF 14A, ~2027 | Compensation structure, officer equity, committee composition — everything the Management section above cannot say |
| May 22, 2028 | §355(e) window closes; acquisition constraint lifts |
Thesis-breaking: ARR declining year over year. Everything in this analysis rests on recurring revenue compounding while reported revenue is suppressed by mix. If ARR stops growing, the mix argument collapses and the reported line was telling the truth all along.
Investment Scorecard
| Dimension | Weight | Score | Rationale |
|---|---|---|---|
| End market | 20% | 5/10 | Diversified across power, data centers, infrastructure and public safety — genuinely defensive and genuinely slow. Marked down from 6 on the annual record: growth decelerated 4.1% → 1.3% → ~0.7% before separation, so the end markets are not carrying this |
| Competitive position | 25% | 7/10 | 97% gross retention, 99% among large customers, gross margin up 600bp in three years and deferred revenue +20.7%. Offset by growing at a fraction of the peer rate and Bricsys facing AutoCAD |
| Financial quality | 20% | 8/10 | 76.9% gross margin, ~20% FCF margin sustained across three years, 0.77x leverage, cash generation flat through the whole separation. The accounting loss obscures a clean cash business |
| Capital allocation | 15% | 5/10 | No track record as an independent company, and the record as a division is that Hexagon took ~96% of free cash flow in each of 2024 and 2025 plus $625M at exit. 2026 is the first year the business keeps its own cash |
| Valuation | 20% | 6/10 | Marked down from 9. Still the cheapest in the peer set at 3.2x revenue and 11.9x EBITDA, but the DCF on the actual margin range gives $19.27 — 5% up, not 26% — and at guided margin it gives the market price exactly |
Weighted score: 6.30 / 10 → Grade B
What moved the grade. It fell from B+ to B on September 9, when the audited three-year record arrived. Two dimensions moved: valuation 9 → 6, because the DCF built on the margin the business has actually delivered gives 5% upside rather than 26%; and end market 6 → 5, because the growth deceleration turns out to predate the separation. Nothing about the business quality changed — competitive position and financial quality are unmoved, and the mix evidence got stronger, not weaker.
What would move it again. A buyback announcement would take capital allocation from 5 to 7 and the grade back to B+ — and it is now the first year the company has cash of its own to do it with. Free cash flow margin sustained above 22% for two years would take valuation to 8 and the grade to A−. Conversely, a second impairment, or ARR growth below 5%, would take competitive position to 5 and the grade to B−.
The score does not include the float finding, and that is deliberate. The −4.4% median return for 50–90% float names is a real cohort result, but the bucket pools three different situations and Octave is in the least harmful one. Scoring against a mixed comparison would import a penalty this company has not earned. It is flagged in section 8 rather than priced into the grade — and if 7A.4 splits that bucket and permanently-constrained names still underperform, this grade should fall again.