Qnity Electronics Q
+11.1%vs Day 1Spinoff of DuPont (DD) · Classic Spinoff · Spun Nov 3, 2025
Expected return (11/13/2026): +10% Gain to loss: 2.5 : 1Pure-play semiconductor and electronics materials supplier growing on volume (+22% in Q3 2026, prices flat) at record margins; guidance raised twice in 2026. Cases $166 / $126 / $70, weighted 30/55/15, $130; the base case fades margins back to 34.5% and 29% by 2030. Carries 44% of DuPont's legacy liabilities including PFAS ($253M recorded). HOLD, target $130.
Current Stats
Post-Spinoff Performance
| Timeline | |
| Spinoff date | November 3, 2025 · S&P 500 |
| Days since spinoff | 376 days |
| Structure | Classic Spinoff |
| §355(e) window closes statutory; a tax matters agreement may bar more, and for longer | November 3, 2027 |
| Parent | DuPont (DD) |
| Day-1 reaction | |
| Day 1 open | $98.00 |
| Day 1 return (open→close) | -1.0% |
| Day 1 price (close) | $97.00 reported $105.01 (unverified) |
| Day 1 range | $95.00 – $100.54 +5.8% spread |
| Day 1 low held? | Breached after 2 sessions to -23.4% below |
| Price levels | |
| Post-spin low (closing) | $73.54 on Nov 24, 2025 · 21 days post-spin |
| Current price (Nov 13, 2026) | $118.36 |
| Returns | |
| Return vs Day 1 (close) | +22.3% |
| — range by day 1 entry theoretical bounds | +18.0% to +24.9% |
| Return vs post-spin low (price) | +60.9% |
| Total return vs low incl. dividends since | +61.4% |
| First-quarter return (≈90d) | -0.8% |
| 1-year return | +22.9% |
| Annualized return (CAGR) | +21.7% |
| Versus benchmarks | |
| S&P 500 over same window | +11.7% |
| Annualized excess vs S&P | +10.3% |
| Shares & ownership | |
| Shares outstanding Sep 30, 2026 | 209,164,927 |
| Diluted average shares the EPS denominator | 210,000,000 |
| Free float | 208,445,491 100% of shares outstanding |
| Held by institutions | 78% insiders 0.5% |
| Share count trend Dec 2024 → Sep 2026 | -0.1% broadly flat |
| Volume & liquidity | |
| Traded per day 20-session median | $288M |
| Normal volume baseline | 1,997,100 shares · now 1.18x |
| Day 1 volume | 5.3x normal · first week 3.1x |
| Decay | half in 5 sessions · normal by 9 |
Computed from split-adjusted closing prices. Returns are total return — (end price + dividends received − start price) ÷ start price — with no reinvestment assumed.
Price History
Closing price, split-adjusted, with volume below. The Price line excludes dividends; Price + dividends adds the cash paid out, with no reinvestment assumed. Individual payments are listed in the table below. Source: Yahoo Finance. Data through Nov 14, 2026.
Raw daily price & volume data · dividends marked
| Date | Open | High | Low | Close | Volume | Float | Turnover | Market cap | Dividend | Split |
|---|---|---|---|---|---|---|---|---|---|---|
| 2026-11-13 | $121.24 | $122.59 | $115.94 | $118.36 | 2,093,700 | 208,445,491 | 1.00% | $24.76B | — | — |
| 2026-11-12 | $122.92 | $127.28 | $122.15 | $122.69 | 2,372,800 | 208,445,491 | 1.13% | $25.66B | — | — |
| 2026-11-11 | $129.37 | $130.01 | $124.27 | $126.57 | 2,427,200 | 208,445,491 | 1.16% | $26.47B | — | — |
| 2026-11-10 | $123.66 | $126.05 | $120.62 | $123.64 | 2,728,800 | 208,445,491 | 1.30% | $25.86B | — | — |
| 2026-11-09 | $119.60 | $126.35 | $118.00 | $125.09 | 2,638,200 | 208,445,491 | 1.26% | $26.16B | — | — |
| 2026-11-06 | $117.80 | $117.91 | $113.01 | $117.00 | 2,531,500 | 208,445,491 | 1.21% | $24.47B | — | — |
| 2026-11-05 | $112.84 | $116.80 | $108.50 | $110.04 | 3,380,000 | 208,445,491 | 1.62% | $23.02B | — | — |
| 2026-11-04 | $120.00 | $120.04 | $112.50 | $118.78 | 3,277,100 | 208,445,491 | 1.57% | $24.84B | — | — |
| 2026-11-03 | $118.60 | $122.74 | $117.22 | $118.89 | 2,455,500 | 208,514,475 | 1.17% | $24.87B | — | — |
| 2026-11-02 | $118.72 | $120.92 | $115.23 | $115.37 | 2,349,600 | 208,514,475 | 1.12% | $24.13B | — | — |
| 2026-10-30 | $116.66 | $120.25 | $114.09 | $116.67 | 2,759,900 | 208,514,475 | 1.32% | $24.40B | — | — |
| 2026-10-29 | $122.50 | $124.91 | $120.68 | $122.66 | 2,326,400 | 208,635,740 | 1.11% | $25.66B | — | — |
| 2026-10-28 | $121.27 | $122.94 | $119.26 | $122.79 | 1,735,000 | 208,679,245 | 0.83% | $25.68B | — | — |
| 2026-10-27 | $115.92 | $118.98 | $115.29 | $118.75 | 1,245,700 | 208,679,245 | 0.60% | $24.84B | — | — |
| 2026-10-26 | $110.32 | $114.49 | $110.00 | $114.07 | 1,988,700 | 208,679,245 | 0.95% | $23.86B | — | — |
| 2026-10-23 | $108.00 | $110.26 | $105.00 | $109.83 | 1,897,800 | 208,679,245 | 0.91% | $22.97B | — | — |
| 2026-10-22 | $116.00 | $116.75 | $108.10 | $108.78 | 2,936,200 | 208,679,245 | 1.40% | $22.75B | — | — |
| 2026-10-21 | $121.50 | $121.80 | $119.16 | $120.17 | 1,558,200 | 208,679,245 | 0.74% | $25.14B | — | — |
| 2026-10-20 | $118.22 | $120.22 | $115.31 | $118.37 | 1,416,600 | 208,679,245 | 0.68% | $24.76B | — | — |
| 2026-10-19 | $119.61 | $120.90 | $118.20 | $119.05 | 1,492,000 | 208,679,245 | 0.71% | $24.90B | — | — |
| 2026-10-16 | $117.49 | $119.42 | $115.10 | $115.37 | 1,803,500 | 208,679,245 | 0.86% | $24.13B | — | — |
| 2026-10-15 | $117.20 | $120.09 | $115.49 | $119.61 | 1,615,400 | 208,679,245 | 0.77% | $25.02B | — | — |
| 2026-10-14 | $122.22 | $125.26 | $118.82 | $121.62 | 1,971,600 | 208,679,245 | 0.94% | $25.44B | — | — |
| 2026-10-13 | $120.82 | $123.10 | $119.53 | $122.90 | 1,926,600 | 208,679,245 | 0.92% | $25.71B | — | — |
| 2026-10-12 | $125.40 | $125.40 | $121.68 | $123.21 | 1,393,900 | 208,679,245 | 0.67% | $25.77B | — | — |
| 2026-10-09 | $128.25 | $129.49 | $124.61 | $126.60 | 1,285,500 | 208,679,245 | 0.61% | $26.48B | — | — |
| 2026-10-08 | $127.50 | $131.29 | $125.27 | $126.68 | 1,501,300 | 208,679,245 | 0.72% | $26.50B | — | — |
| 2026-10-07 | $130.72 | $131.40 | $127.92 | $129.72 | 971,000 | 208,679,245 | 0.46% | $27.13B | — | — |
| 2026-10-06 | $132.50 | $133.66 | $130.49 | $133.63 | 1,326,200 | 208,679,245 | 0.63% | $27.95B | — | — |
| 2026-10-05 | $133.87 | $133.87 | $130.03 | $131.53 | 1,901,800 | 208,679,245 | 0.91% | $27.51B | — | — |
| 2026-10-02 | $131.67 | $132.41 | $130.00 | $131.48 | 1,164,400 | 208,679,245 | 0.56% | $27.50B | — | — |
| 2026-10-01 | $125.03 | $128.50 | $123.44 | $128.45 | 1,303,400 | 208,679,245 | 0.62% | $26.87B | — | — |
| 2026-09-30 | $126.38 | $126.96 | $124.24 | $125.74 | 1,506,300 | 208,679,245 | 0.72% | $26.30B | — | — |
| 2026-09-29 | $126.81 | $127.77 | $124.84 | $125.61 | 718,400 | 208,679,245 | 0.34% | $26.29B | — | — |
| 2026-09-28 | $124.68 | $126.50 | $122.22 | $124.91 | 1,186,100 | 208,679,245 | 0.57% | $26.15B | — | — |
| 2026-09-25 | $122.58 | $125.39 | $121.80 | $124.69 | 829,800 | 208,679,245 | 0.40% | $26.10B | — | — |
| 2026-09-24 | $122.03 | $123.45 | $120.05 | $122.31 | 1,489,000 | 208,679,245 | 0.71% | $25.60B | — | — |
| 2026-09-23 | $124.51 | $126.55 | $122.70 | $124.50 | 914,700 | 208,679,245 | 0.44% | $26.06B | — | — |
| 2026-09-22 | $121.00 | $126.21 | $120.44 | $124.86 | 1,980,300 | 208,679,245 | 0.95% | $26.14B | — | — |
| 2026-09-21 | $121.90 | $122.54 | $119.60 | $121.82 | 1,619,800 | 208,679,245 | 0.77% | $25.50B | — | — |
| 2026-09-18 | $118.08 | $120.72 | $118.08 | $120.05 | 3,906,700 | 208,679,245 | 1.87% | $25.13B | — | — |
| 2026-09-17 | $117.80 | $119.23 | $116.20 | $117.13 | 1,164,500 | 208,679,245 | 0.56% | $24.52B | — | — |
| 2026-09-16 | $116.99 | $118.07 | $113.53 | $114.86 | 1,429,300 | 208,679,245 | 0.68% | $24.04B | — | — |
| 2026-09-15 | $119.15 | $120.00 | $111.75 | $114.59 | 2,515,300 | 208,679,245 | 1.20% | $23.99B | — | — |
| 2026-09-14 | $119.33 | $122.35 | $116.35 | $117.23 | 1,589,100 | 208,679,245 | 0.76% | $24.54B | — | — |
| 2026-09-11 | $125.87 | $127.16 | $124.72 | $126.40 | 865,500 | 208,679,245 | 0.41% | $26.46B | — | — |
| 2026-09-10 | $122.94 | $125.77 | $121.51 | $123.32 | 1,644,300 | 208,679,245 | 0.79% | $25.82B | — | — |
| 2026-09-09 | $122.00 | $126.63 | $121.25 | $125.47 | 1,256,300 | 208,679,245 | 0.60% | $26.27B | — | — |
| 2026-09-08 | $122.02 | $124.59 | $120.39 | $123.28 | 1,397,400 | 208,679,245 | 0.67% | $25.81B | — | — |
| 2026-09-04 | $120.00 | $122.39 | $119.64 | $120.47 | 1,310,100 | 208,708,535 | 0.63% | $25.22B | — | — |
| 2026-09-03 | $117.65 | $119.12 | $114.39 | $118.47 | 1,537,100 | 208,708,535 | 0.73% | $24.80B | — | — |
| 2026-09-02 | $116.58 | $118.77 | $114.75 | $117.69 | 2,101,600 | 208,708,535 | 1.00% | $24.64B | — | — |
| 2026-09-01 | $117.65 | $118.47 | $113.33 | $115.49 | 2,794,000 | 208,708,535 | 1.33% | $24.18B | — | — |
| 2026-08-31 | $120.25 | $121.99 | $118.86 | $119.43 | 1,946,300 | 208,698,074 | 0.93% | $25.00B | $0.08 | — |
| 2026-08-28 | $125.68 | $126.00 | $119.50 | $120.26 | 2,004,900 | 208,698,074 | 0.96% | $25.17B | — | — |
| 2026-08-27 | $128.15 | $129.21 | $125.50 | $126.35 | 1,130,100 | 208,698,074 | 0.54% | $26.45B | — | — |
| 2026-08-26 | $127.12 | $127.92 | $125.14 | $126.20 | 1,455,200 | 208,698,074 | 0.70% | $26.42B | — | — |
| 2026-08-25 | $129.04 | $129.50 | $125.81 | $126.62 | 944,900 | 208,698,074 | 0.45% | $26.51B | — | — |
| 2026-08-24 | $126.74 | $126.81 | $122.47 | $126.24 | 1,614,600 | 208,698,074 | 0.77% | $26.43B | — | — |
| 2026-08-21 | $133.26 | $134.17 | $128.71 | $128.88 | 1,734,600 | 208,698,074 | 0.83% | $26.98B | — | — |
| 2026-08-20 | $125.98 | $134.40 | $125.31 | $133.52 | 4,291,900 | 208,698,074 | 2.05% | $27.95B | — | — |
| 2026-08-19 | $135.72 | $136.07 | $125.71 | $126.04 | 1,925,200 | 208,698,074 | 0.92% | $26.38B | — | — |
| 2026-08-18 | $136.00 | $137.66 | $131.90 | $133.58 | 1,290,100 | 208,698,074 | 0.62% | $27.96B | — | — |
| 2026-08-17 | $143.66 | $144.92 | $139.94 | $140.76 | 1,361,100 | 208,698,074 | 0.65% | $29.47B | — | — |
| 2026-08-14 | $142.55 | $144.08 | $140.00 | $142.30 | 783,400 | 208,698,074 | 0.37% | $29.79B | — | — |
| 2026-08-13 | $143.87 | $146.67 | $142.00 | $142.59 | 1,595,600 | — | 0.76% | $29.85B | — | — |
| 2026-08-12 | $142.34 | $143.99 | $141.11 | $142.08 | 1,499,000 | — | 0.72% | $29.74B | — | — |
| 2026-08-11 | $135.20 | $140.83 | $134.65 | $138.24 | 1,368,200 | — | 0.65% | $28.94B | — | — |
| 2026-08-10 | $139.18 | $139.99 | $134.15 | $134.37 | 1,175,300 | — | 0.56% | $28.13B | — | — |
| 2026-08-07 | $136.46 | $138.97 | $135.71 | $138.00 | 1,311,700 | — | 0.63% | $28.89B | — | — |
| 2026-08-06 | $134.47 | $138.00 | $130.43 | $133.37 | 1,584,400 | — | 0.76% | $27.92B | — | — |
| 2026-08-05 | $140.16 | $141.15 | $135.11 | $135.64 | 2,033,800 | — | 0.97% | $28.39B | — | — |
| 2026-08-04 | $141.04 | $146.08 | $137.00 | $141.67 | 3,113,900 | — | 1.49% | $29.66B | — | — |
| 2026-08-03 | $128.86 | $135.18 | $128.71 | $133.30 | 2,641,600 | — | 1.26% | $27.90B | — | — |
| 2026-07-31 | $135.36 | $137.73 | $128.76 | $131.18 | 1,704,300 | — | 0.81% | $27.46B | — | — |
| 2026-07-30 | $129.49 | $134.66 | $129.04 | $130.52 | 3,334,900 | — | 1.59% | $27.32B | — | — |
| 2026-07-29 | $127.55 | $129.14 | $122.67 | $123.39 | 3,296,100 | — | 1.57% | $25.83B | — | — |
| 2026-07-28 | $127.18 | $128.88 | $123.72 | $127.89 | 3,075,400 | — | 1.47% | $26.77B | — | — |
| 2026-07-27 | $136.00 | $136.07 | $128.67 | $132.97 | 1,640,500 | — | 0.78% | $27.84B | — | — |
| 2026-07-24 | $137.50 | $139.71 | $134.09 | $135.06 | 1,627,800 | — | 0.78% | $28.27B | — | — |
| 2026-07-23 | $137.02 | $140.25 | $135.89 | $138.66 | 1,040,500 | — | 0.50% | $29.03B | — | — |
| 2026-07-22 | $136.15 | $140.63 | $136.15 | $138.74 | 1,032,900 | — | 0.49% | $29.04B | — | — |
| 2026-07-21 | $138.92 | $140.09 | $136.50 | $138.78 | 1,265,100 | — | 0.60% | $29.05B | — | — |
| 2026-07-20 | $138.61 | $139.80 | $134.26 | $134.58 | 1,170,900 | — | 0.56% | $28.17B | — | — |
| 2026-07-17 | $130.45 | $139.87 | $129.09 | $136.35 | 2,235,300 | — | 1.07% | $28.54B | — | — |
| 2026-07-16 | $136.85 | $138.65 | $134.10 | $135.47 | 2,299,500 | — | 1.10% | $28.36B | — | — |
| 2026-07-15 | $143.62 | $145.82 | $133.51 | $140.23 | 1,729,000 | — | 0.83% | $29.36B | — | — |
| 2026-07-14 | $145.80 | $147.88 | $140.01 | $141.67 | 1,567,700 | — | 0.75% | $29.66B | — | — |
| 2026-07-13 | $140.71 | $143.60 | $138.75 | $140.98 | 1,607,100 | — | 0.77% | $29.51B | — | — |
| 2026-07-10 | $141.19 | $145.36 | $139.70 | $143.80 | 1,232,000 | — | 0.59% | $30.10B | — | — |
| 2026-07-09 | $149.10 | $150.56 | $143.03 | $143.46 | 1,565,500 | — | 0.75% | $30.03B | — | — |
| 2026-07-08 | $139.74 | $144.49 | $137.90 | $142.17 | 1,932,100 | — | 0.92% | $29.76B | — | — |
| 2026-07-07 | $140.17 | $142.75 | $134.67 | $140.54 | 2,525,900 | — | 1.21% | $29.42B | — | — |
| 2026-07-06 | $147.99 | $152.89 | $145.54 | $146.68 | 1,946,200 | — | 0.93% | $30.71B | — | — |
| 2026-07-02 | $153.74 | $156.60 | $139.39 | $141.75 | 2,817,800 | — | 1.35% | $29.67B | — | — |
| 2026-07-01 | $158.85 | $162.69 | $152.97 | $153.37 | 1,576,100 | — | 0.75% | $32.11B | — | — |
| 2026-06-30 | $158.05 | $165.23 | $158.00 | $163.31 | 2,567,300 | — | 1.23% | $34.19B | — | — |
| 2026-06-29 | $158.00 | $161.45 | $149.29 | $158.23 | 3,860,400 | — | 1.84% | $33.14B | — | — |
| 2026-06-26 | $161.23 | $162.52 | $155.50 | $158.20 | 1,913,400 | — | 0.91% | $33.13B | — | — |
| 2026-06-25 | $166.00 | $170.00 | $159.40 | $167.49 | 1,355,900 | — | 0.65% | $35.08B | — | — |
| 2026-06-24 | $162.16 | $165.59 | $156.16 | $158.73 | 1,780,900 | — | 0.85% | $33.24B | — | — |
| 2026-06-23 | $163.98 | $167.13 | $160.08 | $161.19 | 2,416,700 | — | 1.15% | $33.76B | — | — |
| 2026-06-22 | $174.96 | $177.28 | $170.37 | $175.64 | 4,092,800 | — | 1.95% | $36.79B | — | — |
| 2026-06-18 | $160.45 | $170.07 | $159.50 | $168.98 | 5,672,900 | — | 2.71% | $35.39B | — | — |
| 2026-06-17 | $156.20 | $162.85 | $156.20 | $156.72 | 2,258,400 | — | 1.08% | $32.82B | — | — |
| 2026-06-16 | $159.44 | $160.54 | $152.17 | $152.24 | 1,364,200 | — | 0.65% | $31.89B | — | — |
| 2026-06-15 | $157.40 | $161.83 | $153.75 | $161.02 | 1,637,500 | — | 0.78% | $33.72B | — | — |
| 2026-06-12 | $148.86 | $152.49 | $147.02 | $150.65 | 1,350,700 | — | 0.64% | $31.55B | — | — |
| 2026-06-11 | $143.75 | $150.12 | $141.84 | $149.12 | 1,484,100 | — | 0.71% | $31.23B | — | — |
| 2026-06-10 | $141.67 | $146.27 | $137.60 | $139.74 | 1,918,800 | — | 0.92% | $29.27B | — | — |
| 2026-06-09 | $146.97 | $150.96 | $135.20 | $144.70 | 1,677,200 | — | 0.80% | $30.31B | — | — |
| 2026-06-08 | $146.65 | $146.81 | $141.91 | $144.45 | 1,375,900 | — | 0.66% | $30.25B | — | — |
| 2026-06-05 | $150.00 | $150.26 | $141.47 | $142.05 | 1,863,000 | — | 0.89% | $29.75B | — | — |
| 2026-06-04 | $151.43 | $156.89 | $150.10 | $154.80 | 1,255,800 | — | 0.60% | $32.42B | — | — |
| 2026-06-03 | $155.61 | $159.33 | $154.95 | $155.00 | 1,731,000 | — | 0.83% | $32.46B | — | — |
| 2026-06-02 | $153.37 | $156.64 | $152.42 | $155.74 | 2,460,700 | — | 1.17% | $32.62B | — | — |
| 2026-06-01 | $152.10 | $154.50 | $148.92 | $151.92 | 2,210,400 | — | 1.06% | $31.82B | — | — |
| 2026-05-29 | $159.00 | $160.95 | $154.50 | $156.00 | 2,500,900 | — | 1.19% | $32.67B | $0.08 | — |
| 2026-05-28 | $160.00 | $160.50 | $155.95 | $158.96 | 1,396,300 | — | 0.67% | $33.29B | — | — |
| 2026-05-27 | $166.51 | $167.06 | $157.00 | $159.11 | 1,702,200 | — | 0.81% | $33.32B | — | — |
| 2026-05-26 | $161.38 | $165.25 | $159.00 | $164.57 | 1,581,100 | — | 0.75% | $34.47B | — | — |
| 2026-05-22 | $155.00 | $157.74 | $153.29 | $156.93 | 1,564,800 | — | 0.75% | $32.87B | — | — |
| 2026-05-21 | $152.84 | $153.88 | $150.23 | $152.76 | 1,449,500 | — | 0.69% | $31.99B | — | — |
| 2026-05-20 | $149.09 | $154.36 | $148.00 | $153.04 | 1,544,700 | — | 0.74% | $32.05B | — | — |
| 2026-05-19 | $144.30 | $147.55 | $141.57 | $145.24 | 1,618,400 | — | 0.77% | $30.42B | — | — |
| 2026-05-18 | $157.98 | $158.01 | $145.57 | $149.03 | 2,181,100 | — | 1.04% | $31.21B | — | — |
| 2026-05-15 | $157.35 | $159.09 | $154.52 | $157.23 | 1,678,400 | — | 0.80% | $32.93B | — | — |
| 2026-05-14 | $163.60 | $165.57 | $160.89 | $164.12 | 2,162,300 | — | 1.03% | $34.37B | — | — |
| 2026-05-13 | $170.72 | $171.52 | $160.22 | $162.02 | 2,660,600 | — | 1.27% | $33.93B | — | — |
| 2026-05-12 | $161.05 | $168.52 | $153.46 | $168.36 | 4,434,400 | — | 2.12% | $35.26B | — | — |
| 2026-05-11 | $147.80 | $156.53 | $147.41 | $153.24 | 3,341,500 | — | 1.60% | $32.09B | — | — |
| 2026-05-08 | $147.78 | $149.30 | $145.56 | $147.33 | 2,008,400 | — | 0.96% | $30.86B | — | — |
| 2026-05-07 | $150.90 | $150.91 | $142.51 | $143.59 | 1,953,400 | — | 0.93% | $30.07B | — | — |
| 2026-05-06 | $148.04 | $151.36 | $145.12 | $149.44 | 1,859,500 | — | 0.89% | $31.30B | — | — |
| 2026-05-05 | $143.74 | $147.99 | $143.50 | $146.47 | 1,131,400 | — | 0.54% | $30.68B | — | — |
| 2026-05-04 | $143.26 | $143.72 | $139.80 | $141.06 | 1,196,100 | — | 0.57% | $29.54B | — | — |
| 2026-05-01 | $141.10 | $143.72 | $138.57 | $143.33 | 1,220,200 | — | 0.58% | $30.02B | — | — |
| 2026-04-30 | $143.08 | $144.90 | $137.35 | $140.66 | 2,511,000 | — | 1.20% | $29.46B | — | — |
| 2026-04-29 | $139.33 | $142.00 | $137.37 | $141.30 | 1,917,500 | — | 0.92% | $29.59B | — | — |
| 2026-04-28 | $138.85 | $141.17 | $135.20 | $137.59 | 1,423,300 | — | 0.68% | $28.82B | — | — |
| 2026-04-27 | $144.01 | $144.84 | $138.01 | $143.85 | 2,116,000 | — | 1.01% | $30.13B | — | — |
| 2026-04-24 | $142.88 | $146.67 | $141.43 | $144.48 | 1,602,100 | — | 0.76% | $30.26B | — | — |
| 2026-04-23 | $138.60 | $146.00 | $138.40 | $140.13 | 2,629,000 | — | 1.26% | $29.35B | — | — |
| 2026-04-22 | $137.38 | $139.79 | $136.00 | $139.25 | 1,379,200 | — | 0.66% | $29.16B | — | — |
| 2026-04-21 | $138.90 | $139.13 | $133.80 | $134.85 | 1,209,900 | — | 0.58% | $28.24B | — | — |
| 2026-04-20 | $136.25 | $138.28 | $134.99 | $138.10 | 1,032,200 | — | 0.49% | $28.92B | — | — |
| 2026-04-17 | $134.27 | $137.80 | $133.87 | $136.29 | 1,399,900 | — | 0.67% | $28.54B | — | — |
| 2026-04-16 | $130.39 | $132.23 | $129.26 | $131.30 | 1,188,000 | — | 0.57% | $27.50B | — | — |
| 2026-04-15 | $131.73 | $132.75 | $129.20 | $131.79 | 1,307,300 | — | 0.62% | $27.60B | — | — |
| 2026-04-14 | $135.69 | $136.31 | $131.75 | $132.77 | 1,264,200 | — | 0.60% | $27.81B | — | — |
| 2026-04-13 | $130.08 | $135.06 | $129.77 | $135.02 | 1,517,800 | — | 0.72% | $28.28B | — | — |
| 2026-04-10 | $131.46 | $132.21 | $130.11 | $130.65 | 1,390,100 | — | 0.66% | $27.36B | — | — |
| 2026-04-09 | $128.74 | $132.49 | $128.74 | $129.88 | 1,578,400 | — | 0.75% | $27.20B | — | — |
| 2026-04-08 | $126.50 | $131.91 | $124.62 | $129.34 | 2,252,000 | — | 1.08% | $27.09B | — | — |
| 2026-04-07 | $117.12 | $119.92 | $116.37 | $118.99 | 1,312,700 | — | 0.63% | $24.92B | — | — |
| 2026-04-06 | $117.00 | $119.05 | $115.32 | $118.87 | 1,021,500 | — | 0.49% | $24.90B | — | — |
| 2026-04-02 | $113.96 | $120.43 | $112.57 | $116.53 | 791,700 | — | 0.38% | $24.41B | — | — |
| 2026-04-01 | $115.92 | $120.82 | $115.92 | $118.56 | 1,266,300 | — | 0.60% | $24.83B | — | — |
| 2026-03-31 | $109.11 | $115.51 | $108.09 | $115.38 | 1,560,600 | — | 0.75% | $24.17B | — | — |
| 2026-03-30 | $113.79 | $113.97 | $106.17 | $107.11 | 1,858,300 | — | 0.89% | $22.44B | — | — |
| 2026-03-27 | $111.22 | $113.06 | $109.70 | $111.76 | 1,473,800 | — | 0.70% | $23.41B | — | — |
| 2026-03-26 | $117.10 | $118.97 | $112.19 | $112.78 | 1,603,200 | — | 0.77% | $23.63B | — | — |
| 2026-03-25 | $120.00 | $122.64 | $119.38 | $120.26 | 1,274,800 | — | 0.61% | $25.19B | — | — |
| 2026-03-24 | $113.71 | $119.31 | $113.71 | $118.34 | 1,709,400 | — | 0.82% | $24.79B | — | — |
| 2026-03-23 | $112.01 | $117.86 | $111.02 | $114.92 | 2,830,100 | — | 1.35% | $24.07B | — | — |
| 2026-03-20 | $111.07 | $111.94 | $106.22 | $107.59 | 5,038,800 | — | 2.41% | $22.54B | — | — |
| 2026-03-19 | $109.86 | $113.78 | $108.57 | $111.94 | 2,290,000 | — | 1.09% | $23.45B | — | — |
| 2026-03-18 | $112.54 | $116.20 | $112.40 | $113.98 | 1,307,200 | — | 0.62% | $23.88B | — | — |
| 2026-03-17 | $112.38 | $113.59 | $110.40 | $113.57 | 1,164,300 | — | 0.56% | $23.79B | — | — |
| 2026-03-16 | $111.95 | $113.22 | $109.90 | $112.25 | 1,830,700 | — | 0.87% | $23.51B | — | — |
| 2026-03-13 | $108.90 | $110.28 | $106.74 | $109.05 | 2,173,800 | — | 1.04% | $22.84B | — | — |
| 2026-03-12 | $113.50 | $113.79 | $105.41 | $107.04 | 2,623,300 | — | 1.25% | $22.42B | — | — |
| 2026-03-11 | $113.89 | $116.66 | $113.79 | $116.27 | 2,475,600 | — | 1.18% | $24.36B | — | — |
| 2026-03-10 | $113.46 | $117.16 | $112.58 | $113.97 | 1,973,300 | — | 0.94% | $23.87B | — | — |
| 2026-03-09 | $106.99 | $114.35 | $106.00 | $114.25 | 1,996,000 | — | 0.95% | $23.93B | — | — |
| 2026-03-06 | $112.06 | $115.92 | $109.27 | $110.14 | 2,299,000 | — | 1.10% | $23.07B | — | — |
| 2026-03-05 | $117.11 | $119.75 | $113.44 | $115.92 | 2,172,500 | — | 1.04% | $24.28B | — | — |
| 2026-03-04 | $118.97 | $120.64 | $116.84 | $120.03 | 2,507,700 | — | 1.20% | $25.14B | — | — |
| 2026-03-03 | $117.28 | $119.31 | $113.71 | $116.12 | 3,234,900 | — | 1.54% | $24.32B | — | — |
| 2026-03-02 | $124.43 | $126.07 | $121.29 | $124.07 | 2,131,800 | — | 1.02% | $25.99B | — | — |
| 2026-02-27 | $122.53 | $127.18 | $120.90 | $126.76 | 4,738,800 | — | 2.26% | $26.55B | $0.08 | — |
| 2026-02-26 | $139.94 | $140.60 | $117.00 | $124.78 | 8,400,000 | — | 4.01% | $26.14B | — | — |
| 2026-02-25 | $118.00 | $120.25 | $116.57 | $119.86 | 4,119,500 | — | 1.97% | $25.11B | — | — |
| 2026-02-24 | $112.39 | $117.91 | $112.39 | $116.79 | 2,421,600 | — | 1.16% | $24.47B | — | — |
| 2026-02-23 | $112.75 | $113.74 | $110.10 | $111.58 | 2,343,700 | — | 1.12% | $23.37B | — | — |
| 2026-02-20 | $111.67 | $116.20 | $111.24 | $113.46 | 2,209,100 | — | 1.05% | $23.77B | — | — |
| 2026-02-19 | $114.61 | $115.10 | $110.54 | $112.86 | 1,656,500 | — | 0.79% | $23.64B | — | — |
| 2026-02-18 | $111.84 | $117.15 | $111.65 | $115.25 | 3,416,700 | — | 1.63% | $24.14B | — | — |
| 2026-02-17 | $110.93 | $113.22 | $108.08 | $111.94 | 1,940,500 | — | 0.93% | $23.45B | — | — |
| 2026-02-13 | $109.04 | $113.88 | $108.07 | $111.69 | 2,743,800 | — | 1.31% | $23.40B | — | — |
| 2026-02-12 | $115.47 | $117.69 | $107.57 | $108.54 | 2,665,700 | — | 1.27% | $22.74B | — | — |
| 2026-02-11 | $110.62 | $114.88 | $109.06 | $114.51 | 3,003,500 | — | 1.43% | $23.99B | — | — |
| 2026-02-10 | $108.26 | $112.41 | $107.35 | $109.30 | 4,257,600 | — | 2.03% | $22.90B | — | — |
| 2026-02-09 | $98.51 | $106.29 | $97.63 | $105.20 | 2,784,200 | — | 1.33% | $22.04B | — | — |
| 2026-02-06 | $94.99 | $99.79 | $94.00 | $98.22 | 1,739,300 | — | 0.83% | $20.58B | — | — |
| 2026-02-05 | $94.57 | $97.00 | $92.67 | $92.77 | 1,515,000 | — | 0.72% | $19.43B | — | — |
| 2026-02-04 | $100.05 | $100.92 | $92.85 | $95.51 | 2,481,600 | — | 1.18% | $20.01B | — | — |
| 2026-02-03 | $100.30 | $102.44 | $97.51 | $99.88 | 2,412,600 | — | 1.15% | $20.92B | — | — |
| 2026-02-02 | $96.23 | $100.83 | $95.90 | $100.67 | 1,998,200 | — | 0.95% | $21.09B | — | — |
| 2026-01-30 | $98.89 | $99.89 | $96.01 | $96.18 | 2,547,600 | — | 1.22% | $20.15B | — | — |
| 2026-01-29 | $102.68 | $103.00 | $96.42 | $99.91 | 1,573,700 | — | 0.75% | $20.93B | — | — |
| 2026-01-28 | $100.94 | $103.10 | $99.25 | $102.43 | 2,381,800 | — | 1.14% | $21.46B | — | — |
| 2026-01-27 | $97.79 | $100.61 | $97.79 | $99.45 | 1,286,000 | — | 0.61% | $20.83B | — | — |
| 2026-01-26 | $96.32 | $99.33 | $95.24 | $96.74 | 1,813,900 | — | 0.87% | $20.27B | — | — |
| 2026-01-23 | $97.50 | $98.00 | $94.96 | $96.11 | 2,288,600 | — | 1.09% | $20.13B | — | — |
| 2026-01-22 | $106.00 | $107.84 | $97.90 | $98.76 | 3,652,300 | — | 1.74% | $20.69B | — | — |
| 2026-01-21 | $96.62 | $103.87 | $95.34 | $102.70 | 4,158,800 | — | 1.99% | $21.51B | — | — |
| 2026-01-20 | $93.97 | $97.63 | $93.12 | $95.13 | 1,719,400 | — | 0.82% | $19.93B | — | — |
| 2026-01-16 | $94.17 | $100.13 | $93.96 | $97.25 | 4,156,500 | — | 1.98% | $20.37B | — | — |
| 2026-01-15 | $93.64 | $97.84 | $92.89 | $93.12 | 4,533,800 | — | 2.16% | $19.51B | — | — |
| 2026-01-14 | $88.45 | $89.94 | $85.67 | $89.88 | 1,266,400 | — | 0.60% | $18.83B | — | — |
| 2026-01-13 | $91.09 | $92.04 | $88.93 | $89.67 | 2,735,400 | — | 1.31% | $18.78B | — | — |
| 2026-01-12 | $89.95 | $92.95 | $89.34 | $90.91 | 2,865,300 | — | 1.37% | $19.04B | — | — |
| 2026-01-09 | $90.17 | $91.89 | $88.84 | $90.31 | 2,140,500 | — | 1.02% | $18.92B | — | — |
| 2026-01-08 | $89.91 | $90.74 | $88.33 | $89.50 | 2,336,800 | — | 1.12% | $18.75B | — | — |
| 2026-01-07 | $92.00 | $92.94 | $89.34 | $90.31 | 1,655,400 | — | 0.79% | $18.92B | — | — |
| 2026-01-06 | $85.21 | $91.91 | $85.00 | $91.14 | 2,103,900 | — | 1.00% | $19.09B | — | — |
| 2026-01-05 | $85.00 | $86.87 | $84.98 | $85.11 | 1,269,500 | — | 0.61% | $17.83B | — | — |
| 2026-01-02 | $81.69 | $86.32 | $81.61 | $84.98 | 1,221,100 | — | 0.58% | $17.80B | — | — |
| 2025-12-31 | $84.09 | $84.09 | $81.56 | $81.65 | 1,098,000 | — | 0.52% | $17.10B | — | — |
| 2025-12-30 | $84.11 | $85.00 | $83.48 | $84.01 | 1,142,800 | — | 0.55% | $17.59B | — | — |
| 2025-12-29 | $84.00 | $84.38 | $83.00 | $83.59 | 1,117,700 | — | 0.53% | $17.51B | — | — |
| 2025-12-26 | $83.63 | $84.43 | $83.47 | $84.21 | 851,200 | — | 0.41% | $17.64B | — | — |
| 2025-12-24 | $83.37 | $83.64 | $82.71 | $83.37 | 637,000 | — | 0.30% | $17.46B | — | — |
| 2025-12-23 | $81.54 | $83.26 | $81.13 | $83.17 | 1,244,100 | — | 0.59% | $17.42B | — | — |
| 2025-12-22 | $80.96 | $82.73 | $80.54 | $81.89 | 1,723,300 | — | 0.82% | $17.15B | — | — |
| 2025-12-19 | $79.37 | $80.00 | $77.18 | $79.70 | 6,553,300 | — | 3.13% | $16.69B | — | — |
| 2025-12-18 | $78.32 | $80.69 | $77.76 | $79.03 | 2,565,700 | — | 1.23% | $16.55B | — | — |
| 2025-12-17 | $78.93 | $78.98 | $75.67 | $76.26 | 2,017,500 | — | 0.96% | $15.97B | — | — |
| 2025-12-16 | $76.50 | $79.13 | $76.14 | $78.50 | 2,971,700 | — | 1.42% | $16.44B | — | — |
| 2025-12-15 | $79.65 | $80.72 | $75.65 | $76.63 | 2,338,300 | — | 1.12% | $16.05B | — | — |
| 2025-12-12 | $84.38 | $84.59 | $78.35 | $78.94 | 2,778,200 | — | 1.33% | $16.53B | — | — |
| 2025-12-11 | $85.76 | $86.24 | $83.51 | $84.80 | 2,563,500 | — | 1.22% | $17.76B | — | — |
| 2025-12-10 | $83.79 | $87.95 | $82.73 | $86.20 | 2,396,800 | — | 1.14% | $18.05B | — | — |
| 2025-12-09 | $84.00 | $85.23 | $83.71 | $85.09 | 1,404,900 | — | 0.67% | $17.82B | — | — |
| 2025-12-08 | $81.95 | $84.69 | $81.82 | $84.30 | 1,653,000 | — | 0.79% | $17.66B | — | — |
| 2025-12-05 | $83.41 | $83.85 | $81.82 | $82.04 | 1,980,300 | — | 0.95% | $17.18B | — | — |
| 2025-12-04 | $80.00 | $83.57 | $79.81 | $83.46 | 1,826,200 | — | 0.87% | $17.48B | — | — |
| 2025-12-03 | $79.97 | $81.05 | $78.90 | $80.28 | 1,244,700 | — | 0.59% | $16.81B | — | — |
| 2025-12-02 | $78.17 | $80.49 | $77.97 | $79.75 | 2,182,000 | — | 1.04% | $16.70B | — | — |
| 2025-12-01 | $79.00 | $81.09 | $77.42 | $77.60 | 1,622,200 | — | 0.77% | $16.25B | — | — |
| 2025-11-28 | $79.28 | $81.25 | $79.28 | $81.09 | 947,300 | — | 0.45% | $16.98B | $0.06 | — |
| 2025-11-26 | $77.95 | $80.74 | $77.00 | $79.23 | 2,234,700 | — | 1.07% | $16.59B | — | — |
| 2025-11-25 | $73.00 | $79.06 | $72.94 | $78.01 | 3,033,500 | — | 1.45% | $16.34B | — | — |
| 2025-11-24 | $76.34 | $76.74 | $72.81 | $73.54 | 5,002,100 | — | 2.39% | $15.40B | — | — |
| 2025-11-21 | $74.97 | $77.93 | $73.22 | $75.80 | 2,736,100 | — | 1.31% | $15.88B | — | — |
| 2025-11-20 | $82.01 | $83.50 | $74.50 | $74.90 | 3,072,500 | — | 1.47% | $15.69B | — | — |
| 2025-11-19 | $79.13 | $80.31 | $75.72 | $79.62 | 3,325,400 | — | 1.59% | $16.68B | — | — |
| 2025-11-18 | $79.50 | $82.03 | $78.01 | $78.98 | 3,116,500 | — | 1.49% | $16.54B | — | — |
| 2025-11-17 | $81.63 | $84.10 | $79.20 | $81.46 | 2,504,600 | — | 1.20% | $17.06B | — | — |
| 2025-11-14 | $84.15 | $87.05 | $81.62 | $83.48 | 2,466,200 | — | 1.18% | $17.48B | — | — |
| 2025-11-13 | $91.50 | $91.75 | $84.82 | $85.90 | 3,926,100 | — | 1.87% | $17.99B | — | — |
| 2025-11-12 | $96.67 | $96.67 | $91.25 | $91.96 | 2,740,700 | — | 1.31% | $19.26B | — | — |
| 2025-11-11 | $98.45 | $102.15 | $95.50 | $96.53 | 2,492,600 | — | 1.19% | $20.22B | — | — |
| 2025-11-10 | $94.93 | $99.39 | $93.60 | $96.60 | 3,220,400 | — | 1.54% | $20.23B | — | — |
| 2025-11-07 | $92.16 | $95.00 | $88.68 | $92.31 | 3,282,800 | — | 1.57% | $19.33B | — | — |
| 2025-11-06 | $100.00 | $101.15 | $93.33 | $93.33 | 4,096,200 | — | 1.96% | $19.55B | — | — |
| 2025-11-05 | $105.01 | $105.40 | $93.38 | $99.65 | 7,108,500 | — | 3.39% | $20.87B | — | — |
| 2025-11-04 | $99.50 | $104.00 | $97.80 | $100.91 | 6,091,300 | — | 2.91% | $21.13B | — | — |
| 2025-11-03 | $98.00 | $100.54 | $95.00 | $97.00 | 10,626,200 | — | 5.07% | $20.32B | — | — |
Close is split-adjusted to current shares. It is not dividend-adjusted: dividends are listed separately, so total return is (end price + dividends received − start price) ÷ start price, checkable by hand. Volume is as-traded.
Momentum: MACD and RSI
Top: MACD (navy) and its signal line (gold); bars show the gap between them, teal when MACD is above.
Bottom: RSI over 14 days; above 70 is usually read as overbought and below 30 as oversold.
The lines start late because MACD needs 26 trading days of prices and RSI 14 before the first value.
The colored strip under the charts shows the state label day by day; hover for the state and the reason.
Both measure momentum in the price and say nothing about value. Hover for each day's arithmetic.
Source: closing prices from this site's daily price archive (Yahoo Finance), not adjusted for dividends. Data through Nov 14, 2026.
How these are calculated
Short Selling
Bars: shares sold short each day in trades reported to FINRA (off-exchange
trades, roughly half of all volume).
Line: the short share of that volume, averaged over 20 sessions.
Gold points: short interest, the shares sold short and not yet bought back,
reported twice a month, also shown as a percentage of the free float and of
shares outstanding.
Daily short volume includes market makers' routine hedging, so a change in the
share is more informative than its level. Hover for each day's figures.
Sources: FINRA; float from this site's daily share records; shares outstanding
from the company's latest quarterly filing. Data through Nov 13, 2026.
Index-Fund Holdings
Daily positions of State Street's SPDR index funds, by the fund's file date.
These are the index funds whose daily holdings can be collected; iShares and
Vanguard funds, often larger holders, publish holdings that cannot be
collected automatically and appear in the written analysis from their
quarterly filings.
Collection began on October 11, 2026. A fund that drops the stock shows as an
exit.
Source: State Street Global Advisors. Data through
Nov 12, 2026.
Update — November 4, 2026: third-quarter results — HOLD, target $123 → $130
Rated at the November 4, 2026 close of $118.78. The results were released before the open that day. Source: the third-quarter results release and the third-quarter 10-Q, both of November 4, 2026. The analyses below are left as published; this section tests the results against the October 15, 2026 update, reruns the three scenarios on the raised guidance and changes the weights.
Overview Summary
The third quarter met the test the October 15, 2026 update set for raising the best case. Sales rose 22%, all of it volume; the Interconnect Solutions margin reached 31.1%, above the 30% the page named; and guidance was raised for the second time, adjusted EBITDA to $1.785–1.805 billion from about $1.70 billion and free cash flow to $800–900 million from $600–700 million. The best case’s weight rises from 25% to 30%, taken from the base case, and the target rises from $123 to $130: about $2 from the weights and about $4.50 from the quarter. At $118.78 the expected return is +9.3% and the gain to loss 2.5 to 1, at the top of the HOLD band; ACCUMULATE starts below $118.06.
Rating: BUY below $103.90 · ACCUMULATE $103.90–118.06 · HOLD $118.06–144.30 · TRIM $144.30–173.16 · SELL above $173.16 · Target $130
The quarter against the tests
| Test (October 15, 2026) | Third quarter 2026 | Verdict |
|---|---|---|
| Guidance raised again with margins above 30% in Interconnect would raise the best case | Interconnect Solutions adjusted EBITDA $236 million on sales of $759 million, a 31.1% margin (26.1% a year earlier); guidance raised for the second time this year | Met |
| Customers trimming orders or rising inventory would raise the worst case | Volume rose 16% in Semiconductor Technologies and 29% in Interconnect; Qnity’s own inventory rose 17% from December 31, 2025, against sales up 22% in the quarter | Not seen |
| Price (the cases assume −1% to −2% a year) | Price and mix were flat in both segments in the quarter; −1% in Semiconductor Technologies for the nine months | Better than the base case |
- Sales were $1,556 million, up 22%: Semiconductor Technologies $797 million (+15%; volume +16%, currency −1%) and Interconnect Solutions $759 million (+30%; volume +29%, currency +1%).
- Adjusted EBITDA was $503 million, a 32.3% margin, against $370 million on the pro forma basis a year earlier. Semiconductor Technologies earned 35.8% and Interconnect 31.1%; the base case had both reaching only 34.5% and 29.0% by 2030.
- Adjusted earnings per share were $1.46, against $0.94; GAAP earnings per share were $0.87.
- The stock fell 0.1% on the day, to $118.78, while SMH, the semiconductor ETF, fell 2.7% and SPY rose 1.7%.
The raised guidance and the fourth quarter
| 2026 | Previous guidance | November 4, 2026 | Implied fourth quarter | Fourth quarter 2025 |
|---|---|---|---|---|
| Net sales | about $5.6 billion | $5.77–5.83 billion | $1,470–1,530M | $1,190M |
| Adjusted EBITDA | about $1.70 billion | $1.785–1.805 billion | $440–460M | $350M |
| Adjusted earnings per share | $4.51 (midpoint) | $4.95–5.05 | ||
| Adjusted free cash flow | $600–700 million | $800–900 million | $193–293M |
The fourth quarter implied by the guidance grows sales 24–29% and EBITDA 26–31% on a year earlier, slightly slower than the third quarter.
Cash and the debt
- Adjusted free cash flow was $320 million in the quarter and $607 million in nine months. The company’s measure leaves out costs shared with DuPont and the cost of separating its IT systems; operating cash flow less capital spending was $357 million for the nine months. Receivables and inventory used $337 million as sales grew, partly offset by $203 million more in payables.
- Net debt was about $2.90 billion at September 30, 2026: debt of $4,019 million (carrying value) less cash of $1,124 million, against $3.06 billion at June 30, 2026. About 1.6 times the guided 2026 EBITDA.
- Qnity bought back $75 million of shares in the nine months and paid $50 million of dividends; diluted shares were 210.0 million, against the 210.3 million the cases used.
- The DuPont indemnity fell to $218 million at September 30, 2026 ($81 million current, $137 million noncurrent), from $253 million at June 30, 2026, and the cases now deduct the lower figure, adding about $0.17 a share. The 10-Q puts the reasonably possible exposure at up to about $100 million above the amount recorded.
The scenarios and the asymmetry after the third quarter
The October 9, 2026 drivers are unchanged except where the bridge shows. 2026 is now the nine months reported plus a fourth quarter at the guidance (sales split between the segments as in the third quarter), each case’s 2026 EBITDA sits at the bottom, middle and top of the raised range, and the margin path starts from the third quarter’s levels, fading to the October 2030 targets.
| Step | Best | Base | Worst | Weighted |
|---|---|---|---|---|
| October 15, 2026, at 25 / 60 / 15 | $163.70 | $120.78 | $65.37 | $123.20 |
| Weights 30 / 55 / 15 | + $2.15 | |||
| Net debt $2.90 billion and 210.0 million shares at September 30, 2026 | + $1.01 | + $0.95 | + $0.87 | + $0.96 |
| DuPont indemnity $218 million at September 30, 2026 (was $253 million) | + $0.17 | + $0.17 | + $0.17 | + $0.17 |
| 2026 sales and EBITDA at the raised guidance | + $0.84 | + $3.65 | + $3.48 | + $2.78 |
| Margins starting from the third quarter’s 35.8% and 31.1% | + $0.71 | + $0.66 | + $0.23 | + $0.61 |
| November 4, 2026, at 30 / 55 / 15 | $166.44 | $126.22 | $70.12 | $129.87 |
| vs $118.78 | +40% | +6% | −41% | +9.3% |
- The cases move less than the quarter. The value rests on the exit multiple of 16 times 2033 EBITDA, and the growth and margin paths from 2027 are those of October 2026; a higher 2026 adds about $4 to the base case.
- The base case’s margins now fall from the third quarter’s level to the 2030 targets, 34.5% and 29.0%. If the third quarter’s margins held through 2030, the base case would be $134.07 (an estimate).
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $122.25 | +3% | 1.3 to 1 |
| Best guess: 30 / 55 / 15 (was 25 / 60 / 15) | $129.87 | +9.3% | 2.5 to 1 |
| Stress: 10 / 40 / 50 | $102.19 | −14% | 0.3 to 1 |
| What the price implies: 18 / 55 / 27 | $118.78 | 0% | 1.0 to 1 |
The weights are a judgement. All values are estimates from the model.
- Why the best case gains 5 points. The October 15, 2026 update named the evidence for raising it: guidance raised again with margins above 30% in Interconnect. Both happened, and volume grew 16–29% with flat prices. The best case still needs margins of 37% and 31% sustained through 2030 and growth of 15% and 24% in 2027, so it stays well short of the base case’s weight.
- The worst case keeps 15%. A semiconductor downturn in 2027 is the risk it represents, and nothing in the quarter points either way on its timing; on the day the stock was nearly flat while the semiconductor index fell 2.7%.
- The price implies 18% on the best case and 27% on the worst, holding the base case at 55%, against the best guess of 30% and 15%.
| Measure | At $118.78 | Formula |
|---|---|---|
| Expected return (header chip) | +9.3% | (30% × $166.44 + 55% × $126.22 + 15% × $70.12) ÷ $118.78 − 1 = ($49.93 + $69.42 + $10.52) ÷ $118.78 − 1 |
| Gain to loss (header chip) | 2.5 to 1 | (30% × $47.66 + 55% × $7.44) ÷ (15% × $48.66) = ($14.30 + $4.09) ÷ $7.30 |
| Expected base gain ÷ expected worst loss | 0.56 to 1 | $4.09 ÷ $7.30 |
| Best gain ÷ worst loss | 0.98 to 1 | $47.66 ÷ $48.66 |
| Base gain ÷ worst loss | 0.15 to 1 | $7.44 ÷ $48.66 |
Both header chips take the color of the rating band the price is in: BUY green (an expected return of +25% or more with gain to loss of 3 to 1 or better), ACCUMULATE blue (+10% to +25%), HOLD gold (−10% to +10%), TRIM orange (−25% to −10%) and SELL red (below −25%). On the best guess they are green below $103.90, blue up to $118.06, gold up to $144.30, orange up to $173.16 and red above. At $118.78 both are gold, the HOLD band.
What it means for the rating
HOLD, target $123 → $130. The target is the best-guess value, $129.87. At $118.78 the expected return is +9.3%, at the top of the HOLD band of −10% to +10% (the site’s rating scale, see the Methodology page); ACCUMULATE starts below $118.06, $0.72 under the price. It is not ACCUMULATE because the expected gain depends mostly on the best case ($14.30 of the $18.39) and the base case is only 6% above the price, with margins that have to hold near a record.
| Action | Level | Reason |
|---|---|---|
| Buy | Below about $103.90 | Expected return 25% or more on the best guess; gain to loss is 6.1 to 1 there |
| Accumulate | $103.90–118.06 | Expected return 10–25% |
| Hold | $118.06–144.30 | Expected return −10% to +10%, around the $130 target |
| Trim | $144.30–173.16 | Expected return −10% to −25% |
| Sell | Above about $173.16 | Expected return below −25% |
| Move the bands down | Customers trimming orders, a fourth quarter below the guidance, or price cuts returning to −2% a year | The worst case’s weight rises |
| Move the bands up | 2027 guidance near the best case’s growth, margins held at the third quarter’s levels | The best case’s weight rises, or the base case’s margins move up |
What the fourth-quarter results (about late February 2027, date not yet announced) must show:
| Item | Why it matters | The base case needs |
|---|---|---|
| Fourth-quarter sales and EBITDA | Guided to $1,470–1,530 million and $440–460 million | Within the range |
| Segment margins | 35.8% and 31.1% in the third quarter; the base case fades them to 34.5% and 29.0% by 2030 | At or above the fade path |
| 2027 guidance | The base case has sales growth of about 13% and EBITDA about $2.1 billion in 2027 | Close to it |
| Price | Flat in the third quarter; the cases assume −1% to −2% a year | No return to larger cuts |
| Inventory and orders | The worst case’s trigger | No customer trimming |
| The DuPont indemnity | $218 million at September 30, 2026, down from $253 million | No large increase in the 10-K |
Update — October 15, 2026: the asymmetry, the money, the debt and where Qnity is — HOLD, target $123
Written against the October 14, 2026 close of $121.62. Sources: Qnity’s FY2025 10-K, the second-quarter 2026 10-Q, the credit agreement and the term-loan repricing of July 1, 2026; SEMI and WSTS industry data, TrendForce, and Qnity’s own and its peers’ results for the cycle; Qnity’s locations page, DuPont press releases, EPA records and local news for the sites; and California’s second amended PFAS complaint of August 6, 2026. The three scenarios of October 9, 2026 are unchanged. The analyses below are left as published; this section sets the scenario weights on the evidence and adds the money, the debt, the physical footprint, short interest and volatility. The rating is unchanged; the target moves from $118 to $123 because the weights change.
The one-line version
Qnity is fairly priced. Weighted 25% best, 60% base and 15% worst on the evidence, it is worth about $123, an expected return of 1% with $1.20 of probability-weighted gain for each $1 of loss, and the price implies almost the same weights. A 2023-style destocking in 2027 looks unlikely: chipmakers’ inventories are at a three-year low and spending on chipmaking equipment is forecast to rise 22–38% in 2027. A milder dip is more likely and would still cost about $19 a share. The debt is large but long: $4.1 billion, raised to pay DuPont, with nothing beyond 1% a year due before 2032 and free cash flow that repays it even in the worst case. Customers are concentrated in East Asia, where most of the plants are; China took 33% of 2025 sales. A new legal risk has appeared: California is seeking to make Qnity directly liable for DuPont’s PFAS costs.
How the money moves
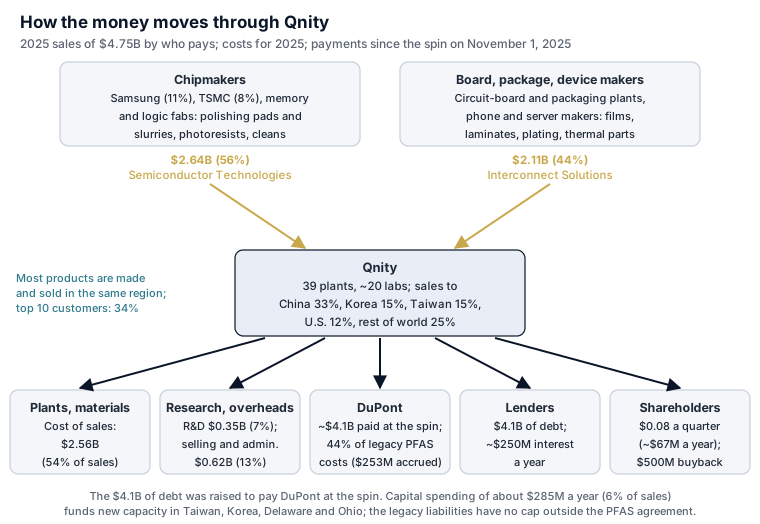
Who pays:
- Chipmakers pay for the Semiconductor Technologies segment, 56% of 2025 sales: polishing pads and slurries, photoresists, cleans. Samsung was 11% of sales and TSMC 8%; the top 10 customers were 34%.
- Circuit-board, packaging and device makers pay for Interconnect Solutions, 44%: films, laminates, plating chemistry and thermal and shielding parts.
- By customer location in 2025: China 33%, Korea 15%, Taiwan 15%, the rest of Asia 16%, the U.S. 12% and Europe and other 9%. About 85% of products are made and sold in the same region.
Where each $100 of revenue went, 2025, as if standalone (2025 results with standalone interest and estimated taxes). The add-back line reverses depreciation, stock compensation and separation costs included in the cost lines, as adjusted EBITDA does. The company’s own pro forma adjusted free cash flow for 2025 was $706M, about $14.90 per $100, close to the $15.07 here; 2026 guidance is $600–700M on about $5.6B of sales. Source: the FY2025 10-K and the second-quarter 2026 10-Q; per-$100 figures are calculations.
About $15 of each $100 of sales becomes free cash flow as a standalone company (an estimate), after interest on the $4.1 billion of debt and capital spending of about 6% of sales; the company’s own pro forma figure for 2025 was $706 million, about $14.90 per $100.
The debt, tranche by tranche
All $4.1 billion was raised at the spin and paid to DuPont, as part of about $4.1 billion of cash it received.
| Tranche | Amount ($M) | Rate | Matures | Repaying early | Security | Notes |
|---|---|---|---|---|---|---|
| Senior secured term loan | 2,338 | SOFR + 1.75% (from July 1, 2026; was + 2.00%), no floor | October 31, 2032 | At par; 1% premium on a repricing before about January 1, 2027 | First lien | Repays $23.5M a year |
| 5.750% senior secured notes | 1,000 | 5.750% fixed | August 15, 2032 | Make-whole before August 15, 2028; then 102.875%, 101.438%, par from 2030 | First lien, equal with the term loan | |
| 6.250% senior unsecured notes | 750 | 6.250% fixed | August 15, 2033 | Make-whole before August 15, 2028; then 103.125%, 101.563%, par from 2030 | Senior unsecured | |
| Total drawn | 4,088 | ~6.0% (term loan floating at ~5.9% today; notes fixed at 5.75% and 6.25%) | ||||
| Revolving credit | $1,250M | SOFR + 1.25–2.25% by first-lien net leverage | October 2030 | First lien | Undrawn; $12M of letters of credit |
All $4.1 billion was raised at the spin and paid to DuPont as part of about $4.1 billion of cash. The term loan floats with no swaps and repays 1% a year; the notes are bullets. The term loan and the 5.750% notes share a first lien on substantially all assets of Qnity and its U.S. and Japanese guarantors. Source: the FY2025 10-K, Note 14, the second-quarter 2026 10-Q, Note 12, the credit agreement and the term-loan repricing of July 1, 2026. As of June 30, 2026.
Principal due by year, including scheduled amortization. Nothing beyond the 1% term-loan amortization is due before 2032; $4.0 billion falls in 2032–33.
Qnity can repay everything due by 2032 from its own cash, even in the worst case. Comparing the cash available by August 2032 with the term loan and the secured notes due that year (estimates):
| Base case | Worst case | |
|---|---|---|
| Free cash flow, July 2026–August 2032 | $6.64B | $3.63B |
| Dividends at $0.08 a quarter | − ~$0.41B | − ~$0.41B |
| Cash at June 30, 2026 | + ~$0.96B | + ~$0.96B |
| Available to repay debt | = ~$7.19B | = ~$4.18B |
| Term loan and secured notes, due 2026–2032 | − $3.34B | − $3.34B |
| Cash left after repaying them | = ~$3.85B | = ~$0.84B |
The base case also covers the $0.75 billion of unsecured notes due in 2033 several times over; the worst case covers them with about $0.09 billion to spare, before any buybacks. $450 million of the $500 million buyback authorized in February 2026 remains.
Interest expense, 2026–2031
The term loan floats with no swaps, so rates matter. It pays SOFR plus 1.75% since its repricing on July 1, 2026, and repays 1% a year; the notes are fixed. The forecast uses the SOFR path priced in fed funds futures on October 9, 2026, as on the site’s other profiles (all figures estimates, $ millions):
| $ millions | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 |
|---|---|---|---|---|---|---|
| SOFR, yearly average | ~3.75% | ~4.40% | ~4.65% | ~4.65% | ~4.65% | ~4.65% |
| Term loan (SOFR + 1.75%) | $132 | $142 | $147 | $145 | $144 | $142 |
| 5.750% secured notes (fixed) | + $58 | + $58 | + $58 | + $58 | + $58 | + $58 |
| 6.250% unsecured notes (fixed) | + $47 | + $47 | + $47 | + $47 | + $47 | + $47 |
| Issuance costs written off over the term (non-cash) | + $10 | + $10 | + $10 | + $10 | + $10 | + $10 |
| Interest expense | = ~$246 | = ~$257 | = ~$261 | = ~$260 | = ~$258 | = ~$257 |
The 2026 figure matches the $122 million reported for the first half, doubled. Source: model in the site’s analysis files.
What a change in rates would do (interest expense, $ millions):
| SOFR path | 2027 | 2028 | 2029 | 2030 | 2031 | 2026–2031 | Change |
|---|---|---|---|---|---|---|---|
| 1 point lower | $234 | $239 | $237 | $236 | $235 | $1,403 | − $137 |
| Futures path | $257 | $261 | $260 | $258 | $257 | $1,540 | |
| 1 point higher | $280 | $284 | $283 | $281 | $279 | $1,677 | + $137 |
| 2 points higher | $303 | $307 | $305 | $303 | $301 | $1,814 | + $274 |
Each point of SOFR costs about $23 million a year, about $0.09 a share after tax, which matches the company’s own estimate of $24 million.
| Covenant | Limit | Now | Room | Protects |
|---|---|---|---|---|
| First-lien net leverage (first-lien debt less all unrestricted cash, over EBITDA as the agreement defines it, which adds back separation and indemnity costs and up to 30% for cost savings) | 4.50× at each quarter end; 5.00× for four quarters after an acquisition over $500M | ~1.5× at June 30, 2026 (an estimate on adjusted EBITDA; not disclosed) | EBITDA could fall ~65% | Revolver only; a breach lets revolver lenders, not term lenders, act first |
| Excess cash flow sweep | 50% of excess cash flow repays the term loan from 2026; 25% at first-lien net leverage of 2.50× or less, none at 2.00× or less | ~1.5×, so no sweep | — | Term loan |
| Dividends and buybacks | Unlimited at total net leverage of 3.00× or less; otherwise baskets of $555M–650M or more | ~2.0× total net leverage (an estimate) | Wide | Credit agreement and both indentures |
| Change of control | Notes: 101% repurchase if anyone acquires over 50%; bank debt: default | — | — | Notes; bank debt |
| Mergers and buybacks (tax matters agreement with DuPont, not the debt) | Until November 2, 2027: no sale of 40% or more of the stock in a combined transaction, no merger, no sale of 25% or more of an active business; buybacks only within the IRS open-market safe harbour | $500M buyback authorized February 20, 2026; $50M used by June 30, 2026 | Restrictions end November 2, 2027 | Shares and M&A |
No credit ratings are disclosed in the filings. Qnity also must keep EBITDA of at least $1.1 billion, its 44% share of $2.5 billion, before transferring businesses without the legacy liabilities that go with them.
The covenant has wide room in every case. First-lien net leverage, on the scenarios with free cash flow after dividends kept as cash, peaks at about 1.5 times at the end of 2027 in the worst case, when EBITDA falls to about $1.2 billion, against the 4.50 times limit; in the base case it is about 0.7 times by the end of 2027. At 2.00 times or less no excess cash flow has to repay the term loan, and at 3.00 times or less of total net leverage there is no limit on dividends and buybacks.
Where Qnity is
Qnity makes its materials close to its customers’ fabs. The 10-K counts about 100 facilities in 20 countries, 39 of them plants (five run by joint ventures), and says about 20% are owned; it names none of them, so the sites below come from Qnity’s locations page, DuPont press releases, EPA records and local news.
About 100 facilities in 20 countries, 39 of them manufacturing sites (5 run by joint ventures), per the 10-K; about 20% are owned. The sites shown are those that could be located individually. Click a point for details. Map data © OpenStreetMap contributors. Source: the FY2025 10-K (counts, regions, head office) and, for individual sites, Qnity’s locations page, DuPont press releases, EPA records, local news and job postings; customer sites from company announcements; coordinates from OpenStreetMap. As of October 15, 2026.
East Asia: Qnity’s plants and technical centres (dark, gold, teal, grey) against its customers’ fabs and packaging plants (red). Samsung (11% of 2025 sales) and TSMC (8%) are the largest customers; China, Korea and Taiwan together took 63% of sales. Click a point for details. Map data © OpenStreetMap contributors. Source: the FY2025 10-K (counts, regions, head office) and, for individual sites, Qnity’s locations page, DuPont press releases, EPA records, local news and job postings; customer sites from company announcements; coordinates from OpenStreetMap. As of October 15, 2026.
United States: Qnity’s plants sit in the Northeast and Ohio, while the new fabs are in Arizona, Texas, New York, Ohio, Idaho and Indiana; several of those are not yet producing (Intel Ohio around 2030, Micron New York around 2030, SK hynix Indiana in 2029). Click a point for details. Map data © OpenStreetMap contributors. Source: the FY2025 10-K (counts, regions, head office) and, for individual sites, Qnity’s locations page, DuPont press releases, EPA records, local news and job postings; customer sites from company announcements; coordinates from OpenStreetMap. As of October 15, 2026.
- East Asia holds most of the plants and most of the customers.
- In Taiwan, the Zhunan pad plant and a new plant next to it, bought for $61.5 million and due to start in early 2027, sit beside TSMC’s packaging sites and close to Hsinchu.
- In Korea, the Cheonan plant (photoresists and pads, with a $110 million expansion to 2029) and the Hwaseong technical centre sit beside Samsung’s Hwaseong, Pyeongtaek and Onyang fabs and near SK hynix.
- Japan has the photoresist plant at Sasakami, which roughly doubled its capacity in 2024, and joint-venture plants for pads, packaging dielectrics and films.
- The U.S. plants are in the Northeast and Ohio: polishing pads in Newark, Delaware (a new 385,000 sq ft plant opened in March 2026), photoresists in Marlborough, Massachusetts, photoresist polymers in Dayton, Ohio, and films in Circleville, Ohio and near Houston. None is near the new fabs in Arizona, Texas, New York, Ohio or Indiana, and several of those fabs will not produce until 2029–31.
- Employees number more than 10,000: 60% in Asia, 32% in the U.S. and Canada, 5% in Europe and 3% in Latin America. Long-lived assets are mostly in the U.S. ($1.06 billion of $1.70 billion).
The scenarios and the asymmetry
The three cases are the ones built on October 9, 2026: best $163.70 (AI-driven volume growth of 15–24% in 2027 and record margins), base $120.78 (12–18% growth in 2027 fading to about 6%, prices falling 1.5% a year) and worst $65.37 (a repeat of 2023’s destocking in 2027), against $121.62 (+35%, −1% and −46%).
Four stress tests around them (estimates):
| Stress | What it assumes | Value | vs $121.62 |
|---|---|---|---|
| Mild dip in 2027, like 2019 | 2027 sales down about 2% and EBITDA about 6%, then the base path | $101.82 | −16% |
| 2023-type destocking (the worst case) | 2027 sales −15%, EBITDA −26%, then slower growth | $65.37 | −46% |
| Deeper fall, like 2009 | 2027 volume −20% to −25%, then the worst case’s path | $58.26 | −52% |
| PFAS beyond the recorded amount | A further $1 billion of liabilities, on the base case | $116.03 | −5% |
Three weightings, and what the price implies. The standard set, 25 / 50 / 25, and the stress set, 10 / 40 / 50, are the same for every company; the best guess is set from the evidence and drives the target and the two chips at the top of the page.
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $117.66 | −3% | 0.7 to 1 |
| Best guess: 25 / 60 / 15 | $123.20 | +1% | 1.2 to 1 |
| Stress: 10 / 40 / 50 | $97.37 | −20% | 0.15 to 1 |
| What the price implies: 23 / 60 / 17 | $121.62 | 0% | 1.0 to 1 |
The weights are a judgement. All values are estimates from the model.
Why the best guess:
- A full destocking in 2027 is unlikely, about 10% on the evidence.
- Deep falls in semiconductor-materials revenue came in 3 of about 25 years: 2001, 2009 (−19%) and 2023 (−8%), each after a demand shock on top of excess inventory. Qnity fell further than the market in 2023 (−15%) because of its China and consumer exposure.
- The signals now point the other way: chipmakers’ inventories are at a three-year low and memory makers’ have fallen about 30% this year; spending on chipmaking equipment is forecast to rise 22–38% in 2027 and fab capacity 5%; memory makers say supply stays tight through 2027; Qnity reports healthy order books.
- Against that, memory buyers are stockpiling at high prices, which ABI Research expects to leave customers overstocked in 2027, and chip stocks have fallen about 10% in the past week on worries about funding for AI spending.
- The worst case gets 15%, above that 10%, because a milder dip is about twice as likely and would cost about $19 a share, and because of the new PFAS claim below.
- The best case keeps the standard 25%. Volume is growing 20–23% now and advanced packaging more than 50%, but the best case also needs record margins, and guidance implies a flat second half of 2026.
- The base case takes 60%. Evidence that would move the weights: customers trimming orders or rising inventory in the third-quarter results (worst case up); guidance raised again with margins above 30% in Interconnect (best case up).
What the price implies. Holding the base case at its 60% weight, the price is matched by the weighting that solves
best weight × $163.70 + 60% × $120.78 + (40% − best weight) × $65.37 = $121.62
which gives a best-case weight of ($121.62 − $72.47 − $26.15) ÷ ($163.70 − $65.37) = 23%, and so 17% on the worst case, close to the best guess.
The asymmetry on the best guess:
| Measure | At $121.62 | What it means |
|---|---|---|
| Expected return (header chip) | +1% | The probability-weighted value, $123.20, against the price |
| Gain to loss (header chip) | 1.2 to 1 | +$10.52 of probability-weighted gain against −$8.94 of loss |
| Best-case gain ÷ worst-case loss | 0.75 to 1 | +$42.08 against −$56.25 |
| Base case against the price | −$0.84 | The base case is slightly below the price, so it adds to the expected loss |
How the measures are calculated. Gain = case value − price; loss = price − case value. Weights are the best guess: 25% best, 60% base, 15% worst.
| Measure | Formula | At $121.62 |
|---|---|---|
| Expected return | (25% × best + 60% × base + 15% × worst) ÷ price − 1 | ($40.93 + $72.47 + $9.81) ÷ $121.62 − 1 = +1% |
| Gain to loss | (25% × best gain) ÷ (60% × base loss + 15% × worst loss) | $10.52 ÷ ($0.50 + $8.44) = 1.2 |
| Best ÷ worst | best gain ÷ worst loss | $42.08 ÷ $56.25 = 0.75 |
| Price-implied best weight | (price − base weight × base − (1 − base weight) × worst) ÷ (best − worst) | ($121.62 − $72.47 − $26.15) ÷ $98.33 = 23% |
The header chips are green at +25% or more and 3 to 1 or better, blue at +10–25% and 2–3 to 1, orange at 0–10% and 1–2 to 1, and red below zero and below 1 to 1. On the best guess, expected return is green below $98.56, blue up to $112.00 and orange up to $123.20; gain to loss is green below $109.85, blue up to $115.66 and orange up to $123.20. Both are red above $123.20.
Short interest and volatility
The tables below show how much of the stock is sold short and how much the price moves. They are inputs to the weights above, and the tables update with the nightly data.
| Report | Settled | Short | % float | % outst. | Days to cover |
|---|---|---|---|---|---|
| First after the spin | Nov 14, 2025 | 2.45M | 1.2% | 1.2% | 1.0 |
| Three months earlier | Jul 15, 2026 | 4.40M | 2.1% | 2.1% | 2.4 |
| Latest | Oct 30, 2026 | 4.31M | 2.1% | 2.1% | 2.2 |
The latest share of float is higher than 16 of the 23 earlier reports since the spin. Short interest in shares, with its share of the float and of shares outstanding. FINRA settlement dates; figures are published about eight business days later. Days to cover is short interest divided by average daily volume, as reported by FINRA. Float and shares outstanding on or before each date, from this site's daily share records and the company's filings.
Short interest is low and steady, at 2.2% of the float on September 30, 2026, about where it has been since June; days to cover rose to 3.0 as trading volume fell. It is too small to weigh on the stock or to change the weights.
| Volatility, annualized | Last 20 sessions | Last 60 sessions | Since the spin |
|---|---|---|---|
| To November 13, 2026 | 69% | 49% | 56% |
At the last 60 sessions' volatility, one standard deviation over a month is about ±15%, or $102.60 to $136.54 from the $118.36 close; about two months in three end inside that range if volatility holds. The median daily move since the spin is 2.5%.
| Results day | Released | Close before | Close after | Move | Times a median day |
|---|---|---|---|---|---|
| November 6, 2025 | After the close | $93.33 | $92.31 | -1.1% | 0.4× |
| February 26, 2026 | Before the open | $119.86 | $124.78 | +4.1% | 1.7× |
| May 12, 2026 | Before the open | $153.24 | $168.36 | +9.9% | 4.0× |
| August 4, 2026 | Before the open | $133.30 | $141.67 | +6.3% | 2.5× |
| November 4, 2026 | Before the open | $118.89 | $118.78 | -0.1% | 0.0× |
Average move on a results day: 4.3% either way, against a median day's 2.5%. The move is measured from the close before the release to the close of the first session after it.
Qnity moves a lot, and results days have moved it more: the three full-quarter releases gave +4.1% (the first guidance), +9.9% and +6.3% (each with guidance raised), against a median day’s 2.5%. Volatility has eased to 28% over the last 20 sessions from 55% since the spin. The November 4, 2026 results are the first with the new chief financial officer and the first chance to hear about 2027, which management declined to discuss in August.
Notes on earlier sections
A further PFAS claim, omitted on October 9, 2026. That update said Qnity’s liability beyond the $253 million recorded “cannot be reasonably estimated”. It did not mention that on August 6, 2026 California asked the federal court handling firefighting-foam cases to add Qnity as a defendant, alleging that DuPont’s transfers to Qnity were fraudulent and asking the court to unwind them or hold the proceeds in trust. No ruling has been found. If the claim succeeded, Qnity could be liable directly, beyond its 44% share through DuPont. On October 1, 2026, 16 state attorneys general brought the same kind of claim against Corteva’s spinoff of Vylor; Qnity is not named in it. The 10-Q, filed before the California filing, puts reasonably possible losses beyond the amount recorded at up to about $100 million more. An omission, not a change in the business.
What it means for the rating
HOLD, target $118 → $123. The target is the best-guess value, $123.20, which differs from October 9, 2026 only through the weights. Both chips are orange at $121.62: the expected return is about 1% and the gain to loss about 1.2 to 1, and the price implies almost the weights the evidence supports. The stock is fairly priced, and the case for buying rests on a lower price.
| Action | Level | Reason |
|---|---|---|
| Accumulate | Below about $110 | Gain to loss reaches 3 to 1 and expected return 12% |
| Hold | $110–134 | |
| Trim | Above $134 | The base case at an 18× exit multiple |
| Move to ACCUMULATE | Third-quarter growth above 15% with guidance raised and customers’ inventory still low | |
| Move to SELL | Guidance cut on weaker orders, customers’ inventory rising, or a ruling that makes Qnity directly liable for PFAS costs |
The table of what the third-quarter results must show, in the October 9, 2026 update below, stands, with two additions: any comment on 2027 and on customers’ inventory, and any development in the California PFAS case.
Update — October 9, 2026: scenarios, trading and the DuPont liabilities — HOLD, target $132 → $118
Written against the October 8, 2026 close of $126.68; peer comparisons run to the October 9, 2026 close. Sources: Qnity’s FY2025 10-K, Q2 2026 10-Q and its 8-Ks of August 21, 2026 and September 10, 2026; management’s remarks at Goldman Sachs’ Communacopia conference on September 10, 2026 (summary); S&P Dow Jones Indices’ October 27, 2025 announcement and Qnity’s PHLX Semiconductor Index release; FINRA short-interest and off-exchange data; the SEC’s Form 13F data sets; funds' Forms N-PORT and SPDR’s daily holdings files; and closing prices for the stock and its peers. Forecasts and scenario values are estimates. The August 24–26, 2026 analysis below is left as published; this section adds what it left out, replaces its valuation with a scenario build, and corrects two points.
The one-line version
Built line by line, Qnity is worth $121 a share in the base case, $164 in the best case and $65 in the worst, which repeats the 2023 destocking; weighted, $118, below the $126.68 price. The downside is larger than the upside, and the price implies about a one-in-eleven chance of another destocking year. The target falls from $132 to $118 and the rating stays HOLD, with accumulation below $107.
Since the August 2026 analysis the stock is unchanged while semiconductor stocks rose 9%: it fell with them on September 14–15, 2026 and recovered less. Qnity carries 44% of DuPont’s legacy liabilities, including PFAS, with $253 million recorded and further amounts that cannot yet be estimated; the August 2026 analysis did not mention them. No insider, index or block trade explains the trading, and Qnity, unlike most spinoffs, had no forced selling at the spin because it went straight into the S&P 500.
What happened since August 26, 2026
| Date | Event | Read |
|---|---|---|
| Aug 21, 2026 | Ken Rizvi named chief financial officer, from Synaptics, effective October 1, 2026, with a $10 million equity award replacing forfeited grants. Interim CFO Michael Goss returns to controller | Ends an interim arrangement |
| Aug 26, 2026 | Deutsche Bank technology conference (chief executive Jon Kemp) | No transcript available |
| Aug 25, 2026, Aug 31, 2026 | Product launches in advanced packaging, including a CMP slurry platform | Routine |
| Sep 10, 2026 | Goldman Sachs conference (below). Same day, an 8-K on the North Carolina PFAS settlement: Qnity’s $43 million share was already accrued in the second quarter | No new charge |
| Sep 14, 2026 | Chip stocks fall 5–6% on an essay by AI executives calling for slower frontier development and a 10-year Treasury yield at 5%; Qnity −7.3% | Sector |
| Sep 16, 2026 | The Federal Reserve raises rates by a quarter point, its first increase since 2023 | Sector |
| Sep 18–21, 2026 | Added to the PHLX Semiconductor Index (SOX), effective September 21, 2026; 3.9 million shares traded at the September 18, 2026 close | Index buying, estimated at $40–180 million |
| Oct 1, 2026 | Mizuho cuts its target from $180 to $160, Outperform, citing Chinese exports and higher rates. Third-quarter results set for November 4, 2026 | Moderate |
| Oct 5–7, 2026 | Zacks Research lowers its rating to Hold | Minor |
Analysts’ average target is about $150, with eight buy and two hold ratings. No broker changed its rating in the period. Qnity filed no buyback 8-K.
What management said
At Goldman Sachs on September 10, 2026, the chief executive:
- On demand, said AI and advanced-node demand would last through 2027–28, and that Qnity had raised its forecast for 2026 industry wafer starts from mid to high single digits. Advanced-node products are about 40% of Semiconductor Technologies sales, growing 20%, and ahead of the 45–50% target for 2030.
- On Interconnect, said about 30% of the segment (advanced packaging, thermal materials and AI circuit boards) was growing more than 50% a year and had been the fastest-growing part of the company for two years.
- On price, described value pricing on new leading-edge products and “some price fade in older technologies”, consistent with the 1–2% annual price declines in the filings.
- On margins, gave a company gross margin of 47%, about 50% in Semiconductor Technologies, with a target above 50% helped by a $100 million cost program.
- On capital, ranked organic investment first and tuck-in acquisitions in packaging, thermal and consumables second, and ruled out transformational acquisitions. Buybacks, the dividend, free cash flow and PFAS were not discussed.
Guidance was not changed: adjusted EPS of $4.40–4.60 for 2026, adjusted EBITDA of about $1.7 billion and free cash flow of $600–700 million.
Revenue by segment
| $ millions | 2022 | 2023 | 2024 | 2025 | H1 2025 | H1 2026 | Change |
|---|---|---|---|---|---|---|---|
| Semiconductor Technologies | 2,615 | 2,251 | 2,450 | 2,642 | 1,288 | 1,466 | +14% |
| Interconnect Solutions | 2,140 | 1,784 | 1,885 | 2,112 | 1,000 | 1,278 | +28% |
| Total | 4,755 | 4,035 | 4,335 | 4,754 | 2,288 | 2,744 | +20% |
The growth is volume. In the second quarter, volume added 23 points, price and mix subtracted 1, and currency added nothing; Semiconductor Technologies’ prices fell 1% and Interconnect’s were flat. China was 33% of second-quarter sales, $478 million, of which $283 million was Interconnect.
The guidance implies the second half grows about 16%, against 20% in the first: revenue of about $5.6 billion means $2.86 billion in the second half against $2.47 billion a year earlier.
Three scenarios
Each segment grows on its own volume, less an annual price decline; segment margins move from their second-quarter levels (Semiconductor Technologies 34.0%, Interconnect 28.8%) to a 2030 level and then hold; corporate costs are about 1% of sales. 2026 is anchored to guidance. Below EBITDA: interest of $244 million a year, a 22% tax rate on adjusted earnings, about $46 million to minority partners, amortization of acquired intangibles on the 10-K schedule ($199 million in 2026 falling to $89 million in 2030), and capital spending plus working capital easing from 9.5% to 6.5% of sales, as in the August 2026 model.
| Driver | Best | Base | Worst | Evidence |
|---|---|---|---|---|
| Semiconductor Technologies volume, 2027 → 2033 | 15% → 7% | 12% → 6% | −12% in 2027, then 5–8% | +14% in H1 2026; −14% in 2023 |
| Interconnect volume, 2027 → 2033 | 24% → 7% | 18% → 6.5% | −16% in 2027, then 5–9% | +28% in H1 2026; −17% in 2023 |
| Price, a year | −1% | −1.5% | −2% | −1% to −2% in 2024–25 |
| Semiconductor Technologies margin by 2030 | 37% | 34.5% | 33% | 39.2% in 2022, 35.8% in 2025 |
| Interconnect margin by 2030 | 31% | 29% | 27% | 21.7% in 2022, 25.5% in 2025 |
| Downturn | none | none | 2027, at 1.7 times the revenue decline in EBITDA | 2023: revenue −15%, EBITDA −26% |
| $ millions | 2025 | 2026E | 2027E | 2028E | 2029E | 2030E |
|---|---|---|---|---|---|---|
| Base — Semiconductor Technologies | 2,642 | 3,010 | 3,326 | 3,608 | 3,879 | 4,131 |
| Interconnect Solutions | 2,112 | 2,635 | 3,069 | 3,422 | 3,713 | 3,992 |
| Net sales | 4,754 | 5,644 | 6,395 | 7,031 | 7,592 | 8,123 |
| Adjusted EBITDA | 1,441 | 1,700 | 1,950 | 2,148 | 2,325 | 2,493 |
| EBITDA margin | 30.3% | 30.1% | 30.5% | 30.5% | 30.6% | 30.7% |
| Adjusted EPS | $4.47 | $5.44 | $5.95 | $6.37 | $6.82 | |
| GAAP EPS | $3.74 | $4.81 | $5.42 | $5.97 | $6.49 | |
| Free cash flow | 601 | 802 | 939 | 1,073 | 1,208 | |
| Best — net sales | 5,801 | 6,858 | 7,849 | 8,751 | 9,583 | |
| Adjusted EBITDA (margin) | 1,740 | 2,134 | 2,488 | 2,828 | 3,158 (33.0%) | |
| Adjusted EPS | $4.62 | $6.02 | $7.05 | $8.00 | $8.98 | |
| Free cash flow | 615 | 907 | 1,141 | 1,381 | 1,626 | |
| Worst — net sales | 5,523 | 4,647 | 4,833 | 5,145 | 5,402 | |
| Adjusted EBITDA (margin) | 1,660 | 1,212 | 1,438 | 1,513 | 1,570 (29.1%) | |
| Adjusted EPS | $4.32 | $3.06 | $3.77 | $3.86 | $3.95 | |
| Free cash flow | 583 | 348 | 533 | 592 | 645 |
The base case keeps the company margin near 30.5%, close to its level across the cycle (31.3% in 2022 and 31.2% in 2025 on segment EBITDA), because Interconnect’s gains are offset by its growing weight and by price declines. Its 2026 adjusted EPS of $4.47 sits inside the guided $4.40–4.60. Free cash flow converts about 35–48% of EBITDA through 2030, lower than most materials companies, because the capacity program and interest absorb most of the difference; cumulative free cash flow from 2027 to 2032 of about $6.8 billion covers the $4.0 billion of debt due in 2032–33.
The valuation, by scenario
The method of the August 2026 analysis, unchanged: free cash flow before interest from 2027 to 2033, discounted at 11%, with a terminal value at 16 times 2033 EBITDA, less net debt of $3,059 million and, new in this bridge, the $253 million of recorded indemnification liabilities to DuPont, treated as debt (see below). Rebuilt with the August 2026 assumptions, the model gives $128 against the $130 published, so the change below comes from the assumptions.
| Scenario | Per share | vs $126.68 | Weight |
|---|---|---|---|
| Best | $164 | +29% | 25% |
| Base | $121 | −5% | 50% |
| Worst | $65 | −48% | 25% |
| Probability-weighted | $118 (117.66) | −7% |
| 10% | 11% | 12% | |
|---|---|---|---|
| Best / base / worst | $174 / $129 / $70 | $164 / $121 / $65 | $154 / $113 / $61 |
| Weighted | $126 | $118 | $110 |
| Exit multiple | 14× | 16× | 18× |
|---|---|---|---|
| Base | $107 | $121 | $134 |
| Weighted | $105 | $118 | $131 |
The base case sits below the August 2026 target of $132 because it charges the annual price declines in the filings, which the August 2026 model’s flat margin did not separate, and because its growth path is slightly slower in 2028–29.
The 25 / 50 / 25 weights are a judgement, and the value moves with them:
| Weights, best / base / worst | Value per share |
|---|---|
| 30 / 50 / 20 | $123 |
| 25 / 50 / 25 (the target) | $118 |
| 20 / 60 / 20 | $118 |
| 15 / 70 / 15 | $119 |
| 10 / 80 / 10 | $120 |
| 20 / 50 / 30 | $113 |
What the best case requires: Interconnect volume growing 24% in 2027 and above 10% through 2029, Semiconductor Technologies growing 15% in 2027, prices falling only 1% a year, and segment margins reaching 37% and 31% by 2030. Semiconductor Technologies’ 37% is below its 2022 level of 39.2% but above any year since; Interconnect’s 31% would be its highest on record. Management’s description of the AI demand outlook supports the volume; the margins need the cost program and pricing on new products to work.
What the worst case requires: a repeat of 2023, when customers stopped ordering for four quarters and revenue fell 15% and EBITDA 26%. The model places it in 2027, with prices falling 2% a year and margins settling below their 2025 levels. A pause in AI data-centre spending, Chinese export controls or a destocking after a year of strong orders would each be enough.
Which assumption matters most, one at a time in the base case:
| Change | Per share | Change |
|---|---|---|
| Exit multiple 18×, not 16× | $134 | +$13 |
| Exit multiple 14× | $107 | −$13 |
| Semiconductor Technologies volume 3 points higher to 2030 | $129 | +$8 |
| Price −0.5% a year, not −1.5% | $129 | +$8 |
| Price −2.5% a year | $113 | −$8 |
| Margins 1.5 points higher by 2030 | $128 | +$7 |
| Interconnect volume 3 points higher to 2030 | $127 | +$7 |
| Capital spending and working capital 1 point of sales lower | $123 | +$2 |
The exit multiple is the largest input, which ties the value to how the market prices semiconductor materials in 2033 as much as to the business; among the operating assumptions, pricing and Semiconductor Technologies’ volume matter as much as the faster-growing Interconnect.
The asymmetry is unfavourable at this price. The best case is $37 above it and the worst $61 below; the ratio of best-case gain to worst-case loss is 0.6, and the probability-weighted ratio of expected gain to expected loss is 0.5. With the best case at 25%, the price implies about a 9% chance of the downturn case, for a business whose last downturn was in 2023.
The DuPont indemnity and PFAS
Under the separation agreements Qnity pays 44% of DuPont’s share of certain legacy liabilities: its funding of the 2021 PFAS cost-sharing agreement with Chemours and Corteva, other legacy PFAS liabilities, and the liabilities of businesses DuPont discontinued or sold. The 44% is Qnity’s share of DuPont’s EBITDA at the time of the spin.
- Recorded: $253 million at June 30, 2026 ($99 million current, $154 million non-current), including $88 million for future spending under the cost-sharing agreement and $43 million for the North Carolina settlement of September 10, 2026.
- Further, under the cost-sharing agreement: DuPont’s share of the $4 billion cap is about $1.4 billion, of which it had spent about $745 million and accrued $217 million. Qnity’s 44% of the remainder, after tax, is an estimated $150 million not yet recorded.
- Beyond the agreement: the 10-Q states that further losses “cannot be reasonably estimated” and may be material.
The valuation above deducts the $253 million recorded. The $150 million estimate is about $0.70 a share; the unbounded part is a risk carried in the worst case rather than in a number.
Interest rates
Of $4.1 billion of debt, the $2.35 billion term loan floats at SOFR plus 1.75% and the $1.75 billion of notes are fixed at 5.75% and 6.25%. Qnity’s own disclosure: a one-point change in rates moves annual interest by $24 million, about $0.09 a share after tax. The cost of capital matters far more, at about $8 a share for each point, as the table above shows; the 11% used here already sits well above the yield on Qnity’s own unsecured notes.
The valuation at a glance
At $126.68: market capitalization $26.5 billion on 209.2 million shares, net debt $3.06 billion and recorded DuPont indemnity $0.25 billion, enterprise value $29.8 billion.
| Measure | Basis | Multiple |
|---|---|---|
| EV / adjusted EBITDA | 2026 guidance (~$1.70B) | 17.5× |
| 2027 base case ($1.95B) | 15.3× | |
| Price / adjusted EPS | 2026 guidance midpoint ($4.51) | 28.1× |
| 2027 base case ($5.44) | 23.3× | |
| Free cash flow yield | 2026 guidance midpoint ($650M) | 2.5% |
| 2027 base case ($802M) | 3.0% | |
| Dividend yield | $0.32 a year | 0.25% |
Who has been trading
| Aug 26 – Sep 11, 2026 | Sep 11 – Sep 15, 2026 | Sep 15 – Oct 6, 2026 | Oct 6 – Oct 9, 2026 | |
|---|---|---|---|---|
| Qnity | +0.2% | −9.3% | +16.6% | −5.5% |
| Semiconductor materials (Entegris, MKS, Element Solutions) | −2.6% | −9.5% | +23.0% | −3.9% |
| Semiconductor equipment (Applied Materials, Lam Research, KLA) | −3.8% | −8.0% | +22.2% | −3.0% |
| iShares Semiconductor ETF | +2.3% | −5.4% | +18.2% | −5.0% |
| DuPont | −8.0% | +0.8% | +4.1% | −2.3% |
| S&P 500 | −0.2% | −0.9% | +2.9% | −0.1% |
Closing prices rebased to August 26 = 100. Baskets are equal-weighted: semiconductor materials (Entegris, MKS, Element Solutions); semiconductor equipment (Applied Materials, Lam Research, KLA); the iShares Semiconductor ETF (SOXX); DuPont, the former parent; and the S&P 500 through SPY. Source: Yahoo Finance closes.
Qnity moves with the semiconductor materials companies (a daily correlation of 0.85 since the end of July 2026) and the semiconductor ETF (0.81), and little with DuPont (0.26). From August 26 to October 9, 2026 it was unchanged while the materials group rose 4.4% and the ETF 8.7%. The shortfall came in the recovery: Qnity fell as far as its peers on September 14 and 15, 2026 and then rose 16.6% to their 22–23%. Since the spin it is up 30% against 65% for the materials group and 82% for the ETF. Mizuho’s target cut on China and the absence of any new information at the September 2026 conference are the only company-specific items in the period; the rest is sector movement.
Daily volume (bars) and cumulative volume as a share of the 209.2 million shares outstanding (line). Gold bars mark days with a notable event; hover over one to see what happened. Source: this site's daily price archive (Yahoo Finance), through Oct 8, 2026.
| Average daily volume | Share of the company traded | Close | |
|---|---|---|---|
| November 2025 | 3.8M | 34.4% | $81.09 |
| December 2025 | 2.0M | 21.0% | $81.65 |
| January 2026 | 2.4M | 22.8% | $96.18 |
| February 2026 | 3.0M | 27.2% | $126.76 |
| March 2026 | 2.2M | 22.7% | $115.38 |
| April 2026 | 1.5M | 15.3% | $140.66 |
| May 2026 | 2.0M | 18.7% | $156.00 |
| June 2026 | 2.2M | 22.1% | $163.31 |
| July 2026 | 1.9M | 20.2% | $131.18 |
| August 2026 | 1.8M | 17.6% | $119.43 |
| September 2026 | 1.6M | 16.1% | $125.74 |
| October 2026 to the 8th | 1.4M | 3.9% | $126.68 |
| Since the spin | 242.1% |
Qnity had almost no forced selling at the spin. S&P Dow Jones Indices added it to the S&P 500 on its first day, so S&P 500 index funds kept the shares they received, and only 11.4% of the company traded in the first three sessions. The one forced trade at the spin was between sector funds: S&P classified Qnity as information technology while DuPont was a materials company, so materials funds sold and technology funds bought. Since then the only index event has been the PHLX Semiconductor Index addition at the September 18, 2026 close, when 3.9 million shares traded, 85% of them on the exchanges rather than off-exchange, the pattern of closing-auction index buying. No S&P, MSCI or FTSE change has involved it, and the largest semiconductor ETFs (SOXX, SMH, XSD) do not hold it.
Insiders have traded little. Directors bought small amounts after the spin (Anne Noonan 3,240 shares at $77.30, Byron Green 1,000 at $79.12) and in August 2026 (Karin de Bondt 1,000 at $138.14). The chief executive and the controller exercised options in December 2025 and sold the resulting shares at about $85, and one director sold 911 shares in May and June 2026 to pay tax on vested awards. No officer or director has a trading plan.
The company has bought back little. Of the $500 million authorized in February 2026, $50 million has been spent: 219,581 shares in March 2026 at $113.78, 133,602 in April 2026 at $131.59, 49,505 in May 2026 at $149.78, and none in June 2026.
Short interest has risen gradually, from about 2.5–3.4 million shares in the first months to 4.5 million (2.1%) on September 15, 2026, with about 2.6 days of volume. The September 30, 2026 figure has not yet been published.
Holders. DuPont’s holders received one Qnity share for every two DuPont shares. Their entitlements, estimated from DuPont 13F positions at September 30, 2025, against their Qnity positions since:
| Holder | Shares received (estimated) | Dec 31, 2025 | June 30, 2026 | Change since the spin |
|---|---|---|---|---|
| Vanguard | 25.4M | 27.3M | 26.1M | Increased, +3% |
| BlackRock | 15.9M | 15.9M | 16.1M | Increased, +1% |
| State Street | 9.1M | 8.9M | 9.4M | Increased, +3% |
| Geode | 5.5M | 5.4M | 5.6M | Increased, +2% |
| Nuveen | 4.5M | 2.4M | 1.3M | Decreased, −72% |
| Invesco | 4.4M | 4.7M | 4.1M | Decreased, −8% |
| Franklin | 3.6M | 3.5M | 0.2M | Decreased, −95% |
| D. E. Shaw | 3.3M | 3.6M | 0.2M | Decreased, −95% |
| JPMorgan | 3.1M | 0.7M | not disclosed | Decreased, −77% by December 31, 2025 |
| Goldman Sachs | 2.9M | 1.1M | 2.1M | Decreased, −28% (sold, then partly rebought) |
| T. Rowe Price | 2.4M | 2.7M | 1.6M | Decreased, −33% |
Index funds kept their shares, which is the S&P 500 placement at work. The active selling came in two rounds. JPMorgan, Goldman Sachs and Nuveen sold most of their entitlements in the first two months, and Franklin and D. E. Shaw sold out in the first half of 2026, along with hedge funds that had bought at the spin (Southpoint, Slate Path). The buyers were Durable Capital (4.6 million shares at June 30, 2026), Allspring (4.4 million), Jane Street, PointState, Two Sigma, Amundi and Sixth Street. The third-quarter Forms 13F, due by about November 16, 2026, will show who sold in September 2026.
Notes on the August 24–26, 2026 analysis
- The DuPont indemnity was not mentioned. The August 2026 analysis covered the debt, goodwill and the cash paid to DuPont but not the 44% share of DuPont’s legacy liabilities, including PFAS, with $253 million recorded at June 30, 2026. It is now deducted in the valuation and described above. This is an omission corrected, not a change in the business.
- The August 26, 2026 close was $126.20, not $125.50. The multiples and the reverse discounted cash flow in that analysis were struck at $125.50; at $126.20 they move by about half a percent and no conclusion changes. This is a data correction.
October 2026 recommendation
Rating: HOLD, maintained. Target: $132 → $118. Grade: unchanged.
What changed. The business did not: guidance stands, management’s demand outlook is firm, and the second quarter grew 22% on volume. The target falls because the scenario build charges the annual price declines the filings show, deducts the recorded DuPont indemnity, and weighs a 2023-style downturn at 25%, which the August 2026 target did not.
Why HOLD rather than SELL.
- The base case is close to the price, at $121 against $126.68, and the business is growing faster than any year in its record.
- The balance sheet carries a downturn. Nothing matures before 2032, the revolver is undrawn, and base-case free cash flow covers the 2032–33 maturities.
- The best case is credible: management’s description of AI and advanced-node demand supports the volumes in it.
Why HOLD rather than ACCUMULATE.
- The weighted value is below the price and the downside is larger than the upside: $61 a share to the worst case against $37 to the best.
- The price implies little risk of a downturn, about a 9% chance, in a business whose last downturn cut EBITDA by a quarter.
- The DuPont indemnity is open-ended beyond what is recorded.
Action for October 2026:
| Accumulate below $107 | Where expected gain is twice expected loss on the three scenarios |
| Hold between $107 and $134 | |
| Trim above $134 | The base case at an 18× exit multiple |
| Move to ACCUMULATE | Third-quarter organic growth above 15% with guidance raised, or Interconnect margin above 30%, at a price below about $120 |
| Move to SELL | Guidance cut on weaker orders, China export restrictions on Qnity’s products, or a material PFAS charge beyond the recorded amounts |
What to watch in the third-quarter results (November 4, 2026):
| Line | The test |
|---|---|
| Organic growth | About 16% for the second half, as guidance implies; the split between volume and price |
| Interconnect margin | Holding near 29% or rising |
| Semiconductor Technologies margin | Stabilizing near 34% as Delaware capacity ramps |
| Free cash flow | On track for $600–700 million, which needs about three-quarters of it in the second half |
| China | The share of sales, and any comment on export controls after China’s suspension expires on November 10, 2026 |
| DuPont indemnity | Any change to the $253 million recorded |
| Capital return | Buybacks resumed or not, under the new chief financial officer |
Post-Spin Analysis — August 24, 2026
Written against the August 26 close of $125.50. Primary sources: the FY2025 10-K (filed 2026-02-26) and the Q2 2026 10-Q (filed 2026-08-04), supported by the Q2 results release. Share count and float per the Q2 10-Q and market data.
Customer concentration, the price-versus-volume split, segment economics and the debt structure are taken directly from the filings. One figure — the share of revenue that is AI-linked — is not disclosed anywhere and is flagged where it matters.
The one-line version
The stock is down 29% from its June high while management raised full-year EPS guidance 20%. Every dollar of that decline is multiple compression, and the business is growing 22% on volume, not price.
“Volume, not price” is the whole thesis, and it cuts both ways. Qnity’s own disclosure shows realised price falling 1–2% a year in both segments, in 2024 and 2025 — the two strongest years the semiconductor industry has ever had. It sits in the layer of the AI value chain with the least pricing power: qualification protects the socket, but the customer sets the price. When the buildout normalizes, that is the layer that gives back the most multiple.
A reverse DCF says the market is paying for 8.0% long-run revenue growth and a flat 30.2% margin. The four-year record suggests flat is right — segment margin was 31.3% in 2022 and 31.2% in 2025, having recovered a 2023 destocking in which revenue fell 15% and EBITDA fell 26%. Interconnect gained 3.8 points over that span; Semiconductor Technologies lost 3.4.
The question is not whether Qnity is a good business — the filings settle that it is. It is whether the AI acceleration is a cycle or a step-change, and you are being asked to pay a fair price for the answer. Rating HOLD, target $132, accumulate below ~$115.
The filings add one thing that cuts hard the other way: China is 33% of net sales, and 41% of the fast-growing Interconnect segment. That is the single largest risk on this page and it is not in the price discussion at all.
What the business actually is
DuPont’s electronics arm, separated November 3, 2025 and added to the S&P 500 immediately. It sells consumable materials into chip fabrication and into what goes around the chip. Two segments, and the distinction matters more than it first appears:
| Segment | Q2'26 sales | Organic | Segment EBITDA | Margin | What it sells |
|---|---|---|---|---|---|
| Semiconductor Technologies | $744M | +16% | $253M | 34.0% | CMP pads and slurries, photoresists, functional sub-layers, advanced overcoats, post-CMP cleaners, post-etch residue removers |
| Interconnect Solutions | $685M | +28% | $197M | 28.8% | Advanced packaging materials, PCB laminates, thermal management, electronic interconnects |
| Total | $1,429M | +22% | $431M | 30.2% |
Read the margin column against the growth column. The faster-growing segment is the lower-margin one, by 5.2 percentage points, so mix is a drag on the blended margin.
But the 10-K complicates the obvious conclusion. Interconnect’s margin is closing the gap fast:
Interconnect Solutions adj. operating EBITDA margin FY2023 $333M on $1,784M = 18.7% FY2024 $448M on $1,885M = 23.8% FY2025 $539M on $2,112M = 25.5% Q2 2026 $197M on $685M = 28.8% Meanwhile Semiconductor Technologies is going the other way — 35.8% for FY2025 against 34.0% in Q2 2026, as growth investment in R&D and supply chain lands. The segment gap has narrowed from 10.3pp to 5.2pp in eighteen months. Mix is still a drag, but a shrinking one, and if Interconnect keeps converging the drag disappears entirely.
FY2025 for scale: $4,754M of revenue, +9.7% — Semiconductor Technologies $2,642M (adj. EBITDA $945M, 35.8%), Interconnect Solutions $2,112M ($539M, 25.5%). R&D was $354M, or 7.4% of sales.
Management Team
| Role | Name | Background |
|---|---|---|
| CEO | Jon Kemp (50) | Ran this business inside DuPont — President of the Electronics & Industrial segment since August 2019, and President of DuPont Electronics & Communications 2015–2017. On the SEMI board of directors since 2016. An economist by training, with a Darden MBA |
| CFO (from Oct 1, 2026) | Ken Rizvi (new) | Appointed August 21, 2026. Most recently CFO of Synaptics; before that CFO of Smart Global Holdings (now Penguin Solutions), UTAC Group (assembly and test), and Isola Group — a direct competitor in PCB laminates. Earlier, finance roles at Micron and ON Semiconductor |
| Interim CFO to Oct 1 | Michael Goss (50) | Qnity’s controller and principal accounting officer; 14 years at DuPont as VP and Controller. Returns to VP Finance and Controllership when Rizvi starts |
| President, Interconnect Solutions | Chuck Xu (61) | Ran the Interconnect business group inside DuPont from August 2023, and DuPont E&I strategy and M&A from February 2021 |
| General Counsel | Peter Hennessey (48) | DuPont associate general counsel and corporate secretary from 2019; before that a partner at Ballard Spahr |
| Chief People Officer | Kathleen Fortebuono (55) | DuPont VP Global Rewards and Talent from 2019; earlier Chemours, eBay |
The CFO seat has been the unstable one, and it has just been filled well. Qnity separated in November 2025, lost or never appointed a permanent CFO, ran on an interim CFO from January 2026, and only named a permanent one on August 21, 2026 — nine months in. For a company carrying $4.0B of new debt, guiding to a back-end-weighted free-cash-flow year and integrating standalone systems, that is a long time to run finance on an interim basis, and it belongs in any assessment of execution risk in the first year.
The appointment itself is a good one, and specifically so. Rizvi’s career is almost entirely inside the semiconductor supply chain — memory (Micron), analogue (ON), assembly and test (UTAC), systems (Smart Global) and most recently a listed chip company (Synaptics). He also ran finance at Isola Group, which competes directly with Qnity’s laminates business. That is an unusually precise fit for a company whose two segments sit at exactly those two points in the chain. He starts October 1, so the Q3 print will still be Goss’s.
A note on timing. The Rizvi appointment was announced on August 21, 2026 — the same day as the closing price this analysis was originally written against. It is new information relative to the first version of this page, and it is the reason the Management score below moves up rather than down despite nine months of interim finance leadership.
The board
Nine directors, and the composition is notably outward-facing for a spinoff — this is not a DuPont board with a new name on it:
- Terrence R. Curtin (57) — CEO of TE Connectivity, a $16B connectivity and sensors business. A sitting large-cap CEO in an adjacent industry, on Audit.
- Mark A. Blinn (64) — CEO of Flowserve 2009–2017 and its CFO before that; chairs Nomination and Governance; three other public boards.
- Steven M. Sterin (54) — chairs Audit; former public-company CFO and McKinsey senior adviser.
- Karin De Bondt (56) — SVP and Chief Strategy Officer of Trane Technologies.
- Byron Green (62) — former VP Global Operations, L3Harris.
- Plus a former President and Chief Strategy Officer of Samsung — relevant, given Samsung is Qnity’s largest customer at ~11% of sales.
Three former or current CFOs, a sitting large-cap CEO, and someone from the largest customer’s senior ranks. With no director drawn from DuPont’s board or executive ranks, this is a genuinely independent board, and none of the former-parent entanglement that complicates some separations applies here.
The one alignment gap is real and unchanged: insider ownership is roughly 0.1%. Management runs this business on salary and grants, not on a stake.
The financial record — four years, and one correction
Qnity’s own 10-K shows three years. The Form 10 information statement shows 2022, and it changes the picture materially, because 2022 was a peak and 2023 was a severe downturn that no post-spin filing puts in front of you.
| ($M) | 2022 | 2023 | 2024 | 2025 | 2026E (guide) |
|---|---|---|---|---|---|
| Net sales | 4,755 | 4,035 | 4,335 | 4,754 | ~5,600 |
| YoY | −15% | +7% | +10% | +18% | |
| Gross margin | 45.4% | 43.5% | 46.0% | 46.2% | — |
| Segment adjusted EBITDA | 1,488 | 1,110 | 1,332 | 1,484 | — |
| margin | 31.3% | 27.5% | 30.7% | 31.2% | — |
| Company adjusted EBITDA | n/d | 1,083 | 1,307 | 1,441 | ~1,700 |
Read the first and fourth columns. Net sales in 2025 were $4,754M against $4,755M in 2022. Segment adjusted EBITDA was $1,484M against $1,488M. Three years of “growth” precisely recovered a downturn and did nothing more.
By segment, and this is where the two businesses separate:
| ($M) | 2022 | 2023 | 2024 | 2025 |
|---|---|---|---|---|
| Semiconductor Technologies | 2,615 | 2,251 | 2,450 | 2,642 |
| adjusted EBITDA | 1,024 | 777 | 884 | 945 |
| margin | 39.2% | 34.5% | 36.1% | 35.8% |
| Interconnect Solutions | 2,140 | 1,784 | 1,885 | 2,112 |
| adjusted EBITDA | 464 | 333 | 448 | 539 |
| margin | 21.7% | 18.7% | 23.8% | 25.5% |
2022 figures are “Operating EBITDA” from the Form 10; 2023–25 are “Segment Adjusted Operating EBITDA” from the 10-K. The two agree exactly for 2023 (777 / 333). One figure was restated: 2024 Semiconductor Technologies is $874M in the Form 10 and $884M in the 10-K; we use the 10-K.
Correction: “ten points in three years” was wrong
An earlier version of this page said twice that Interconnect’s margin had risen ten points in three years, and used it in the price-target box as evidence that margin expansion was not in the price.
The filings do not support it. Interconnect’s margin went 21.7% (2022) → 25.5% (2025) — 3.8 points over three years. Measured from the 2023 trough it is 6.8 points. Neither is ten. The error came from anchoring on 2023 without checking what 2022 looked like, and 2023 was the bottom of a destocking cycle.
The underlying point survives, at about a third of the stated size. Interconnect’s margin is structurally higher than it was at the last peak, by 3.8 points, and that is a real improvement in the AI-levered segment.
The half of the record that is genuinely good, and the half that is not
Interconnect is a better business than it was in 2022 — 3.8 points of margin on 1.3% lower revenue, driven by mix into thermal management, advanced packaging and low-loss laminates. That is the segment nearest the AI build, and it is earning more per dollar of sales than at the last peak.
Semiconductor Technologies is a worse one. Margin 39.2% → 35.8%, down 3.4 points against a peak, on 1% more revenue. This is the larger segment — 56% of sales and 64% of segment profit — and its unit economics have not recovered to where they were. Nothing in the filings explains it as a one-off.
Net, at the company level, the margin is flat across the cycle: 31.3% in 2022 against 31.2% in 2025 on segment EBITDA. The mix improved; the average did not.
What 2023 tells you, and it is the most useful year on this page
2023 is the only stress test this business has on record as a standalone reporting entity, and it was severe:
| 2023 versus 2022 | Semiconductor Tech | Interconnect |
|---|---|---|
| Net sales | −14% | −17% |
| Adjusted EBITDA | −24% | −28% |
| Volume | −14% | −11% |
| Price and mix | +1% | −2% |
Revenue fell 15% at the company level and EBITDA fell 26% — about 1.7x downside operating leverage. The cause was ordinary: “inventory destocking and reduced semiconductor fabrication utilisation rates due to demand weakness, led by China.” Not a share loss, not a technology miss — customers simply stopped ordering for four quarters.
Hold that number. Any view of what Qnity is worth if the AI build normalizes has to start from the fact that the last time its customers destocked, EBITDA fell 26% in a single year.
Growth — is it accelerating, and how long can it run?
Yes, it is accelerating, and the acceleration is unusually well documented because the company has now revised its own guidance twice in three quarters.
| Revenue | Adj. EPS | Implied growth | |
|---|---|---|---|
| FY2026 guidance at the spin | $4.97–5.17B | $3.55–3.95 | +4.6% to +8.8% |
| FY2026 guidance now (Aug 4) | $5.55–5.65B | $4.40–4.60 | ≈ +18% |
| Investor-day long-term algorithm | — | — | 6–7% organic |
The company is running at roughly three times the growth rate it published for itself nine months ago. Guidance is up 10.5% on revenue and 20% on EPS since the spin.
The quarterly path confirms it is still building, not fading:
| Q1'26 | Q2'26 | |
|---|---|---|
| Total organic | +18% | +22% |
| Interconnect Solutions | +22% | +28% |
| Advanced packaging (within ICS) | — | >+50% |
It is volume, not price — and that is the best available answer
Revenue growth can come from content gains or from price, and the two are worth very different multiples. The 10-Q settles which this is, and the answer is as clean as it gets:
Q2 2026 net sales “up 22% … primarily due to a 23% increase in volume.” Semiconductor Technologies “increased due to an 18% increase in volume … partially offset by unfavorable local price and product mix and currency.” Interconnect Solutions “up 30% … primarily due to a 28% increase in volume and a 2% favorable currency impact.”
| Q2 2026 | Sales growth | of which volume | Price / mix |
|---|---|---|---|
| Semiconductor Technologies | +16% | +18% | negative |
| Interconnect Solutions | +30% | +28% | +2% currency |
| Total | +22% | +23% | slightly negative |
Volume growth exceeds revenue growth in both segments. Qnity is not raising prices — it is shipping more material and giving a little back on price and mix. That is the higher-quality version of this outcome: it is consistent with genuine content and share gains rather than pricing power being harvested, and it means the growth is not borrowing from future pricing.
The mechanism management describes is content per wafer, not wafer count — “shrink and stack.” As chips move from 2D scaling to 3D stacking and advanced packaging, the number of process steps using Qnity’s consumables rises even if unit volumes do not. The 10-Q attributes it to “AI driven applications, particularly in advanced nodes, including advanced packaging and high bandwidth memory” and, for Interconnect, “new content and share gains in advanced packaging, AI PCB and thermal management.”
This is a better growth mechanism than end-market volume, because it survives a flat semiconductor cycle.
The evidence that management believes it
Capacity is the tell, because it is expensive and hard to reverse:
- A 385,000 sq ft manufacturing facility opened in Delaware during Q1 2026.
- A new advanced production site in Taiwan, operational early 2027.
- Management on customer capex: customers have “put a lot of steel on the ground,” and “2027 is stacking up nicely.”
Building two plants into a cycle you expect to end is not a thing management teams do.
The one number that cuts the other way
Second-half guidance implies deceleration. Reconstructing from the reported quarters:
| 1H | 2H | FY | |
|---|---|---|---|
| 2025 (implied) | $2,286M | $2,464M | $4,750M |
| 2026 | $2,744M | $2,856M (guide) | $5,600M (mid) |
| Growth | +20.0% | +15.9% | +17.9% |
A first half at +20% guided to a second half at +15.9%. Two readings: management is being conservative having already raised twice, or the comparison base is genuinely hardening. The Q3 print settles it, and it is the single most informative event between now and year-end.
Where Qnity sits in the value chain — and how much power that gives it
This is the most important question on the page and the one the AI narrative obscures. Every layer of the semiconductor chain has re-rated on the AI buildout. When the buildout normalizes, the layers that keep their valuation will be the ones that can hold price. Qnity’s own filings say, unusually clearly, that it is not one of them.
What Qnity actually makes
Qnity sells consumables at two distinct points in making an electronic system. It sells no chips and no equipment.
| Where it is consumed | Product | What it does |
|---|---|---|
| Inside the wafer fab (Semiconductor Technologies, 56% of sales) | CMP slurries and pads (IC1000, Ikonic, Optiplane) | Chemical-mechanical planarization — polishing the wafer flat between each of the dozens of layers built on it. Consumed per wafer, repeatedly |
| Advanced cleans and etchants (PlasmaSolv, CuSolve, EtchSolv) | Removing photoresist and residue after CMP and etch | |
| Lithography and OLED materials | Patterning chemistry and display materials | |
| Inside the package and the board (Interconnect Solutions, 44%) | Plating and metallization (Circuposit, Microfill, Solderon) | Building the copper pathways in advanced packaging, substrates and PCBs |
| Dry film photoresist and dielectrics (Riston, Intervia) | Patterning those pathways | |
| Thermal and EMI materials (Laird — Tputty, Tflex, CoolZorb) | Moving heat out of a processor and shielding it | |
| Laminates (Pyralux, Interra) | The flexible and low-loss substrate a board is built on |
Everything on that list is bought by the piece, consumed in production, and reordered. Qnity’s revenue is a function of how many wafers its customers start and how many packages they build — not of how much those chips sell for.
The power map
Value in the AI chain accrues where supply is scarce. Ranked roughly by bargaining power:
| Layer | Source of power | Can it raise price? |
|---|---|---|
| Chip architecture and software (NVIDIA) | Ecosystem lock-in | Yes, decisively |
| EUV lithography (ASML) | Sole supplier | Yes |
| Leading-edge foundry (TSMC) | Effective monopoly at the leading node | Yes |
| HBM memory (SK Hynix, Micron, Samsung) | Three suppliers, sold out | Yes, sharply |
| Advanced packaging capacity (CoWoS) | Capacity rationed | Yes |
| Process equipment (AMAT, Lam) | Oligopoly per process step | Somewhat |
| → Process materials (Qnity, Entegris, JSR, Shin-Etsu, Merck) | Qualification lock-in | No — see below |
| PCB fabrication, assembly | Scale only | No |
Qnity’s protection is qualification, not scarcity, and those are different things. Requalifying a CMP slurry at a leading node takes a customer twelve to twenty-four months of test wafers, so incumbency is genuinely sticky — Qnity rarely loses a socket. But there are four to six credible suppliers in every one of its categories, and the buyer on the other side of the table is TSMC or Samsung. High switching costs protect the revenue. They do not create pricing power. You keep the business; you keep it at the customer’s price.
The evidence, and it is unusually direct
Most companies make you infer bargaining power. Qnity discloses it, because it breaks revenue growth into price and volume every year:
| Change in net sales from | 2023 | 2024 | 2025 |
|---|---|---|---|
| Semiconductor Technologies — price and mix | +1% | −2% | −1% |
| volume | −14% | +12% | +9% |
| Interconnect Solutions — price and mix | −2% | −2% | −2% |
| volume | −11% | +9% | +14% |
Read the 2024 and 2025 columns. Those are the two strongest years the semiconductor industry has ever had. NVIDIA was earning ~75% gross margins, TSMC was raising wafer prices, HBM was allocated. In those same two years Qnity gave price back in both segments, every year. Its volumes grew 9–14% and its realised price fell.
And the 2023 column is the mirror image that completes the proof. In the downturn Semiconductor Technologies actually took +1% price — the filings attribute it to “actions taken to offset cost inflation” — while volume fell 14%. Qnity can pass through its own costs. It cannot capture its customers' upside. That is a cost-plus supplier with good technology, not a scarce input.
The tension worth sitting with. Qnity spends 7.4% of sales on R&D — $354M in 2025, an intensity that belongs to a differentiated technology business. It prices like a commodity one. It invests like ASML and prices like a chemicals company, and the four-year record shows the second characteristic winning: company-level margin 31.3% in 2022, 31.2% in 2025.
What this means when the buildout normalizes
Qnity’s earnings are levered to AI volume and not at all to AI pricing. That is a specific and asymmetric exposure:
- In the up-cycle it gets the volume — 22% growth in Q2 2026 — but hands back 1–2 points of price a year, so the margin barely moves.
- In the down-cycle it loses the volume and still cannot get price. 2023 is the measured version of this: revenue −15%, EBITDA −26%.
This is why the layer matters more than the company. Qnity is a good business — qualified into leading-edge nodes, 46% gross margins, a genuinely improving packaging franchise. But it occupies the part of the chain with the least pricing power, and that is the part that gives back the most multiple when the cycle turns, because none of its current multiple is protected by scarcity.
The magnitude is not hypothetical. Qnity trades at 17.2x forward EBITDA today. Its own post-spin low, nine months ago, was 10.9x. Apply that multiple to the EBITDA decline the 2023 destocking actually produced — 26% — and the arithmetic gives roughly $51 a share. That is not a forecast, and it assumes a repeat of the worst year on record simultaneously with a return to the worst multiple on record. It is the shape of the risk, and it is why this page carries a HOLD on a business it rates A−.
In depth: competitive dynamics
Qnity competes in a consolidated, high-switching-cost, qualification-gated market. Materials get designed into a customer’s process flow and re-qualifying a replacement costs the customer time and yield risk, which is why incumbency in this industry is durable and share moves slowly.
| Where | Principal competitors |
|---|---|
| CMP pads and slurries | Entegris, Resonac, Fujifilm |
| Photoresists and lithography materials | JSR, Shin-Etsu, Tokyo Ohka, Merck KGaA (EMD Electronics) |
| Advanced packaging materials | Resonac, Ajinomoto, Sumitomo Bakelite |
| PCB / laminates | Panasonic, Isola, and regional laminators |
Entegris is the closest listed comparable and the one worth watching for read-across. Note that Amkor is a customer-adjacent packaging service provider, not a materials competitor — a distinction some coverage blurs.
Three pieces of third-party validation are worth more than any margin figure, because in this industry design-in is the moat:
- NVIDIA — materials R&D collaboration for next-generation AI and advanced packaging.
- imec — advanced packaging roadmap collaboration.
- Apple — inclusion in the American Manufacturing Program.
You do not get into those rooms on price.
The honest limit of this section. Segment-level market share is still not disclosed anywhere, so “share and content gains” remains management’s characterisation. The competitive assessment is qualitative by necessity.
Who Qnity actually sells to — and where
Both answers are in the 10-K’s revenue disaggregation, and they point in opposite directions.
Customer concentration is better than expected
| 2025 | 2024 | 2023 | |
|---|---|---|---|
| Top ten customers, % of net sales | 34% | 34% | 32% |
Named above 5%: Samsung Electronics ≈11% and TSMC ≈8% of FY2025 net sales. Nothing else is disclosed as individually material.
For a company this levered to AI infrastructure, that is a reassuring answer. Two customers above 8%, a top ten at 34% that has barely moved in three years, and the remaining eight averaging under 2% each. This is a diversified book, not a two-customer business — and it removes what would have been the most dangerous hidden risk.
Geographic concentration is the real risk
FY2025 net sales by region, from the 10-K’s revenue disaggregation:
| Semiconductor Tech | Interconnect | Total | % | |
|---|---|---|---|---|
| China | $713M | $857M | $1,570M | 33.0% |
| South Korea | $617M | $108M | $725M | 15.3% |
| Taiwan | $535M | $172M | $707M | 14.9% |
| Other Asia Pacific | $278M | $467M | $745M | 15.7% |
| Asia Pacific total | $2,143M | $1,604M | $3,747M | 78.8% |
| EMEA | $206M | $172M | $378M | 8.0% |
| Americas (US $591M) | $293M | $336M | $629M | 13.2% |
⚠️ China is 33% of the company and 40.6% of Interconnect Solutions
The fastest-growing, most AI-levered segment is also the most China-exposed one. The United States — where Qnity is listed, where it just opened a 385,000 sq ft plant, and whose export-control regime governs the industry — is 12.4% of revenue.
Qnity’s own risk factors name this directly: trade disputes “can and have limited our ability to sell certain products to certain customers,” and China is described as “a market that is important to our business.” The company’s mitigation is local-for-local sourcing, which it says “helps limit our exposure to tariff-related risks” while conceding it “may not fully mitigate the impact of prolonged or escalating” disruption.
This does not appear in the growth narrative, the sell-side targets, or the multiple. It is the single most likely cause of a permanent de-rating, and it is what holds the Competitive Position and Financial Profile scores below 5.
Financials — and one trap
A GAAP trap worth naming
| Q2 2026 | ||
|---|---|---|
| Adjusted EPS | $1.19 | +53% |
| GAAP EPS | $0.59 | −34% |
A screen run on GAAP EPS shows a business in collapse. It is not. The gap is spin costs, purchase accounting, and interest on $4.0B of new debt that did not exist in the prior-year comparative.
Read EBITDA and cash flow instead, and ignore EPS until the comparative is clean — roughly four quarters after separation. Qnity is three quarters in, and the divergence here is violent enough to fool an automated screen outright.
Capital intensity — and a second-half that has to deliver
Adjusted FCF guidance of $600–700M against $1,700M of adjusted EBITDA is a 38% conversion rate — modest for a business at this margin. The 10-Q shows why, and adds a problem.
| 1H 2026 vs 1H 2025 ($M) | 1H26 | 1H25 |
|---|---|---|
| Cash provided by operating activities | 376 | 480 |
| Capital expenditures | (212) | (153) |
| Free cash flow | 164 | 327 |
First-half FCF was $164M against a $600–700M full-year guide. That requires roughly 75% of the year’s free cash flow to arrive in the second half. Management attributes the 1H shortfall to interest payments on debt that did not exist a year ago, plus working capital — “higher trade receivables due to increased sales and higher inventory … to support sales growth.” Both are explicable and both should reverse. But it is a large back-end weighting on a number that carries a lot of the valuation, and it is the most concrete “show-me” on this page.
Where the capex is going is more encouraging than the total:
| 1H capex by segment ($M) | 1H26 | 1H25 |
|---|---|---|
| Semiconductor Technologies | 125 | 57 |
| Interconnect Solutions | 41 | 44 |
| Corporate | 25 | 8 |
Semiconductor Technologies capex more than doubled — that is Delaware. Interconnect capex actually fell, while that segment grew 30%. The growth engine is the capital-light one; the spending is in the slower segment. FY2025 capex was $285M (6.0% of sales) and D&A $376M, so the current rate is a genuine step-up, not the run-rate.
Capital allocation — begun, and deliberately small
Qnity started returning capital in its first full year, which most spinoffs do not. The amounts are token, and that is the point.
| ($M) | 1H 2026 | 1H 2025 |
|---|---|---|
| Dividends paid to stockholders | (34) | — |
| Repurchases of common stock | (50) | — |
| Distributions to noncontrolling interests | (6) | (8) |
| Total returned | (90) | (8) |
| against free cash flow of | 164 | 327 |
The buyback authorisation is $500M, approved February 20, 2026 — about 1.9% of the market capitalization. $50M of it has been used in six months. The dividend runs roughly $0.16 a share per half, a yield of about 0.26%.
Both are best read as signalling rather than as capital allocation. Together they consumed 55% of a first half in which free cash flow was itself depressed. Qnity is telling the market it intends to be a returner of capital without yet committing meaningful cash to it — sensible for a company nine months old with $4.0B of debt and a capacity program running.
The capital program is the real allocation decision
| ($M) | 2023 | 2024 | 2025 | 1H 2026 |
|---|---|---|---|---|
| Capital expenditures (cash) | 231 | 200 | 285 | 212 |
| Depreciation and amortization | 403 | 394 | 376 | — |
| Capex / D&A | 57% | 51% | 76% | tracking >100% |
Capex ran at half of depreciation through the downturn and is now stepping up hard — the first half of 2026 alone spent 74% of what all of 2025 did. Where it goes matters more than the total:
| Capex by segment ($M) | 2023 | 2024 | 2025 |
|---|---|---|---|
| Semiconductor Technologies | 121 | 88 | 146 |
| Interconnect Solutions | 70 | 95 | 114 |
| Corporate | 26 | 29 | 15 |
Both segments are being funded, and Interconnect’s spend has grown faster off a smaller base — 63% growth over two years against 21% for Semiconductor Technologies. Given that Interconnect is the segment whose margin has actually expanded since 2022 while Semiconductor Technologies’ has contracted, that is capital going to the right place. It is the clearest evidence on this page that management has read its own segment data the same way.
The caveat is the one already flagged: free cash flow guidance of $600–700M requires ~75% of the year’s cash in the second half, and capex is accelerating into exactly that window.
The balance sheet, in detail
Structure — from 10-K Note 14, and it is unusually clean:
| Instrument | Principal | Rate | Matures |
|---|---|---|---|
| Senior secured notes | $1,000M | 5.750% | Aug 2032 |
| Senior unsecured notes | $750M | 6.250% | Aug 2033 |
| Senior secured term loan | $2,350M | SOFR + 1.75%¹ | 2032 |
| Senior secured revolver | $1,250M — undrawn | SOFR + 1.25–2.25% | Oct 2030 |
| Total drawn principal | $4,100M |
¹ Repriced from SOFR + 2.00% on July 1, 2026 — after the quarter closed — with no change to principal, maturity, amortization or covenants. Saves ≈$6M a year.
| Position at June 30, 2026 | |
|---|---|
| Total debt (carrying) | $4,020M |
| Cash | $961M |
| Net debt | $3,059M |
| Total net leverage | 1.80x FY26E adj. EBITDA |
| First-lien net leverage (covenant basis: secured notes + term loan, net) | ≈1.41x |
| Covenant limit | 4.50x, revolver only, tested quarterly |
| Undrawn revolver + cash | ≈$2.2B of liquidity |
| Interest expense | $61M in Q2; $122M in 1H → ≈$244M annualised |
The maturity wall is the best feature. Scheduled amortization is 1% of original principal — $24M a year through 2030 — and then $3,980M falls due in 2032–33. There is no refinancing event for six years, the revolver is completely undrawn with only $12M of letters of credit against it, and the notes trade above par ($4,107M fair value on $4,020M carrying). Covenant headroom is roughly 3x. On the debt, there is nothing to worry about.
Two things that are less comfortable
Goodwill is $7,518M — 52% of total assets ($14,331M) and essentially equal to total equity ($7,546M). Tangible book value is around zero. That is inherited from DuPont’s electronics acquisition history, not created here, but it means there is no asset cushion beneath the leverage and a cyclical downturn brings impairment risk against a $27B market cap.
The $4.1B raised went straight out the door to DuPont. The 10-K is explicit: the term loan “was funded on October 31, 2025, and paid directly to DuPont, along with the proceeds from the issuance of the Notes, in the form of a cash dividend in connection with the Separation.” Qnity was levered up to pay its parent. That is textbook financial engineering — a debt-funded distribution to the parent — and it is the correct label for this spin.
Valuation
Where the multiple has been
| Price | EV | EV/EBITDA | Adj. P/E | |
|---|---|---|---|---|
| Day-1 close | $97.00 | $23.4B | 13.7x | 21.6x |
| Post-spin low — Nov 24, 2025 | $73.54 | $18.5B | 10.9x | 16.3x |
| Peak — Jun 22, 2026 | $175.64 | $39.8B | 23.4x | 39.0x |
| Now — Aug 26, 2026 | $125.50 | $29.3B | 17.2x | 27.8x |
(All on FY26 guidance midpoints, so the earlier rows are shown on today’s numbers deliberately — the point is to isolate the multiple.)
The de-rate is −24.6% of multiple against a +20% guidance raise. There is no company event in the price data: the fall began June 22, six weeks before the strong Q2 print, on ordinary volume, with the two worst sessions at −8.2% each on roughly 1x normal turnover. No news search surfaces a company-specific cause. This reads as a sector de-rate of the AI-materials complex, not a Qnity event, and no company filing or announcement explains it.
Discounted cash flow
Unlevered FCF, 2027–2033 explicit. Revenue decelerating 14% → 6% across the window (converging on management’s own 6–7% algorithm), EBITDA margin easing up 30.8% → 31.5% as Interconnect’s margin convergence offsets its mix weight, capex
- working capital normalizing 9.5% → 6.5% of sales as Delaware and Taiwan season, cash tax 22%.
The margin assumption deserves a second path, and the four-year record is why. Easing up to 31.5% requires expansion this company has not delivered across a full cycle — segment margin was 31.3% in 2022 and 31.2% in 2025. Holding the margin flat at the 30.4% currently guided — which is also, not coincidentally, what the reverse DCF says the market is already assuming — gives:
Exit multiple 14x 16x 18x Margin easing to 31.5% (as modeled) $121 $135 $150 Margin flat at 30.4% $116 $130 $144 About $5 a share, or 4%. Small enough not to change the conclusion, large enough that the page should not claim the higher path as its base. We carry the flat path.
| ($M) | 2027 | 2028 | 2029 | 2030 | 2031 | 2032 | 2033 |
|---|---|---|---|---|---|---|---|
| Revenue | 6,384 | 7,086 | 7,724 | 8,342 | 8,926 | 9,506 | 10,076 |
| Growth | 14.0% | 11.0% | 9.0% | 8.0% | 7.0% | 6.5% | 6.0% |
| EBITDA | 1,966 | 2,211 | 2,433 | 2,628 | 2,812 | 2,994 | 3,174 |
| Capex + WC | (606) | (567) | (541) | (542) | (580) | (618) | (655) |
| Unlevered FCF | 1,003 | 1,245 | 1,456 | 1,617 | 1,731 | 1,843 | 1,954 |
Choosing the discount rate — the assumption that matters most
The rate matters more than any other input, so it is shown as a build-up rather than asserted. Qnity is a cyclical, single-geography-concentrated materials business ten months into its life as a public company — that is not a 1.0 beta.
| Beta | Cost of equity | WACC | |
|---|---|---|---|
| 1.0 | 9.7% | 9.1% | a defensive compounder — not this |
| 1.3 | 11.4% | 10.6% | too generous for this business |
| 1.5 | 12.4% | 11.6% | typical semis-materials |
| 1.65 | 13.3% | 12.5% | |
| 1.9 | 14.6% | 13.6% | cyclical + single-country concentration |
| 2.1 | 15.8% | 14.6% | stress |
Risk-free 4.2%, equity risk premium 5.5%, after-tax cost of debt 3.9%, debt weight 10%.
Two checks anchor it. Qnity’s own unsecured notes yield 6.25%, so any cost of equity close to 10% would sit barely above the company’s own junior debt — implausible for a business with a third of sales in China. And the realised volatility is high:
Annualised realised volatility since the spin is 57.8%, against roughly 15–18% for a broad equity index, and 17 of 200 sessions closed worse than −5%. Volatility is not beta, but a stock this violent does not carry a 1.3.
Value per share across the range
Terminal value from an exit multiple, because that is how these assets actually change hands.
| WACC ↓ / exit → | 12x | 14x | 16x | 18x | 20x |
|---|---|---|---|---|---|
| 10% | $113 | $129 | $145 | $160 | $176 |
| 11% (base) | $106 | $121 | $136 | $150 | $165 |
| 12% | $100 | $114 | $127 | $141 | $155 |
| 13% | $94 | $107 | $120 | $133 | $145 |
| 14% | $88 | $100 | $112 | $125 | $137 |
| 15% | $83 | $94 | $106 | $117 | $128 |
| 16% | $78 | $89 | $99 | $110 | $121 |
Spot is $125.50. Read the grid as a hurdle: at a 10% WACC you need a 14x exit to justify today’s price; at the 11% used here, roughly 15x; at 12% you need 18x; at 14% you need 20x; at 15% and above no exit multiple up to 20x works.
Inverting it — what discount rate does the market itself imply?
| At an exit of | $125.50 implies a WACC of |
|---|---|
| 12x | 8.0% |
| 14x | 10.0% |
| 16x | 11.8% |
| 18x | 13.4% |
| 20x | 14.9% |
At a 16x exit the market is discounting Qnity at 11.8% — close to the 11% used here, and squarely inside the defensible band. The stock is not obviously mispriced in either direction.
What this does to the earlier headline
The first version of this page said the market was paying for only 7% long-run growth. That figure was a function of the 10% discount rate, and it does not survive the correction:
| WACC | Revenue CAGR the market implies at $125.50 |
|---|---|
| 10.0% | 7.0% |
| 11.0% | 8.0% |
| 12.5% | 9.4% |
| 14.0% | 10.8% |
At the 11% used here the market is paying for 8.0% long-run revenue growth, against ~18% guided for this year and 22% delivered last quarter. It is not extrapolating the AI ramp — but nor is it pricing the pre-spin plan. The gap between 8% and what the business is currently doing is the entire opportunity, and it is narrower than a lower discount rate would make it look.
On margin there is no gap at all: at 11% the market implies a steady 30.2% EBITDA margin against the 30.4% currently guided. The market is taking today’s margin and holding it flat forever. Any durable expansion is upside not in the price — though the four-year record above sets a limit on how much to expect: Interconnect has gained 3.8 points since 2022, and Semiconductor Technologies has lost 3.4, leaving the company-level margin flat across the cycle. Flat forever may be closer to right than the growth narrative suggests.
Why the textbook perpetuity DCF is not shown as the answer
Run with 3.0% terminal growth, the Gordon-growth version embeds a terminal multiple of 8.8x. Nothing in this sector trades or transacts near 8.8x — Qnity is at 17.2x, Entegris in the high twenties, and Solstice is paying 23.5x headline for Element Solutions. That is a finding about the method, not about Qnity, which is why the exit-multiple construction is used above.
Earnings-based valuation
The page already flags that GAAP EPS is unusable across the separation date. The four-year record lets us say by how much, and the answer runs against the bearish findings above rather than with them.
Two distortions, both in the same direction. 2023 and 2024 carry no interest expense at all — the $4.0B of debt arrived in November 2025 — and the carve-out tax rate was 15.7% and 19.6% against 24.2% in 2025.
| ($M except per share) | 2023 | 2024 | 2025 |
|---|---|---|---|
| Income before income taxes (as reported) | 632 | 901 | 962 |
| less incremental standalone interest (to ~$244M) | (244) | (244) | (179) |
| Normalized pre-tax | 388 | 657 | 783 |
| Tax at 24% | (93) | (158) | (188) |
| less noncontrolling interests | (26) | (31) | (37) |
| Normalized EPS | $1.28 | $2.24 | $2.66 |
| add back intangible amortization, after tax | 0.95 | 0.84 | 0.75 |
| Normalized cash EPS | $2.23 | $3.08 | $3.41 |
| Reported diluted EPS | $2.42 | $3.31 | $3.30 |
| Effective tax rate as reported | 15.7% | 19.6% | 24.2% |
Reported EPS was flat between 2024 and 2025 — $3.31 against $3.30 — and that is an artefact. Normalized, earnings rose 19%, from $2.24 to $2.66. The reported line was penalised by two months of interest the prior year did not carry and by a tax rate five points higher. The business improved more in 2025 than its own income statement shows, and a screen run on reported EPS sees a company that stopped growing.
This is the one place where the longer record makes Qnity look better rather than worse, and it is worth stating plainly given how much of this page cuts the other way.
What it does not do is make the shares cheap. On normalized cash EPS of $3.41, the stock trades at 36.8x trailing. On the FY2026 guided adjusted figure of roughly $4.51 it is 27.8x. Both are full multiples for a business whose realised price falls 1–2% a year.
Cross-checks
Multiple on FY27E EBITDA of $1,966M: 14x → $116.89 · 16x → $135.67 · 18x → $154.46 · 20x → $173.24.
Transaction comp. Solstice Advanced Materials is paying ~23.5x headline for Element Solutions, or ~18.2x adjusted for the $180M of guided synergies. Qnity trades at 17.2x with faster growth and a ~6pp higher EBITDA margin than the asset being bought. (ESI’s ~$618M of EBITDA is inferred from the reported 23.45x multiple, not confirmed; and deal multiples carry a control premium that trading multiples do not.)
Sell-side: 12-month consensus target around $176.75; RBC Capital at $200, Outperform.
Price target: $132 · range $116–155 · HOLD
Method Value DCF — flat 30.4% margin, WACC 11%, 16x exit $130 DCF — margin easing to 31.5%, 16x exit $135 DCF — flat margin, 14x / 18x exit $116 / $144 FY27E EBITDA at 16x (flat margin: $1,941M) $134 FY27E EBITDA at 18x (the Element Solutions transaction anchor) $152 Sell-side consensus ~$177 Base $132 is +5.2% to the August 26 close of $125.50. Two independent methods land within $4 of each other.
The target moved down from $136, entirely because the margin path did. The four-year record shows segment margin at 31.3% in 2022 and 31.2% in 2025 — flat across a full cycle — so the model now holds it flat rather than easing it up. Nothing about the business changed; the evidence about what it earns through a cycle did.
Recommendation: HOLD. This is a good business at a fair price, not a cheap one. The upside case is real but narrow: the market is paying for 8% long-run growth and a flat margin, and Qnity is currently delivering 22% growth on volume. If that growth persists, the stock is worth more than $132.
The margin half of that case is weaker than this page previously claimed. Across the full cycle — 2022 to 2025 — Qnity’s segment EBITDA margin went from 31.3% to 31.2%. Interconnect gained 3.8 points and Semiconductor Technologies lost 3.4. The market pricing a flat margin forever is not obviously making a mistake, and the case now rests on volume growth alone.
Accumulate below ~$115, where the 16x case offers a double-digit return and the 14x downside is close to covered. At a 2.4% free-cash-flow yield there is no valuation floor: if the advanced-materials complex de-rates further, Qnity goes with it.
Price-target maintenance
This target is a living figure, reviewed after every quarterly print and on any material event — guidance revision, capacity announcement, export-control action touching Qnity’s categories, or a sector transaction that re-anchors the exit multiple. The next scheduled review is the Q3 2026 print, which also settles the second-half free-cash-flow question and the 2H growth guide.
When it moves, the change and its reason are appended here — the prose above is not rewritten; revisions are appended.
What this most resembles
Qnity has three characteristics that should drive its outcome, and each can be tested against something.
Cut 1 — the materials spinoff four days earlier
Solstice Advanced Materials separated from Honeywell on October 30, 2025. Qnity separated from DuPont on November 3. Two advanced-materials businesses, released from diversified American industrial parents, in the same week, both levered on separation to pay the parent, both sold as pure-play re-ratings into structural growth.
They have since produced the same analytical error, in the same direction.
| Solstice | Qnity | |
|---|---|---|
| The growth story | Regulated refrigerant substitution | AI semiconductor buildout |
| What the post-spin filings showed | Margin expanding off 2024 | Margin expanding off 2023 |
| What the longer record showed | RAS margin down in every year since 2023 | Company margin flat 2022 → 2025 |
| The trough that anchored it | H2 2025 | FY2023 destocking |
In both cases the two years of disclosure a new spinco provides began at a cyclical low, and in both cases reading the recovery as expansion overstated the business. That is not a coincidence — it is a structural feature of spinoff analysis, because a parent is most willing to separate a business after a bad patch, and the spinco’s first filings therefore start from one. It is why the four-year table above exists, and why it was worth the work to build.
Cut 2 — spun into a re-rated end market
The relevant precedent set is businesses separated while their end market carried an unusually high multiple. The pattern is that the multiple, not the business, turns out to be the variable. Qnity’s own nine-month trading history is already a small version of it: 10.9x at the post-spin low in November 2025, 23.4x at the June 2026 peak, 17.2x now — a 2.1x range in the multiple, on a business whose guidance only went up.
Nothing in that range was a company event. The page documents that the June de-rate began six weeks before a strong Q2 print, on ordinary volume, with no identifiable cause. For a business in a low-pricing-power layer, the multiple is the position — which is a different statement from the usual spinoff thesis that operational improvement drives the return.
Cut 3 — the link in a re-rated chain that cannot hold price
This is the cut with no clean precedent in our completed set, and it is the one that matters most. The closest analogue is not another spinoff at all: it is what happened to semiconductor materials and equipment suppliers after the 2021–22 cycle. The chain re-rated together on the way up and sorted on the way down, with the sorting variable being pricing power rather than growth.
Qnity’s own 2023 is the local version of that experiment: revenue −15%, EBITDA −26%, price +1% in one segment and −2% in the other. It did not get to defend its earnings with price, because it never had that option.
What the three cuts say together. Qnity is a good business whose margin has not actually expanded across a full cycle, in a layer of the value chain that cannot price, trading at a multiple that has moved 2.1x in nine months for reasons unrelated to its results. None of that argues it is a bad holding. All of it argues that the entry price is the whole decision — which is the same conclusion the valuation section reaches by a different route.
In depth: valuation against peers
The page previously named Entegris as “the closest listed comparable” without a multiple beside it. Here it is, at the August 26, 2026 close.
| Company | What it sells | Price | EV | LTM EBITDA | EV/EBITDA | Fwd P/E |
|---|---|---|---|---|---|---|
| Lam Research | Etch and deposition equipment | $312.53 | $392.3B | $8.64B | 45.4x | 27.0x |
| Applied Materials | Process equipment, broadest portfolio | $477.61 | $379.1B | $10.15B | 37.3x | 25.9x |
| Entegris | Filtration, materials handling, specialty materials | $142.24 | $24.4B | $0.91B | 26.7x | 28.4x |
| MKS Instruments | Subsystems, lasers, PCB chemistry | $272.45 | $21.9B | $1.06B | 20.7x | 15.5x |
| Qnity | Process materials and interconnect materials | $125.50 | $29.3B | $1.44B | 20.3x | 27.8x |
| Qnity on FY2026 guidance | $1.70B | 17.2x |
Qnity is the cheapest name in this group on trailing EBITDA, and it is not an anomaly — it is the ranking the power map predicts.
Read the table top to bottom and it sorts almost exactly by pricing power. Lam and Applied sell capital equipment into an oligopoly of two or three suppliers per process step and carry 37–45x. Entegris — closest to Qnity, but with a larger share of genuinely sole-sourced filtration and handling products — carries 26.7x. MKS, whose PCB chemistry business overlaps Qnity’s Interconnect segment most directly, carries 20.7x — and it is the other name in the group that cannot raise price. Qnity sits with MKS, not with Entegris.
The 6.4-turn discount to Entegris is the number to explain, because Entegris is the comparison the bull case rests on. Three reasons it is at least partly deserved:
- Entegris has more sole-sourced content. Its filtration and fluid-handling products are frequently specified with no qualified alternative. Qnity’s categories have four to six.
- Qnity carries 1.80x net leverage; Entegris carries less relative scale of separation debt, and Qnity’s $4.1B was borrowed to pay a former parent.
- China is 33% of Qnity’s revenue. It is a materially smaller share for the equipment names, whose China exposure has already been through an export-control repricing.
And one reason it is not. Qnity is growing faster — 22% in the most recent quarter against Entegris’s high-single digits — at a higher EBITDA margin (30.4% guided against roughly 28%). On growth-adjusted terms the discount is harder to defend, and that is the strongest quantitative argument the bull case has.
The honest summary. Qnity is cheap against the semiconductor complex and fairly priced against the part of it that shares its economics. If you believe the whole chain re-rates together, Qnity is the cheap way to own it. If you believe the chain sorts by pricing power when the cycle turns, Qnity is priced about right and MKS is the better comparison than Entegris. This page takes the second view, which is why the rating is HOLD.
In depth: is Qnity an acquisition target?
Not before November 3, 2027, and probably not after.
The statutory answer. Qnity was distributed tax-free under §355 on 2025-11-03. Under §355(e), an acquisition of 50% or more of its stock within two years is presumed part of a plan related to the distribution and would make the separation taxable to DuPont. The tax matters agreement will place that cost on Qnity’s side of the line. The window closes 2027-11-03.
The practical answer. At a $27B market cap and $30B enterprise value, the buyer list is short. Merck KGaA (EMD Electronics) and Shin-Etsu are the only strategics of remotely the right scale and both would face a serious antitrust review in photoresists and CMP. Entegris is smaller than the target. Private equity is priced out at a 2.4% FCF yield.
The more interesting direction is the reverse. §355(e) counts an acquisition of 50% or more of a spun-off company’s stock — so it also caps how much of its own stock that company can issue as acquisition currency. A peer demonstrates the constraint in practice: Solstice Advanced Materials, separated from Honeywell eight months earlier, structured its Element Solutions purchase to hand target holders ~44% of the combined company, six points under the threshold.
What expires for Qnity on 2027-11-03 is therefore not primarily its acquirability. It is its freedom to use its own paper. With 99.7% float, a clean balance sheet at 1.80x, and a consolidating materials sector, that is the catalyst worth diarising — and it arrives fourteen months from now.
Tail scenarios
Low probability, high magnitude, short of black swan. For Qnity most of the interesting tails are about where its content sits, not about how many wafers get started — which is the variable the price already reflects.
Upside tails — the adjacencies
1. Requalification cycles are the only moments a materials supplier can take share, and two are coming. The power analysis above says Qnity cannot raise price inside a qualified socket. The corollary is the opportunity: when the process changes, every supplier requalifies from zero. Two such transitions are visible:
- Glass core substrates. The industry’s next substrate technology, with capacity being built by Intel, Samsung and Absolics. Qnity’s metallization, plating and dielectric chemistry transfers directly, and a new substrate means a new qualification round in which incumbency counts for less than chemistry.
- Co-packaged optics. As interconnect moves optical at the package level, low-loss laminates and optical materials become more of the bill of materials. Qnity already sells low-loss adhesives, coverlays and modified-polyimide laminates, and holds optical and silver-nanowire materials in ACP.
This is the one mechanism by which Qnity’s revenue per wafer can step up rather than grind. It is not in any consensus number because it is not in any guidance.
2. Thermal is the content that scales with the problem, not with the unit count. Laird sells thermal interface materials and EMI shielding — Tputty, Tflex, CoolZorb — priced against the heat that must be moved. AI rack power density has gone from roughly 10kW to over 100kW. Every other line in Qnity’s portfolio is consumed per wafer or per board; this one is consumed per watt. Adjacent and unowned: liquid-cooling interface materials, cold-plate compounds, immersion-compatible formulations. If Qnity buys or builds into cooling, it converts a percentage-growth line into a multiple-growth one.
3. Advanced packaging keeps taking value from the fab — and Qnity’s own P&L is already showing it. As compute moves from monolithic dies to chiplets and 3D stacking, more of a processor’s value is created after the wafer leaves the fab. Interconnect’s margin has risen 3.8 points since 2022 while Semiconductor Technologies’ has fallen 3.4. That is the migration, visible inside one company. The upside case is not that Interconnect becomes the bigger segment — it earns a lower margin, so mix shift alone is dilutive — but that its margin keeps converging on Semiconductor Technologies’. Each point of Interconnect margin is worth about $21M of EBITDA; closing the remaining ten-point gap would be worth more than $200M, or roughly 12% of guided EBITDA.
4. Qnity buys something, and it can. Net leverage is 1.80x, liquidity is ~$2.2B, and there is no maturity before 2032. The new CFO executed “two transformational transactions” at Smart Global; the Interconnect president ran DuPont E&I’s M&A. Laird was itself a 2021 DuPont acquisition, so the playbook exists inside the building.
One constraint that is easy to miss. Section 355(e) does not only block Qnity from being acquired until November 3, 2027 — it binds Qnity as an acquirer too. A large enough stock-funded acquisition inside the two-year window can itself trigger the change-of-control test and cost the separation its tax-free status. Cash deals are unaffected, and with $2.2B of liquidity Qnity has room for a meaningful one. But the transformational, paper-funded deal is off the table until late 2027.
Downside tails
1. The normalization scenario, which is this page’s central risk. Set out in the value-chain section above: the last time Qnity’s customers destocked, EBITDA fell 26% in a year. Apply the post-spin trough multiple of 10.9x to that and the arithmetic reaches roughly $51. Not a forecast — the shape of what a low-pricing-power layer gives back when the cycle turns.
2. A qualification loss at a leading node — the mirror of upside tail 1. Requalification cycles cut both ways. Losing a CMP slurry or pad socket at N2 means losing it for the life of the node, which is years, and the loss would not be visible in reported numbers until the node ramps. Qnity discloses no segment share, so an investor cannot monitor this directly. It is the largest un-observable risk on the page.
3. The customers are the ones qualifying the second source. Samsung is ~11% of sales and TSMC ~8%. Neither needs to insource anything to hurt Qnity — they need only keep a second qualified supplier warm in each category, which is standard practice and is the mechanism already producing 1–2% annual price decline. A step-change in that program — a deliberate push on consumable cost per wafer — would show up as price, not volume, and there is no evidence in four years of disclosure that Qnity can resist it.
4. Goodwill. $7,518M, 52% of total assets and close to the entire equity base, inherited from DuPont’s acquisition history. A 2023-style downturn arriving alongside a lower multiple makes the impairment test genuinely hard. It is non-cash and does not touch the covenant, but a writedown would confirm that the price DuPont paid for these assets was not recovered — which is a statement about the business, not the accounting.
5. China, which the page already treats as the base case risk rather than a tail — 33% of sales and 40.6% of Interconnect. It is listed here only to note that the tail version is different from the base version: not tariffs or slower demand, but an export-control action naming Qnity’s specific product categories, which would strand a third of revenue rather than tax it.
What would change this view
| Direction | Trigger |
|---|---|
| Better | Q3 organic growth holding ≥20%, exposing the 2H guide as conservatism · working capital unwinding so 2H FCF lands the guide · capex guided down for 2027 as Taiwan completes · Interconnect margin continuing to converge on Semiconductor Technologies · any disclosure quantifying AI-linked revenue |
| Worse | Q3 organic decelerating below the implied ~16%, confirming a hardening base · Q3 free cash flow failing to close the gap to the $600–700M guide after $164M in 1H · a third capacity announcement extending the capex cycle · Interconnect margin convergence stalling |
| Thesis-breaking | Export-control or tariff action reaching Qnity’s product categories in China — 33% of sales, 40.6% of Interconnect · goodwill impairment against the $7.5B carrying value · sustained wafer-start weakness that content gains fail to offset |
Investment Scorecard
Scored on the five weighted dimensions set out in our methodology.
| Dimension | Weight | Score | Rationale |
|---|---|---|---|
| Financial Profile | 25% | 4.0 | 30.4% adjusted EBITDA margin, +22% organic growth on volume, $5.6B revenue scale, 1.80x net leverage with no maturity before 2032 and an undrawn $1.25B revolver — the balance sheet is close to ideal. Marked down from 4.5 on the four-year record: company margin was flat across the cycle (31.3% in 2022, 31.2% in 2025), and the 2023 destocking took revenue down 15% and EBITDA down 26% — 1.7x downside operating leverage, demonstrated. Also held down by 38% free-cash-flow conversion and goodwill at 52% of assets |
| Competitive Position | 25% | 3.5 | Qualification-gated consumables with high switching costs; design-in relationships with NVIDIA, imec and Apple; a leading position in advanced-node CMP. Marked down from 4.0 on the pricing evidence: realised price fell 1–2% in both segments in both 2024 and 2025 — the two strongest years the industry has had. Qualification protects the socket but confers no pricing power, and the field is genuinely competitive (Entegris, JSR, Shin-Etsu, Merck EMD) with no disclosed segment share |
| Strategic Rationale | 20% | 4.0 | A growing, high-margin business released from a diversified parent rather than a problem being shed. Discounted for the $4.1B of separation debt paid straight to DuPont |
| Management & Governance | 20% | 3.5 | Unchanged, but for different reasons than before. Added on the positive side: a genuinely independent board — three current or former public-company CFOs, a sitting large-cap CEO (TE Connectivity), and a former Samsung president — plus an unusually well-matched permanent CFO in Ken Rizvi (Synaptics, Smart Global, UTAC, and Isola, a direct laminates competitor). Guidance raised twice in three quarters and an opportunistic July debt repricing. Against that: nine months on an interim CFO while carrying $4.0B of new debt, and insider ownership of ~0.1% |
| Acquisition Potential | 10% | 2.0 | Blocked by §355(e) until November 3, 2027, and at ~$30B enterprise value the plausible buyer list is two names, both facing antitrust review in overlapping product lines |
| Weighted Score | 3.58 | ||
| Investment Grade | A− · Strong Opportunity |
| Grade | A− (3.58) |
| Rating | HOLD |
| Price target | $132 (range $116–155), reviewed each quarter |
Why the score moved: 3.83 → 3.58
Two markdowns, each charged to one dimension only:
- Competitive Position 4.0 → 3.5, on the pricing decomposition. Realised price fell in both segments in both 2024 and 2025 — the strongest two years the industry has had. That is a fact about market power, and it belongs here.
- Financial Profile 4.5 → 4.0, on the four-year record. Company margin was flat across the cycle, and 2023 demonstrated 1.7x downside operating leverage. That is a fact about earnings stability, and it belongs there.
Strategic Rationale is deliberately unchanged at 4.0 and Acquisition Potential at 2.0. Nothing new bears on either, and re-charging the pricing finding to a third dimension would be double-counting one objection.
The band does not change. A− is 3.5–3.9, and 3.58 sits inside it. The evidence changed what we know about the earnings, not whether this is a good business.
The grade and the rating are different judgments, and they point different ways here. The grade measures business quality, and it remains high: the customer book is diversified and stable, the debt structure is close to ideal, Interconnect’s margin is genuinely better than at the last peak, and normalized earnings rose 19% in 2025 where reported EPS showed nothing. The rating measures price, and at 17.2x forward EBITDA with a 2.5% free-cash-flow yield there is little margin for error. An A− business can be a HOLD.
What would force a downgrade of the grade — as opposed to the rating — is narrower: an export-control action reaching Qnity’s product categories in China, impairment against the $7.5B of goodwill, a stall in Interconnect’s margin convergence, or a further step down in realised price, which is the line to watch every quarter now that four years of it are visible. Absent those, this is a high-quality business waiting for a better entry.