Sandisk SNDK
+2268.1%vs Day 1Spinoff of Western Digital (WDC) · Classic Spinoff · Spun Feb 24, 2025
Expected return (11/13/2026): -9% Gain to loss: 0.5 : 1Priced for NAND prices to stay high about two years longer than an ordinary cycle allows. Cases $1,346 / $767 / $389 (management's plan / an ordinary cycle / a fast reversion) after Q1 FY2027 beat but guided only modest price increases; weighted 20/60/20, $807, -25%. Contracts cover about half of FY2027 bits and two-thirds of FY2028. No debt. TRIM, target $807 (pre-split).
Current Stats
Post-Spinoff Performance
| Timeline | |
| Spinoff date | February 24, 2025 · Nasdaq |
| Days since spinoff | 628 days · 627 trading-day window |
| Structure | Classic Spinoff |
| §355(e) window closes statutory; a tax matters agreement may bar more, and for longer | February 24, 2027 |
| Parent | Western Digital Corp (WDC) |
| Day-1 reaction | |
| Day 1 open | $52.00 |
| Day 1 return (open→close) | -6.5% |
| Day 1 price (close) | $48.60 |
| Day 1 range | $46.21 – $53.00 +14.7% spread |
| Day 1 low held? | Breached after 2 sessions to -39.6% below |
| Price levels | |
| Post-spin low (closing) | $29.62 on Apr 22, 2025 · 57 days post-spin |
| Lowest traded | $27.89 on Apr 7, 2025 · 42 days post-spin |
| Current price (Nov 13, 2026) | $885.01 |
| Returns | |
| Return vs Day 1 (close) | +1721.0% |
| — range by day 1 entry theoretical bounds | +1569.8% to +1815.2% |
| Return vs post-spin low | +2887.9% |
| First-quarter return (≈90d) | -23.3% |
| 1-year return | +1213.8% |
| Annualized return (CAGR) | +442.2% |
| Versus benchmarks | |
| S&P 500 over same window | +29.0% |
| Annualized excess vs S&P | +426.2% |
| Risk & recovery | |
| Max drawdown | -65.5% |
| Days to recover Day 1 | 7 days |
| Shares & ownership | |
| Shares outstanding Sep 30, 2026 | 144,000,000 |
| Diluted average shares the EPS denominator | 154,000,000 |
| Free float | 140,388,379 99% of shares outstanding |
| Held by institutions | 82% insiders 1.7% |
| Share count trend Mar 2025 → Sep 2026 | -0.7% net buyback |
| Volume & liquidity | |
| Traded per day 20-session median | $12B |
| Normal volume baseline | 2,200,450 shares · now 4.77x |
| Day 1 volume | 15.4x normal · first week 6.2x |
| Decay | half in 2 sessions · normal by 15 |
Computed from split-adjusted closing prices. Returns are total return — (end price + dividends received − start price) ÷ start price — with no reinvestment assumed.
Price History
Closing price, split-adjusted, with volume below. No dividends have been paid, so price return and total return are the same. Source: Yahoo Finance. Data through Nov 14, 2026.
Raw daily price & volume data
| Date | Open | High | Low | Close | Volume | Float | Turnover | Market cap | Dividend | Split |
|---|---|---|---|---|---|---|---|---|---|---|
| 2026-11-13 | $915.86 | $939.53 | $848.50 | $885.01 | 12,170,100 | 140,388,379 | 8.45% | $127.44B | — | — |
| 2026-11-12 | $887.40 | $953.20 | $869.46 | $937.46 | 13,262,200 | 140,388,379 | 9.21% | $134.99B | — | — |
| 2026-11-11 | $928.06 | $1011.05 | $920.11 | $977.69 | 16,403,500 | 140,388,379 | 11.39% | $140.79B | — | — |
| 2026-11-10 | $861.97 | $914.82 | $826.67 | $859.99 | 13,796,400 | 140,388,379 | 9.58% | $123.84B | — | — |
| 2026-11-09 | $856.44 | $904.00 | $830.64 | $886.51 | 13,983,800 | 140,388,379 | 9.71% | $127.66B | — | — |
| 2026-11-06 | $898.27 | $912.09 | $816.42 | $835.06 | 17,763,700 | 140,388,379 | 12.34% | $120.25B | — | — |
| 2026-11-05 | $962.25 | $967.99 | $803.97 | $806.43 | 30,722,600 | 140,388,379 | 21.34% | $116.13B | — | — |
| 2026-11-04 | $1079.91 | $1120.22 | $1014.00 | $1037.40 | 11,541,000 | 140,388,379 | 8.01% | $149.39B | — | — |
| 2026-11-03 | $1107.53 | $1153.19 | $1100.53 | $1126.52 | 8,550,400 | 140,388,379 | 5.94% | $162.22B | — | — |
| 2026-11-02 | $1157.98 | $1159.31 | $1067.40 | $1075.08 | 10,569,900 | 140,388,379 | 7.34% | $154.81B | — | — |
| 2026-10-30 | $1215.09 | $1239.00 | $1115.16 | $1150.89 | 17,469,600 | 140,388,379 | 12.13% | $165.73B | — | — |
| 2026-10-29 | $1381.49 | $1385.80 | $1321.99 | $1330.05 | 8,483,600 | 140,388,379 | 5.89% | $191.53B | — | — |
| 2026-10-28 | $1356.60 | $1408.45 | $1343.85 | $1404.77 | 9,261,200 | 140,388,379 | 6.43% | $202.29B | — | — |
| 2026-10-27 | $1267.90 | $1315.98 | $1259.00 | $1304.84 | 7,061,900 | 140,411,145 | 4.90% | $187.90B | — | — |
| 2026-10-26 | $1251.88 | $1287.84 | $1229.00 | $1255.58 | 6,713,900 | 142,129,440 | 4.66% | $180.80B | — | — |
| 2026-10-23 | $1271.62 | $1299.99 | $1228.89 | $1238.03 | 7,923,500 | 144,517,018 | 5.50% | $178.28B | — | — |
| 2026-10-22 | $1317.26 | $1355.00 | $1244.60 | $1260.93 | 10,414,800 | 144,517,018 | 7.23% | $181.57B | — | — |
| 2026-10-21 | $1415.23 | $1424.48 | $1327.62 | $1378.22 | 6,964,100 | 144,505,305 | 4.84% | $198.46B | — | — |
| 2026-10-20 | $1336.96 | $1388.88 | $1330.00 | $1365.38 | 6,579,900 | 144,505,305 | 4.57% | $196.61B | — | — |
| 2026-10-19 | $1359.00 | $1407.00 | $1357.64 | $1371.12 | 8,535,400 | 144,503,840 | 5.93% | $197.44B | — | — |
| 2026-10-16 | $1348.82 | $1362.35 | $1296.19 | $1299.30 | 8,954,700 | 144,503,840 | 6.22% | $187.10B | — | — |
| 2026-10-15 | $1313.66 | $1397.64 | $1276.00 | $1394.83 | 13,279,800 | 144,503,840 | 9.22% | $200.86B | — | — |
| 2026-10-14 | $1427.38 | $1461.80 | $1402.02 | $1403.34 | 7,458,800 | 144,503,840 | 5.18% | $202.08B | — | — |
| 2026-10-13 | $1406.22 | $1484.00 | $1401.01 | $1482.33 | 8,400,300 | 144,503,840 | 5.83% | $213.46B | — | — |
| 2026-10-12 | $1538.11 | $1539.10 | $1464.43 | $1487.33 | 8,803,900 | 144,503,840 | 6.11% | $214.18B | — | — |
| 2026-10-09 | $1633.33 | $1637.95 | $1575.69 | $1581.82 | 5,606,800 | 144,503,840 | 3.89% | $227.78B | — | — |
| 2026-10-08 | $1669.49 | $1675.00 | $1584.14 | $1609.46 | 9,357,000 | 144,503,840 | 6.50% | $231.76B | — | — |
| 2026-10-07 | $1620.00 | $1733.28 | $1617.77 | $1692.42 | 9,166,900 | 144,509,697 | 6.37% | $243.71B | — | — |
| 2026-10-06 | $1700.00 | $1716.50 | $1650.00 | $1660.46 | 6,529,700 | 144,509,697 | 4.53% | $239.11B | — | — |
| 2026-10-05 | $1725.00 | $1743.24 | $1681.00 | $1704.16 | 6,502,500 | 144,509,697 | 4.52% | $245.40B | — | — |
| 2026-10-02 | $1773.12 | $1774.23 | $1713.47 | $1719.99 | 8,191,500 | 144,509,697 | 5.69% | $247.68B | — | — |
| 2026-10-01 | $1735.26 | $1802.00 | $1708.00 | $1787.69 | 9,218,100 | 144,509,697 | 6.40% | $257.43B | — | — |
| 2026-09-30 | $1729.78 | $1756.00 | $1720.71 | $1739.89 | 6,052,400 | 144,509,697 | 4.20% | $250.54B | — | — |
| 2026-09-29 | $1744.07 | $1749.78 | $1693.00 | $1729.76 | 5,963,000 | 144,509,697 | 4.08% | $252.54B | — | — |
| 2026-09-28 | $1736.64 | $1762.00 | $1659.02 | $1712.89 | 6,662,200 | 144,509,697 | 4.56% | $250.08B | — | — |
| 2026-09-25 | $1791.94 | $1815.00 | $1742.59 | $1777.80 | 7,341,800 | 144,509,697 | 5.03% | $259.56B | — | — |
| 2026-09-24 | $1785.47 | $1802.99 | $1726.39 | $1753.62 | 8,231,700 | 144,509,697 | 5.64% | $256.03B | — | — |
| 2026-09-23 | $1895.41 | $1902.22 | $1803.67 | $1816.57 | 7,732,000 | 144,509,697 | 5.30% | $265.22B | — | — |
| 2026-09-22 | $1757.51 | $1909.48 | $1756.82 | $1887.04 | 12,927,100 | 144,509,697 | 8.85% | $275.51B | — | — |
| 2026-09-21 | $1826.00 | $1834.49 | $1737.01 | $1766.64 | 10,442,700 | 144,509,697 | 7.15% | $257.93B | — | — |
| 2026-09-18 | $1625.20 | $1797.00 | $1616.00 | $1791.82 | 17,788,400 | 144,509,697 | 12.18% | $261.61B | — | — |
| 2026-09-17 | $1564.53 | $1625.35 | $1564.50 | $1614.39 | 8,480,500 | 144,509,697 | 5.81% | $235.70B | — | — |
| 2026-09-16 | $1549.74 | $1560.58 | $1504.20 | $1519.97 | 7,419,200 | 144,483,342 | 5.08% | $221.92B | — | — |
| 2026-09-15 | $1569.71 | $1579.99 | $1509.14 | $1530.90 | 6,873,900 | 144,483,342 | 4.71% | $223.51B | — | — |
| 2026-09-14 | $1521.53 | $1581.84 | $1505.00 | $1551.99 | 9,586,700 | 144,448,201 | 6.57% | $226.59B | — | — |
| 2026-09-11 | $1713.50 | $1720.70 | $1616.80 | $1633.35 | 9,371,400 | 144,448,201 | 6.42% | $238.47B | — | — |
| 2026-09-10 | $1725.44 | $1733.95 | $1674.00 | $1692.59 | 8,737,100 | 144,448,201 | 5.98% | $247.12B | — | — |
| 2026-09-09 | $1751.30 | $1807.22 | $1728.02 | $1764.17 | 9,574,900 | 144,448,201 | 6.56% | $257.57B | — | — |
| 2026-09-08 | $1769.43 | $1807.38 | $1733.78 | $1737.99 | 11,199,700 | 144,448,201 | 7.67% | $253.75B | — | — |
| 2026-09-04 | $1586.00 | $1740.00 | $1581.00 | $1740.00 | 16,557,000 | 144,417,453 | 11.34% | $254.04B | — | — |
| 2026-09-03 | $1544.55 | $1576.80 | $1511.00 | $1554.99 | 8,688,900 | 144,417,453 | 5.95% | $227.03B | — | — |
| 2026-09-02 | $1531.62 | $1587.86 | $1509.24 | $1553.40 | 8,939,600 | 144,417,453 | 6.12% | $226.80B | — | — |
| 2026-09-01 | $1526.01 | $1609.60 | $1513.00 | $1536.87 | 11,729,800 | 144,417,453 | 8.03% | $224.38B | — | — |
| 2026-08-31 | $1486.40 | $1572.69 | $1449.50 | $1566.70 | 23,378,800 | 144,417,453 | 16.01% | $228.74B | — | — |
| 2026-08-28 | $1448.00 | $1517.75 | $1435.61 | $1484.98 | 8,141,400 | 144,417,453 | 5.58% | $216.81B | — | — |
| 2026-08-27 | $1549.42 | $1557.89 | $1456.00 | $1484.95 | 8,854,300 | 144,417,453 | 6.06% | $216.80B | — | — |
| 2026-08-26 | $1455.57 | $1511.77 | $1450.05 | $1499.37 | 8,968,600 | 144,417,453 | 6.14% | $218.91B | — | — |
| 2026-08-25 | $1533.69 | $1564.99 | $1467.01 | $1480.77 | 9,032,300 | 144,366,207 | 6.19% | $216.19B | — | — |
| 2026-08-24 | $1494.09 | $1517.00 | $1416.56 | $1493.12 | 14,032,400 | 144,366,207 | 9.61% | $218.00B | — | — |
| 2026-08-21 | $1604.81 | $1614.06 | $1570.01 | $1596.08 | 7,576,500 | 144,366,207 | 5.19% | $233.03B | — | — |
| 2026-08-20 | $1569.00 | $1631.40 | $1554.00 | $1600.62 | 11,459,600 | 144,336,923 | 7.85% | $233.69B | — | — |
| 2026-08-19 | $1682.41 | $1699.00 | $1542.00 | $1568.87 | 16,280,200 | 144,336,923 | 11.15% | $229.06B | — | — |
| 2026-08-18 | $1677.54 | $1724.99 | $1600.20 | $1625.78 | 18,650,700 | 144,336,923 | 12.77% | $237.36B | — | — |
| 2026-08-17 | $1700.74 | $1827.99 | $1698.00 | $1786.85 | 18,037,600 | 144,336,923 | 12.35% | $260.88B | — | — |
| 2026-08-14 | $1646.93 | $1667.19 | $1565.00 | $1641.11 | 21,000,300 | 144,336,923 | 14.38% | $239.60B | — | — |
| 2026-08-13 | $1339.83 | $1580.88 | $1331.58 | $1528.11 | 22,094,400 | — | 15.13% | $223.10B | — | — |
| 2026-08-12 | $1358.22 | $1389.28 | $1308.53 | $1344.29 | 12,054,700 | — | 8.26% | $196.27B | — | — |
| 2026-08-11 | $1260.56 | $1287.04 | $1242.06 | $1271.05 | 9,412,800 | — | 6.45% | $185.57B | — | — |
| 2026-08-10 | $1203.41 | $1278.76 | $1194.01 | $1237.92 | 10,870,900 | — | 7.45% | $180.74B | — | — |
| 2026-08-07 | $1309.30 | $1309.53 | $1184.37 | $1212.21 | 13,953,700 | — | 9.56% | $176.98B | — | — |
| 2026-08-06 | $1173.26 | $1324.00 | $1163.09 | $1258.58 | 19,161,700 | — | 13.12% | $183.75B | — | — |
| 2026-08-05 | $1398.77 | $1441.76 | $1345.00 | $1350.50 | 16,369,800 | — | 11.21% | $197.17B | — | — |
| 2026-08-04 | $1358.21 | $1446.62 | $1340.00 | $1427.62 | 14,685,300 | — | 10.06% | $208.43B | — | — |
| 2026-08-03 | $1159.84 | $1316.45 | $1121.27 | $1288.03 | 14,759,300 | — | 10.11% | $188.05B | — | — |
| 2026-07-31 | $1383.69 | $1404.99 | $1187.26 | $1214.83 | 21,176,600 | — | 14.50% | $177.37B | — | — |
| 2026-07-30 | $1135.01 | $1285.48 | $1124.00 | $1279.96 | 24,398,700 | — | 16.71% | $186.87B | — | — |
| 2026-07-29 | $1119.33 | $1124.80 | $998.19 | $1015.89 | 24,491,100 | — | 16.77% | $148.32B | — | — |
| 2026-07-28 | $1173.60 | $1188.00 | $1050.72 | $1096.10 | 26,627,200 | — | 18.24% | $160.03B | — | — |
| 2026-07-27 | $1462.99 | $1462.99 | $1222.01 | $1278.23 | 21,275,600 | — | 14.57% | $186.62B | — | — |
| 2026-07-24 | $1551.17 | $1573.09 | $1411.50 | $1436.56 | 14,081,100 | — | 9.64% | $209.74B | — | — |
| 2026-07-23 | $1567.60 | $1696.37 | $1558.61 | $1610.33 | 12,756,900 | — | 8.74% | $235.11B | — | — |
| 2026-07-22 | $1526.00 | $1628.40 | $1516.01 | $1599.27 | 10,539,100 | — | 7.22% | $233.49B | — | — |
| 2026-07-21 | $1511.67 | $1595.64 | $1489.65 | $1589.40 | 14,295,900 | — | 9.79% | $232.05B | — | — |
| 2026-07-20 | $1408.78 | $1454.99 | $1375.61 | $1390.95 | 12,572,000 | — | 8.61% | $203.08B | — | — |
| 2026-07-17 | $1365.20 | $1501.20 | $1325.03 | $1354.82 | 19,810,900 | — | 13.57% | $197.80B | — | — |
| 2026-07-16 | $1527.49 | $1551.63 | $1390.04 | $1411.08 | 17,449,900 | — | 11.95% | $206.02B | — | — |
| 2026-07-15 | $1717.29 | $1729.50 | $1478.50 | $1615.00 | 19,082,600 | — | 13.07% | $235.79B | — | — |
| 2026-07-14 | $1807.00 | $1812.54 | $1711.47 | $1757.82 | 9,630,900 | — | 6.60% | $256.64B | — | — |
| 2026-07-13 | $1792.86 | $1800.00 | $1646.17 | $1673.97 | 13,900,700 | — | 9.52% | $244.40B | — | — |
| 2026-07-10 | $1778.98 | $1946.83 | $1773.00 | $1915.92 | 11,022,700 | — | 7.55% | $279.72B | — | — |
| 2026-07-09 | $1835.61 | $1952.59 | $1801.00 | $1858.27 | 13,359,300 | — | 9.15% | $271.31B | — | — |
| 2026-07-08 | $1591.80 | $1734.69 | $1590.00 | $1727.18 | 12,048,600 | — | 8.25% | $252.17B | — | — |
| 2026-07-07 | $1619.28 | $1638.88 | $1485.02 | $1617.70 | 14,530,800 | — | 9.95% | $236.18B | — | — |
| 2026-07-06 | $1828.68 | $1837.77 | $1713.20 | $1744.43 | 9,164,200 | — | 6.28% | $254.69B | — | — |
| 2026-07-02 | $2043.80 | $2052.54 | $1693.00 | $1745.00 | 17,259,300 | — | 11.82% | $254.77B | — | — |
| 2026-07-01 | $2085.17 | $2129.98 | $2002.05 | $2032.22 | 11,056,500 | — | 7.57% | $296.70B | — | — |
| 2026-06-30 | $2109.73 | $2280.80 | $2070.00 | $2273.73 | 11,454,300 | — | 7.85% | $331.96B | — | — |
| 2026-06-29 | $2090.71 | $2090.71 | $1895.00 | $2050.39 | 11,251,000 | — | 7.60% | $303.46B | — | — |
| 2026-06-26 | $2170.00 | $2256.11 | $2063.04 | $2090.71 | 16,867,100 | — | 11.40% | $309.43B | — | — |
| 2026-06-25 | $2238.30 | $2348.00 | $2092.08 | $2335.00 | 15,030,200 | — | 10.16% | $345.58B | — | — |
| 2026-06-24 | $1987.53 | $2021.50 | $1861.01 | $1914.46 | 10,421,300 | — | 7.04% | $283.34B | — | — |
| 2026-06-23 | $2007.70 | $2060.00 | $1949.96 | $1963.60 | 12,868,300 | — | 8.69% | $290.61B | — | — |
| 2026-06-22 | $2293.31 | $2354.39 | $2251.28 | $2273.73 | 9,977,600 | — | 6.74% | $336.51B | — | — |
| 2026-06-18 | $2044.74 | $2191.69 | $2029.00 | $2184.75 | 12,178,300 | — | 8.23% | $323.34B | — | — |
| 2026-06-17 | $2074.59 | $2074.59 | $1938.00 | $1958.80 | 9,182,500 | — | 6.20% | $289.90B | — | — |
| 2026-06-16 | $2134.20 | $2167.33 | $1980.18 | $1991.55 | 9,588,500 | — | 6.48% | $294.75B | — | — |
| 2026-06-15 | $2101.12 | $2119.90 | $2021.11 | $2107.86 | 9,156,400 | — | 6.19% | $311.96B | — | — |
| 2026-06-12 | $1890.98 | $2021.65 | $1865.11 | $1980.10 | 11,926,100 | — | 8.06% | $293.05B | — | — |
| 2026-06-11 | $1672.26 | $1895.00 | $1665.00 | $1881.51 | 13,759,400 | — | 9.30% | $278.46B | — | — |
| 2026-06-10 | $1624.38 | $1764.65 | $1590.00 | $1643.23 | 10,362,000 | — | 7.00% | $243.20B | — | — |
| 2026-06-09 | $1700.50 | $1803.00 | $1536.00 | $1646.54 | 16,221,600 | — | 10.96% | $243.69B | — | — |
| 2026-06-08 | $1634.00 | $1694.99 | $1602.00 | $1642.00 | 8,189,300 | — | 5.53% | $243.02B | — | — |
| 2026-06-05 | $1678.88 | $1682.00 | $1514.36 | $1559.32 | 13,289,000 | — | 8.98% | $230.78B | — | — |
| 2026-06-04 | $1741.31 | $1825.90 | $1725.08 | $1759.68 | 10,518,500 | — | 7.11% | $260.43B | — | — |
| 2026-06-03 | $1736.00 | $1861.00 | $1708.88 | $1831.50 | 11,884,700 | — | 8.03% | $271.06B | — | — |
| 2026-06-02 | $1750.06 | $1772.40 | $1708.80 | $1716.36 | 7,093,300 | — | 4.79% | $254.02B | — | — |
| 2026-06-01 | $1731.15 | $1804.00 | $1686.16 | $1761.43 | 9,681,700 | — | 6.54% | $260.69B | — | — |
| 2026-05-29 | $1682.00 | $1708.82 | $1641.08 | $1694.98 | 8,751,100 | — | 5.91% | $250.86B | — | — |
| 2026-05-28 | $1596.31 | $1697.96 | $1560.18 | $1641.64 | 10,004,100 | — | 6.76% | $242.96B | — | — |
| 2026-05-27 | $1645.99 | $1658.77 | $1528.28 | $1589.94 | 10,394,200 | — | 7.02% | $235.31B | — | — |
| 2026-05-26 | $1535.21 | $1641.74 | $1520.00 | $1589.55 | 12,919,700 | — | 8.73% | $235.25B | — | — |
| 2026-05-22 | $1520.71 | $1528.00 | $1473.52 | $1478.69 | 9,657,100 | — | 6.53% | $218.85B | — | — |
| 2026-05-21 | $1377.47 | $1546.09 | $1377.47 | $1542.24 | 13,746,100 | — | 9.29% | $228.25B | — | — |
| 2026-05-20 | $1437.98 | $1444.00 | $1366.98 | $1392.56 | 9,141,200 | — | 6.18% | $206.10B | — | — |
| 2026-05-19 | $1289.75 | $1392.86 | $1278.11 | $1383.29 | 13,309,300 | — | 8.99% | $204.73B | — | — |
| 2026-05-18 | $1431.67 | $1440.00 | $1277.33 | $1333.01 | 13,904,400 | — | 9.39% | $197.29B | — | — |
| 2026-05-15 | $1321.00 | $1426.38 | $1315.75 | $1407.61 | 14,011,300 | — | 9.47% | $208.33B | — | — |
| 2026-05-14 | $1394.40 | $1453.77 | $1362.00 | $1382.72 | 11,213,600 | — | 7.58% | $204.64B | — | — |
| 2026-05-13 | $1512.48 | $1513.57 | $1404.86 | $1447.23 | 11,618,700 | — | 7.85% | $214.19B | — | — |
| 2026-05-12 | $1492.00 | $1508.32 | $1367.00 | $1452.02 | 17,138,500 | — | 11.58% | $214.90B | — | — |
| 2026-05-11 | $1586.25 | $1600.00 | $1514.47 | $1547.56 | 16,516,800 | — | 11.16% | $229.04B | — | — |
| 2026-05-08 | $1394.37 | $1564.00 | $1391.12 | $1562.34 | 20,567,600 | — | 13.90% | $231.23B | — | — |
| 2026-05-07 | $1379.42 | $1400.99 | $1292.57 | $1339.96 | 16,243,300 | — | 10.98% | $198.31B | — | — |
| 2026-05-06 | $1437.40 | $1439.70 | $1337.56 | $1409.98 | 21,114,100 | — | 14.27% | $208.68B | — | — |
| 2026-05-05 | $1289.01 | $1418.88 | $1286.13 | $1406.32 | 20,668,200 | — | 13.96% | $208.14B | — | — |
| 2026-05-04 | $1222.18 | $1275.11 | $1205.00 | $1255.86 | 17,853,000 | — | 12.06% | $185.87B | — | — |
| 2026-05-01 | $1059.02 | $1189.24 | $1048.00 | $1187.00 | 23,126,800 | — | 15.63% | $175.68B | — | — |
| 2026-04-30 | $1112.43 | $1115.00 | $1076.05 | $1096.51 | 15,088,300 | — | 10.19% | $162.28B | — | — |
| 2026-04-29 | $1070.60 | $1103.00 | $1060.00 | $1064.21 | 11,350,200 | — | 7.67% | $157.50B | — | — |
| 2026-04-28 | $1027.60 | $1054.22 | $980.28 | $1002.35 | 14,119,000 | — | 9.54% | $148.35B | — | — |
| 2026-04-27 | $1019.65 | $1070.66 | $1008.88 | $1070.20 | 13,005,000 | — | 8.79% | $158.39B | — | — |
| 2026-04-24 | $954.56 | $1002.09 | $947.00 | $989.90 | 11,642,800 | — | 7.87% | $146.51B | — | — |
| 2026-04-23 | $948.54 | $978.88 | $926.11 | $932.43 | 12,272,600 | — | 8.29% | $138.00B | — | — |
| 2026-04-22 | $922.01 | $981.06 | $895.74 | $979.07 | 15,497,400 | — | 10.47% | $144.90B | — | — |
| 2026-04-21 | $927.85 | $938.78 | $899.20 | $903.49 | 10,245,900 | — | 6.92% | $133.72B | — | — |
| 2026-04-20 | $930.97 | $951.47 | $900.37 | $913.02 | 11,303,500 | — | 7.64% | $135.13B | — | — |
| 2026-04-17 | $920.84 | $930.50 | $886.00 | $920.99 | 25,655,700 | — | 17.33% | $136.31B | — | — |
| 2026-04-16 | $896.62 | $929.50 | $892.51 | $919.47 | 13,851,900 | — | 9.36% | $136.08B | — | — |
| 2026-04-15 | $929.86 | $937.99 | $873.93 | $891.72 | 16,269,600 | — | 10.99% | $131.97B | — | — |
| 2026-04-14 | $964.02 | $965.00 | $902.00 | $944.46 | 19,821,500 | — | 13.39% | $139.78B | — | — |
| 2026-04-13 | $867.09 | $953.41 | $866.95 | $952.50 | 20,234,400 | — | 13.67% | $140.97B | — | — |
| 2026-04-10 | $873.95 | $873.95 | $835.28 | $851.77 | 13,343,800 | — | 9.02% | $126.06B | — | — |
| 2026-04-09 | $817.08 | $855.00 | $805.00 | $851.57 | 17,233,600 | — | 11.64% | $126.03B | — | — |
| 2026-04-08 | $784.00 | $807.99 | $758.19 | $780.90 | 16,898,900 | — | 11.42% | $115.57B | — | — |
| 2026-04-07 | $715.70 | $738.01 | $687.68 | $710.80 | 14,406,500 | — | 9.73% | $105.20B | — | — |
| 2026-04-06 | $720.34 | $736.00 | $711.00 | $724.63 | 12,773,700 | — | 8.63% | $107.25B | — | — |
| 2026-04-02 | $642.09 | $707.31 | $641.00 | $701.59 | 17,443,900 | — | 11.79% | $103.84B | — | — |
| 2026-04-01 | $652.29 | $710.85 | $645.10 | $692.73 | 22,322,700 | — | 15.08% | $102.52B | — | — |
| 2026-03-31 | $588.01 | $636.32 | $578.42 | $635.34 | 20,685,000 | — | 13.98% | $94.03B | — | — |
| 2026-03-30 | $642.12 | $651.00 | $558.58 | $572.50 | 20,501,200 | — | 13.85% | $84.73B | — | — |
| 2026-03-27 | $599.75 | $638.52 | $599.37 | $615.83 | 16,684,200 | — | 11.27% | $91.14B | — | — |
| 2026-03-26 | $654.00 | $659.66 | $602.03 | $603.17 | 19,023,800 | — | 12.85% | $89.27B | — | — |
| 2026-03-25 | $651.00 | $687.22 | $638.00 | $677.86 | 20,618,700 | — | 13.93% | $100.32B | — | — |
| 2026-03-24 | $693.69 | $711.30 | $680.19 | $702.48 | 14,536,300 | — | 9.82% | $103.97B | — | — |
| 2026-03-23 | $716.00 | $748.78 | $678.84 | $702.49 | 22,925,100 | — | 15.49% | $103.97B | — | — |
| 2026-03-20 | $772.70 | $777.60 | $698.35 | $709.71 | 23,508,600 | — | 15.88% | $105.04B | — | — |
| 2026-03-19 | $707.15 | $776.00 | $692.00 | $772.09 | 21,266,400 | — | 14.37% | $114.27B | — | — |
| 2026-03-18 | $730.02 | $761.52 | $715.50 | $753.69 | 20,663,100 | — | 13.96% | $111.55B | — | — |
| 2026-03-17 | $716.00 | $721.37 | $695.12 | $720.17 | 14,782,100 | — | 9.99% | $106.59B | — | — |
| 2026-03-16 | $687.52 | $720.00 | $687.43 | $703.63 | 19,406,300 | — | 13.11% | $104.14B | — | — |
| 2026-03-13 | $630.75 | $671.67 | $623.06 | $661.62 | 18,806,900 | — | 12.71% | $97.92B | — | — |
| 2026-03-12 | $647.00 | $651.99 | $612.21 | $618.82 | 17,284,100 | — | 11.68% | $91.59B | — | — |
| 2026-03-11 | $625.95 | $655.68 | $618.80 | $655.43 | 15,815,800 | — | 10.69% | $97.00B | — | — |
| 2026-03-10 | $599.23 | $636.58 | $595.56 | $618.89 | 18,133,200 | — | 12.25% | $91.60B | — | — |
| 2026-03-09 | $517.00 | $589.51 | $517.00 | $588.73 | 21,205,500 | — | 14.33% | $87.13B | — | — |
| 2026-03-06 | $548.25 | $570.90 | $526.63 | $527.33 | 16,108,900 | — | 10.88% | $78.04B | — | — |
| 2026-03-05 | $594.39 | $603.53 | $559.10 | $565.59 | 15,433,600 | — | 10.43% | $83.71B | — | — |
| 2026-03-04 | $586.84 | $607.48 | $576.30 | $599.06 | 15,614,300 | — | 10.55% | $88.66B | — | — |
| 2026-03-03 | $581.64 | $593.16 | $557.09 | $565.41 | 20,533,500 | — | 13.87% | $83.68B | — | — |
| 2026-03-02 | $618.65 | $648.80 | $597.60 | $619.08 | 17,519,900 | — | 11.84% | $91.62B | — | — |
| 2026-02-27 | $627.08 | $661.20 | $621.27 | $635.36 | 18,208,200 | — | 12.30% | $94.03B | — | — |
| 2026-02-26 | $645.74 | $659.86 | $607.00 | $651.90 | 23,672,700 | — | 16.00% | $96.48B | — | — |
| 2026-02-25 | $644.30 | $661.20 | $624.43 | $632.38 | 18,561,500 | — | 12.54% | $93.59B | — | — |
| 2026-02-24 | $682.50 | $684.09 | $612.92 | $638.52 | 30,408,300 | — | 20.55% | $94.50B | — | — |
| 2026-02-23 | $659.59 | $691.54 | $644.38 | $666.49 | 18,569,400 | — | 12.55% | $98.64B | — | — |
| 2026-02-20 | $616.00 | $650.29 | $615.65 | $649.97 | 17,001,000 | — | 11.49% | $96.20B | — | — |
| 2026-02-19 | $597.33 | $634.48 | $590.10 | $621.09 | 19,601,600 | — | 13.24% | $91.92B | — | — |
| 2026-02-18 | $582.49 | $616.98 | $574.50 | $600.40 | 25,097,600 | — | 16.96% | $88.86B | — | — |
| 2026-02-17 | $612.00 | $628.65 | $588.95 | $590.59 | 19,143,200 | — | 12.93% | $87.41B | — | — |
| 2026-02-13 | $610.53 | $661.50 | $586.37 | $626.56 | 23,640,400 | — | 15.97% | $92.73B | — | — |
| 2026-02-12 | $640.55 | $668.00 | $615.62 | $630.29 | 23,321,100 | — | 15.76% | $93.28B | — | — |
| 2026-02-11 | $578.50 | $612.80 | $575.00 | $599.34 | 20,472,700 | — | 13.83% | $88.70B | — | — |
| 2026-02-10 | $573.88 | $582.28 | $540.14 | $541.64 | 15,904,000 | — | 10.75% | $80.16B | — | — |
| 2026-02-09 | $592.16 | $603.98 | $551.51 | $583.40 | 15,290,700 | — | 10.33% | $86.34B | — | — |
| 2026-02-06 | $614.50 | $615.36 | $575.50 | $597.95 | 21,327,300 | — | 14.41% | $88.50B | — | — |
| 2026-02-05 | $563.75 | $619.41 | $562.10 | $576.20 | 27,725,500 | — | 18.73% | $85.28B | — | — |
| 2026-02-04 | $654.00 | $662.79 | $582.00 | $584.55 | 29,007,600 | — | 19.60% | $86.51B | — | — |
| 2026-02-03 | $694.06 | $725.00 | $646.20 | $695.51 | 31,213,200 | — | 21.09% | $102.94B | — | — |
| 2026-02-02 | $588.81 | $674.00 | $584.10 | $665.24 | 28,765,800 | — | 19.44% | $98.46B | — | — |
| 2026-01-30 | $651.23 | $676.69 | $533.00 | $576.25 | 40,932,100 | — | 27.66% | $85.28B | — | — |
| 2026-01-29 | $535.85 | $546.75 | $507.24 | $539.30 | 23,010,300 | — | 15.55% | $79.82B | — | — |
| 2026-01-28 | $500.10 | $531.46 | $499.15 | $527.63 | 16,486,300 | — | 11.14% | $78.09B | — | — |
| 2026-01-27 | $481.01 | $503.00 | $471.15 | $481.43 | 14,015,600 | — | 9.47% | $71.25B | — | — |
| 2026-01-26 | $476.48 | $494.70 | $454.33 | $470.80 | 13,435,200 | — | 9.08% | $69.68B | — | — |
| 2026-01-23 | $503.44 | $506.30 | $463.01 | $473.83 | 21,061,100 | — | 14.23% | $70.13B | — | — |
| 2026-01-22 | $501.29 | $509.50 | $467.56 | $503.44 | 20,607,500 | — | 13.92% | $74.51B | — | — |
| 2026-01-21 | $463.05 | $501.95 | $448.53 | $501.29 | 21,365,000 | — | 14.44% | $74.19B | — | — |
| 2026-01-20 | $412.17 | $457.37 | $412.17 | $453.12 | 17,872,400 | — | 12.08% | $67.06B | — | — |
| 2026-01-16 | $425.59 | $432.02 | $399.70 | $413.62 | 15,703,000 | — | 10.61% | $61.22B | — | — |
| 2026-01-15 | $398.83 | $423.35 | $398.61 | $409.24 | 14,146,600 | — | 9.56% | $60.57B | — | — |
| 2026-01-14 | $390.00 | $401.20 | $377.00 | $387.81 | 10,862,500 | — | 7.34% | $57.40B | — | — |
| 2026-01-13 | $393.20 | $398.00 | $379.41 | $389.81 | 10,818,600 | — | 7.31% | $57.69B | — | — |
| 2026-01-12 | $373.97 | $395.16 | $373.97 | $389.27 | 14,603,900 | — | 9.87% | $57.61B | — | — |
| 2026-01-09 | $341.60 | $384.00 | $334.54 | $377.41 | 19,353,200 | — | 13.08% | $55.86B | — | — |
| 2026-01-08 | $360.73 | $360.98 | $310.78 | $334.54 | 21,404,400 | — | 14.46% | $49.51B | — | — |
| 2026-01-07 | $340.88 | $354.93 | $331.23 | $353.56 | 14,886,100 | — | 10.06% | $52.33B | — | — |
| 2026-01-06 | $288.74 | $352.00 | $288.50 | $349.63 | 24,249,700 | — | 16.38% | $51.75B | — | — |
| 2026-01-05 | $284.22 | $285.00 | $266.33 | $274.08 | 9,812,600 | — | 6.63% | $40.56B | — | — |
| 2026-01-02 | $244.35 | $275.80 | $244.00 | $275.24 | 11,104,300 | — | 7.50% | $40.74B | — | — |
| 2025-12-31 | $241.41 | $241.90 | $235.24 | $237.38 | 4,180,400 | — | 2.82% | $35.13B | — | — |
| 2025-12-30 | $245.87 | $247.48 | $236.52 | $240.22 | 6,617,000 | — | 4.50% | $35.31B | — | — |
| 2025-12-29 | $241.55 | $250.00 | $236.01 | $244.25 | 5,706,200 | — | 3.88% | $35.90B | — | — |
| 2025-12-26 | $259.60 | $261.50 | $245.10 | $250.05 | 5,553,700 | — | 3.78% | $36.76B | — | — |
| 2025-12-24 | $244.90 | $261.37 | $244.50 | $250.08 | 5,642,600 | — | 3.84% | $36.76B | — | — |
| 2025-12-23 | $238.42 | $245.50 | $234.00 | $244.90 | 5,305,700 | — | 3.61% | $36.00B | — | — |
| 2025-12-22 | $249.65 | $252.00 | $226.60 | $241.05 | 8,663,400 | — | 5.89% | $35.43B | — | — |
| 2025-12-19 | $222.29 | $243.71 | $221.00 | $237.61 | 10,925,000 | — | 7.43% | $34.93B | — | — |
| 2025-12-18 | $222.74 | $231.00 | $214.00 | $219.46 | 9,924,100 | — | 6.75% | $32.26B | — | — |
| 2025-12-17 | $215.99 | $221.99 | $205.52 | $206.83 | 8,232,300 | — | 5.60% | $30.40B | — | — |
| 2025-12-16 | $201.13 | $210.50 | $199.50 | $209.31 | 6,638,400 | — | 4.52% | $30.77B | — | — |
| 2025-12-15 | $214.45 | $217.00 | $200.34 | $201.87 | 6,265,000 | — | 4.26% | $29.67B | — | — |
| 2025-12-12 | $232.11 | $236.00 | $204.80 | $206.18 | 12,083,200 | — | 8.22% | $30.31B | — | — |
| 2025-12-11 | $230.00 | $244.19 | $217.67 | $241.61 | 7,622,500 | — | 5.19% | $35.52B | — | — |
| 2025-12-10 | $218.00 | $234.17 | $215.20 | $232.86 | 6,090,400 | — | 4.14% | $34.23B | — | — |
| 2025-12-09 | $222.27 | $224.33 | $213.50 | $219.46 | 6,299,000 | — | 4.29% | $32.26B | — | — |
| 2025-12-08 | $235.66 | $238.86 | $215.60 | $225.47 | 8,710,000 | — | 5.93% | $33.14B | — | — |
| 2025-12-05 | $212.40 | $229.45 | $211.25 | $228.47 | 8,451,300 | — | 5.75% | $33.59B | — | — |
| 2025-12-04 | $192.32 | $214.99 | $189.68 | $213.31 | 12,166,500 | — | 8.28% | $31.36B | — | — |
| 2025-12-03 | $196.70 | $199.18 | $187.70 | $194.38 | 9,868,200 | — | 6.71% | $28.57B | — | — |
| 2025-12-02 | $211.75 | $217.00 | $192.80 | $205.35 | 11,095,800 | — | 7.55% | $30.19B | — | — |
| 2025-12-01 | $211.84 | $215.30 | $205.24 | $210.17 | 10,280,900 | — | 6.99% | $30.89B | — | — |
| 2025-11-28 | $225.25 | $237.77 | $211.73 | $223.28 | 13,367,500 | — | 9.09% | $32.82B | — | — |
| 2025-11-26 | $226.00 | $228.00 | $205.40 | $215.04 | 43,000,900 | — | 29.25% | $31.61B | — | — |
| 2025-11-25 | $228.40 | $229.07 | $209.00 | $220.50 | 14,680,600 | — | 9.99% | $32.41B | — | — |
| 2025-11-24 | $206.05 | $228.18 | $205.13 | $226.96 | 13,798,900 | — | 9.39% | $33.36B | — | — |
| 2025-11-21 | $205.37 | $205.50 | $183.00 | $200.27 | 20,061,000 | — | 13.65% | $29.44B | — | — |
| 2025-11-20 | $252.17 | $254.60 | $192.62 | $195.96 | 26,590,900 | — | 18.09% | $28.81B | — | — |
| 2025-11-19 | $251.11 | $256.98 | $233.79 | $245.96 | 12,005,800 | — | 8.17% | $36.16B | — | — |
| 2025-11-18 | $257.15 | $260.63 | $229.11 | $244.93 | 16,433,900 | — | 11.18% | $36.00B | — | — |
| 2025-11-17 | $253.40 | $282.80 | $253.00 | $265.88 | 14,211,500 | — | 9.67% | $39.08B | — | — |
| 2025-11-14 | $236.00 | $270.49 | $235.05 | $254.16 | 19,464,400 | — | 13.24% | $37.36B | — | — |
| 2025-11-13 | $268.00 | $271.84 | $234.13 | $243.57 | 23,274,900 | — | 15.83% | $35.80B | — | — |
| 2025-11-12 | $271.58 | $284.76 | $267.05 | $283.10 | 13,730,300 | — | 9.34% | $41.62B | — | — |
| 2025-11-11 | $262.29 | $275.87 | $255.87 | $271.58 | 12,180,900 | — | 8.29% | $39.92B | — | — |
| 2025-11-10 | $247.00 | $270.91 | $247.00 | $267.95 | 15,276,400 | — | 10.39% | $39.39B | — | — |
| 2025-11-07 | $208.42 | $240.00 | $203.40 | $239.48 | 20,552,100 | — | 13.98% | $35.20B | — | — |
| 2025-11-06 | $212.00 | $226.50 | $205.18 | $207.69 | 10,402,700 | — | 7.08% | $30.53B | — | — |
| 2025-11-05 | $201.88 | $218.94 | $201.87 | $216.50 | 10,336,300 | — | 7.03% | $31.83B | — | — |
| 2025-11-04 | $188.13 | $202.98 | $185.00 | $194.57 | 9,800,800 | — | 6.67% | $28.60B | — | — |
| 2025-11-03 | $210.85 | $213.40 | $189.10 | $207.01 | 10,626,000 | — | 7.23% | $30.43B | — | — |
| 2025-10-31 | $203.50 | $209.77 | $189.58 | $199.33 | 6,920,700 | — | 4.71% | $29.30B | — | — |
| 2025-10-30 | $192.02 | $204.92 | $191.09 | $195.82 | 7,341,500 | — | 4.99% | $28.79B | — | — |
| 2025-10-29 | $186.67 | $205.64 | $181.51 | $204.36 | 9,365,000 | — | 6.37% | $30.04B | — | — |
| 2025-10-28 | $175.49 | $178.82 | $164.56 | $175.53 | 9,140,800 | — | 6.22% | $25.80B | — | — |
| 2025-10-27 | $191.50 | $191.85 | $173.72 | $176.49 | 11,235,500 | — | 7.64% | $25.94B | — | — |
| 2025-10-24 | $174.40 | $187.36 | $173.50 | $186.16 | 10,653,100 | — | 7.25% | $27.37B | — | — |
| 2025-10-23 | $146.99 | $167.95 | $146.00 | $167.05 | 9,011,400 | — | 6.13% | $24.56B | — | — |
| 2025-10-22 | $149.10 | $157.40 | $144.82 | $146.95 | 7,516,800 | — | 5.11% | $21.60B | — | — |
| 2025-10-21 | $145.80 | $150.16 | $142.76 | $149.29 | 4,177,900 | — | 2.84% | $21.95B | — | — |
| 2025-10-20 | $145.98 | $152.63 | $145.50 | $148.04 | 6,626,100 | — | 4.51% | $21.76B | — | — |
| 2025-10-17 | $139.22 | $150.82 | $136.29 | $140.16 | 8,279,800 | — | 5.63% | $20.60B | — | — |
| 2025-10-16 | $146.00 | $149.09 | $141.70 | $144.27 | 6,289,600 | — | 4.28% | $21.21B | — | — |
| 2025-10-15 | $134.75 | $144.55 | $130.50 | $144.30 | 8,971,100 | — | 6.10% | $21.21B | — | — |
| 2025-10-14 | $123.59 | $130.48 | $120.96 | $127.29 | 7,078,600 | — | 4.82% | $18.71B | — | — |
| 2025-10-13 | $129.74 | $135.91 | $124.05 | $134.61 | 8,297,300 | — | 5.64% | $19.79B | — | — |
| 2025-10-10 | $131.46 | $132.00 | $116.17 | $116.91 | 7,860,200 | — | 5.35% | $17.19B | — | — |
| 2025-10-09 | $127.00 | $131.60 | $126.12 | $129.68 | 3,561,500 | — | 2.42% | $19.06B | — | — |
| 2025-10-08 | $121.50 | $132.28 | $120.20 | $131.88 | 7,173,400 | — | 4.88% | $19.39B | — | — |
| 2025-10-07 | $125.20 | $125.20 | $115.68 | $120.95 | 6,594,600 | — | 4.49% | $17.78B | — | — |
| 2025-10-06 | $133.60 | $134.79 | $119.29 | $121.17 | 9,963,900 | — | 6.78% | $17.81B | — | — |
| 2025-10-03 | $128.29 | $137.05 | $126.70 | $128.41 | 10,193,700 | — | 6.93% | $18.88B | — | — |
| 2025-10-02 | $128.69 | $132.29 | $123.26 | $124.14 | 9,453,400 | — | 6.43% | $18.25B | — | — |
| 2025-10-01 | $113.06 | $123.85 | $112.00 | $121.12 | 12,237,400 | — | 8.32% | $17.80B | — | — |
| 2025-09-30 | $114.10 | $120.74 | $112.11 | $112.20 | 11,414,800 | — | 7.77% | $16.49B | — | — |
| 2025-09-29 | $104.25 | $114.00 | $103.35 | $113.50 | 12,435,400 | — | 8.52% | $16.57B | — | — |
| 2025-09-26 | $96.00 | $99.65 | $94.39 | $97.12 | 6,418,000 | — | 4.40% | $14.18B | — | — |
| 2025-09-25 | $96.26 | $100.45 | $93.54 | $94.29 | 10,569,300 | — | 7.24% | $13.77B | — | — |
| 2025-09-24 | $103.56 | $107.72 | $96.63 | $99.83 | 12,409,300 | — | 8.50% | $14.58B | — | — |
| 2025-09-23 | $105.00 | $110.21 | $104.70 | $106.40 | 7,835,000 | — | 5.37% | $15.53B | — | — |
| 2025-09-22 | $105.76 | $108.80 | $101.59 | $102.92 | 7,692,200 | — | 5.27% | $15.03B | — | — |
| 2025-09-19 | $98.00 | $102.99 | $96.71 | $102.21 | 6,459,900 | — | 4.42% | $14.92B | — | — |
| 2025-09-18 | $97.30 | $102.93 | $96.86 | $98.87 | 9,441,900 | — | 6.47% | $14.44B | — | — |
| 2025-09-17 | $90.78 | $94.81 | $90.22 | $93.97 | 7,031,000 | — | 4.82% | $13.72B | — | — |
| 2025-09-16 | $90.31 | $93.13 | $89.56 | $91.55 | 6,292,100 | — | 4.31% | $13.37B | — | — |
| 2025-09-15 | $85.30 | $92.06 | $85.12 | $90.09 | 8,981,300 | — | 6.15% | $13.15B | — | — |
| 2025-09-12 | $85.31 | $86.96 | $82.28 | $86.13 | 5,641,700 | — | 3.86% | $12.57B | — | — |
| 2025-09-11 | $82.30 | $85.89 | $81.38 | $84.30 | 10,167,400 | — | 6.96% | $12.31B | — | — |
| 2025-09-10 | $72.42 | $74.49 | $72.03 | $73.92 | 4,053,000 | — | 2.78% | $10.79B | — | — |
| 2025-09-09 | $70.26 | $71.40 | $69.57 | $70.51 | 3,364,300 | — | 2.30% | $10.29B | — | — |
| 2025-09-08 | $68.65 | $71.00 | $67.86 | $70.50 | 5,869,100 | — | 4.02% | $10.29B | — | — |
| 2025-09-05 | $65.52 | $68.67 | $63.74 | $68.55 | 9,050,000 | — | 6.20% | $10.01B | — | — |
| 2025-09-04 | $55.67 | $62.65 | $55.55 | $62.50 | 10,189,000 | — | 6.98% | $9.12B | — | — |
| 2025-09-03 | $51.92 | $53.22 | $50.65 | $53.01 | 1,689,700 | — | 1.16% | $7.74B | — | — |
| 2025-09-02 | $51.01 | $51.70 | $50.07 | $51.07 | 2,023,400 | — | 1.39% | $7.46B | — | — |
| 2025-08-29 | $51.15 | $52.94 | $50.82 | $52.47 | 4,228,000 | — | 2.90% | $7.66B | — | — |
| 2025-08-28 | $48.56 | $51.23 | $48.56 | $50.87 | 2,919,400 | — | 2.00% | $7.43B | — | — |
| 2025-08-27 | $47.40 | $49.08 | $47.40 | $48.44 | 2,145,100 | — | 1.47% | $7.07B | — | — |
| 2025-08-26 | $46.75 | $48.21 | $46.75 | $47.35 | 2,577,800 | — | 1.77% | $6.91B | — | — |
| 2025-08-25 | $46.36 | $46.88 | $46.01 | $46.78 | 1,318,100 | — | 0.90% | $6.83B | — | — |
| 2025-08-22 | $46.11 | $47.19 | $45.63 | $46.37 | 2,208,300 | — | 1.51% | $6.77B | — | — |
| 2025-08-21 | $43.87 | $45.60 | $43.56 | $45.50 | 1,802,300 | — | 1.23% | $6.64B | — | — |
| 2025-08-20 | $44.86 | $45.00 | $43.20 | $44.40 | 1,526,800 | — | 1.05% | $6.48B | — | — |
| 2025-08-19 | $46.23 | $46.50 | $44.26 | $44.58 | 2,372,900 | — | 1.63% | $6.51B | — | — |
| 2025-08-18 | $44.25 | $45.87 | $44.25 | $45.52 | 2,541,700 | — | 1.74% | $6.65B | — | — |
| 2025-08-15 | $43.06 | $46.13 | $42.82 | $44.54 | 7,519,200 | — | 5.15% | $6.50B | — | — |
| 2025-08-14 | $46.43 | $47.26 | $46.08 | $46.68 | 3,549,300 | — | 2.43% | $6.82B | — | — |
| 2025-08-13 | $47.02 | $48.46 | $46.80 | $47.01 | 2,348,500 | — | 1.61% | $6.86B | — | — |
| 2025-08-12 | $45.21 | $47.86 | $45.00 | $46.83 | 3,204,500 | — | 2.19% | $6.84B | — | — |
| 2025-08-11 | $45.70 | $46.35 | $43.17 | $43.37 | 3,095,000 | — | 2.12% | $6.33B | — | — |
| 2025-08-08 | $41.41 | $44.85 | $41.00 | $44.34 | 3,516,500 | — | 2.41% | $6.47B | — | — |
| 2025-08-07 | $42.00 | $42.35 | $40.53 | $40.69 | 2,207,200 | — | 1.51% | $5.94B | — | — |
| 2025-08-06 | $42.72 | $43.00 | $41.62 | $42.10 | 1,553,800 | — | 1.06% | $6.15B | — | — |
| 2025-08-05 | $42.53 | $43.40 | $41.37 | $41.93 | 1,422,900 | — | 0.97% | $6.12B | — | — |
| 2025-08-04 | $42.11 | $42.54 | $41.60 | $42.51 | 1,540,000 | — | 1.05% | $6.21B | — | — |
| 2025-08-01 | $42.18 | $42.22 | $40.10 | $41.33 | 1,661,800 | — | 1.14% | $6.03B | — | — |
| 2025-07-31 | $43.73 | $44.62 | $42.24 | $42.92 | 1,849,200 | — | 1.27% | $6.27B | — | — |
| 2025-07-30 | $42.07 | $43.47 | $42.07 | $43.39 | 1,334,800 | — | 0.91% | $6.33B | — | — |
| 2025-07-29 | $42.26 | $43.19 | $41.68 | $42.93 | 1,202,600 | — | 0.82% | $6.27B | — | — |
| 2025-07-28 | $43.08 | $43.24 | $41.57 | $41.89 | 851,300 | — | 0.58% | $6.12B | — | — |
| 2025-07-25 | $42.48 | $42.60 | $41.50 | $42.48 | 869,200 | — | 0.60% | $6.20B | — | — |
| 2025-07-24 | $43.08 | $43.50 | $42.03 | $42.06 | 1,347,100 | — | 0.92% | $6.14B | — | — |
| 2025-07-23 | $41.06 | $43.65 | $41.06 | $43.00 | 2,220,800 | — | 1.52% | $6.28B | — | — |
| 2025-07-22 | $41.51 | $41.98 | $40.89 | $41.36 | 1,846,700 | — | 1.26% | $6.04B | — | — |
| 2025-07-21 | $41.73 | $42.28 | $40.55 | $41.61 | 2,174,200 | — | 1.49% | $6.08B | — | — |
| 2025-07-18 | $41.54 | $42.28 | $40.84 | $42.19 | 1,678,600 | — | 1.15% | $6.16B | — | — |
| 2025-07-17 | $41.40 | $42.26 | $41.04 | $41.52 | 2,290,100 | — | 1.57% | $6.06B | — | — |
| 2025-07-16 | $42.76 | $42.96 | $40.30 | $41.36 | 2,338,400 | — | 1.60% | $6.04B | — | — |
| 2025-07-15 | $42.80 | $43.45 | $42.51 | $42.72 | 2,398,200 | — | 1.64% | $6.24B | — | — |
| 2025-07-14 | $44.63 | $44.85 | $41.46 | $42.48 | 5,486,900 | — | 3.76% | $6.20B | — | — |
| 2025-07-11 | $46.29 | $47.42 | $45.83 | $46.09 | 1,242,000 | — | 0.85% | $6.73B | — | — |
| 2025-07-10 | $47.37 | $47.75 | $46.62 | $46.95 | 1,734,300 | — | 1.19% | $6.85B | — | — |
| 2025-07-09 | $46.12 | $47.09 | $45.99 | $46.20 | 1,575,100 | — | 1.08% | $6.75B | — | — |
| 2025-07-08 | $46.12 | $47.25 | $45.61 | $46.17 | 2,347,200 | — | 1.61% | $6.74B | — | — |
| 2025-07-07 | $47.14 | $47.24 | $45.09 | $45.22 | 2,446,100 | — | 1.68% | $6.60B | — | — |
| 2025-07-03 | $46.10 | $47.32 | $45.89 | $46.41 | 1,441,600 | — | 0.99% | $6.78B | — | — |
| 2025-07-02 | $44.52 | $46.24 | $44.17 | $46.21 | 3,509,400 | — | 2.40% | $6.75B | — | — |
| 2025-07-01 | $45.70 | $45.92 | $44.30 | $44.96 | 2,893,400 | — | 1.98% | $6.56B | — | — |
| 2025-06-30 | $47.23 | $47.34 | $45.33 | $45.35 | 3,034,600 | — | 2.08% | $6.62B | — | — |
| 2025-06-27 | $47.23 | $47.74 | $46.19 | $47.15 | 3,624,000 | — | 2.50% | $6.84B | — | — |
| 2025-06-26 | $49.60 | $49.82 | $47.07 | $47.44 | 3,449,600 | — | 2.38% | $6.88B | — | — |
| 2025-06-25 | $47.34 | $48.16 | $47.05 | $47.25 | 2,357,900 | — | 1.63% | $6.85B | — | — |
| 2025-06-24 | $47.18 | $48.75 | $46.71 | $47.34 | 1,740,600 | — | 1.20% | $6.86B | — | — |
| 2025-06-23 | $46.36 | $48.25 | $45.80 | $46.95 | 1,791,600 | — | 1.24% | $6.81B | — | — |
| 2025-06-20 | $46.98 | $48.21 | $44.76 | $46.58 | 4,762,700 | — | 3.28% | $6.75B | — | — |
| 2025-06-18 | $45.00 | $47.43 | $44.86 | $46.62 | 3,351,400 | — | 2.31% | $6.76B | — | — |
| 2025-06-17 | $44.23 | $44.56 | $43.53 | $44.09 | 2,914,900 | — | 2.01% | $6.39B | — | — |
| 2025-06-16 | $43.37 | $44.85 | $42.56 | $44.21 | 2,901,800 | — | 2.00% | $6.41B | — | — |
| 2025-06-13 | $41.00 | $42.83 | $40.78 | $42.50 | 2,755,900 | — | 1.90% | $6.16B | — | — |
| 2025-06-12 | $39.67 | $41.83 | $39.44 | $41.30 | 2,052,000 | — | 1.42% | $5.99B | — | — |
| 2025-06-11 | $42.38 | $43.23 | $39.89 | $40.23 | 3,891,800 | — | 2.68% | $5.83B | — | — |
| 2025-06-10 | $41.79 | $42.66 | $40.75 | $41.59 | 4,056,300 | — | 2.80% | $6.03B | — | — |
| 2025-06-09 | $40.27 | $42.24 | $39.55 | $41.82 | 10,990,300 | — | 7.58% | $6.06B | — | — |
| 2025-06-06 | $39.73 | $40.15 | $38.53 | $39.15 | 10,955,500 | — | 7.56% | $5.68B | — | — |
| 2025-06-05 | $39.38 | $40.45 | $37.33 | $39.12 | 5,456,000 | — | 3.76% | $5.67B | — | — |
| 2025-06-04 | $38.64 | $40.27 | $38.35 | $39.82 | 1,860,500 | — | 1.28% | $5.77B | — | — |
| 2025-06-03 | $37.45 | $39.24 | $36.87 | $38.64 | 1,294,000 | — | 0.89% | $5.60B | — | — |
| 2025-06-02 | $37.54 | $37.88 | $36.21 | $37.33 | 1,621,000 | — | 1.12% | $5.41B | — | — |
| 2025-05-30 | $38.19 | $38.45 | $36.68 | $37.69 | 5,499,600 | — | 3.79% | $5.47B | — | — |
| 2025-05-29 | $39.04 | $39.22 | $37.69 | $38.60 | 1,501,900 | — | 1.04% | $5.60B | — | — |
| 2025-05-28 | $38.40 | $38.91 | $37.80 | $38.58 | 1,055,800 | — | 0.73% | $5.59B | — | — |
| 2025-05-27 | $37.94 | $38.62 | $37.50 | $38.18 | 1,411,000 | — | 0.97% | $5.54B | — | — |
| 2025-05-23 | $36.25 | $37.57 | $35.79 | $37.28 | 1,232,900 | — | 0.85% | $5.41B | — | — |
| 2025-05-22 | $38.40 | $39.28 | $37.77 | $37.84 | 1,764,900 | — | 1.22% | $5.49B | — | — |
| 2025-05-21 | $40.04 | $40.48 | $38.35 | $38.60 | 1,816,200 | — | 1.25% | $5.60B | — | — |
| 2025-05-20 | $38.78 | $41.11 | $38.45 | $40.18 | 1,756,400 | — | 1.21% | $5.83B | — | — |
| 2025-05-19 | $39.33 | $39.50 | $38.53 | $38.78 | 1,765,400 | — | 1.22% | $5.62B | — | — |
| 2025-05-16 | $40.52 | $41.00 | $39.92 | $40.44 | 2,132,500 | — | 1.47% | $5.86B | — | — |
| 2025-05-15 | $41.17 | $41.86 | $39.75 | $40.54 | 1,930,800 | — | 1.33% | $5.88B | — | — |
| 2025-05-14 | $42.00 | $43.43 | $41.01 | $41.93 | 1,828,400 | — | 1.26% | $6.08B | — | — |
| 2025-05-13 | $41.85 | $43.80 | $41.30 | $42.00 | 2,186,700 | — | 1.51% | $6.09B | — | — |
| 2025-05-12 | $41.14 | $42.24 | $40.00 | $41.27 | 5,374,400 | — | 3.71% | $5.98B | — | — |
| 2025-05-09 | $37.96 | $38.79 | $37.28 | $37.74 | 2,039,200 | — | 1.41% | $5.47B | — | — |
| 2025-05-08 | $34.97 | $37.76 | $33.13 | $36.66 | 4,969,000 | — | 3.43% | $5.32B | — | — |
| 2025-05-07 | $34.00 | $35.56 | $33.38 | $34.97 | 3,640,000 | — | 2.51% | $5.07B | — | — |
| 2025-05-06 | $34.02 | $34.43 | $33.46 | $33.83 | 1,707,600 | — | 1.18% | $4.91B | — | — |
| 2025-05-05 | $33.83 | $35.23 | $33.53 | $34.61 | 1,993,800 | — | 1.38% | $5.02B | — | — |
| 2025-05-02 | $33.11 | $35.41 | $33.05 | $34.40 | 2,193,700 | — | 1.51% | $4.99B | — | — |
| 2025-05-01 | $32.48 | $34.19 | $32.48 | $32.59 | 1,910,200 | — | 1.32% | $4.73B | — | — |
| 2025-04-30 | $31.84 | $32.47 | $31.01 | $32.11 | 2,322,100 | — | 1.60% | $4.66B | — | — |
| 2025-04-29 | $31.39 | $33.04 | $31.39 | $32.94 | 1,385,900 | — | 0.96% | $4.78B | — | — |
| 2025-04-28 | $32.63 | $33.00 | $31.66 | $32.27 | 1,421,000 | — | 0.98% | $4.68B | — | — |
| 2025-04-25 | $32.26 | $33.37 | $31.60 | $32.85 | 1,322,100 | — | 0.91% | $4.76B | — | — |
| 2025-04-24 | $30.81 | $32.98 | $30.31 | $32.29 | 2,590,500 | — | 1.79% | $4.68B | — | — |
| 2025-04-23 | $31.99 | $32.78 | $30.20 | $30.36 | 2,750,200 | — | 1.90% | $4.40B | — | — |
| 2025-04-22 | $30.26 | $31.12 | $29.32 | $29.62 | 2,883,700 | — | 1.99% | $4.29B | — | — |
| 2025-04-21 | $31.07 | $31.07 | $28.94 | $29.81 | 2,579,400 | — | 1.78% | $4.32B | — | — |
| 2025-04-17 | $31.75 | $32.66 | $30.39 | $31.29 | 2,057,200 | — | 1.42% | $4.54B | — | — |
| 2025-04-16 | $32.30 | $33.12 | $30.75 | $32.03 | 2,321,000 | — | 1.60% | $4.64B | — | — |
| 2025-04-15 | $33.30 | $34.56 | $32.89 | $33.23 | 1,936,800 | — | 1.34% | $4.82B | — | — |
| 2025-04-14 | $33.75 | $36.17 | $32.48 | $33.55 | 4,102,300 | — | 2.83% | $4.86B | — | — |
| 2025-04-11 | $30.56 | $32.05 | $28.27 | $31.97 | 4,856,000 | — | 3.35% | $4.64B | — | — |
| 2025-04-10 | $34.60 | $35.03 | $30.51 | $31.08 | 4,153,400 | — | 2.86% | $4.51B | — | — |
| 2025-04-09 | $31.92 | $39.65 | $31.26 | $36.58 | 5,601,600 | — | 3.86% | $5.30B | — | — |
| 2025-04-08 | $33.00 | $35.84 | $31.66 | $32.35 | 5,979,600 | — | 4.12% | $4.69B | — | — |
| 2025-04-07 | $29.22 | $32.98 | $27.89 | $31.48 | 6,238,600 | — | 4.30% | $4.56B | — | — |
| 2025-04-04 | $35.72 | $35.87 | $28.36 | $30.11 | 11,428,600 | — | 7.88% | $4.37B | — | — |
| 2025-04-03 | $44.80 | $44.80 | $37.55 | $38.26 | 7,372,000 | — | 5.08% | $5.55B | — | — |
| 2025-04-02 | $46.92 | $48.71 | $46.51 | $47.67 | 1,725,300 | — | 1.19% | $6.91B | — | — |
| 2025-04-01 | $47.55 | $49.36 | $46.58 | $48.11 | 2,115,600 | — | 1.46% | $6.98B | — | — |
| 2025-03-31 | $47.41 | $48.40 | $47.02 | $47.61 | 2,113,400 | — | 1.46% | $6.90B | — | — |
| 2025-03-28 | $52.21 | $52.89 | $48.46 | $48.97 | 3,987,300 | — | — | — | — | — |
| 2025-03-27 | $51.95 | $54.24 | $51.71 | $52.88 | 1,618,100 | — | — | — | — | — |
| 2025-03-26 | $53.53 | $53.70 | $51.98 | $52.62 | 1,242,400 | — | — | — | — | — |
| 2025-03-25 | $52.13 | $53.18 | $51.76 | $52.20 | 3,079,000 | — | — | — | — | — |
| 2025-03-24 | $54.61 | $55.69 | $51.84 | $52.99 | 3,562,800 | — | — | — | — | — |
| 2025-03-21 | $55.10 | $55.45 | $51.92 | $53.96 | 6,372,200 | — | — | — | — | — |
| 2025-03-20 | $56.51 | $57.17 | $54.92 | $56.21 | 2,701,900 | — | — | — | — | — |
| 2025-03-19 | $56.30 | $57.60 | $55.67 | $56.33 | 2,520,700 | — | — | — | — | — |
| 2025-03-18 | $55.14 | $57.89 | $54.57 | $56.42 | 2,587,300 | — | — | — | — | — |
| 2025-03-17 | $54.80 | $58.36 | $54.74 | $55.65 | 2,930,700 | — | — | — | — | — |
| 2025-03-14 | $49.43 | $54.94 | $49.43 | $54.82 | 4,847,600 | — | — | — | — | — |
| 2025-03-13 | $50.00 | $50.87 | $47.86 | $48.44 | 3,547,400 | — | — | — | — | — |
| 2025-03-12 | $53.00 | $53.10 | $50.38 | $50.44 | 2,177,500 | — | — | — | — | — |
| 2025-03-11 | $51.84 | $53.19 | $49.82 | $52.16 | 3,153,400 | — | — | — | — | — |
| 2025-03-10 | $50.49 | $53.67 | $49.55 | $53.00 | 5,223,800 | — | — | — | — | — |
| 2025-03-07 | $49.20 | $51.13 | $47.16 | $51.00 | 7,825,500 | — | — | — | — | — |
| 2025-03-06 | $47.41 | $49.06 | $45.24 | $46.50 | 4,157,300 | — | — | — | — | — |
| 2025-03-05 | $47.60 | $49.40 | $46.50 | $48.47 | 5,071,800 | — | — | — | — | — |
| 2025-03-04 | $46.69 | $50.10 | $45.10 | $48.69 | 6,074,700 | — | — | — | — | — |
| 2025-03-03 | $48.49 | $50.88 | $47.60 | $50.31 | 4,813,000 | — | — | — | — | — |
| 2025-02-28 | $45.23 | $48.70 | $43.75 | $46.85 | 7,713,800 | — | — | — | — | — |
| 2025-02-27 | $46.04 | $47.87 | $41.58 | $45.16 | 9,676,100 | — | — | — | — | — |
| 2025-02-26 | $46.15 | $49.91 | $45.30 | $46.58 | 8,389,000 | — | — | — | — | — |
| 2025-02-25 | $48.30 | $55.01 | $47.81 | $48.16 | 8,198,900 | — | — | — | — | — |
| 2025-02-24 | $52.00 | $53.00 | $46.21 | $48.60 | 33,848,500 | — | — | — | — | — |
Close is split-adjusted to current shares. It is not dividend-adjusted: dividends are listed separately, so total return is (end price + dividends received − start price) ÷ start price, checkable by hand. Volume is as-traded.
Momentum: MACD and RSI
Top: MACD (navy) and its signal line (gold); bars show the gap between them, teal when MACD is above.
Bottom: RSI over 14 days; above 70 is usually read as overbought and below 30 as oversold.
The lines start late because MACD needs 26 trading days of prices and RSI 14 before the first value.
The colored strip under the charts shows the state label day by day; hover for the state and the reason.
Both measure momentum in the price and say nothing about value. Hover for each day's arithmetic.
Source: closing prices from this site's daily price archive (Yahoo Finance), not adjusted for dividends. Data through Nov 14, 2026.
How these are calculated
Short Selling
Bars: shares sold short each day in trades reported to FINRA (off-exchange
trades, roughly half of all volume).
Line: the short share of that volume, averaged over 20 sessions.
Gold points: short interest, the shares sold short and not yet bought back,
reported twice a month, also shown as a percentage of the free float and of
shares outstanding.
Daily short volume includes market makers' routine hedging, so a change in the
share is more informative than its level. Hover for each day's figures.
Sources: FINRA; float from this site's daily share records; shares outstanding
from the company's latest quarterly filing. Data through Nov 13, 2026.
Index-Fund Holdings
Daily positions of State Street's SPDR index funds, by the fund's file date.
These are the index funds whose daily holdings can be collected; iShares and
Vanguard funds, often larger holders, publish holdings that cannot be
collected automatically and appear in the written analysis from their
quarterly filings.
Collection began on October 11, 2026. A fund that drops the stock shows as an
exit.
Source: State Street Global Advisors. Data through
Nov 12, 2026.
Update — November 2, 2026: first-quarter FY2027 results and the 10-Q — SELL → TRIM, target $860 → $807
Rated at the November 2, 2026 close of $1,075.08. The results were released after the October 29, 2026 close of $1,330.05. Sources: the first-quarter FY2027 results release (October 29, 2026), the first-quarter 10-Q (filed October 30, 2026), the conference call (transcript summary; no official transcript was available), Kioxia’s results of October 30, 2026 (report), TrendForce’s NAND spot report of October 28, 2026, analyst actions as collected by StockAnalysis, and FINRA short interest. Peer prices are Yahoo closes. All per-share figures are before the 8-for-1 split, which trades from November 20, 2026; after it, divide by 8 (the target becomes about $101). Earlier sections are left as published.
The one-line version
The quarter beat, and the next one is guided higher, but on volume more than price. Revenue was $11.03 billion against a $10.3–10.8 billion guide, and the second quarter is guided at $12.2–12.6 billion. Management said the first quarter’s 23% growth was about 60% bits and 40% price, and that prices will rise “modestly” from here. The same morning Kioxia guided its own prices for the December 2026 quarter about flat. The October 23, 2026 update named a second-quarter guide implying prices up 10% or more as the test for the best case; it was not met.
The re-struck cases are $1,346, $767 and $389. The quarter’s beat and the buyback raise them; lower FY2027 prices take most of that back. Weighted 20% best, 60% base and 20% worst (from 25 / 55 / 20), they are worth $807, an expected return of −24.9% at $1,075.08, with 17 cents of probability-weighted gain for each dollar of loss. The rating moves from SELL to TRIM because the price fell 19% in two sessions, to just inside the TRIM band; SELL applies again above about $1,076.
What happened since October 23, 2026
| Date | Event | Read |
|---|---|---|
| Oct 26, 2026 | TrendForce: 512Gb TLC wafer spot price −9.2% in one week, to $16.88, about 26% below March 2026 | Spot prices lead contract prices; the fall came from phone-maker discounting in China |
| Oct 27, 2026 | BlackRock’s Schedule 13G/A: 11.1 million shares, 7.7%, at September 30, 2026 | The largest disclosed holding |
| Oct 28–29, 2026 | SK hynix and Samsung results: NAND prices up mid-20s% and high teens in the September 2026 quarter; Samsung expects supply to stay tight into 2028 | Price increases are slowing from the June 2026 quarter’s |
| Oct 29, 2026 | Sandisk’s results, the 8-for-1 split (record November 9, 2026) and the second-quarter guide | Below |
| Oct 30, 2026 | Kioxia guides its December 2026 quarter prices about flat and operating profit about 15% below consensus; Intel blames memory costs for a weak guide | Sandisk −13.5%, the memory group −5% to −8% |
| Oct 30, 2026 | The 10-Q: $88.9 billion of contracted revenue still to be delivered, $10.5 billion of buyback authorization left | Below |
| Oct 30, 2026 | Price targets cut, ratings held: Goldman $2,200 → $2,000, BofA $2,500 → $2,000, Wells Fargo $1,550 → $1,300 (Equal Weight), RBC $1,600 → $1,400 (Sector Perform) | Mostly lower multiples on “late-cycle” earnings |
| Nov 2, 2026 | Sandisk −6.6% to $1,075.08 | In line with the group: Micron −5.8%, Western Digital −7.5%, Seagate −7.9% |
The quarter against the tests
The October 23, 2026 update set out what the results had to show. Each test, with the result:
| Test | Base case needed | Result | |
|---|---|---|---|
| First-quarter revenue and gross margin against the guide | At or above the midpoint ($10.55 billion; 84%) | $11.03 billion and 85.1%, above the top of both ranges | Passed |
| The second-quarter guide | Revenue up 10% or more on the first quarter | Midpoint $12.4 billion, +12.4%; “modest like-for-like price increases” | Passed for the base case; the best case’s test (prices up 10% or more) failed |
| Bits sold and inventory days | Inventory days flat | Bits up an estimated 13% on the 60 / 40 split; days in inventory 166 for the quarter against 178 for FY2026 (same definition, different periods); inventory up 12% in dollars against revenue up 23% | Passed |
| The contracts | More than half of FY2027 bits; no renegotiation | “About 50%” of FY2027 bits and two-thirds of FY2028; no renegotiation; no new contract beyond the two already announced | Borderline |
| The buyback | Stated | $5.0 billion for 3.15 million shares, at $1,551 in August and $1,638 in September 2026; $10.5 billion left | Stated, at about twice the target |
| Capital spending and Kitakami Fab3 | Output no earlier than FY2029 | Spending to rise to a mid-single-digit share of FY2027 revenue (first quarter 3.4%); Fab3 not discussed; Kioxia has said it operates from its FY2029 | Passed |
| Datacenter | Growing on bits, separate from price | Datacenter revenue $4.80 billion, +61% on the quarter; management expects datacenter bit demand up about 40% in calendar 2027 | Passed; no split of bits and price |
What management said on the call
- Prices and bits. First-quarter growth was about 60% bits and 40% price. Prices are to “continue to increase modestly throughout the year”. The third quarter is “normally our weakest sequential quarter” (bits fell 19% in it last year), and the finance chief asked analysts to be conservative about it.
- The contracts. About 50% of FY2027 bits and about two-thirds of FY2028 bits are under the long-term agreements; the first quarter closed two, both announced before. One of the largest customers has signed a second tranche and others are “coming back for a second round”. The pipeline “exceeds our supply through the end of the decade”. No change was given to the $93.9 billion minimum or the eight customers.
- The guarantees. 95% of the counterparties are investment grade, and most of the security is held by third-party banks, off the balance sheet. The 10-Q puts the collateral at $12.8 billion at October 2, 2026, against $5.0 billion cited on October 23, 2026 from earlier disclosures.
- Supply. Bit growth stays at mid-to-high teens, with no acceleration of node transitions; the contracts would let Sandisk change supply “eventually”, but “we’re just not there yet”.
- Capital return. 100% of excess cash goes back to shareholders; the board will add authorization as needed.
Why the stock fell 19% in two sessions
| Oct 29 → Oct 30, 2026 | Oct 30 → Nov 2, 2026 | Two sessions | |
|---|---|---|---|
| Sandisk | −13.5% | −6.6% | −19.2% |
| Micron | −5.3% | −5.8% | −10.8% |
| Western Digital | −7.4% | −7.5% | −14.4% |
| Seagate | −8.0% | −7.9% | −15.2% |
| Semiconductors (SOXX) | −8.2% | −3.8% | −11.7% |
About half of the two-day fall was the group. The rest came on October 30, 2026, the day after the results:
- The guide graded as in line, not a beat. The second-quarter revenue midpoint was 0.7–0.9% above the average estimate and 0.8% below Mizuho’s; earnings per share at the midpoint were 2–4% above.
- Price growth is slowing at every maker at once. Sandisk’s “modest” increases, Kioxia’s flat guide and the spot fall all point the same way. Sandisk’s price per bit rose an estimated 8–9% in the first quarter by the 60 / 40 split, against Kioxia’s mid-20s% and SK hynix’s mid-20s%.
- Analysts cut multiples, not estimates. Wells Fargo wrote that the shares need to digest “a slowing pace of earnings upside”; BofA cut its target on “late-cycle valuations”.
The model’s base case already assumed prices peak in FY2027 and halve by FY2029, so the fall moves the price toward the base case rather than changing it. What it does change is the best case: its FY2027 prices assumed the increases would continue at the pace of the June 2026 quarter.
The scenarios and the asymmetry, re-struck
What changed in the model.
- Anchored to the first quarter’s actual results instead of its guide. Revenue of $11.03 billion and an 85.1% gross margin reproduce $49.55 of earnings a share against the reported $49.51, and $56.86 at the second-quarter guide’s midpoints against the guided $55–57.
- Balance sheet at October 2, 2026. Net cash after customer deposits, prepayments and tax due is $2.85 billion (from $2.51 billion), and shares are 142.3 million plus 6.6 million unvested awards (from 146.4 million plus 6.6 million). Because the first quarter’s cash is now in the balance sheet, only the rest of FY2027 is valued.
- FY2027 prices lowered. Against the first quarter, FY2027’s average price is now 7% higher in the best case (was 20%), 5% in the base (was 12%) and 2% lower in the worst (was flat). The later years keep their shape. These are judgements; the call, Kioxia’s guide and the spot fall are the evidence.
| Case | What it assumes | FY2027 / FY2028 EPS | Value | vs $1,075.08 |
|---|---|---|---|---|
| Best | Management’s FY2028–30 model: revenue grows with bits at about an 80%+ gross margin; prices 7% above the first quarter’s in FY2027, 12% in FY2028, then easing; a fade to a 60% mid-cycle margin | $232 / $279 | $1,346 | +25% |
| Base | An ordinary memory cycle: prices 5% above the first quarter’s in FY2027, then about halved by FY2029 as new capacity arrives; the contracts honoured; a 42% mid-cycle margin | $226 / $198 | $767 | −29% |
| Worst | A fast reversion like 2019 or 2023: prices turning down within FY2027 and back near FY2025 levels by FY2029; customers pay half the floor premium; a 28% mid-cycle margin | $209 / $107 | $389 | −64% |
The price paths, the mid-cycle margins and the 11% discount rate are judgements. All values are estimates from the model.
From the October 23, 2026 target to this one (estimates, on the old weights until the last line):
| Step | Value | Change |
|---|---|---|
| October 23, 2026, at 25 / 55 / 20 | $857 | |
| + First-quarter revenue and margin | $893 | + ~$36 |
| + Fewer shares after the buyback | $917 | + ~$25 |
| + Net cash, stock compensation and the valuation date | $919 | + ~$2 |
| − The first quarter’s cash counted in net cash, not again in FY2027 | $871 | − ~$48 |
| − Lower FY2027 prices | $836 | − ~$35 |
| − Weights 20 / 60 / 20 | $807 | − ~$29 |
Stress tests, one change at a time on the base case (estimates):
| Change | Value | vs $1,075.08 |
|---|---|---|
| Prices hold through FY2029, then fall | $995 | −7% |
| Between base and best: the floors hold, prices fall 30%, a 50% mid-cycle margin | $942 | −12% |
| Prices hold at the FY2027 level through FY2028, then fall | $878 | −18% |
| Bit growth 17% a year instead of 13% | $843 | −22% |
| A 50% mid-cycle margin instead of 42% | $831 | −23% |
| Discount rate 9% instead of 11% | $820 | −24% |
| Customers pay only half the floor premium | $762 | −29% |
| No contract floors at all | $757 | −30% |
| Capital spending 6% of revenue instead of 4% | $745 | −31% |
| Cost per bit falling 12% a year instead of 9% | $739 | −31% |
| Discount rate 13% | $727 | −32% |
| A 35% mid-cycle margin | $724 | −33% |
| Between base and worst: prices down 60% by FY2029, half the floors paid, a 35% margin | $554 | −48% |
The price is close to a base case delayed by two years: prices that hold through FY2029 before falling give $995, 7% below the price. Each year the decline is delayed adds about $110 a share.
Three weightings, and what the price implies.
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $817 | −24.0% | 0.21 to 1 |
| Best guess: 20 / 60 / 20 | $807 | −24.9% | 0.17 to 1 |
| Stress: 10 / 40 / 50 | $636 | −40.9% | 0.06 to 1 |
| What the price implies: 53 / 47 / 0 | $1,075 | 0% | 1.0 to 1 |
The weights are a judgement. All values are estimates from the model.
Why the best guess moved from 25 / 55 / 20:
- The best case drops to 20%. It needed prices to keep rising at about the June 2026 quarter’s pace, and the test the October 23, 2026 update set for it, a second-quarter guide implying prices up 10% or more, was not met. It keeps 20% because supply is tight at every maker into 2028, contracts cover two-thirds of FY2028’s bits, and the large new fabs (Micron’s in Singapore, Kitakami Fab3, Samsung’s P5) produce only from 2028–29.
- The base case rises to 60%. Its shape, a peak in FY2027 and a fall as that capacity arrives, is what the makers' own statements and TrendForce’s expectation of a balanced market in the second half of 2027 describe.
- The worst case stays at 20%. None of its tests was triggered: prices are still rising, inventory days fell, and no customer has renegotiated. It stays above zero because these contracts have not been through a downturn, and in the four downturns since 2008 flash prices fell by about half within two to five quarters.
- Evidence that would move the weights at the next results: like-for-like prices up again and a third quarter that holds its bits (best case up); prices flat or down, inventory days rising, or a customer seeking new terms (worst case up). TrendForce’s first-quarter 2027 contract forecast, due in late December 2026, comes first.
What the price implies. At the 60% base weight the price is above every mix of the best and base cases, so the worst case is set to zero and the price solves
best weight × $1,345.98 + (100% − best weight) × $767.06 = $1,075.08
for a best weight of ($1,075.08 − $767.06) ÷ ($1,345.98 − $767.06) = 53%, against 78% at the October 22, 2026 close.
The asymmetry on the best guess:
| Measure | At $1,075.08 | What it means |
|---|---|---|
| Expected return (header chip) | −24.9% | The probability-weighted value, $807.16, against the price |
| Gain to loss (header chip) | 0.17 to 1 | +$54.18 of probability-weighted gain against −$322.10 of loss |
| Expected base-case gain ÷ expected worst-case loss | 0 to 1 | The base case is itself a loss of $308.02 |
| Best-case gain ÷ worst-case loss | 0.39 to 1 | +$270.90 against −$686.43 |
| Base-case gain ÷ worst-case loss | −0.45 to 1 | −$308.02 against −$686.43 |
How the measures are calculated. Gain = case value − price; loss = price − case value. Weights are the best guess: 20% best, 60% base, 20% worst.
| Measure | Formula | At $1,075.08 |
|---|---|---|
| Expected return | (20% × best + 60% × base + 20% × worst) ÷ price − 1 | ($269.20 + $460.24 + $77.73) ÷ $1,075.08 − 1 = −24.9% |
| Gain to loss | (20% × best gain) ÷ (60% × base loss + 20% × worst loss) | $54.18 ÷ ($184.81 + $137.29) = 0.17 |
| Expected base ÷ expected worst | (60% × base gain) ÷ (20% × worst loss) | $0 ÷ $137.29 = 0 |
| Best ÷ worst | best gain ÷ worst loss | $270.90 ÷ $686.43 = 0.39 |
| Base ÷ worst | base gain ÷ worst loss | −$308.02 ÷ $686.43 = −0.45 |
| Price-implied best weight, worst at zero | (price − base) ÷ (best − base) | $308.02 ÷ $578.92 = 53% |
The header chips are green at +25% or more and 3 to 1 or better, blue at +10–25% and 2–3 to 1, orange at 0–10% and 1–2 to 1, and red below zero and below 1 to 1. On the best guess, expected return is green below $646, blue up to $734 and orange up to $807; gain to loss is green below $688, blue up to $737 and orange up to $807. Both are red above $807, and so both are red at $1,075.08.
Short interest and who is trading
Short interest kept falling: 4.70 million shares on October 15, 2026 (3.2% of the shares outstanding), from 4.82 million on September 30, 2026, about half a day of average volume. The October 31, 2026 figure is due about November 10, 2026. Short sellers did not drive the fall in October 2026: short interest fell during it. The only insider filing since October 23, 2026 is a tax withholding; BlackRock’s 7.7% at September 30, 2026 is the largest disclosed holding.
Notes on earlier sections
Clarification: the weights. The October 23, 2026 update marked its 25 / 55 / 20 weights and its SELL rating “(proposed)”. The weights above, 20 / 60 / 20, are set; the October 23, 2026 text is left as published. A clarification.
Change: the collateral. The October 23, 2026 update cited $5.0 billion of collateral behind the contracts. The 10-Q gives $12.8 billion at October 2, 2026, and management cited $16.5 billion of financial guarantees in August 2026. A business change, from new contracts and later disclosure; no earlier figure is corrected.
What it means for the rating
SELL → TRIM, target $860 → $807. The target is the best-guess value, $807.16. At $1,075.08 the expected return is −24.9%, inside the TRIM band (−10% to −25%) by $1; SELL applies above about $1,076, and a single up day would return it there. It is TRIM rather than HOLD because the price still needs 53% on management’s plan, more than the evidence supports after a guide that failed the best case’s own test. It is not SELL because the fall has taken the price to the edge of the band, and the next two quarters are still likely to be the best in Sandisk’s history.
| Action | Level | Reason |
|---|---|---|
| Buy | Below about $646 | Both chips green: expected return above 25% and gain to loss above 3 to 1 |
| Accumulate | $646–734 | Expected return 10–25% |
| Hold | $734–897 | Expected return −10% to +10% |
| Trim | $897–1,076 | Expected return −10% to −25% |
| Sell | Above about $1,076 | Expected return below −25% |
| Move toward HOLD | Like-for-like prices rising again in the second quarter, a third quarter that holds its bits, or contracts extended into FY2030–31 | |
| Move toward SELL | Prices flat or falling, inventory days rising, or a customer seeking new contract terms |
What the second-quarter results (about late January 2027) must show:
| Item | Why it matters | Base case needs |
|---|---|---|
| Revenue and gross margin against the guide ($12.2–12.6 billion; 84.5–85.5%) | The base case assumes FY2027 prices 5% above the first quarter’s | At or above the midpoint |
| The price per bit, like for like | The best case needs increases to continue; the base case needs them to stop by mid-2027 | Up modestly, as guided |
| The third-quarter guide | Management warned it is the weakest quarter; bits fell 19% in it last year | Revenue down no more than about 10% |
| Inventory days (166 in the first quarter) | Rising inventory with slowing prices is how a cycle turns | Flat or lower |
| The contracts | The floors are the main protection in the worst case | No renegotiation; any new tranche dated beyond FY2028 |
| The buyback | At prices above the target it reduces value per share | Pace and average price stated |
| TrendForce’s first-quarter 2027 forecast (late December 2026) | The first independent read on 2027 contract prices | No decline |
Update — October 23, 2026: the scenarios, the money, the contracts and who is trading — SELL, target none → $860
Written against the October 22, 2026 close of $1,260.93. Sources: the FY2026 10-K (filed August 17, 2026), the fourth-quarter FY2026 results release with the first-quarter FY2027 guidance (August 5, 2026), the revolver amendment (September 11, 2026), Sandisk’s Forms 4 and Schedule 13G filings, FINRA short interest, the Q4 call transcript, a summary of the September 9, 2026 Goldman Sachs conference remarks, TrendForce’s NAND price forecasts, and the Kioxia–Sandisk investment announcement (August 27, 2026). Peer prices are Yahoo closes; Sandisk’s prices and volumes are from this site’s own archive. The August 25 analysis below is left as published. It gave no price target because the earnings base could not be sized; this section sizes it with three cases built on the price of a bit of flash, and with the long-term customer contracts that the August analysis did not cover. First-quarter FY2027 results are due Thursday, October 29, 2026, after the close, and the section ends with what they must show.
The one-line version
Sandisk is priced for prices to stay near today’s for about four years. The three cases are worth $1,399 (management’s plan), $774 (an ordinary memory cycle) and $407 (a fast reversion). Weighted 25% best, 55% base and 20% worst (proposed), they are worth $857, an expected return of −32%, with 8 cents of probability-weighted gain for each dollar of loss. The price equals 78% weight on the best case with nothing on the worst.
The near term is strong. Q1 FY2027 is guided at $10.3–10.8 billion of revenue and $44–46 of earnings a share, about 7 times annualised earnings, and TrendForce expects NAND contract prices to rise another 15–20% in the fourth quarter of 2026. What decides the value is what happens after 2027: TrendForce expects supply to catch up in 2027, and Kioxia and Sandisk themselves announced more than $31 billion of new fab investment in August.
The contracts are new and matter less than they seem. Eight customers have committed a minimum of $93.9 billion, with prices that management says protect about an 80% gross margin. In the base case market prices stay above the floors until FY2029, so the floors move the base value by only about $16; they protect the worst case more.
There is no debt; the obligations that stand in its place are the Flash Ventures commitments ($6.6 billion) and a DRAM purchase commitment to Nanya ($5.9 billion). Since September 22 the stock fell 33% with the memory group (−27%): no company news, no index selling. One data correction: the August analysis tied the +26% day of July 30, 2026 to the FY2026 results, which came on August 5.
What happened since August 25
| Date | What happened | Stock that day | Read |
|---|---|---|---|
| Aug 27 | Kioxia and Sandisk announce more than $31 billion (about ¥5 trillion) of investment at Yokkaichi and Kitakami through 2032, subject to government support | −1.0% | The capacity response that ends a pricing cycle, announced by the company itself. News reports put the new Kitakami fab’s output at about FY2029 |
| Aug 31 | Joins the MSCI World Index at the close (MSCI’s August review) | +5.5% | 23.4 million shares, the heaviest day since the analysis: index buying |
| Sep 4 | The memory group rallies; after the close S&P Dow Jones Indices announces Sandisk’s addition to the S&P 100 from September 21 | +11.9% | The move came before the announcement; Western Digital rose 5.9% the same day |
| Sep 9 | CEO and CFO at the Goldman Sachs conference: contracts cover about two-thirds of FY2028 bits, with “price floors that protect contracted business at about 80% gross margins”; mid-teens supply growth over 12–18 months; 100% of free cash flow to buybacks | +1.5% | The fullest description of the contracts so far (transcript summary) |
| Sep 14 and 17 | CEO David Goeckeler sells 67,679 shares under his May 29 trading plan, at an average of $1,551 (about $105 million) | −5.0%, +6.2% | About 55% of the plan’s 124,192-share maximum |
| Sep 18 | S&P 100 addition and quarterly rebalance at the close; options expiry | +11.0% | 17.8 million shares |
| Sep 22 | Rosenblatt starts at Buy, $2,400 (report): NAND becoming “system-critical” for AI; closing high since the analysis, $1,887.04 | +6.8% | The peak came one session after the S&P 100 addition took effect |
| Sep 30 | TrendForce forecasts fourth-quarter NAND contract prices up 15–20%, enterprise SSDs fastest; Micron reports after the close: more than 75% of its 2027 output committed, and supply “much tighter” in 2027 and 2028 (call highlights) | +0.6% | Prices still rising, but client and mobile demand soft |
| Oct 12 | Memory sell-off after a Chinese DRAM maker, CXMT, reported progress on a denser memory cell and an AI datacenter product (report) | −6.0% | DRAM news; Sandisk sells no DRAM |
| Oct 16 | No company news | −6.8% | The week ended −18% |
| Oct 22 | Memory sell-off; Western Digital reports after the close | −8.5% | Micron −6.3%, Western Digital −6.4% on the day |
How the money moves
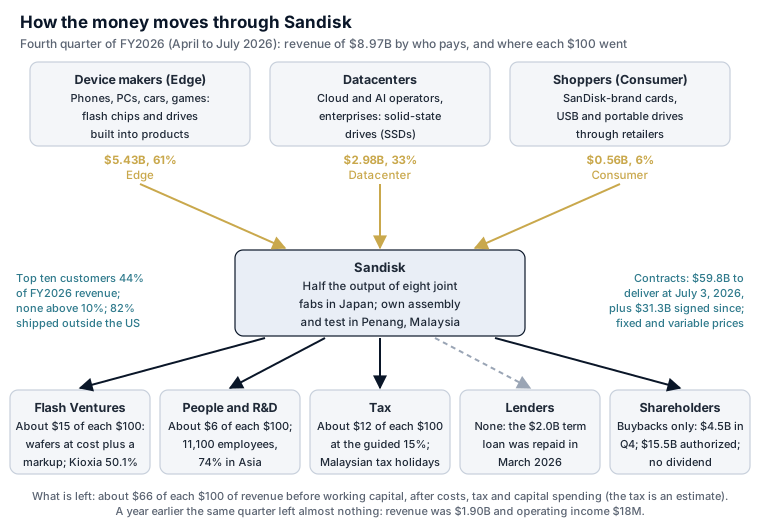
Who pays:
- Device makers, 61% of fourth-quarter revenue (Edge, $5.43 billion): flash for phones, PCs, cars and games. Its FY2026 growth came almost entirely from price.
- Datacenters, 33% ($2.98 billion, up from $0.27 billion five quarters earlier): solid-state drives for cloud and AI operators and enterprises, the one business that grew on volume (about 120% more exabytes in FY2026).
- Shoppers, 6% (Consumer, $0.56 billion): SanDisk-brand cards and drives through retailers.
- No customer is 10% of revenue; the ten largest were 44% in FY2026. 82% is shipped outside the United States, 48% to China and Hong Kong (where device makers’ factories are).
- Eight customers have signed long-term contracts (management calls them its “new business model”): they commit a stated volume over several years, at prices with fixed and variable parts, backed by deposits and guarantees. The 10-K counts $59.8 billion still to be delivered at July 3, 2026, 19% of it within twelve months, plus two contracts of $31.3 billion signed after the year-end. Management puts the total at a minimum of $93.9 billion at floor prices, more than half of FY2027’s bits and about two-thirds of FY2028’s.
Where each $100 of revenue went, fourth quarter of FY2026 (April 4 to July 3, 2026, as reported, with tax at the guided rate). About $66 of each $100 of revenue was left after costs, tax at the guided 15% and capital spending, before working capital. A year earlier the same quarter’s revenue was $1,901M and its operating income $18M; the change is almost all price. In the quarter, receivables grew with revenue and took about $25 of each $100, and customer deposits and prepayments under the long-term contracts returned about $23. Sandisk’s own free cash flow was $7,083M ($79 of each $100), helped by tax not yet paid; its adjusted free cash flow, which leaves out the deposits and prepayments and counts Flash Ventures, was $5,035M ($56). Source: the fourth-quarter FY2026 results release (statements of operations and cash flows); per-$100 figures are calculations.
About $66 of each $100 of revenue was left in the fourth quarter after costs, tax and capital spending, before working capital (the tax is an estimate at the guided 15%). The cost of a wafer barely moves with its selling price, so almost all of a price change reaches profit: a year earlier, on revenue of $1.90 billion, the same quarter’s operating income was $18 million. Receivables grew with revenue and took about $25 of each $100; customer deposits and prepayments under the contracts returned about $23.
The debt: none, and what stands in its place
Sandisk repaid its $2.0 billion term loan in full on March 4, 2026 and has no debt. The revolver was extended on September 9, 2026 and is undrawn. The obligations below are the ones that behave like debt in a downturn (10-K, July 3, 2026):
| Obligation | Amount | Terms |
|---|---|---|
| Revolving credit facility | $1.5B, undrawn | SOFR + 1.375%, 0.175% on the undrawn amount; matures September 9, 2031; one maintenance test, a maximum leverage ratio; collateral released at an investment-grade rating |
| Flash Ventures commitments | $6.56B | $2.63B in FY2027, $2.58B in FY2028–29, $1.32B in FY2030–31: depreciation reimbursement, equipment lease payments, committed loans and equity, other costs |
| Guarantees of Flash Ventures’ equipment leases | $0.92B (¥149.0 billion) | Half of each lease; $378M falls due in FY2027 |
| Payments to Kioxia for manufacturing services and supply | $1.2B over 2026–2029 | Agreed with the extension of the ventures to December 31, 2034 |
| DRAM purchases from Nanya | $5.89B minimum, FY2027–31 | Committed volumes at quarterly variable prices; agreed with Sandisk’s $970M investment in Nanya |
| Customer deposits | $1.50B | Refundable at the end of each contract |
| Other purchase obligations | $4.90B | Mostly FY2028–29 |
None of this is a solvency question at today’s earnings: the fourth quarter alone produced $7.1 billion of operating cash. It matters in the worst case, where revenue falls to about $20 billion by FY2029 while the largely fixed Flash Ventures costs keep running: the gross margin that year is about 64% with half the floor premium paid, and about 46% at market prices alone. Interest is now income: $70 million in FY2026 against $73 million of expense before the term loan was repaid. The two-year tax window from the spin closes February 24, 2027, after which an acquisition of Sandisk would no longer make the spin taxable to Western Digital; at about $185 billion of market value that is of little practical weight.
Where Sandisk is
Every wafer Sandisk sells comes from eight fabs in Japan that it shares with Kioxia, six at Yokkaichi and two at Kitakami; Sandisk owns 49.9% of the three Flash Ventures companies and takes about half the output, at cost plus a markup. The chips are assembled and tested in Penang, Malaysia (owned, 1.18 million square feet), in Shanghai through a venture 20% owned with JCET, and by contract manufacturers. Sites are from the 10-K’s property list, Sandisk’s office pages and Kioxia’s plant pages; a few are placed at the city centre.
All of Sandisk’s wafers come from eight fabs in Japan that it shares with Kioxia; the chips are assembled and tested in Penang, Malaysia (1.18 million sq ft, owned), in Shanghai through a venture with JCET, and by contract manufacturers. Design work is spread across California, Israel, India, Taiwan and Japan. About 11,100 employees in 33 countries: 74% in Asia-Pacific, 19% in the Americas, 7% in Europe, the Middle East and Africa. Click a point for details. Map data © OpenStreetMap contributors. Source: the FY2026 10-K (Item 2, Properties), Sandisk’s office-locations page and Kioxia’s plant pages; points geocoded with OpenStreetMap, or at the city centre where no address was found. As of October 23, 2026.
Asia is where the chips are made and where most are delivered: $14.2B of FY2026’s $20.2B of revenue was shipped to Asia (China $4.5B, Hong Kong $5.1B, the rest of Asia $4.6B), largely to device makers’ factories. Yokkaichi and Kitakami are about 600 km apart; both sit in earthquake zones. Penang holds $445M of Sandisk’s $674M of long-lived assets. Click a point for details. Map data © OpenStreetMap contributors. Source: the FY2026 10-K (Item 2, Properties), Sandisk’s office-locations page and Kioxia’s plant pages; points geocoded with OpenStreetMap, or at the city centre where no address was found. As of October 23, 2026.
- Revenue by where it is shipped, FY2026: Asia $14.2 billion (70%: Hong Kong $5.1 billion, China $4.5 billion, the rest of Asia $4.6 billion), the Americas $4.3 billion (21%; the United States $3.7 billion) and Europe, the Middle East and Africa $1.7 billion (9%). Asia’s share rose from 61% in FY2025 as device makers paid the higher prices.
- About 11,100 employees in 33 countries: 74% in Asia-Pacific, 19% in the Americas, 7% in Europe, the Middle East and Africa. Design work sits in Milpitas and Irvine, California; Kfar Saba, Tefen and Omer, Israel; Bengaluru, India; Hsinchu and Taichung, Taiwan; and near Yokohama, Japan.
- The concentration is in Japan for supply and in China and Hong Kong for demand. Both Japanese sites lie in earthquake zones, and an export-control change affecting China would reach about half of revenue.
- New capacity: Kitakami K2 began output in FY2026 and started tenth-generation flash in July 2026; the August 27 plan adds a third Kitakami fab, with output from about FY2029 according to news reports (shown as planned).
The scenarios and the asymmetry
The cases. Revenue is bits sold times the price of a bit; cost is bits times the cost of making one; both are indexed to the first quarter of FY2027, where the guide implies a cost of about 16 cents for each dollar of price. Bits grow 10–15% a year (management guides mid-teens), the cost per bit falls 6–10% a year, operating costs stay between 5% and 16% of revenue, and capital spending, Sandisk’s own plus its net funding of Flash Ventures, is 4% of revenue. The contracts set a floor under the price of the contracted bits at an 80% gross margin. Each case is a ten-year cash-flow valuation at 11%, with a terminal value once the margin has reached the case’s mid-cycle level by FY2034, plus $2.5 billion of net cash after customer deposits, prepayments and tax due. There is no published valuation to reproduce; the model returns $45.77 of earnings a share at the midpoints of the Q1 FY2027 guide, against the guided $44–46.
| Case | What it assumes | FY2027 / FY2028 EPS | Value | vs $1,260.93 |
|---|---|---|---|---|
| Best | Management’s FY2028–30 model: revenue grows with bits at about an 80%+ gross margin; FY2027 prices 20% above the first quarter’s and held to FY2030; then a fade to a 60% mid-cycle margin, above anything in the record | $244 / $292 | $1,399 | +11% |
| Base | An ordinary memory cycle: FY2027 prices 12% above the first quarter’s, then about half that by FY2029 as the new capacity arrives; the contracts honoured; a 42% mid-cycle margin, about the old SanDisk’s 2010–15 average | $225 / $181 | $774 | −39% |
| Worst | A fast reversion like 2019 or 2023: prices back near FY2025 levels by FY2029; customers renegotiate and pay half the floor premium; fabs underloaded; a 28% mid-cycle margin, about the Western Digital flash years’ average | $197 / $101 | $407 | −68% |
The price paths, the mid-cycle margins and the 11% discount rate are judgements; the table below shows how far each moves the value. All values are estimates from the model.
Most of the value in every case is the next four years of cash: free cash flow in FY2027–30 is about $1,077 a share in the best case, $663 in the base and $404 in the worst. In each case the mid-cycle margin means prices far below today’s by the early 2030s: at a 42% margin a bit sells for about 1.7 times its cost, against about 6 times in the first quarter of FY2027.
Stress tests, one change at a time on the base case (estimates):
| Change | Value | vs $1,260.93 |
|---|---|---|
| Between base and best: prices fall only a quarter by FY2029, a 50% mid-cycle margin | $1,007 | −20% |
| Prices hold at the FY2027 level through FY2028, then fall | $893 | −29% |
| Bit growth 17% a year instead of 13% | $847 | −33% |
| A 50% mid-cycle margin instead of 42% | $837 | −34% |
| Discount rate 9% instead of 11% | $826 | −35% |
| Customers pay only half the floor premium | $766 | −39% |
| No contract floors at all | $758 | −40% |
| Capital spending 6% of revenue instead of 4% | $751 | −40% |
| Cost per bit falling 12% a year instead of 9% (prices follow cost down) | $742 | −41% |
| Discount rate 13% | $735 | −42% |
| A 35% mid-cycle margin | $731 | −42% |
| Between base and worst: prices down 60% by FY2029, half the floors paid, a 35% margin | $566 | −55% |
The largest single factor is how long prices stay high: a year’s delay in the decline adds about $120 a share, and the in-between case toward the best adds about $230. None of the single changes brings the base case near the price; the discount rate and the mid-cycle margin move it by $40–60 each.
Three weightings, and what the price implies. The standard set, 25 / 50 / 25, and the stress set, 10 / 40 / 50, are the same for every company; the best guess drives the target and the two chips at the top of the page.
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $839 | −33% | 0.08 to 1 |
| Best guess (proposed): 25 / 55 / 20 | $857 | −32% | 0.08 to 1 |
| Stress: 10 / 40 / 50 | $653 | −48% | 0.02 to 1 |
| What the price implies: 78 / 22 / 0 | $1,261 | 0% | 1.0 to 1 |
The weights are a judgement. All values are estimates from the model.
Why the best guess:
- The best case gets 25%, the standard weight. It needs prices to hold near today’s for about four years. No memory upturn on record has lasted that long (2016–18 and 2020–22 each lasted about two years), but two facts are new: contracts covering about two-thirds of FY2028’s bits, backed by $5.0 billion of collateral and $1.5 billion of deposits, and datacenter demand that management says is now more than half the NAND market. Micron expects supply to be “much tighter” in 2027 and 2028 than in 2026.
- The base case takes 55%. TrendForce expects NAND supply to turn sufficient in 2027, with “increasing downward pressure on prices” as new capacity arrives while consumer demand stays weak (July 30, 2026); the capacity is being built, including Sandisk’s own share of the $31 billion Japan plan and SK Hynix’s 30,000–50,000-wafer-a-month line at Dalian, due in the first half of 2027 (TrendForce); and the fourth-quarter forecast already shows client and mobile prices barely rising.
- The worst case takes 20%, below the standard 25%, because the contracts’ deposits and guarantees make a collapse to FY2023–25 losses less likely than in earlier cycles. It is still the history of this business: three of its four reported years were losses.
- The price implies 78% on the best case and nothing on the worst. That is more than management’s own plan carries, since the best case already assumes it. Brokers’ targets average about $2,120 across 28 analysts (MarketBeat); the difference from this page is what happens after the contracts end.
- Evidence that would move the weights at the October 29 results: a second-quarter guide that implies prices up 10% or more, new contracts beyond $93.9 billion, and inventory days falling (best case up); a guide implying flat or falling prices, inventory days rising above 178, or any contract renegotiation (worst case up).
What the price implies. At the best guess’s 55% base weight the price is above every mix of the best and base cases, so the worst case is set to zero and the price solves
best weight × $1,399.22 + (100% − best weight) × $773.93 = $1,260.93
for a best weight of ($1,260.93 − $773.93) ÷ ($1,399.22 − $773.93) = 78%, leaving 22% on the base case.
The asymmetry on the best guess:
| Measure | At $1,260.93 | What it means |
|---|---|---|
| Expected return (header chip) | −32% | The probability-weighted value, $856.91, against the price |
| Gain to loss (header chip) | 0.08 to 1 | +$34.57 of probability-weighted gain against −$438.59 of loss |
| Expected base-case gain ÷ expected worst-case loss | 0 to 1 | The base case is itself a loss of $487.00 |
| Best-case gain ÷ worst-case loss | 0.16 to 1 | +$138.29 against −$853.71 |
| Base-case gain ÷ worst-case loss | −0.57 to 1 | −$487.00 against −$853.71 |
How the measures are calculated. Gain = case value − price; loss = price − case value. Weights are the best guess: 25% best, 55% base, 20% worst.
| Measure | Formula | At $1,260.93 |
|---|---|---|
| Expected return | (25% × best + 55% × base + 20% × worst) ÷ price − 1 | ($349.80 + $425.66 + $81.44) ÷ $1,260.93 − 1 = −32% |
| Gain to loss | (25% × best gain) ÷ (55% × base loss + 20% × worst loss) | $34.57 ÷ ($267.85 + $170.74) = 0.08 |
| Expected base ÷ expected worst | (55% × base gain) ÷ (20% × worst loss) | $0 ÷ $170.74 = 0 |
| Best ÷ worst | best gain ÷ worst loss | $138.29 ÷ $853.71 = 0.16 |
| Base ÷ worst | base gain ÷ worst loss | −$487.00 ÷ $853.71 = −0.57 |
| Price-implied best weight, worst at zero | (price − base) ÷ (best − base) | $487.00 ÷ $625.29 = 78% |
The header chips are green at +25% or more and 3 to 1 or better, blue at +10–25% and 2–3 to 1, orange at 0–10% and 1–2 to 1, and red below zero and below 1 to 1. On the best guess, expected return is green below $686, blue up to $779 and orange up to $857; gain to loss is green below $728, blue up to $779 and orange up to $857. Both are red above $857, and so both are red at $1,260.93.
Who has been trading Sandisk
Since August 24 Sandisk rose and fell with the memory makers, by more in both directions. Rebased to the August 24 close:
Closing prices rebased to August 24 = 100. Baskets are equal-weighted, in local currency: memory makers (Micron, Samsung Electronics, SK Hynix, Kioxia); hard-drive makers (Western Digital, the former parent, and Seagate); semiconductors and the S&P 500 through their ETFs (SMH, SPY). Seoul and Tokyo closes are carried to the New York session. Source: Yahoo Finance closes.
| From the close of | Sandisk | Memory makers | Hard-drive makers | Semiconductors (SMH) | S&P 500 |
|---|---|---|---|---|---|
| August 24 to September 22 | +26.4% | +11.3% | +11.2% | +11.1% | +1.5% |
| September 22 to October 22 | −33.2% | −27.0% | −27.1% | −13.9% | −1.2% |
| August 24 to October 22 | −15.6% | −18.8% | −18.9% | −4.3% | +0.3% |
Equal-weighted baskets in local currency: memory makers are Micron, Samsung Electronics, SK Hynix and Kioxia; hard-drive makers are Western Digital, the former parent, and Seagate. Seoul and Tokyo closes are carried to the New York session. Yahoo closes.
This is a sector move. Sandisk’s daily returns since August 24 correlate 0.86 with Micron’s, 0.67–0.71 with the hard-drive makers’ and 0.28 with the S&P 500’s. The extra rise to September 22 came with two index additions; the fall since matches Kioxia (−34% from its high) and SK Hynix (−34%) and needs no company explanation.
Daily volume (bars) and cumulative volume as a share of the 146.4 million shares outstanding (line). Gold bars mark days with a notable event; hover over one to see what happened. Source: this site's daily price archive (Yahoo Finance), through Oct 22, 2026.
2.7 times the share count traded in 42 sessions (a median of 8.8 million shares a day, 6% of the shares), and 1.2 times since September 22. The heaviest days were index days (August 31, September 18); the October fall came on ordinary volume, the pattern of buyers stepping back; a large holder selling would show as heavy days.
Index buying went one way. Since the spin Sandisk has moved from the S&P SmallCap 600 (February 2025) to the S&P 500 (November 28, 2025), the Nasdaq-100 (April 20, 2026), the Russell 1000 Growth (June 2026), MSCI World (August 31, 2026) and the S&P 100 (September 21, 2026). Each forced buying; none since has forced selling, because a falling price changes no fund’s holding in an index weighted by market value.
Who holds it. 13F filings at June 30, 2026 (the latest; September 30 filings arrive by about November 14):
| Holder | Shares at June 30, 2026 | Change from March 31 | Since |
|---|---|---|---|
| Vanguard (two advisers) | about 13.2M (9.0%) | about flat | 7.6% in the September 4 proxy |
| BlackRock | 10.30M (7.0%) | −1% | 6.1% in the proxy |
| FMR (Fidelity) | 7.86M (5.4%) | −41% | 5.3% (13G amendment, June 30) |
| State Street | 5.93M (4.0%) | +6% | |
| Invesco | 5.61M (3.8%) | +381% | Nasdaq-100 funds, after the April addition |
| J.P. Morgan | 3.94M (2.7%) | +176% | |
| Jane Street | 1.16M long, plus options | 5.0% at July 30 (13G), across its trading entities |
From the SEC’s 13F data sets; percentages of 146.4 million shares. Vanguard’s two advisers are Vanguard Capital Management and Vanguard Portfolio Management.
- Fidelity sold about 5.5 million shares in the June quarter, the largest reduction by any holder.
- Western Digital has sold its last shares: its 10-K reports none at July 3, 2026, so the former parent’s overhang is gone.
- No officer or director has bought. The sales are mostly under trading plans adopted in March to June 2026: the CEO 67,679 shares in September (above), the CFO 1,000 of his 11,000-share plan, the chief technology officer 7,112 shares in June and September, and the chief legal officer about 600 shares a month.
- The company is the largest buyer. It bought 2.84 million shares at an average of $1,600 ($4.5 billion) in the fourth quarter and has $15.5 billion of authorization left; shares outstanding fell by about 1.1 million between August 7 and September 4, an estimate of about $1.7 billion of buying in five weeks. At the best guess’s $857 a share, buying at today’s price moves value from the holders who stay to those who sell.
Index membership, now and next
| Index family | Member? | Evidence |
|---|---|---|
| S&P 500 and S&P 100 | Yes | S&P Dow Jones Indices, November 24, 2025 and September 4, 2026; Information Technology |
| Nasdaq-100 | Yes | From April 20, 2026 |
| MSCI World and ACWI | Yes | From the close of August 31, 2026 |
| Russell 1000 Growth | Yes | FTSE Russell’s June 2026 reconstitution moved it from 0% to 100% growth |
| Semiconductor funds (SMH) | Probably not | Data vendors class it as technology hardware, storage and peripherals; not found among SMH’s holdings |
No index event is likely to force trading in the next three months. The Nasdaq-100’s December reconstitution and S&P’s December rebalance can change its weight only through the share count; MSCI’s November review is announced in early November.
Short interest and volatility
The tables below show how much of the stock is sold short and how much the price moves. They are inputs to the weights above, and the tables update with the nightly data.
| Report | Settled | Short | % float | % outst. | Days to cover |
|---|---|---|---|---|---|
| First after the spin | Oct 15, 2025 | 6.72M | 4.7% | 4.6% | 1.0 |
| Three months earlier | Jul 15, 2026 | 7.86M | 5.4% | 5.4% | 1.0 |
| Lowest since the spin | Oct 15, 2026 | 4.70M | 3.3% | 3.3% | 1.0 |
| Latest | Oct 30, 2026 | 4.91M | 3.4% | 3.4% | 1.0 |
The latest share of float is higher than 2 of the 25 earlier reports since the spin. Short interest in shares, with its share of the float and of shares outstanding. FINRA settlement dates; figures are published about eight business days later. Days to cover is short interest divided by average daily volume, as reported by FINRA. Float and shares outstanding on or before each date, from this site's daily share records and the company's filings.
Short interest has more than halved since June, from 10.9 million shares (7.5%) on June 15 to 4.8 million (3.3%) on September 30, about half a day of average volume (FINRA reports days to cover with a minimum of 1.0). A short position that small and that easily covered says little about the downside. The October 15 figure is due about October 27, two days before results.
| Volatility, annualized | Last 20 sessions | Last 60 sessions | Since the spin |
|---|---|---|---|
| To November 13, 2026 | 136% | 94% | 104% |
At the last 60 sessions' volatility, one standard deviation over a month is about ±31%, or $673.72 to $1162.56 from the $885.01 close; about two months in three end inside that range if volatility holds. The median daily move since the spin is 3.4%.
| Results day | Released | Close before | Close after | Move | Times a median day |
|---|---|---|---|---|---|
| May 7, 2025 | After the close | $34.97 | $36.66 | +4.8% | 1.4× |
| August 14, 2025 | After the close | $46.68 | $44.54 | -4.6% | 1.3× |
| November 6, 2025 | After the close | $207.69 | $239.48 | +15.3% | 4.4× |
| January 29, 2026 | After the close | $539.30 | $576.25 | +6.9% | 2.0× |
| April 30, 2026 | After the close | $1096.51 | $1187.00 | +8.3% | 2.4× |
| August 5, 2026 | After the close | $1350.50 | $1258.58 | -6.8% | 2.0× |
| October 29, 2026 | After the close | $1330.05 | $1150.89 | -13.5% | 3.9× |
Average move on a results day: 8.6% either way, against a median day's 3.4%. The move is measured from the close before the release to the close of the first session after it.
Results days move the stock 4.6–15.3% the next session: +4.8%, −4.6%, +15.3%, +6.9%, +8.3% and −6.8% after the six releases since the spin, all made after the close. The last, on August 5, 2026, was followed by a 6.8% fall.
Notes on earlier sections
Data correction: the July 30, 2026 move. Why the stock moved the way it did says the +26.0% on July 30, 2026 came “on the FY2026 results”. The results were released on August 5, 2026, after the close, and the stock fell 6.8% the next session. Sandisk released no results that day. A data correction; no other figure changes.
Omission: the long-term contracts. The August analysis listed “long-term supply agreements at fixed pricing” under What would change this view as a development that would improve the outlook. By then Sandisk had already signed them: the 10-K, filed August 17, 2026, counts $59.8 billion of contracted revenue still to be delivered and two further contracts of $31.3 billion signed after the year-end, and the August 5 call gave the $93.9 billion minimum. They are covered above. An omission.
Clarification: capital intensity. The August analysis measured capital spending at 2.2% of FY2026 revenue, counting Sandisk’s own capital spending and its net loans to Flash Ventures, which is the cash measure. Management’s “approximately 6%” for FY2027 includes Sandisk’s share of the ventures’ gross spending, part of which returns through the wafer price. Both are correct on their own basis; the model uses 4%. A clarification.
What it means for the rating
SELL, target none → $860 (proposed). The target is the best-guess value, $857; it is the first this page has published. At $1,260.93 the stock is 47% above the target and 63% above the base case, and both chips are red. It is SELL rather than HOLD because the price needs 78% on management’s plan, more than any memory upturn on record has delivered, and the company is announcing the capacity that ends it. It is not a stronger call because the next two quarters are likely to be the best in Sandisk’s history: prices are still rising, the contracts protect much of FY2028, and a strong guide on October 29 could lift the stock further before the cycle turns.
| Action | Level | Reason |
|---|---|---|
| Buy | Below about $690 | Both chips green: expected return above 25% and gain to loss above 3 to 1 |
| Accumulate | $690–780 | Expected return 10–25% |
| Hold | $780–1,000 | Up to the in-between case toward the best ($1,007) |
| Sell | Above about $1,000 | |
| Move to HOLD | Prices still rising into 2027 on the second-quarter guide, new contracts beyond $93.9 billion, and inventory days falling | |
| Stay at SELL | A guide implying flat or lower prices, inventory days above 178, or any customer renegotiating a contract |
What the October 29 results must show:
| Item | Why it matters | Base case needs |
|---|---|---|
| First-quarter revenue and gross margin against the guide ($10.3–10.8 billion; 83–85%) | The base case assumes FY2027 prices 12% above the first quarter’s | At or above the midpoint |
| The second-quarter guide | It implies the price of a bit for October–December, which TrendForce expects up 15–20% | Revenue up 10% or more on the first quarter |
| Bits sold and inventory days (178 at July 3, 2026) | Higher inventory is held for the contracts; rising inventory with rising prices is how a cycle turns | Inventory days flat |
| The contracts: share of bits, new customers, any change in terms | The floors are the main protection in the worst case | More than half of FY2027 bits, no renegotiation |
| The buyback in the first quarter | 100% of free cash flow, at prices above the best guess | Stated |
| Capital spending and Sandisk’s share of the Kitakami Fab3 plan | The capacity that ends the cycle, and its timing | Output no earlier than FY2029 |
| Datacenter revenue and enterprise SSD | The one line that grew on volume | Growing on bits, separate from price |
Post-Spin Analysis — August 25, 2026
Written against the August 24 close of $1,493.12. Primary sources: the FY2026 Form 10-K (filed 2026-08-17, for the year ended July 3, 2026) and the FY2025 Form 10-K. Two full annual reports covering four fiscal years — the deepest record of any name we cover.
The one-line version
Sandisk has returned +2,972% since its February 2025 spin. It is the single best outcome in the 559-name universe, and it is the hardest thing we have had to value.
At $1,493.12 it trades at 20.2x trailing earnings — which sounds unremarkable until you see what produced those earnings. Revenue rose 175% in FY2026 while the company shipped only mid-teens percent more bits. Roughly 91% of the growth was price. Revenue per gigabyte rose ~150% in Datacenter and ~180% in Edge.
The company lost money in three of the four years for which records exist. Cumulative FY2023–25 operating losses were $6.4 billion. FY2026 operating income was $12.4 billion.
A 35% reversion in NAND pricing takes the P/E from 20x to 47x. A 50% reversion takes it to 110x. Against a three-year average operating income the shares trade at roughly 74x. The multiple looks lowest exactly at the top — which is the oldest trap in commodity investing.
Rating HOLD. No price target — see below. Grade B (2.93): a genuinely improved business riding a pricing spike nobody can size.
What the business actually is
The NAND flash memory business separated from Western Digital on February 24, 2025 — Western Digital retained the hard-disk-drive business and Sandisk took flash. It sells into three end markets, and the mix has changed beyond recognition in eighteen months:
| End market | FY2024 | FY2025 | FY2026 | FY26 growth |
|---|---|---|---|---|
| Datacenter | $325M | $960M | $5,153M | +437% |
| Edge | $4,069M | $4,127M | $12,160M | +195% |
| Consumer | $2,269M | $2,268M | $2,935M | +29% |
| Total | $6,663M | $7,355M | $20,248M | +175% |
Datacenter was 5% of revenue two years ago and is 25% now. That is the AI infrastructure build arriving in a memory company’s accounts.
Manufacturing sits in a joint venture. Sandisk and Kioxia operate Flash Ventures across eight fabs in Japan — six at Yokkaichi, two at Kitakami. The structure matters enormously for the economics: FY2026 capital expenditure was $177 million, or 0.9% of revenue. A semiconductor business that does not carry its own fab capex converts profit to cash at a rate almost nothing else in the industry can match.
That figure understates the real commitment, and Capital allocation below sets out by how much — Sandisk funds fab capacity through loans to the joint venture rather than through its own capital budget, which puts the true FY2026 total nearer 2.2% of revenue.
Management Team
| Role | Name | Background |
|---|---|---|
| Chairman & CEO | David V. Goeckeler | Was CEO of Western Digital and executed the split that created this company. Before that, EVP and general manager of Cisco’s $34B networking and security business; began his career at Bell Laboratories |
| EVP & CFO | Luis F. Visoso | |
| VP, Chief Accounting Officer | Michael R. Pokorny |
Board members with directly relevant operating histories:
| Background | |
|---|---|
| Dr. Thomas Caulfield | Former President and CEO of GlobalFoundries; previously ran IBM Microelectronics’ 300mm wafer fabrication and R&D operations |
| Devinder Kumar | CFO of AMD for a decade (2013–2023) after 39 years at the company, including 11 as corporate controller |
| Dr. Necip Sayiner | Former CEO of Intersil through its sale to Renesas, and before that CEO of Silicon Laboratories |
Also on the board: Alexander R. Bradley, Richard B. Cassidy II, Ellyn J. Shook, Miyuki Suzuki. Caulfield and Suzuki joined Western Digital’s board in 2021 and carried across at the separation.
Three observations.
The parent’s chief executive chose this half. Goeckeler ran Western Digital, decided to divide it, and took flash rather than hard drives. That is a stronger signal than any strategic rationale in a Form 10 — the person with the most information about both businesses picked one. Eighteen months later the flash half is worth several times the parent.
The board is unusually well-matched to the problem. A former foundry CEO, a former semiconductor CFO of a decade’s standing, and a two-time semiconductor CEO. For a company whose central question is where it sits in a capacity cycle, that is the right expertise, and it is rarer on spinoff boards than it should be.
Chairman and CEO are combined. Goeckeler holds both roles. That is a governance structure some investors discount, and it is worth stating plainly rather than leaving to a proxy statement.
The insider selling plans, disclosed in the 10-K
Both senior executives adopted Rule 10b5-1 selling plans in May 2026 — weeks before the stock peaked at $2,335 on June 25:
Plan adopted Maximum shares Approximate value at $1,493 David Goeckeler, CEO May 29, 2026 up to 124,192 ~$185M Luis Visoso, CFO May 22, 2026 up to 11,000 ~$16M A 10b5-1 plan is the correct and compliant way for an insider to sell, and adopting one is not a signal about the business — the schedule is fixed in advance precisely so it cannot be. Goeckeler’s plan runs to September 2027 and a portion of his shares is withheld for tax at roughly 45%.
It is disclosed in the annual report and an investor should know it exists. After a 2,972% run, the people with the best view of the cycle have arranged to sell into it on a schedule.
The financial record — four years, and it is brutal
| Fiscal year | Revenue | YoY | Gross margin | Operating income | Ex-impairment |
|---|---|---|---|---|---|
| FY2023 | $6,086M | — | 7.1% | ($2,035M) | ($2,706M) |
| FY2024 | $6,663M | +9.5% | 16.1% | ($468M) | ($468M) |
| FY2025 | $7,355M | +10.4% | 30.1% | ($1,377M) | ($3,207M) |
| FY2026 | $20,248M | +175.3% | 71.5% | $12,389M | $12,389M |
Read the gross margin column. 7.1% → 16.1% → 30.1% → 71.5%. That is not a company improving. That is a commodity price.
Sandisk lost money in three of the four years on record, with cumulative operating losses ex-impairment of $6.4 billion across FY2023–25 — including a $1.83 billion goodwill impairment in FY2025 and $671 million in FY2023. Then it earned $12.4 billion in one year.
The decomposition that decides the investment
The 10-K is unusually clear about what happened, and the numbers are the crux:
| Revenue growth | Volume (exabytes) | Revenue per gigabyte | |
|---|---|---|---|
| Datacenter | +437% | +~120% | +~150% |
| Edge | +195% | +high single digits | +~180% |
| Total | +175% | +mid-teens | — |
Total bits shipped rose mid-teens percent. Revenue rose 175%. Roughly 91% of the increase was price, not volume.
The exception is Datacenter, and it is the entire bull case. Volume there rose ~120% — that is real physical demand from AI infrastructure, not a price effect. Datacenter is now $5.2 billion of revenue and growing on units.
Edge is the exposure. At $12.2 billion it is 60% of the company, and it grew on +180% pricing against high-single-digit volume. That is the part that reverts.
Where Sandisk sits in the value chain
Sandisk has almost no durable pricing power and, at this moment, more pricing power than any other business we look at. Those are not contradictory. They are the two halves of what a commodity memory business is, and holding both at once is the only honest way to read the FY2026 accounts.
The price is the industry’s, not the company’s
91% of FY2026 revenue growth was price. Revenue rose 175% on mid-teens bit growth; revenue per gigabyte rose roughly 150% in Datacenter and 180% in Edge. No product decision, customer relationship or technology advantage produced that. The NAND supply-demand balance did.
| Against | Position |
|---|---|
| Customers | Total in shortage, none in glut. A hyperscaler buying enterprise SSDs today has no alternative and pays what is asked. The same buyer in 2024 dictated terms to a loss-making supplier |
| Competitors — Samsung, SK Hynix, Micron, Kioxia, YMTC | The determinant. Roughly five independent capacity decisions set the price for all of them. Capacity takes two to three years to add and cannot be un-added |
| The joint-venture partner — Kioxia | A genuine constraint. Sandisk does not own fabs outright; Flash Ventures is operated jointly across eight fabs in Japan. It cannot unilaterally expand or restrain its own supply |
| Equipment suppliers | Weak. The same handful of tool vendors serve every producer, and lead times lengthen exactly when everyone wants capacity |
The structural point, and it is unlike anything else on this site. For most businesses, margin is a function of what the company has built — a data set, an installed base, a patent, a cost position. Sandisk’s margin is a function of what its competitors decide to build. It can execute perfectly and still earn nothing, and it can execute unremarkably and earn $12.4 billion, which is roughly what happened in consecutive years.
That is why this page carries no price target. A target requires a view on mid-cycle earnings; mid-cycle earnings here require a view on four other companies’ capital budgets. We do not have one, and neither does anyone quoting a number.
The joint venture cuts both ways, and the second edge is under-weighted
The favorable half is well understood. Flash Ventures means Sandisk does not carry solo fab capital expenditure, which is why headline capex was $177M on $20.2B of revenue and why free cash flow converted at 57% of sales in FY2026. Almost nothing in semiconductors does that.
The unfavorable half is that it also removes control. Capacity decisions are joint. When the cycle turns — and the entire question on this page is when — a solo operator can idle its own fabs. A joint venture negotiates.
The one development that could change the structural answer
Datacenter went from 5% of revenue two years ago to 25% today. That matters beyond the growth rate, because enterprise SSD is a more qualified product than consumer flash. Hyperscalers specify endurance, latency consistency and failure characteristics, and they validate a supplier’s parts into a platform.
If a meaningful share of Sandisk’s output becomes qualification-gated rather than spot-priced, the business becomes structurally different — closer to a components supplier with design-in protection than to a commodity producer. It is far too early to claim that has happened. But it is the only mechanism by which this company escapes being a price-taker, and it is worth watching in the mix disclosure rather than in the margin.
Why the stock moved the way it did
| Day-1 close, 2025-02-24 | $48.60 |
| Post-spin low, 2025-04-22 (57 sessions) | $29.62 — −39% below day 1 |
| Peak, 2026-06-25 | $2,335.00 |
| Post-peak trough, 2026-07-29 | $1,015.89 — −56.5% |
| Now | $1,493.12 — −36.1% from peak, +47.0% off the trough |
The forced-selling flush was severe and it worked. Day-1 volume ran 15.4x baseline, the stock fell 6.5% on its first session, and it kept falling for 57 sessions to $29.62 — nearly 40% below the day-1 close. Anyone who bought the flush low has made roughly 50 times their money.
Then nothing happened for four months, and the stock traded between $32 and $52 through August 2025. The inflection was September 2025, when it went from $52.47 to $112.20 in a single month as NAND pricing turned.
The largest single sessions are all pricing and earnings events: +27.6% on 2026-01-06, +22.0% on 2026-06-25 (the peak), −20.3% on 2025-11-20, and +26.0% on 2026-07-30 — the day after the post-peak trough, on the FY2026 results.
Realised volatility is 105.5% annualised, and volume still runs 7.4x the post-spin baseline. This is not a stock that has settled.
Capital allocation
The balance sheet was transformed in twelve months, and the buyback is now the central capital decision in front of this board.
| ($M) | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Cash from operating activities | (309) | 84 | 11,671 |
| Purchases of property, plant and equipment | (166) | (204) | (177) |
| Free cash flow | (475) | (120) | 11,494 |
| Net funding to/from Flash Ventures | +239 | +182 | (275) |
| Repurchases of common stock | — | — | (4,524) |
| Debt repaid | — | (100) | (1,900) |
| Cash at year end | 328 | 1,481 | 4,762 |
| Total debt at year end | 1,900 | — |
Read the last two rows together. Sandisk entered FY2026 with $1.9B of debt and $1.5B of cash. It ended with no debt at all and $4.76B of cash, having returned $4.5B to shareholders in between. That is a complete balance-sheet reconstruction inside one fiscal year, and it was funded entirely by the pricing cycle.
The capital-expenditure figure understates the real commitment
This page has said capex was $177M, or 0.9% of revenue. That is the headline number and it is correct as far as it goes — but it is not the whole capital commitment, because Sandisk funds fab capacity through the joint venture rather than on its own balance sheet:
| ($M) | FY2024 | FY2025 | FY2026 |
|---|---|---|---|
| Notes receivable issued to Flash Ventures | (243) | (333) | (462) |
| Notes receivable repaid by Flash Ventures | 482 | 515 | 187 |
| Distributions from Flash Ventures | — | 176 | — |
| Net cash to (from) the JV | +239 | +182 | (275) |
Total FY2026 capital commitment was roughly $452M — capex plus net JV funding — or 2.2% of revenue. Still extraordinarily light for a semiconductor business, but two and a half times the headline figure, and the more useful number.
And there is a signal buried in that table. In FY2024 and FY2025 the joint venture was a net repayer of cash to Sandisk. In FY2026 it became a net borrower, for the first time, by $275M.
That is what the beginning of a capacity build looks like in a cash flow statement. Capacity is the mechanism that ends every NAND pricing cycle, and it takes two to three years to arrive. The single most important variable on this page has just turned, quietly, in a line item nobody reads — and it turned in the direction that eventually ends the earnings this valuation rests on.
The $20 billion authorization
| Authorized April 2026 | $6.0B |
| Authorized August 5, 2026 | $14.0B |
| Total authorized | $20.0B — about 9% of the market capitalization |
| Repurchased in FY2026 | $4.5B |
| Remaining | ≈$15.5B |
| Dividend | None |
Against FY2026 free cash flow of $11.5B, $20B is under two years of cash. Against the three-year average of roughly $3.6B, it is five and a half years. Which of those is the right denominator is the entire question on this page, restated as a capital-allocation decision.
The uncomfortable arithmetic. The board authorized $6B in April and tripled the program to $20B in August — after the shares had risen roughly thirty-fold from the post-spin low. Every dollar spent at today’s price is a bet that current earnings are closer to permanent than to peak.
That is not automatically wrong. With no debt, $4.8B of cash and negligible capital needs of its own, Sandisk has few alternative uses; and a company that hoards cash through a cycle peak has its own history of destroying value. But it is the same bet the equity holder is making, made with the equity holder’s money, at the equity holder’s price — and it is being sized off a single year of results.
The tell to watch is pace, not authorization. $4.5B in a year against a $20B authorization is measured. A sharp acceleration from here would say management believes the cycle has further to run — which is information, and the only forward-looking statement about NAND pricing this management team is likely to make.
Valuation — and why there is no price target
| At $1,493.12 | |
|---|---|
| Shares outstanding | 146.4M |
| Market capitalization | $218.6B |
| Cash | $4,762M |
| Total debt | $0 — repaid in full during FY2026 |
| Enterprise value | $213.9B |
| FY2026 diluted EPS | $73.76 |
| P/E on trailing earnings | 20.2x |
| EV / FY2026 operating income | 17.3x |
The balance sheet is pristine. Debt went from $1.9 billion to zero and cash stands at $4.8 billion. On any measure of financial risk this company is now unassailable — which is precisely what a peak-cycle balance sheet looks like.
What price reversion does
Holding volume and cost of revenue flat and varying only realised pricing:
| Revenue per GB | Revenue | Operating income | Operating margin | EPS | P/E |
|---|---|---|---|---|---|
| unchanged | $20,248M | $12,389M | 61.2% | $74.29 | 20.1x |
| −20% | $16,198M | $8,339M | 51.5% | $50.01 | 29.9x |
| −35% | $13,161M | $5,302M | 40.3% | $31.79 | 47.0x |
| −50% | $10,124M | $2,265M | 22.4% | $13.58 | 109.9x |
| −60% | $8,099M | $240M | 3.0% | $1.44 | 1,037x |
| −65% | $7,087M | ($772M) | (10.9%) | ($4.63) | loss |
For scale: FY2025 revenue was $7,355M. Pricing back at FY2025 levels on FY2026 volume would put revenue near $8.4 billion — the bottom two rows of that table.
Mid-cycle earnings
| Denominator | Operating income | EV multiple |
|---|---|---|
| FY2026 peak | $12,389M | 17.3x |
| Three-year average, FY24–26 | $2,905M | 73.6x |
| Four-year average, FY23–26 | $1,502M | 142x |
This is the whole valuation problem in one table. On peak earnings the stock is unremarkable. On any normalized measure it is extraordinarily expensive. Which is right depends entirely on whether NAND pricing has structurally re-rated or is at a cyclical top — and nobody knows.
Why no price target
Every other company we cover gets one. Sandisk does not, and the reason is methodological rather than evasive.
A price target requires a defensible normalized earnings figure. For Sandisk the plausible range runs from an operating loss to $12.4 billion, and the correct answer depends on a commodity price that has moved 180% in a year and could move as far back. A target would imply a precision the data cannot support, and publishing one would be false confidence.
What can be said instead:
- At unchanged pricing, the shares are worth more than they trade for — a 20x business growing datacenter volume at triple digits is not expensive.
- At FY2025 pricing with FY2026 volume, the equity is worth a fraction of today’s price.
- The market at $1,493 is discounting roughly a 20–25% price reversion, which is neither obviously optimistic nor obviously conservative.
That is an honest description of a bet, not a valuation.
Tail scenarios
Upside tails
1. NAND pricing is structurally re-rated, not cyclically peaked. If AI infrastructure demand keeps supply tight for several years — an argument the industry is making seriously — then FY2026 is a new base rather than a peak. At unchanged pricing the shares compound from a 20x multiple with no debt. This is the bull case and it is not absurd.
2. Datacenter keeps compounding on volume. It grew ~120% in exabytes, not just price. At $5.2 billion and 25% of revenue, another two years of that mix shift would make Sandisk a fundamentally different, less cyclical business.
3. The $20 billion buyback. Sized and dated in Capital allocation above. With no debt and a capital budget near 2% of revenue, the cash is genuinely there. Retiring shares at a cyclical peak is the risk; retiring them into a reversion would be exceptional capital allocation.
4. Capital-light economics persist. The Flash Ventures structure keeps Sandisk’s own capital budget under 1% of revenue, and even including net funding to the joint venture the FY2026 total was about 2.2%. Whatever the cycle does to margins, this company keeps more of its profit than an integrated memory maker. “Permanent” would be too strong — the JV became a net borrower from Sandisk in FY2026 for the first time, which is what a capacity build looks like early.
Downside tails
1. The reversion is faster and deeper than the table above. Memory pricing does not glide down; it falls. In prior NAND downcycles contract prices halved within four quarters. The −50% row is not a tail — it is a normal memory downcycle, and it puts the shares on 110x.
2. Supply responds. Every NAND producer is seeing the same prices. Samsung, SK Hynix, Micron, Kioxia and YMTC all have capacity decisions in front of them, and the industry’s history is that they all add at once. The 10-K’s own risk factors name declining average selling prices first.
3. The buyback destroys value. $20 billion authorised at a share price up 2,972%, funded by peak-cycle cash flow. If pricing reverts, the company will have retired stock near the top with money it needed at the bottom — the mistake memory companies have made in every previous cycle.
4. Edge normalizes hard. Sixty percent of revenue grew on 180% pricing against high-single-digit volume. There is no demand story underneath that mix — it is consumer and client devices absorbing higher prices, which they do until they do not.
What the tails say about the position
The distribution here is wider than for anything else we cover, in both directions, and it is not symmetric in time. The upside requires several years of sustained tightness; the downside can arrive in two quarters.
That argues for a small position or none, and against any position sized on the 20x headline multiple.
What this most resembles
Nothing in the universe, which is itself the finding.
| vs Day 1 | Excess vs S&P | |
|---|---|---|
| Sandisk | +2,972% | +926pp annualised |
| nVent Electric (the next best) | +601.5% | +15.6pp |
| Wabtec | +309.6% | +6.7pp |
| Universe median | +45.9% | −7.2pp |
Sandisk’s annualised excess return is roughly sixty times the next best name in the universe. It is not an outlier within the distribution; it is outside it.
The closest structural analogue is not a spinoff at all — it is any commodity producer at a cycle peak: enormous trailing earnings, a low trailing multiple, a pristine balance sheet, and an earnings base that can halve in a year. Every element of the Sandisk setup has been seen before in memory, oil and shipping. What is unusual is that it happened to a company eighteen months out of a spinoff.
In depth: competitive dynamics
1. The industry structure
NAND flash is a five-player oligopoly with no meaningful barriers on the demand side and enormous ones on the supply side:
| Producer | Position |
|---|---|
| Samsung | Largest, fully integrated, can fund capacity through any cycle |
| SK Hynix (incl. Solidigm) | Second, strengthened by the Intel NAND acquisition |
| Kioxia | Sandisk’s JV partner — they share the fabs |
| Sandisk | Roughly co-equal with Kioxia in Flash Ventures output |
| Micron | Smaller in NAND, larger in DRAM |
| YMTC | Chinese, capacity-constrained by export controls |
2. The JV is the single most important structural fact
Sandisk does not own fabs outright. Flash Ventures with Kioxia operates eight plants in Japan, and Sandisk takes its share of output. The consequences run both ways:
✅ Own capital budget of 0.9% of revenue. Sandisk captures memory-cycle upside without carrying memory-cycle capital intensity. In FY2026 it converted $12.4 billion of operating income on $177 million of capex — though net funding to the joint venture added a further $275 million, so the honest figure is 2.2% of revenue rather than 0.9%.
✅ Capacity discipline is shared. Neither partner can unilaterally flood the market, which is a genuine restraint on the industry’s worst instinct.
⚠️ No control over the technology roadmap or capacity timing. Sandisk cannot independently decide to add supply when prices are high — or refuse to when its partner wants to.
⚠️ Concentration in Japan. Eight fabs in two locations, in a seismically active country.
3. Moats and weak spots
⚠️ There is no product moat. NAND is a commodity. Bits are fungible, priced on spot and contract markets, and qualified across suppliers. The 10-K’s first listed risk is “average selling prices, volatile demand, technological change, industry consolidation, lengthy product qualifications, and supply constraints.”
✅ The brand has real value in Consumer and Edge. SanDisk-branded retail products command a premium that pure bit suppliers do not.
✅ Customer concentration is unusually low for semiconductors. The top ten customers are 44% of revenue and no single customer exceeds 10% — better diversification than most names we cover.
❓ Datacenter qualification may become a moat. Enterprise SSD qualification at hyperscalers is slow and sticky. If Sandisk’s ~120% datacenter volume growth reflects design wins rather than allocation, that is a durable position. The filings do not distinguish the two, and it is the most important undisclosed fact about this company.
In depth: valuation against peers
Memory companies are valued on where you think you are in the cycle, and the convention is deliberately inverted: a low trailing P/E at peak earnings is a warning, not an attraction; a high one at trough earnings is often the entry.
| Trailing P/E | What it signals | |
|---|---|---|
| Sandisk today | 20.2x | Peak earnings — the multiple is low because earnings are extreme |
| Sandisk at FY2025 | loss-making | Trough — when the shares traded at $30–50 |
The like-for-like comparison that matters is Sandisk against itself. At the April 2025 low the company was loss-making and the market capitalization was roughly $4.3 billion. Today it earns $11.4 billion a year and is valued at $218.6 billion. The business improved enormously; the question is how much of that improvement is permanent.
We do not publish peer trading multiples we cannot compute from primary filings. Samsung, SK Hynix, Micron and Kioxia figures were not independently verified and are therefore described rather than quoted.
In depth: is Sandisk an acquisition target?
No, on three separate grounds.
Size. At a $218.6 billion enterprise value the list of possible acquirers is empty. This is now one of the largest semiconductor companies in the world by market capitalization.
§355(e). The two-year window from the Western Digital separation runs to February 24, 2027. An acquisition of 50% or more inside it would make the spin taxable to Western Digital.
Antitrust. The only industrially logical buyers are the other four NAND producers, and any combination among the top five would be blocked in every major jurisdiction.
The interesting corporate-action question is the reverse: does Sandisk buy something, or restructure Flash Ventures?
With $4.8 billion of cash, no debt and $12 billion of annual operating income at current pricing, Sandisk has more capital than at any point in its history — and a joint venture structure that leaves it without control of its own manufacturing. Consolidating Flash Ventures, or a transaction with Kioxia itself, is the transaction that would change the company most.
Memory companies making large acquisitions at cycle peaks has a poor history, and the $20 billion buyback suggests the board has chosen a different route.
What would change this view
| Direction | Trigger |
|---|---|
| Better | Datacenter volume continuing at triple-digit growth for another two quarters, which would establish it as a demand story rather than a price one · disclosure separating design wins from allocation · long-term supply agreements at fixed pricing · the buyback executing into weakness rather than strength |
| Worse | Contract NAND pricing rolling over · any of the five producers announcing major capacity additions · net funding to Flash Ventures rising further, which is capacity arriving two to three years ahead of the price effect · Edge volume declining as customers resist pricing · the buyback consuming cash at the peak |
| Thesis-breaking | A 40%+ reversion in realised pricing, which on the table above takes earnings down roughly 80% · a Flash Ventures disruption at Yokkaichi or Kitakami · export-control changes affecting the Asian customer base, which is 70% of revenue |
Investment Scorecard
Scored on the five weighted dimensions set out in our methodology.
| Dimension | Weight | Score | Rationale |
|---|---|---|---|
| Financial Profile | 25% | 3.0 | Zero debt, $4.8B of cash, a capital budget of roughly 2.2% of revenue including joint-venture funding, and $12.4B of operating income — a pristine balance sheet. But a business whose operating income swung from −$3.2B to +$12.4B in a single year does not have a 4-rated financial profile whatever today’s balance sheet says. Cumulative FY2023–25 losses were $6.4B |
| Competitive Position | 25% | 2.5 | NAND is a commodity with no product moat — the 10-K names declining selling prices as its first risk. Offset by low customer concentration (top ten 44%, none above 10%), a genuine consumer brand, and the capital-light JV structure. The datacenter position may be a moat but the filings do not establish it |
| Strategic Rationale | 20% | 4.0 | Separating flash from hard drives was the correct structural decision — two businesses with different capital cycles, customers and economics. The spin let each be valued properly, and the outcome vindicated it emphatically |
| Management & Governance | 20% | 3.0 | Repaid $1.9B of debt in full and built a $4.8B cash position — exactly right. But $20B of buyback authorised after a 2,972% run, funded by peak-cycle cash flow, is the decision every memory company has got wrong before. Scored on the tension |
| Acquisition Potential | 10% | 1.5 | Effectively zero. Too large, blocked by §355(e) until February 2027, and any logical buyer would be blocked on antitrust |
| Weighted Score | 2.93 | ||
| Investment Grade | B · Moderate / Hold |
What the capital-allocation and value-chain work changed: nothing, and that is the finding
Both sections were added after this grade was set, and neither moved a score — the scorecard had already priced the commodity position, the pristine balance sheet and the awkwardness of a $20B authorization struck after a thirty-fold move.
One figure was corrected. Capital intensity is 2.2% of revenue, not 0.9%, once loans to Flash Ventures are counted alongside the capital budget. That is still remarkably light and does not change the conclusion.
And one new indicator was found, which is recorded in What would change this view rather than in a score: the joint venture became a net borrower from Sandisk in FY2026 for the first time. Capacity is what ends every NAND pricing cycle, and this is what its beginning looks like in a cash flow statement — two to three years before it reaches the price.
First grade for this company, and the lowest we have assigned
B (2.93) on a stock that has returned +2,972%. That is not a contradiction — the grade measures business quality, and NAND flash is a commodity business with no pricing power at the trough. The four-year record shows exactly that: three years of losses, one extraordinary year.
The rating is HOLD rather than SELL because the datacenter volume growth is real, the balance sheet is pristine, and a structurally tighter NAND market is a genuine possibility rather than a hope.
What would take it to A−: evidence that datacenter demand is design-win driven and durable, which would make Sandisk a specialty supplier rather than a commodity producer. What would take it to C: a pricing reversion with the buyback already spent.