Solstice Advanced Materials SOLS
+21.0%vs Day 1Spinoff of Honeywell (HON) · Classic Spinoff · Spun Oct 30, 2025
Expected return (11/13/2026): -13% Gain to loss: 0.3 : 1Honeywell's former advanced-materials arm: low-global-warming refrigerants (about 70% of sales, ~37% segment margin), electronic and specialty materials, and half of ConverDyn, the only U.S. uranium converter. Standalone again since the Element Solutions merger was terminated on August 27, 2026, with a $500M buyback authorized.
Current Stats
Post-Spinoff Performance
| Timeline | |
| Spinoff date | October 30, 2025 · S&P MidCap 400 |
| Days since spinoff | 380 days |
| Structure | Classic Spinoff |
| §355(e) window closes statutory; a tax matters agreement may bar more, and for longer | October 30, 2027 |
| Parent | Honeywell (HON) |
| Day-1 reaction | |
| Day 1 open | $48.60 |
| Day 1 return (open→close) | +0.3% |
| Day 1 price (close) | $48.74 reported $50.05 (unverified) |
| Day 1 range | $47.60 – $53.80 +13.0% spread |
| Day 1 low held? | Breached after 1 session to -15.1% below |
| Price levels | |
| Post-spin low (closing) | $41.43 on Nov 18, 2025 · 19 days post-spin |
| Current price (Nov 13, 2026) | $66.12 |
| Returns | |
| Return vs Day 1 (close) | +36.1% |
| — range by day 1 entry theoretical bounds | +23.3% to +39.4% |
| Return vs post-spin low (price) | +59.6% |
| Total return vs low incl. dividends since | +60.1% |
| First-quarter return (≈90d) | +34.5% |
| 1-year return | +24.7% |
| Annualized return (CAGR) | +34.6% |
| Versus benchmarks | |
| S&P 500 over same window | +12.2% |
| Annualized excess vs S&P | +22.9% |
| Shares & ownership | |
| Shares outstanding Sep 30, 2026 | 157,210,055 |
| Diluted average shares the EPS denominator | 159,000,000 |
| Free float | 157,020,807 100% of shares outstanding |
| Held by institutions | 83% insiders 1.3% |
| Share count trend Jun 2025 → Sep 2026 | -1.0% net buyback |
| Volume & liquidity | |
| Traded per day 20-session median | $127M |
| Normal volume baseline | 2,292,850 shares · now 0.89x |
| Day 1 volume | 10.3x normal · first week 6.4x |
| Decay | half in 5 sessions · normal by 10 |
Computed from split-adjusted closing prices. Returns are total return — (end price + dividends received − start price) ÷ start price — with no reinvestment assumed.
Price History
Closing price, split-adjusted, with volume below. The Price line excludes dividends; Price + dividends adds the cash paid out, with no reinvestment assumed. Individual payments are listed in the table below. Source: Yahoo Finance. Data through Nov 14, 2026.
Raw daily price & volume data · dividends marked
| Date | Open | High | Low | Close | Volume | Float | Turnover | Market cap | Dividend | Split |
|---|---|---|---|---|---|---|---|---|---|---|
| 2026-11-13 | $66.88 | $67.00 | $64.06 | $66.12 | 1,416,500 | 157,020,807 | 0.90% | $10.39B | — | — |
| 2026-11-12 | $66.00 | $66.92 | $65.54 | $66.51 | 1,412,800 | 157,020,807 | 0.90% | $10.46B | — | — |
| 2026-11-11 | $67.22 | $67.75 | $65.67 | $67.15 | 1,965,700 | 157,020,807 | 1.25% | $10.56B | — | — |
| 2026-11-10 | $62.73 | $65.17 | $62.65 | $65.02 | 2,735,700 | 157,020,807 | 1.74% | $10.22B | — | — |
| 2026-11-09 | $59.29 | $63.69 | $58.94 | $63.65 | 2,921,300 | 157,020,807 | 1.86% | $10.01B | — | — |
| 2026-11-06 | $56.09 | $58.64 | $55.30 | $58.00 | 3,138,800 | 157,020,807 | 2.00% | $9.12B | — | — |
| 2026-11-05 | $56.48 | $57.84 | $54.81 | $55.04 | 4,420,800 | 157,020,807 | 2.81% | $8.65B | — | — |
| 2026-11-04 | $60.40 | $62.00 | $56.32 | $57.70 | 5,847,200 | 157,020,807 | 3.72% | $9.07B | — | — |
| 2026-11-03 | $59.60 | $62.47 | $59.53 | $61.74 | 3,470,200 | 157,020,807 | 2.21% | $9.71B | — | — |
| 2026-11-02 | $61.18 | $61.56 | $58.23 | $58.93 | 2,058,800 | 157,020,807 | 1.31% | $9.26B | — | — |
| 2026-10-30 | $60.54 | $61.31 | $59.14 | $60.55 | 1,531,100 | 157,022,379 | 0.97% | $9.52B | — | — |
| 2026-10-29 | $62.80 | $63.12 | $61.72 | $62.56 | 1,542,100 | 157,021,403 | 0.98% | $9.84B | — | — |
| 2026-10-28 | $63.22 | $63.46 | $62.38 | $63.25 | 1,166,900 | 158,656,752 | 0.74% | $9.94B | — | — |
| 2026-10-27 | $60.79 | $63.06 | $60.64 | $62.97 | 1,794,000 | 158,656,752 | 1.14% | $9.90B | — | — |
| 2026-10-26 | $59.42 | $61.21 | $59.19 | $60.38 | 1,893,900 | 158,656,752 | 1.20% | $9.49B | — | — |
| 2026-10-23 | $59.04 | $59.94 | $57.15 | $59.42 | 1,998,300 | 158,656,752 | 1.27% | $9.34B | — | — |
| 2026-10-22 | $64.00 | $64.09 | $59.40 | $59.80 | 2,825,100 | 158,656,752 | 1.80% | $9.40B | — | — |
| 2026-10-21 | $64.35 | $65.43 | $63.67 | $64.99 | 2,827,300 | 158,656,752 | 1.80% | $10.22B | — | — |
| 2026-10-20 | $61.94 | $63.42 | $60.43 | $63.06 | 4,452,700 | 158,656,752 | 2.83% | $9.91B | — | — |
| 2026-10-19 | $59.60 | $60.97 | $59.48 | $60.47 | 1,934,000 | 158,656,752 | 1.23% | $9.51B | — | — |
| 2026-10-16 | $59.76 | $60.65 | $58.70 | $59.25 | 1,893,900 | 158,656,752 | 1.20% | $9.31B | — | — |
| 2026-10-15 | $58.96 | $60.19 | $57.00 | $59.92 | 2,281,300 | 158,656,752 | 1.45% | $9.42B | — | — |
| 2026-10-14 | $60.02 | $60.98 | $59.17 | $60.13 | 2,661,000 | 158,656,752 | 1.69% | $9.45B | — | — |
| 2026-10-13 | $60.44 | $61.66 | $59.24 | $60.91 | 1,519,300 | 158,656,752 | 0.97% | $9.58B | — | — |
| 2026-10-12 | $61.21 | $61.48 | $60.05 | $60.71 | 1,480,900 | 158,656,752 | 0.94% | $9.54B | — | — |
| 2026-10-09 | $60.68 | $61.66 | $59.76 | $61.35 | 1,686,200 | 158,656,752 | 1.07% | $9.64B | — | — |
| 2026-10-08 | $59.98 | $61.08 | $59.26 | $60.23 | 1,895,400 | 158,656,752 | 1.21% | $9.47B | — | — |
| 2026-10-07 | $60.84 | $60.98 | $59.42 | $60.36 | 1,701,600 | 158,656,752 | 1.08% | $9.49B | — | — |
| 2026-10-06 | $58.24 | $61.35 | $58.16 | $61.27 | 2,600,300 | 158,656,752 | 1.65% | $9.63B | — | — |
| 2026-10-05 | $57.33 | $58.83 | $56.81 | $58.06 | 2,508,900 | 158,656,752 | 1.60% | $9.13B | — | — |
| 2026-10-02 | $57.72 | $58.05 | $56.72 | $57.70 | 1,578,800 | 158,656,752 | 1.00% | $9.07B | — | — |
| 2026-10-01 | $56.00 | $57.02 | $54.78 | $56.98 | 1,842,400 | 158,656,752 | 1.17% | $8.96B | — | — |
| 2026-09-30 | $55.69 | $57.06 | $54.81 | $56.32 | 2,717,100 | 158,656,752 | 1.73% | $8.85B | — | — |
| 2026-09-29 | $56.86 | $56.92 | $55.51 | $56.01 | 1,785,100 | 158,656,752 | 1.12% | $8.90B | — | — |
| 2026-09-28 | $56.00 | $57.54 | $55.35 | $56.93 | 2,919,300 | 158,656,752 | 1.84% | $9.04B | — | — |
| 2026-09-25 | $55.96 | $57.12 | $55.77 | $56.65 | 1,414,400 | 158,656,752 | 0.89% | $9.00B | — | — |
| 2026-09-24 | $57.07 | $57.16 | $55.43 | $56.01 | 2,519,700 | 158,656,752 | 1.59% | $8.90B | — | — |
| 2026-09-23 | $58.80 | $59.42 | $57.80 | $57.98 | 1,565,400 | 158,656,752 | 0.99% | $9.21B | — | — |
| 2026-09-22 | $57.69 | $59.21 | $57.06 | $58.89 | 1,707,600 | 158,656,752 | 1.08% | $9.35B | — | — |
| 2026-09-21 | $58.23 | $58.23 | $57.01 | $57.69 | 1,849,400 | 158,656,752 | 1.16% | $9.16B | — | — |
| 2026-09-18 | $58.83 | $59.01 | $57.27 | $57.31 | 3,442,500 | 158,656,752 | 2.17% | $9.10B | — | — |
| 2026-09-17 | $58.73 | $59.98 | $58.54 | $58.80 | 1,698,900 | 158,656,752 | 1.07% | $9.34B | — | — |
| 2026-09-16 | $57.99 | $59.52 | $57.28 | $58.48 | 1,914,200 | 158,656,752 | 1.21% | $9.29B | — | — |
| 2026-09-15 | $58.26 | $58.64 | $56.77 | $57.16 | 2,119,100 | 158,656,752 | 1.33% | $9.08B | — | — |
| 2026-09-14 | $60.11 | $60.11 | $57.60 | $57.78 | 3,233,300 | 158,656,752 | 2.04% | $9.18B | — | — |
| 2026-09-11 | $62.16 | $63.11 | $61.48 | $61.53 | 1,740,900 | 158,656,752 | 1.10% | $9.77B | — | — |
| 2026-09-10 | $62.21 | $63.27 | $61.23 | $61.56 | 1,780,000 | 158,656,752 | 1.12% | $9.78B | — | — |
| 2026-09-09 | $64.45 | $65.34 | $63.01 | $63.26 | 1,889,600 | 158,656,752 | 1.19% | $10.05B | — | — |
| 2026-09-08 | $64.73 | $65.68 | $64.31 | $64.53 | 1,930,700 | 158,656,752 | 1.22% | $10.25B | — | — |
| 2026-09-04 | $61.84 | $65.20 | $61.42 | $63.73 | 2,714,600 | 158,656,752 | 1.71% | $10.12B | — | — |
| 2026-09-03 | $62.32 | $62.33 | $60.35 | $61.37 | 2,073,100 | 158,656,752 | 1.31% | $9.75B | — | — |
| 2026-09-02 | $62.16 | $62.79 | $60.30 | $60.99 | 2,470,400 | 158,656,752 | 1.56% | $9.69B | — | — |
| 2026-09-01 | $62.80 | $64.00 | $60.66 | $61.73 | 2,998,200 | 158,656,752 | 1.89% | $9.81B | — | — |
| 2026-08-31 | $63.47 | $64.93 | $62.43 | $63.39 | 5,154,100 | 158,656,752 | 3.24% | $10.07B | — | — |
| 2026-08-28 | $65.00 | $67.50 | $63.13 | $63.53 | 16,466,600 | 158,656,752 | 10.37% | $10.09B | — | — |
| 2026-08-27 | $56.87 | $57.56 | $55.88 | $56.34 | 2,921,700 | 158,656,752 | 1.84% | $8.95B | $0.07 | — |
| 2026-08-26 | $55.22 | $56.96 | $55.00 | $56.37 | 2,594,600 | 158,656,752 | 1.63% | $8.95B | — | — |
| 2026-08-25 | $55.36 | $55.98 | $54.62 | $55.54 | 3,073,900 | 158,656,752 | 1.94% | $8.82B | — | — |
| 2026-08-24 | $55.95 | $56.09 | $54.56 | $55.36 | 2,149,700 | 158,656,752 | 1.35% | $8.79B | — | — |
| 2026-08-21 | $56.89 | $57.50 | $56.05 | $56.16 | 2,059,100 | 158,656,752 | 1.30% | $8.92B | — | — |
| 2026-08-20 | $56.57 | $56.97 | $55.43 | $56.62 | 2,365,200 | 158,656,752 | 1.49% | $8.99B | — | — |
| 2026-08-19 | $60.11 | $60.78 | $57.19 | $57.34 | 2,841,900 | 158,656,752 | 1.79% | $9.11B | — | — |
| 2026-08-18 | $61.22 | $61.35 | $60.01 | $60.09 | 1,880,400 | 158,656,752 | 1.18% | $9.54B | — | — |
| 2026-08-17 | $62.62 | $63.07 | $61.75 | $62.55 | 1,309,400 | 158,656,752 | 0.82% | $9.94B | — | — |
| 2026-08-14 | $62.51 | $63.68 | $62.09 | $62.65 | 1,086,100 | 158,656,752 | 0.68% | $9.95B | — | — |
| 2026-08-13 | $62.21 | $63.24 | $61.80 | $62.57 | 1,615,300 | — | 1.02% | $9.94B | — | — |
| 2026-08-12 | $62.50 | $62.98 | $61.38 | $62.21 | 1,538,000 | — | 0.97% | $9.88B | — | — |
| 2026-08-11 | $60.91 | $61.89 | $60.37 | $61.11 | 1,384,000 | — | 0.87% | $9.71B | — | — |
| 2026-08-10 | $61.10 | $61.44 | $59.47 | $60.32 | 1,571,000 | — | 0.99% | $9.58B | — | — |
| 2026-08-07 | $61.99 | $63.05 | $60.75 | $60.96 | 1,900,900 | — | 1.20% | $9.68B | — | — |
| 2026-08-06 | $62.18 | $63.49 | $61.49 | $62.18 | 1,311,800 | — | 0.83% | $9.88B | — | — |
| 2026-08-05 | $63.50 | $63.50 | $61.06 | $62.50 | 3,175,800 | — | 2.00% | $9.93B | — | — |
| 2026-08-04 | $63.20 | $64.74 | $62.12 | $63.52 | 2,570,600 | — | 1.62% | $10.09B | — | — |
| 2026-08-03 | $60.21 | $62.76 | $59.51 | $62.23 | 2,845,700 | — | 1.79% | $9.88B | — | — |
| 2026-07-31 | $58.96 | $60.86 | $57.86 | $60.17 | 3,965,700 | — | 2.50% | $9.56B | — | — |
| 2026-07-30 | $58.10 | $60.03 | $57.26 | $57.39 | 4,840,700 | — | 3.05% | $9.12B | — | — |
| 2026-07-29 | $57.48 | $58.29 | $53.87 | $55.66 | 6,858,500 | — | 4.32% | $8.84B | — | — |
| 2026-07-28 | $60.04 | $60.70 | $55.87 | $57.31 | 4,379,400 | — | 2.76% | $9.10B | — | — |
| 2026-07-27 | $60.65 | $61.69 | $58.84 | $60.59 | 3,920,100 | — | 2.47% | $9.62B | — | — |
| 2026-07-24 | $61.14 | $62.51 | $60.03 | $60.54 | 4,317,500 | — | 2.72% | $9.62B | — | — |
| 2026-07-23 | $60.10 | $61.97 | $60.10 | $60.88 | 2,705,300 | — | 1.70% | $9.67B | — | — |
| 2026-07-22 | $60.47 | $62.15 | $60.20 | $60.67 | 3,288,300 | — | 2.07% | $9.64B | — | — |
| 2026-07-21 | $57.13 | $60.40 | $56.33 | $60.08 | 4,811,500 | — | 3.03% | $9.54B | — | — |
| 2026-07-20 | $58.71 | $59.58 | $56.32 | $56.47 | 2,302,000 | — | 1.45% | $8.97B | — | — |
| 2026-07-17 | $56.50 | $59.48 | $56.20 | $58.38 | 2,702,700 | — | 1.70% | $9.27B | — | — |
| 2026-07-16 | $60.38 | $60.54 | $58.06 | $58.24 | 3,675,300 | — | 2.31% | $9.25B | — | — |
| 2026-07-15 | $62.97 | $63.53 | $59.87 | $61.03 | 4,633,900 | — | 2.92% | $9.69B | — | — |
| 2026-07-14 | $62.97 | $63.94 | $61.83 | $63.36 | 4,328,100 | — | 2.72% | $10.06B | — | — |
| 2026-07-13 | $62.14 | $63.44 | $60.25 | $61.06 | 3,780,100 | — | 2.38% | $9.70B | — | — |
| 2026-07-10 | $62.26 | $62.70 | $61.06 | $61.30 | 3,233,800 | — | 2.04% | $9.74B | — | — |
| 2026-07-09 | $63.85 | $64.46 | $61.78 | $62.80 | 6,732,400 | — | 4.24% | $9.98B | — | — |
| 2026-07-08 | $61.01 | $62.50 | $60.00 | $61.01 | 6,559,400 | — | 4.13% | $9.69B | — | — |
| 2026-07-07 | $68.27 | $68.59 | $60.35 | $62.10 | 15,011,200 | — | 9.45% | $9.86B | — | — |
| 2026-07-06 | $73.39 | $73.81 | $66.67 | $68.05 | 12,581,900 | — | 7.92% | $10.81B | — | — |
| 2026-07-02 | $82.80 | $85.50 | $79.30 | $80.19 | 1,953,900 | — | 1.23% | $12.74B | — | — |
| 2026-07-01 | $87.32 | $87.32 | $81.75 | $82.95 | 1,900,700 | — | 1.20% | $13.18B | — | — |
| 2026-06-30 | $84.45 | $90.25 | $83.52 | $88.60 | 1,797,600 | — | 1.13% | $14.07B | — | — |
| 2026-06-29 | $82.19 | $83.79 | $80.68 | $82.54 | 1,268,700 | — | 0.80% | $13.11B | — | — |
| 2026-06-26 | $85.60 | $85.62 | $81.48 | $82.69 | 7,581,000 | — | 4.77% | $13.13B | — | — |
| 2026-06-25 | $87.96 | $89.17 | $86.45 | $86.91 | 1,229,300 | — | 0.77% | $13.80B | — | — |
| 2026-06-24 | $84.71 | $88.08 | $83.29 | $86.66 | 1,320,700 | — | 0.83% | $13.76B | — | — |
| 2026-06-23 | $82.73 | $86.40 | $82.40 | $84.67 | 1,326,000 | — | 0.84% | $13.45B | — | — |
| 2026-06-22 | $85.79 | $87.89 | $85.17 | $86.95 | 924,700 | — | 0.58% | $13.81B | — | — |
| 2026-06-18 | $86.29 | $87.32 | $83.81 | $85.57 | 2,755,500 | — | 1.74% | $13.59B | — | — |
| 2026-06-17 | $84.04 | $86.61 | $84.04 | $85.14 | 1,532,300 | — | 0.96% | $13.52B | — | — |
| 2026-06-16 | $87.14 | $88.46 | $83.11 | $83.56 | 1,060,400 | — | 0.67% | $13.27B | — | — |
| 2026-06-15 | $85.08 | $87.25 | $84.01 | $86.66 | 1,280,000 | — | 0.81% | $13.76B | — | — |
| 2026-06-12 | $81.30 | $83.92 | $81.18 | $83.06 | 1,400,700 | — | 0.88% | $13.19B | — | — |
| 2026-06-11 | $77.62 | $81.28 | $77.61 | $81.17 | 1,518,200 | — | 0.96% | $12.89B | — | — |
| 2026-06-10 | $79.55 | $80.83 | $77.51 | $77.69 | 1,364,400 | — | 0.86% | $12.34B | — | — |
| 2026-06-09 | $82.49 | $82.60 | $76.99 | $80.28 | 2,577,900 | — | 1.62% | $12.75B | — | — |
| 2026-06-08 | $82.06 | $82.71 | $79.54 | $80.46 | 1,812,400 | — | 1.14% | $12.78B | — | — |
| 2026-06-05 | $84.56 | $85.61 | $80.20 | $81.02 | 2,150,400 | — | 1.35% | $12.87B | — | — |
| 2026-06-04 | $85.09 | $85.77 | $84.00 | $84.13 | 1,195,100 | — | 0.75% | $13.36B | — | — |
| 2026-06-03 | $87.05 | $89.72 | $86.47 | $86.60 | 1,341,000 | — | 0.84% | $13.75B | — | — |
| 2026-06-02 | $84.37 | $89.00 | $84.37 | $87.39 | 1,419,500 | — | 0.89% | $13.88B | — | — |
| 2026-06-01 | $84.53 | $85.14 | $82.59 | $83.78 | 1,484,200 | — | 0.93% | $13.30B | — | — |
| 2026-05-29 | $83.93 | $86.41 | $82.59 | $84.23 | 1,895,500 | — | 1.19% | $13.38B | — | — |
| 2026-05-28 | $85.55 | $86.02 | $84.06 | $84.57 | 1,783,600 | — | 1.12% | $13.43B | — | — |
| 2026-05-27 | $84.76 | $86.43 | $83.15 | $86.10 | 1,474,000 | — | 0.93% | $13.67B | $0.07 | — |
| 2026-05-26 | $83.21 | $84.86 | $81.31 | $84.64 | 1,806,100 | — | 1.14% | $13.44B | — | — |
| 2026-05-22 | $79.95 | $82.87 | $78.69 | $81.76 | 1,877,600 | — | 1.18% | $12.98B | — | — |
| 2026-05-21 | $80.94 | $82.64 | $78.50 | $79.38 | 2,859,400 | — | 1.80% | $12.61B | — | — |
| 2026-05-20 | $80.94 | $84.55 | $80.71 | $84.48 | 1,366,600 | — | 0.86% | $13.42B | — | — |
| 2026-05-19 | $80.34 | $81.30 | $78.31 | $79.87 | 1,529,500 | — | 0.96% | $12.68B | — | — |
| 2026-05-18 | $85.07 | $85.20 | $80.41 | $82.07 | 2,292,800 | — | 1.44% | $13.03B | — | — |
| 2026-05-15 | $83.99 | $85.97 | $83.04 | $85.11 | 2,003,300 | — | 1.26% | $13.52B | — | — |
| 2026-05-14 | $86.57 | $88.39 | $84.50 | $86.81 | 2,069,200 | — | 1.30% | $13.79B | — | — |
| 2026-05-13 | $90.75 | $90.80 | $86.51 | $88.57 | 3,439,800 | — | 2.17% | $14.06B | — | — |
| 2026-05-12 | $85.00 | $87.41 | $83.35 | $87.32 | 2,651,800 | — | 1.67% | $13.87B | — | — |
| 2026-05-11 | $79.42 | $86.79 | $78.72 | $85.42 | 4,010,200 | — | 2.53% | $13.56B | — | — |
| 2026-05-08 | $79.01 | $79.35 | $76.66 | $78.25 | 2,073,600 | — | 1.31% | $12.43B | — | — |
| 2026-05-07 | $83.24 | $83.98 | $77.47 | $77.76 | 2,444,900 | — | 1.54% | $12.35B | — | — |
| 2026-05-06 | $78.62 | $82.46 | $76.45 | $82.01 | 5,785,200 | — | 3.64% | $13.02B | — | — |
| 2026-05-05 | $83.00 | $84.99 | $82.61 | $83.56 | 2,882,800 | — | 1.82% | $13.27B | — | — |
| 2026-05-04 | $80.78 | $81.63 | $79.43 | $81.07 | 1,273,200 | — | 0.80% | $12.87B | — | — |
| 2026-05-01 | $81.78 | $82.89 | $80.26 | $80.59 | 1,328,400 | — | 0.84% | $12.80B | — | — |
| 2026-04-30 | $78.04 | $82.31 | $78.00 | $81.95 | 1,547,200 | — | 0.97% | $13.01B | — | — |
| 2026-04-29 | $79.53 | $80.00 | $76.03 | $76.96 | 1,523,900 | — | 0.96% | $12.22B | — | — |
| 2026-04-28 | $80.46 | $80.97 | $77.03 | $79.71 | 2,147,400 | — | 1.35% | $12.66B | — | — |
| 2026-04-27 | $82.13 | $83.47 | $79.50 | $81.37 | 1,443,100 | — | 0.91% | $12.92B | — | — |
| 2026-04-24 | $81.75 | $82.50 | $80.60 | $81.30 | 1,349,400 | — | 0.85% | $12.91B | — | — |
| 2026-04-23 | $81.85 | $82.97 | $80.18 | $81.05 | 1,773,200 | — | 1.12% | $12.87B | — | — |
| 2026-04-22 | $81.49 | $81.95 | $79.78 | $81.34 | 1,948,100 | — | 1.23% | $12.92B | — | — |
| 2026-04-21 | $82.50 | $84.00 | $78.16 | $80.33 | 2,326,100 | — | 1.46% | $12.76B | — | — |
| 2026-04-20 | $81.30 | $81.91 | $79.50 | $81.40 | 1,858,500 | — | 1.17% | $12.93B | — | — |
| 2026-04-17 | $81.02 | $82.00 | $78.83 | $81.20 | 2,660,300 | — | 1.68% | $12.89B | — | — |
| 2026-04-16 | $79.36 | $80.07 | $77.82 | $79.96 | 2,128,800 | — | 1.34% | $12.70B | — | — |
| 2026-04-15 | $79.80 | $81.26 | $78.56 | $79.24 | 1,787,400 | — | 1.13% | $12.58B | — | — |
| 2026-04-14 | $80.36 | $80.88 | $78.45 | $80.22 | 1,872,700 | — | 1.18% | $12.74B | — | — |
| 2026-04-13 | $81.72 | $82.34 | $81.30 | $82.01 | 1,270,800 | — | 0.80% | $13.02B | — | — |
| 2026-04-10 | $83.32 | $84.00 | $81.52 | $81.96 | 1,020,900 | — | 0.64% | $13.01B | — | — |
| 2026-04-09 | $83.26 | $83.96 | $81.60 | $82.81 | 1,779,100 | — | 1.12% | $13.15B | — | — |
| 2026-04-08 | $80.83 | $83.45 | $80.58 | $83.35 | 2,446,300 | — | 1.54% | $13.24B | — | — |
| 2026-04-07 | $77.80 | $79.28 | $76.82 | $77.55 | 1,080,600 | — | 0.68% | $12.31B | — | — |
| 2026-04-06 | $76.50 | $78.61 | $75.98 | $78.03 | 1,233,900 | — | 0.78% | $12.39B | — | — |
| 2026-04-02 | $75.40 | $79.85 | $74.95 | $76.42 | 1,656,500 | — | 1.04% | $12.14B | — | — |
| 2026-04-01 | $77.47 | $79.50 | $77.37 | $77.52 | 1,837,800 | — | 1.16% | $12.31B | — | — |
| 2026-03-31 | $72.74 | $76.67 | $72.60 | $76.16 | 2,023,900 | — | 1.27% | $12.09B | — | — |
| 2026-03-30 | $75.99 | $77.00 | $72.30 | $72.40 | 1,989,500 | — | 1.25% | $11.49B | — | — |
| 2026-03-27 | $73.78 | $75.60 | $73.30 | $75.03 | 1,722,400 | — | 1.08% | $11.91B | — | — |
| 2026-03-26 | $74.38 | $75.84 | $74.00 | $74.43 | 1,205,100 | — | 0.76% | $11.82B | — | — |
| 2026-03-25 | $73.47 | $76.47 | $73.45 | $76.35 | 1,673,600 | — | 1.05% | $12.12B | — | — |
| 2026-03-24 | $70.15 | $73.58 | $70.11 | $72.11 | 2,148,000 | — | 1.35% | $11.45B | — | — |
| 2026-03-23 | $69.46 | $72.02 | $69.00 | $70.95 | 2,571,800 | — | 1.62% | $11.26B | — | — |
| 2026-03-20 | $73.86 | $74.69 | $66.55 | $67.05 | 29,609,600 | — | 18.65% | $10.64B | — | — |
| 2026-03-19 | $71.91 | $73.43 | $70.12 | $73.08 | 1,788,600 | — | 1.13% | $11.60B | — | — |
| 2026-03-18 | $75.00 | $76.50 | $74.07 | $74.41 | 2,772,100 | — | 1.75% | $11.81B | — | — |
| 2026-03-17 | $73.78 | $75.67 | $71.82 | $75.15 | 1,487,800 | — | 0.94% | $11.93B | — | — |
| 2026-03-16 | $74.00 | $75.88 | $73.08 | $73.27 | 1,858,500 | — | 1.17% | $11.63B | — | — |
| 2026-03-13 | $72.28 | $74.21 | $71.24 | $73.22 | 2,394,400 | — | 1.51% | $11.62B | — | — |
| 2026-03-12 | $74.31 | $74.64 | $71.75 | $72.08 | 1,963,700 | — | 1.24% | $11.44B | — | — |
| 2026-03-11 | $75.51 | $75.55 | $72.61 | $75.18 | 1,605,200 | — | 1.01% | $11.93B | — | — |
| 2026-03-10 | $74.19 | $76.34 | $73.67 | $74.95 | 2,577,000 | — | 1.62% | $11.90B | — | — |
| 2026-03-09 | $70.36 | $73.93 | $69.00 | $73.87 | 3,540,800 | — | 2.23% | $11.73B | — | — |
| 2026-03-06 | $74.49 | $74.71 | $71.11 | $72.17 | 2,398,800 | — | 1.51% | $11.46B | — | — |
| 2026-03-05 | $74.25 | $78.81 | $74.23 | $76.72 | 3,598,800 | — | 2.27% | $12.18B | — | — |
| 2026-03-04 | $74.50 | $75.60 | $72.88 | $75.11 | 2,247,000 | — | 1.42% | $11.92B | — | — |
| 2026-03-03 | $75.00 | $75.44 | $72.25 | $73.90 | 2,575,800 | — | 1.62% | $11.73B | — | — |
| 2026-03-02 | $77.73 | $78.99 | $75.94 | $78.88 | 2,998,200 | — | 1.89% | $12.52B | — | — |
| 2026-02-27 | $76.12 | $78.59 | $74.13 | $78.51 | 3,219,600 | — | 2.03% | $12.46B | — | — |
| 2026-02-26 | $80.01 | $81.70 | $75.81 | $78.32 | 3,497,100 | — | 2.20% | $12.43B | — | — |
| 2026-02-25 | $80.83 | $80.99 | $76.77 | $79.87 | 2,921,900 | — | 1.84% | $12.68B | — | — |
| 2026-02-24 | $79.46 | $80.66 | $78.08 | $79.09 | 2,229,700 | — | 1.40% | $12.56B | $0.07 | — |
| 2026-02-23 | $80.00 | $80.89 | $77.69 | $78.55 | 2,409,900 | — | 1.52% | $12.47B | — | — |
| 2026-02-20 | $77.50 | $80.50 | $77.18 | $80.05 | 2,882,000 | — | 1.82% | $12.71B | — | — |
| 2026-02-19 | $80.84 | $80.90 | $77.45 | $77.86 | 2,485,400 | — | 1.57% | $12.36B | — | — |
| 2026-02-18 | $81.57 | $82.88 | $78.50 | $80.92 | 3,336,600 | — | 2.10% | $12.85B | — | — |
| 2026-02-17 | $78.06 | $83.31 | $77.60 | $80.90 | 4,671,700 | — | 2.94% | $12.84B | — | — |
| 2026-02-13 | $77.00 | $79.75 | $75.66 | $78.22 | 4,663,300 | — | 2.94% | $12.42B | — | — |
| 2026-02-12 | $78.66 | $84.44 | $77.44 | $78.03 | 9,358,900 | — | 5.90% | $12.39B | — | — |
| 2026-02-11 | $67.58 | $75.43 | $66.11 | $74.95 | 7,784,700 | — | 4.90% | $11.90B | — | — |
| 2026-02-10 | $64.70 | $65.33 | $63.52 | $63.80 | 2,582,800 | — | 1.63% | $10.13B | — | — |
| 2026-02-09 | $64.91 | $65.86 | $63.90 | $64.66 | 2,569,300 | — | 1.62% | $10.26B | — | — |
| 2026-02-06 | $63.42 | $65.19 | $63.04 | $64.79 | 2,237,500 | — | 1.41% | $10.29B | — | — |
| 2026-02-05 | $63.78 | $64.95 | $62.91 | $63.42 | 2,257,800 | — | 1.42% | $10.07B | — | — |
| 2026-02-04 | $66.41 | $67.74 | $63.54 | $65.22 | 2,949,900 | — | 1.86% | $10.35B | — | — |
| 2026-02-03 | $65.00 | $66.84 | $64.60 | $66.26 | 1,861,400 | — | 1.17% | $10.52B | — | — |
| 2026-02-02 | $61.45 | $64.51 | $61.19 | $64.39 | 1,845,000 | — | 1.16% | $10.22B | — | — |
| 2026-01-30 | $62.70 | $63.96 | $60.64 | $61.77 | 2,060,000 | — | 1.30% | $9.81B | — | — |
| 2026-01-29 | $65.99 | $66.05 | $62.71 | $63.59 | 2,216,200 | — | 1.40% | $10.09B | — | — |
| 2026-01-28 | $62.88 | $65.79 | $62.25 | $65.57 | 3,509,900 | — | 2.21% | $10.41B | — | — |
| 2026-01-27 | $62.00 | $62.84 | $61.61 | $62.36 | 2,225,400 | — | 1.40% | $9.90B | — | — |
| 2026-01-26 | $62.66 | $62.99 | $61.10 | $61.49 | 2,657,100 | — | 1.67% | $9.76B | — | — |
| 2026-01-23 | $62.68 | $63.75 | $61.69 | $62.84 | 2,706,600 | — | 1.70% | $9.98B | — | — |
| 2026-01-22 | $63.54 | $64.31 | $62.38 | $62.92 | 2,197,100 | — | 1.38% | $9.99B | — | — |
| 2026-01-21 | $61.66 | $63.77 | $61.22 | $63.43 | 2,148,100 | — | 1.35% | $10.07B | — | — |
| 2026-01-20 | $61.08 | $62.86 | $59.82 | $61.56 | 2,957,600 | — | 1.86% | $9.77B | — | — |
| 2026-01-16 | $61.20 | $61.60 | $59.60 | $60.89 | 3,140,500 | — | 1.98% | $9.67B | — | — |
| 2026-01-15 | $57.90 | $60.87 | $56.45 | $60.51 | 4,202,500 | — | 2.65% | $9.61B | — | — |
| 2026-01-14 | $55.00 | $58.10 | $54.63 | $57.37 | 4,474,600 | — | 2.82% | $9.11B | — | — |
| 2026-01-13 | $53.56 | $55.54 | $52.84 | $55.01 | 3,243,700 | — | 2.04% | $8.73B | — | — |
| 2026-01-12 | $53.09 | $53.50 | $51.55 | $52.01 | 2,013,900 | — | 1.27% | $8.26B | — | — |
| 2026-01-09 | $52.11 | $53.68 | $52.05 | $53.03 | 2,660,900 | — | 1.68% | $8.42B | — | — |
| 2026-01-08 | $51.80 | $54.25 | $51.72 | $52.11 | 3,404,700 | — | 2.14% | $8.27B | — | — |
| 2026-01-07 | $50.85 | $52.21 | $49.55 | $51.98 | 2,787,600 | — | 1.76% | $8.25B | — | — |
| 2026-01-06 | $49.06 | $49.99 | $48.75 | $49.73 | 2,259,600 | — | 1.42% | $7.89B | — | — |
| 2026-01-05 | $49.28 | $50.22 | $48.77 | $49.33 | 1,886,300 | — | 1.19% | $7.83B | — | — |
| 2026-01-02 | $48.51 | $49.31 | $48.23 | $49.28 | 1,426,300 | — | 0.90% | $7.82B | — | — |
| 2025-12-31 | $48.91 | $49.29 | $48.44 | $48.58 | 1,162,000 | — | 0.73% | $7.71B | — | — |
| 2025-12-30 | $49.11 | $49.53 | $48.84 | $48.86 | 947,600 | — | 0.60% | $7.76B | — | — |
| 2025-12-29 | $49.66 | $50.39 | $49.01 | $49.29 | 1,760,500 | — | 1.11% | $7.82B | — | — |
| 2025-12-26 | $49.89 | $50.37 | $49.51 | $49.77 | 784,800 | — | 0.49% | $7.90B | — | — |
| 2025-12-24 | $49.30 | $49.90 | $48.27 | $49.61 | 1,124,400 | — | 0.71% | $7.87B | — | — |
| 2025-12-23 | $49.92 | $50.05 | $48.72 | $48.75 | 1,812,300 | — | 1.14% | $7.74B | — | — |
| 2025-12-22 | $50.63 | $51.82 | $49.41 | $50.14 | 3,325,200 | — | 2.10% | $7.96B | — | — |
| 2025-12-19 | $48.58 | $50.70 | $48.08 | $50.35 | 37,846,300 | — | 23.84% | $7.99B | — | — |
| 2025-12-18 | $49.08 | $49.60 | $47.30 | $48.58 | 2,729,300 | — | 1.72% | $7.71B | — | — |
| 2025-12-17 | $47.83 | $49.75 | $47.83 | $48.86 | 2,731,700 | — | 1.72% | $7.76B | — | — |
| 2025-12-16 | $48.49 | $49.24 | $47.63 | $47.97 | 1,753,600 | — | 1.10% | $7.61B | — | — |
| 2025-12-15 | $49.59 | $50.26 | $48.62 | $48.77 | 2,119,500 | — | 1.34% | $7.74B | — | — |
| 2025-12-12 | $50.83 | $51.72 | $49.31 | $49.99 | 2,524,200 | — | 1.59% | $7.93B | — | — |
| 2025-12-11 | $49.22 | $50.58 | $48.96 | $50.28 | 2,842,000 | — | 1.79% | $7.98B | — | — |
| 2025-12-10 | $47.47 | $49.27 | $46.99 | $49.08 | 2,997,600 | — | 1.89% | $7.79B | — | — |
| 2025-12-09 | $46.32 | $48.29 | $45.73 | $47.39 | 2,805,900 | — | 1.77% | $7.52B | — | — |
| 2025-12-08 | $47.17 | $48.40 | $46.53 | $46.69 | 2,058,200 | — | 1.30% | $7.41B | — | — |
| 2025-12-05 | $46.63 | $47.95 | $46.59 | $47.13 | 2,207,000 | — | 1.39% | $7.48B | — | — |
| 2025-12-04 | $47.32 | $47.88 | $46.35 | $46.96 | 2,499,700 | — | 1.57% | $7.45B | — | — |
| 2025-12-03 | $46.51 | $47.78 | $46.42 | $47.57 | 2,727,900 | — | 1.72% | $7.55B | — | — |
| 2025-12-02 | $47.58 | $47.94 | $46.20 | $46.65 | 2,984,300 | — | 1.88% | $7.40B | — | — |
| 2025-12-01 | $47.65 | $49.27 | $47.28 | $47.72 | 2,586,200 | — | 1.63% | $7.57B | — | — |
| 2025-11-28 | $46.18 | $47.74 | $46.07 | $47.68 | 1,110,900 | — | 0.70% | $7.57B | — | — |
| 2025-11-26 | $46.74 | $47.15 | $45.51 | $46.23 | 2,534,400 | — | 1.60% | $7.34B | — | — |
| 2025-11-25 | $45.37 | $47.00 | $44.81 | $46.89 | 3,060,200 | — | 1.93% | $7.44B | — | — |
| 2025-11-24 | $44.84 | $46.00 | $44.71 | $45.47 | 3,193,800 | — | 2.01% | $7.22B | — | — |
| 2025-11-21 | $43.49 | $45.46 | $43.30 | $44.44 | 3,811,600 | — | 2.40% | $7.05B | — | — |
| 2025-11-20 | $45.18 | $46.67 | $42.77 | $43.25 | 4,882,400 | — | 3.08% | $6.86B | — | — |
| 2025-11-19 | $41.58 | $43.75 | $41.32 | $42.72 | 4,270,700 | — | 2.69% | $6.78B | — | — |
| 2025-11-18 | $41.04 | $42.54 | $40.43 | $41.43 | 3,535,600 | — | 2.23% | $6.58B | — | — |
| 2025-11-17 | $43.12 | $43.80 | $41.03 | $41.58 | 4,173,600 | — | 2.63% | $6.60B | — | — |
| 2025-11-14 | $45.09 | $46.01 | $43.47 | $43.56 | 3,378,800 | — | 2.13% | $6.91B | — | — |
| 2025-11-13 | $46.34 | $47.47 | $45.45 | $45.73 | 2,813,400 | — | 1.77% | $7.26B | — | — |
| 2025-11-12 | $46.12 | $47.09 | $45.47 | $46.93 | 3,171,200 | — | 2.00% | $7.45B | — | — |
| 2025-11-11 | $47.24 | $49.98 | $46.00 | $46.12 | 3,259,400 | — | 2.05% | $7.32B | — | — |
| 2025-11-10 | $47.28 | $49.00 | $46.63 | $47.19 | 4,771,100 | — | 3.01% | $7.49B | — | — |
| 2025-11-07 | $44.44 | $48.38 | $44.08 | $47.49 | 12,997,200 | — | 8.19% | $7.54B | — | — |
| 2025-11-06 | $47.00 | $48.00 | $44.47 | $45.02 | 7,744,500 | — | 4.88% | $7.15B | — | — |
| 2025-11-05 | $43.89 | $49.70 | $43.00 | $48.33 | 10,252,200 | — | 6.46% | $7.67B | — | — |
| 2025-11-04 | $42.19 | $44.53 | $41.00 | $43.65 | 11,057,900 | — | 6.97% | $6.93B | — | — |
| 2025-11-03 | $45.00 | $46.25 | $43.82 | $44.01 | 13,738,200 | — | 8.66% | $6.99B | — | — |
| 2025-10-31 | $48.88 | $49.36 | $44.80 | $45.07 | 14,246,100 | — | 8.98% | $7.15B | — | — |
| 2025-10-30 | $48.60 | $53.80 | $47.60 | $48.74 | 23,638,000 | — | 14.89% | $7.74B | — | — |
Close is split-adjusted to current shares. It is not dividend-adjusted: dividends are listed separately, so total return is (end price + dividends received − start price) ÷ start price, checkable by hand. Volume is as-traded.
Momentum: MACD and RSI
Top: MACD (navy) and its signal line (gold); bars show the gap between them, teal when MACD is above.
Bottom: RSI over 14 days; above 70 is usually read as overbought and below 30 as oversold.
The lines start late because MACD needs 26 trading days of prices and RSI 14 before the first value.
The colored strip under the charts shows the state label day by day; hover for the state and the reason.
Both measure momentum in the price and say nothing about value. Hover for each day's arithmetic.
Source: closing prices from this site's daily price archive (Yahoo Finance), not adjusted for dividends. Data through Nov 14, 2026.
How these are calculated
Short Selling
Bars: shares sold short each day in trades reported to FINRA (off-exchange
trades, roughly half of all volume).
Line: the short share of that volume, averaged over 20 sessions.
Gold points: short interest, the shares sold short and not yet bought back,
reported twice a month, also shown as a percentage of the free float and of
shares outstanding.
Daily short volume includes market makers' routine hedging, so a change in the
share is more informative than its level. Hover for each day's figures.
Sources: FINRA; float from this site's daily share records; shares outstanding
from the company's latest quarterly filing. Data through Nov 13, 2026.
Index-Fund Holdings
Daily positions of State Street's SPDR index funds, by the fund's file date.
These are the index funds whose daily holdings can be collected; iShares and
Vanguard funds, often larger holders, publish holdings that cannot be
collected automatically and appear in the written analysis from their
quarterly filings.
Collection began on October 11, 2026. A fund that drops the stock shows as an
exit.
Source: State Street Global Advisors. Data through
Nov 12, 2026.
Update — November 4, 2026: third-quarter results — HOLD, target $57 → $58
Rated at the November 4, 2026 close of $57.70. The results were released before the open that day. Source: the third-quarter results release of November 4, 2026. The analyses below are left as published; this short section tests the results against the October 15, 2026 update. The scenarios and weights are unchanged except for the September 30, 2026 balances.
Overview Summary
The third quarter met neither of the tests the October 15, 2026 update set for the weights. Refrigerant sales grew 8%, half the first half’s 16%, and the segment margin was 34.5%, between the mid-30s the best case needs and the 30% that would raise the worst case. Guidance was raised slightly, to adjusted EBITDA of $1,050–1,060 million, which the base case already assumed. With net debt of $1.25 billion and 157.2 million shares after the buyback, the target moves from $57 to $58. The stock fell 6.5% on the day to $57.70, two cents below the $57.72 best-guess value.
Rating: BUY below $46.18 · ACCUMULATE $46.18–52.47 · HOLD $52.47–64.14 · TRIM $64.14–76.96 · SELL above $76.96 · Target $58
The quarter against the tests
| Test (October 15, 2026) | Third quarter 2026 | Verdict |
|---|---|---|
| Refrigerant growth near the first half’s 16%, with the segment margin in the mid-30s would raise the best case | Refrigerants $433 million, +8%, on automotive and data-center demand; Refrigerants & Applied Solutions margin 34.5%, down 0.8 points on a year earlier on higher research spending and up 1.6 points on the second quarter | Not met |
| Refrigerant sales falling, or a segment margin below 30%, would raise the worst case | Neither | Passes |
| Electronic & Specialty Materials | Record sales of $320 million, +13%; electronic materials +31% (sputtering targets and thermal materials for memory and AI chips); margin 21.2%, against 16.7% | Ahead of the base case |
| Nuclear | Sales $66 million, +4% | In line |
- Net sales were $1,046 million, up 8%, with organic growth of 8% from both volume and price; adjusted EBITDA was $265 million, a 25.3% margin, up 13%. Healthcare packaging grew 24% after destocking in the second half of 2025; building solutions and intermediates fell 5% on weak construction.
- Guidance was raised for the second quarter running: net sales $4,195–4,220 million (from $4,125–4,185 million), adjusted EBITDA $1,050–1,060 million (from $1,035–1,055 million), adjusted earnings per share $2.90–2.95. The fourth quarter is guided to sales of $1,010–1,035 million and EBITDA of $246–256 million. The base case already has 2026 at sales of $4,193 million and EBITDA of $1,048 million, so the guidance does not change it.
- Free cash flow was $368 million in nine months, after capital spending of $325 million (guided to $420–440 million for the year).
The balances and the buyback
- Net debt was $1,254 million at September 30, 2026: total debt of $1,968 million less cash of $714 million, 1.3 times trailing EBITDA, against $1,222 million at June 30, 2026.
- Solstice bought 1.7 million shares for $100 million in the quarter and intends to complete most of the $500 million authorization by the end of the first quarter of 2027. Shares outstanding were 157.2 million, against the 158.9 million the cases used. At $57.70 the remaining $400 million would buy about 6.9 million shares, about 4.4% of the total.
- The quarterly dividend stays at $0.075 (declared November 3, 2026, payable December 10, 2026).
| Best | Base | Worst | Weighted (30 / 45 / 25) | |
|---|---|---|---|---|
| October 15, 2026 | $82.62 | $57.39 | $26.81 | $57.31 |
| November 4, 2026 (net debt and shares at September 30, 2026) | $83.30 | $57.80 | $26.89 | $57.72 |
| vs $57.70 | +44% | +0% | −53% | +0.0% |
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $56.45 | −2% | 0.8 to 1 |
| Best guess: 30 / 45 / 25 (unchanged) | $57.72 | +0.0% | 1.00 to 1 |
| Stress: 10 / 40 / 50 | $44.90 | −22% | 0.2 to 1 |
| What the price implies: 30 / 45 / 25 | $57.70 | 0% | 1.0 to 1 |
The weights are a judgement. All values are estimates from the model. Gain to loss is (30% × best gain + 45% × any base gain) ÷ (25% × worst loss + 45% × any base loss). Both header chips take the color of the rating band the price is in: BUY green (an expected return of +25% or more with gain to loss of 3 to 1 or better), ACCUMULATE blue (+10% to +25%), HOLD gold (−10% to +10%), TRIM orange (−25% to −10%) and SELL red (below −25%). On the best guess they are green below $46.18, blue up to $52.47, gold up to $64.14, orange up to $76.96 and red above. At $57.70 both are gold, the HOLD band.
What it means for the rating
HOLD, target $57 → $58. The target is the best-guess value, $57.72. At $57.70 the expected return is +0.0%, inside the HOLD band of −10% to +10%. The quarter answered neither question the weights turn on: refrigerant growth slowed without turning negative, and the margin held between the two tests. The next test is the 2027 guidance in February 2027, the first to show whether refrigerant growth settles nearer the base case’s 3–7% a year or the best case’s 10%.
| Action | Level | Reason |
|---|---|---|
| Buy | Below about $46.18 | Expected return 25% or more on the best guess; gain to loss is 3.4 to 1 there |
| Accumulate | $46.18–52.47 | Expected return 10–25% |
| Hold | $52.47–64.14 | Expected return −10% to +10%, around the $58 target |
| Trim | $64.14–76.96 | Expected return −10% to −25% |
| Sell | Above about $76.96 | Expected return below −25% |
The table of what the fourth-quarter results must show, in the October 15, 2026 update below, stands, with refrigerant growth now measured against the third quarter’s 8%.
Update — October 15, 2026: the scenarios, the money, the debt and where Solstice is — HOLD, target $62 → $57
Written against the October 14, 2026 close of $60.13. Sources: Solstice’s FY2025 10-K, its second-quarter 2026 10-Q and results, the credit agreement and notes indenture, the 8-K of August 27, 2026; Chemours’ 2026 results for refrigerant markets; the EPA’s HFC rules and the EU’s F-gas regulation and PFAS process; Cameco’s 2025 and 2026 reports for uranium-conversion prices; EPA records, the company’s careers site and Honeywell releases for the plants. The analyses below are left as published; this section builds the three cases line by line, adds the money, the debt, the footprint, short interest and volatility, and corrects the valuation for General Atomics' share of ConverDyn. The rating is unchanged; the target moves from $62 to $57.
The one-line version
Solstice is three businesses, and refrigerant pricing decides most of the value. Built line by line, it is worth $57.39 in the base case, $82.62 in the best and $26.81 in the worst; weighted 30% best, 45% base and 25% worst, about $57, 5% below the price. Refrigerants are the swing factor: a fall in prices as the newer refrigerants commoditise would cost about $13 a share on its own, and Chemours, the closest competitor, has just warned of destocking in the air-conditioning aftermarket. Nuclear is the steadiest part: Metropolis is the only U.S. uranium converter and is contracted through 2030 at rising prices. The debt is light: $2.0 billion with net leverage of about 1.3 times and nothing due before 2032. A correction: the August 24, 2026 valuation did not deduct General Atomics’ half of ConverDyn, which Solstice consolidates; doing so takes about $4.50 off every value.
What happened since September 2, 2026
| Date | Event | Read |
|---|---|---|
| Sep 3, 2026 | Jefferies starts at Buy, $86 | Analysts’ average target is about $78; the low is $60 |
| Sep 9–10, 2026 | Solstice asserts its patents on making HFO-1234ze against an unnamed competitor, a month after Chemours launched its own 1234ze | The patent position is being defended in public |
| Sep 14 and 24, 2026 | Shares fall 6.1% and 3.4% with no reported reason | Short interest halved in September as merger-arbitrage positions closed |
| Sep 29, 2026 | Metropolis lawsuits settled in principle for a reported ~$80 million | Management calls it immaterial; the Department of Energy is expected to reimburse much of it |
| Oct 1–5, 2026 | Mizuho cuts its target to $65, UBS to $76 | Valuation and sector moves; no change in the business reported |
| ~Oct 10, 2026 | A $49 million expansion of the Buffalo research centre | |
| Oct 12, 2026 | Barclays starts at Overweight, $73 | |
| Nov 4, 2026 | Third-quarter results, before the open | The first test of refrigerant demand after Chemours’ warning |
No buybacks under the $500 million authorisation have been disclosed, and insiders have neither bought nor sold.
How the money moves
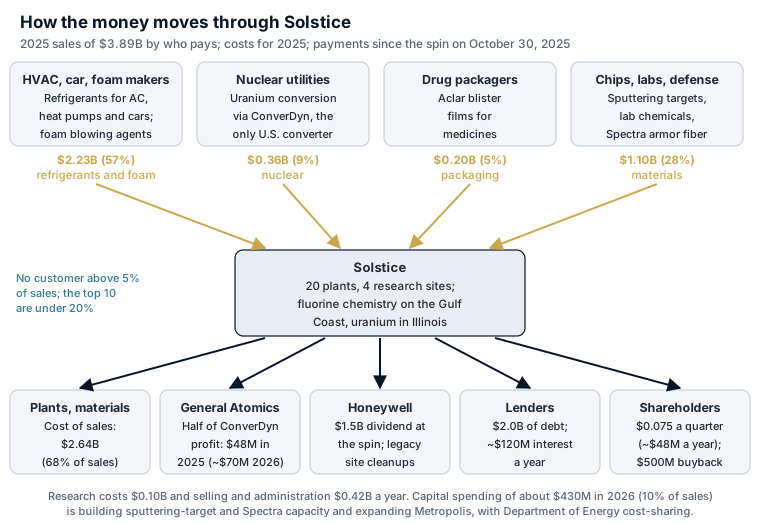
Who pays:
- Air-conditioning, car and foam makers pay for refrigerants and foam blowing agents: $2.23 billion, 57% of 2025 sales, of which refrigerants were $1.51 billion.
- Nuclear utilities pay for uranium conversion through ConverDyn, the joint venture with General Atomics that markets everything Metropolis produces: $356 million, 9%.
- Drug packagers buy Aclar blister films: $204 million, 5%.
- Chipmakers, laboratories and defense contractors buy sputtering targets and other electronic materials, lab chemicals (Fluka, Hydranal) and Spectra fiber for armor: $1.10 billion, 28%.
- No customer is above 5% of sales, and the top 10 are under 20%. 57% of sales go outside the U.S., counting exports.
Where each $100 of revenue went, 2025, as if standalone (2025 results with standalone costs, interest and estimated taxes). The add-back line reverses depreciation, stock compensation, spin costs and the standalone-cost adjustment in the company’s adjusted standalone EBITDA. 2025 capital spending was high (10.5% of sales) because of new capacity for sputtering targets and Spectra fiber; 2026 guidance is $420–440M on about $4.15B of sales, and free cash flow should rise as the projects finish. Source: the FY2025 10-K and the Q4 2025 results; per-$100 figures are calculations.
About $6 of each $100 became free cash flow in 2025 (an estimate on a standalone basis), held down by capital spending of 10.5% of sales on new capacity for sputtering targets and Spectra fiber. Spending is guided to stay near 10% in 2026; as those projects finish, free cash flow should rise.
The debt, tranche by tranche
The $2.0 billion was raised at the spin, and $1.5 billion of it went to Honeywell as a dividend.
| Tranche | Amount ($M) | Rate | Matures | Repaying early | Security | Notes |
|---|---|---|---|---|---|---|
| Term loan B | 1,000 | SOFR + 1.75%, no floor (5.41% at June 30, 2026) | October 29, 2032 | At par | First lien; U.S. subsidiaries guarantee | Repays $10M a year |
| 5.625% senior notes | 1,000 | 5.625% fixed | September 30, 2033 | Make-whole to September 30, 2028; then 102.813%, 101.406%, par from 2030 | Senior unsecured | |
| Total drawn | 2,000 | ~5.5% (term loan floating at 5.41% at June 30, 2026; notes fixed at 5.625%) | ||||
| Revolving credit | $1,000M | SOFR + 1.50–2.00% by first-lien leverage; 0.25–0.35% on the unused amount | October 2030 | First lien | Undrawn | |
| Letter-of-credit facilities | $750M, uncommitted | 0.60–0.95% | — | — | $276M of letters of credit issued |
The $2.0 billion was raised at the spin; $1.5 billion of it was paid to Honeywell as a dividend. The term loan floats with no swaps and repays $10M a year; the notes are a bullet. Finance leases of $109M and $276M of letters of credit are not shown. Source: the second-quarter 2026 10-Q, the credit agreement and the notes indenture. As of June 30, 2026.
Principal due by year, including scheduled amortization. Nothing beyond $10M a year is due before October 2032.
Solstice can repay all its debt from its own cash, even in the worst case. Comparing the cash available by October 2032 with the term loan due then (estimates):
| Base case | Worst case | |
|---|---|---|
| Free cash flow, July 2026–October 2032 | $2.82B | $1.74B |
| Dividends at $0.075 a quarter | − ~$0.30B | − ~$0.30B |
| Cash at June 30, 2026 | + ~$0.75B | + ~$0.75B |
| Available to repay debt | = ~$3.27B | = ~$2.19B |
| Term loan, due 2026–2032 | − $1.00B | − $1.00B |
| Cash left after repaying it | = ~$2.27B | = ~$1.19B |
Both cases also cover the $1.0 billion of notes due in 2033, the worst case with about $0.19 billion to spare, before any buybacks. The $500 million buyback would use about a fifth of the base case’s surplus.
Interest expense, 2026–2031
Half the debt floats. The term loan pays SOFR plus 1.75% with no swaps; the notes are fixed at 5.625%. On the SOFR path priced in fed funds futures on October 9, 2026, as on the site’s other profiles (all figures estimates, $ millions):
| $ millions | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 |
|---|---|---|---|---|---|---|
| SOFR, yearly average | ~3.75% | ~4.40% | ~4.65% | ~4.65% | ~4.65% | ~4.65% |
| Term loan (SOFR + 1.75%) | $55 | $61 | $62 | $62 | $61 | $61 |
| 5.625% notes (fixed) | + $56 | + $56 | + $56 | + $56 | + $56 | + $56 |
| Revolver fee (0.25% on $1.0B undrawn) | + $3 | + $3 | + $3 | + $3 | + $3 | + $3 |
| Issuance costs written off over the term (non-cash) | + $4 | + $4 | + $4 | + $4 | + $4 | + $4 |
| Interest expense | = ~$117 | = ~$123 | = ~$125 | = ~$125 | = ~$124 | = ~$123 |
What a change in rates would do (interest expense, $ millions):
| SOFR path | 2027 | 2028 | 2029 | 2030 | 2031 | 2026–2031 | Change |
|---|---|---|---|---|---|---|---|
| 1 point lower | $113 | $115 | $115 | $114 | $114 | $679 | − $59 |
| Futures path | $123 | $125 | $125 | $124 | $123 | $738 | |
| 1 point higher | $133 | $135 | $134 | $133 | $133 | $796 | + $58 |
| 2 points higher | $143 | $145 | $144 | $143 | $142 | $854 | + $116 |
Each point of SOFR costs about $10 million a year, about $0.05 a share after tax, which matches the company’s own estimate.
| Covenant | Limit | Now | Room | Protects |
|---|---|---|---|---|
| First-lien net leverage (first-lien debt less all unrestricted cash, over EBITDA as the agreement defines it) | 3.50×; 4.00× for four quarters after an acquisition of $250M or more | ~0.25× at June 30, 2026 (an estimate) | Very wide | Revolver; term lenders act only after revolver lenders accelerate |
| Interest coverage (EBITDA over net interest) | At least 2.75× | ~10× (an estimate) | EBITDA could fall about 70% | Revolver |
| Excess cash flow sweep | 50% above 2.50× first-lien leverage, 25% to 2.00×, none at or below 2.00× | ~0.25×, so no sweep | — | Term loan |
| Dividends and buybacks | Unlimited at total net leverage of 3.25× or less (3.50× under the notes); otherwise baskets of $350M or more | ~1.3× net leverage | Wide; the $500M buyback fits | Credit agreement and notes |
| Change of control | Notes: 101% repurchase if anyone acquires over 50%; bank debt: default at 35% of the votes | — | — | Notes; bank debt |
| Mergers and buybacks (tax matters agreement with Honeywell, not the debt) | Through October 30, 2027: no sale of 40% or more of the stock in a combined transaction, no merger, no sale of 30% or more of an active business; buybacks only on the open market and below 20% of the shares | $500M authorized August 27, 2026; none disclosed | Restrictions end October 30, 2027 | Shares and M&A |
No credit ratings are disclosed. The notes’ covenants fall away if two agencies rate them investment grade.
The covenants have room in every case. Even in the worst case, with EBITDA falling to about $750 million by 2030, interest coverage stays above six times against the 2.75 minimum, and first-lien net leverage stays under one time.
Where Solstice is
The plants follow the chemistry. The 10-K counts 20 plants (16 in the Americas) and four research sites but names only the head office in Morris Plains, New Jersey, the Buffalo research centre and Metropolis; the sites below come from EPA records, the careers site and Honeywell releases.
The 10-K counts 20 plants, 16 of them in the Americas, and 4 research sites; about 15 are located here. Refrigerants are made on the Gulf Coast, uranium conversion at Metropolis, and electronic materials in Spokane and Pennsylvania. Click a point for details. Map data © OpenStreetMap contributors. Source: the FY2025 10-K (Morris Plains, Buffalo, Metropolis and the counts) and, for the other sites, EPA records, the company’s careers site and Honeywell press releases; coordinates from OpenStreetMap. As of October 15, 2026.
Outside the U.S. Solstice has one European plant (Seelze, lab chemicals), plants in Korea, Thailand and Japan, joint ventures in Mexico, China and Taiwan, and sales and service offices; 43% of 2025 sales originated outside the U.S. Click a point for details. Map data © OpenStreetMap contributors. Source: the FY2025 10-K (Morris Plains, Buffalo, Metropolis and the counts) and, for the other sites, EPA records, the company’s careers site and Honeywell press releases; coordinates from OpenStreetMap. As of October 15, 2026.
- Refrigerants come from the Gulf Coast. Geismar, Louisiana makes hydrofluoric acid and HFO-1234yf for cars; Baton Rouge makes Solstice ze for chillers and foam, its capacity doubled in 2021.
- Metropolis, Illinois is the only uranium-conversion plant in the U.S. Idle from 2017 to 2023, it is being debottlenecked to about 10,000 tonnes a year, with Department of Energy cost-sharing, and a second plant is under study.
- Electronic materials are made in Spokane, Washington (sputtering targets; a $200 million expansion to double capacity by 2029), Fombell, Pennsylvania (high-purity metals), Bryan, Texas and Muskegon, Michigan; Spectra fiber in Colonial Heights, Virginia (a $220 million expansion to 2030).
- Abroad, there is one European plant (Seelze, Germany, lab chemicals, about 650 staff), plants in Korea, Thailand and Japan, and joint ventures in Mexico, China and Taiwan. About 4,100 people work for Solstice; the 10-K gives no regional split.
The scenarios and the asymmetry
The August 24, 2026 valuation moved one lever, the company margin. The model now builds each product line: refrigerants, foam blowing agents, nuclear, packaging, electronic materials, lab chemicals and Spectra fiber, with nuclear’s margin modelled separately and General Atomics’ share of it deducted. It keeps the August method, an 11% discount rate and an exit at 11 times 2033 EBITDA, and reproduces the August value of $69 to within two cents before the changes.
| Best | Base | Worst | |
|---|---|---|---|
| Refrigerants | +10% a year from volume and price; margin back to 38% | Aftermarket destocking in 2027 (+3%), then +6–7% a year | Destocking (−8% in 2027), then prices falling as the newer refrigerants commoditise; margin to 28% |
| Nuclear | Contracts reprice to today’s prices; EBITDA ~$290M by 2030 | “Double-digit” EBITDA growth as guided; ~$205M by 2030 | Plant output and margin flat |
| Electronic and specialty materials | Sputtering targets +15% a year; margin 24.5% | +11% a year; margin 21.5% | A 2023-style downturn in 2027 |
| Company EBITDA, 2030 | $1.81B (30.7%) | $1.37B (26.7%) | $0.75B (19.1%) |
| Value per share | $82.62 | $57.39 | $26.81 |
| vs $60.13 | +37% | −5% | −55% |
Stress tests on the base case, one change at a time (estimates):
| Change | Value | Change |
|---|---|---|
| Refrigerant prices falling: growth 1% a year, margin to 31% | $44.31 | −$13.08 |
| Exit multiple 9×, if EU limits on PFAS reach HFO refrigerants after 2032 | $48.61 | −$8.78 |
| Refrigerant destocking in 2027 (−8%), then the base path | $53.21 | −$4.18 |
| Discount rate 12% | $53.86 | −$3.53 |
| A 2023-style materials downturn in 2027 | $54.61 | −$2.77 |
| Metropolis flat, nuclear margin stuck at 31% | $54.76 | −$2.63 |
| Nuclear repricing as in the best case | $60.61 | +$3.22 |
| Discount rate 10% | $61.17 | +$3.78 |
Refrigerant pricing matters most, and nuclear least, despite its profile. The evidence on refrigerants cuts both ways:
- For the price holding: the U.S. cuts HFC supply to 30% of its baseline in 2029, and the EPA is enforcing the allowance system; the 2026 changes to the rules delayed commercial refrigeration but left home air-conditioning on the new refrigerants; Solstice’s patents on 1234yf run into the 2030s; U.S. air-conditioning shipments are up 6% this year through August.
- Against it: Chemours guided its third-quarter refrigerant earnings down to $125–140 million on destocking after the 2025 shortage, and its price gains slowed from 11% in the first quarter to 2% in the second; Chemours has added about 40% to its 1234yf capacity and doubled its supply from China; the EU’s PFAS restriction keeps HFO refrigerants in scope, with exemptions that may run only to about 2032–2039.
- Nuclear is contracted through 2030 at prices rising toward today’s long-term level of about $55 per kilogram of uranium, against $18–40 when the older contracts were signed; electronic materials grew 15–21% in each of the last three quarters.
Three weightings, and what the price implies. The standard set, 25 / 50 / 25, and the stress set, 10 / 40 / 50, are the same for every company; the best guess drives the target and the two chips at the top of the page.
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $56.05 | −7% | 0.6 to 1 |
| Best guess: 30 / 45 / 25 | $57.31 | −5% | 0.7 to 1 |
| Stress: 10 / 40 / 50 | $44.62 | −26% | 0.13 to 1 |
| What the price implies: 35 / 45 / 20 | $60.13 | 0% | 1.0 to 1 |
The weights are a judgement. All values are estimates from the model.
Why the best guess spreads the weight. Each case has real evidence behind it, and refrigerant prices, which decide most of the value, could plausibly settle anywhere across the range: nuclear and electronic materials support the best case, Chemours’ warning supports the worst, and the regulation and patents support the middle. So the weights are spread more evenly than on most profiles, with the worst case slightly less likely than the best: 30% best, 45% base, 25% worst. Evidence that would move them: refrigerant sales falling year on year or a segment margin below 30% in the third-quarter results (worst case up); refrigerant growth holding near the first half’s 16% with the margin in the mid-30s, as guided (best case up).
What the price implies. Holding the base case at its 45% weight, the price is matched by the weighting that solves
best weight × $82.62 + 45% × $57.39 + (55% − best weight) × $26.81 = $60.13
which gives a best-case weight of ($60.13 − $25.83 − $14.75) ÷ ($82.62 − $26.81) = 35%, and so 20% on the worst case. The market is slightly more optimistic than the best guess.
The asymmetry on the best guess:
| Measure | At $60.13 | What it means |
|---|---|---|
| Expected return (header chip) | −5% | The probability-weighted value, $57.31, against the price |
| Gain to loss (header chip) | 0.7 to 1 | +$6.75 of probability-weighted gain against −$9.56 of loss |
| Best-case gain ÷ worst-case loss | 0.67 to 1 | +$22.49 against −$33.32 |
| Base case against the price | −$2.74 | The base case is below the price, so it adds to the expected loss |
How the measures are calculated. Gain = case value − price; loss = price − case value. Weights are the best guess: 30% best, 45% base, 25% worst.
| Measure | Formula | At $60.13 |
|---|---|---|
| Expected return | (30% × best + 45% × base + 25% × worst) ÷ price − 1 | ($24.79 + $25.83 + $6.70) ÷ $60.13 − 1 = −5% |
| Gain to loss | (30% × best gain) ÷ (45% × base loss + 25% × worst loss) | $6.75 ÷ ($1.23 + $8.33) = 0.7 |
| Best ÷ worst | best gain ÷ worst loss | $22.49 ÷ $33.32 = 0.67 |
| Price-implied best weight | (price − base weight × base − (1 − base weight) × worst) ÷ (best − worst) | ($60.13 − $25.83 − $14.75) ÷ $55.81 = 35% |
The header chips are green at +25% or more and 3 to 1 or better, blue at +10–25% and 2–3 to 1, orange at 0–10% and 1–2 to 1, and red below zero and below 1 to 1. On the best guess, expected return is green below $45.85, blue up to $52.10 and orange up to $57.31; gain to loss is green below $47.15, blue up to $51.21 and orange up to $57.31. Both are red above $57.31.
Short interest and volatility
The tables below show how much of the stock is sold short and how much the price moves. They are inputs to the weights above, and the tables update with the nightly data.
| Report | Settled | Short | % float | % outst. | Days to cover |
|---|---|---|---|---|---|
| First after the spin | Oct 31, 2025 | 7.15M | 4.5% | 4.5% | 1.8 |
| Lowest since the spin | Nov 28, 2025 | 2.40M | 1.5% | 1.5% | 1.0 |
| Three months earlier | Jul 15, 2026 | 11.33M | 7.1% | 7.1% | 1.9 |
| Latest | Oct 30, 2026 | 4.67M | 2.9% | 3.0% | 2.2 |
The latest share of float is higher than 14 of the 24 earlier reports since the spin. Short interest in shares, with its share of the float and of shares outstanding. FINRA settlement dates; figures are published about eight business days later. Days to cover is short interest divided by average daily volume, as reported by FINRA. Float and shares outstanding on or before each date, from this site's daily share records and the company's filings.
Short interest halved in September 2026, from about 10 million shares at the end of August to 5.2 million, about 3.3% of the float, once the Element Solutions deal ended. Merger arbitrage usually means shorting the acquirer, so the fall most likely reflects those positions closing; it is back to its level of June 2026 and too small to change the weights.
| Volatility, annualized | Last 20 sessions | Last 60 sessions | Since the spin |
|---|---|---|---|
| To November 13, 2026 | 69% | 53% | 56% |
At the last 60 sessions' volatility, one standard deviation over a month is about ±17%, or $56.72 to $77.07 from the $66.12 close; about two months in three end inside that range if volatility holds. The median daily move since the spin is 1.9%.
| Results day | Released | Close before | Close after | Move | Times a median day |
|---|---|---|---|---|---|
| November 6, 2025 | Before the open | $48.33 | $45.02 | -6.8% | 3.7× |
| February 11, 2026 | Before the open | $63.80 | $74.95 | +17.5% | 9.3× |
| May 6, 2026 | Before the open | $83.56 | $82.01 | -1.9% | 1.0× |
| July 30, 2026 | Before the open | $55.66 | $57.39 | +3.1% | 1.7× |
| November 4, 2026 | Before the open | $61.74 | $57.70 | -6.5% | 3.5× |
Average move on a results day: 7.2% either way, against a median day's 1.9%. The move is measured from the close before the release to the close of the first session after it.
Results days have moved Solstice a lot: −6.8%, +17.5%, −1.9% and +3.1%, an average of 7.3% against a median day’s 1.8%. Since the spin it has closed as low as $41.43 (November 18, 2025) and as high as $88.60 (June 30, 2026). The November 4, 2026 results test the refrigerant question directly: a quarter showing the aftermarket destocking that Chemours reported would point toward the worst case, while refrigerant growth near the first half’s pace would support the best.
Notes on earlier sections
- The August 24, 2026 valuation omitted General Atomics’ share of ConverDyn. Solstice consolidates ConverDyn, its 50/50 joint venture with General Atomics, so all of the nuclear business’s revenue and EBITDA are in its figures, and General Atomics’ half of ConverDyn’s profit appears as a noncontrolling interest ($48 million in 2025, about $70 million a year in 2026). The August discounted-cash-flow model valued that profit as Solstice’s. Deducting it, at an estimated 38% of nuclear EBITDA, lowers every value by about $4.50 a share: the August “flat margin” value of $61 becomes about $57, and the $69 recovery case about $64. A data correction.
- Index membership. The August 24, 2026 analysis described Solstice as added to the S&P 500 at the spin, which it was. The index funds’ holdings files now show it in the S&P MidCap 400 and the S&P Composite 1500, and not in the S&P 500, consistent with a reported move to the MidCap 400 on March 23, 2026. A clarification.
What it means for the rating
HOLD, target $62 → $57. The target is the best-guess value, $57.31. About $4.50 of the change is the correction for General Atomics’ share of ConverDyn; the rest comes from building the cases line by line. Both chips are red at $60.13: the expected return is about −5% and the gain to loss about 0.7 to 1, with the price slightly above the weighted value. HOLD rather than SELL because the gap is small, inside the range a single quarter can move, and the November 4, 2026 results directly test the variable that decides most of the value.
| Action | Level | Reason |
|---|---|---|
| Accumulate | Below about $47 | Gain to loss reaches 3 to 1 and expected return about 22% |
| Hold | $47–70 | |
| Trim | Above $70 | The best case at a 9× exit multiple |
| Move to SELL | Refrigerant sales falling year on year with a segment margin below 30%, or an EU decision ending HFO refrigerant use without long exemptions | |
| Move to ACCUMULATE | Refrigerant growth sustained with mid-30s margins, plus executed buybacks, at a price below about $55 |
What to watch in the third-quarter results (November 4, 2026):
| Line | The test |
|---|---|
| Refrigerants | Growth against the first half’s 16%; any sign of the aftermarket destocking Chemours reported |
| Refrigerants & Applied Solutions margin | Mid-30s, as guided; below 30% points to the worst case |
| Nuclear | The size of the loan-return effect (about −$30 million of sales); new contract prices |
| Electronic materials | Growth near 15% as sputtering-target capacity is pulled forward |
| Capital return | Buybacks executed under the $500 million authorisation |
| Guidance | 2026 sales of $4,125–4,185 million and adjusted EBITDA of $1,035–1,055 million held or raised |
Update — September 2, 2026 — the Element Solutions merger is terminated
Written against the September 2 close of $60.99. Primary sources: the Element Solutions termination announcement (August 27, 2026), the report of the +12.8% session and the $500M buyback, and the Q2 2026 Form 10-Q. The analysis below this section is unchanged and is retained as written; see What this section supersedes at the end.
The one-line version
The upside case landed, and the price took it the same week.
The August 24 analysis said the upside case here was the deal not happening. On August 27 both boards mutually terminated the merger. Neither party owes the other anything — no break fee, no stranded financing cost, no reverse-termination liability — despite a disclosed fee of $385M, or $513M in specified circumstances. Solstice paired the announcement with a $500M share repurchase authorisation. The stock rose 12.8% in a single session, to $63.53.
Rating BUY → HOLD. Target $62, unchanged. Grade A− (3.63), unchanged.
Nothing about the business got worse. The thesis was right and it resolved: the shares closed the discount. At $60.99 against a standalone fair value of roughly $61 on a range of $55–$69, they now trade essentially at fair value — 1.6% below the $62 target, which is not a margin of safety. An A− business at fair value is a hold, not a buy.
The pop has partly faded, and that is worth noting rather than smoothing over: $63.53 on August 28, $60.99 three sessions later. The re-rating was real and most of it has held, but roughly a third of the initial move has come back.
What the termination restores
July’s downgrade was explicit that it was a thesis change, not a drawdown to buy. The security being graded was a clean, high-margin specialty-materials pure-play. What the merger would have created was a leveraged acquirer integrating a $14.5B target nine months after independence, with pro-forma leverage rising toward ≈3.5x on a $4.685B Goldman bridge commitment.
That security no longer exists. The original one does, with FY2026 guidance intact — revenue $4.13–4.19B, adjusted EBITDA $1.04–1.06B — and net leverage of 1.13x against $750M of cash.
The arithmetic that took 22.5% out of the stock over two sessions in July was issuing paper at ≈9.4x EV/EBITDA to buy an asset at 26.5x (19.9x after guided synergies). Unwinding that was worth money, and the market said so immediately.
Why this is not a return to BUY
This is a change of direction from the reading earlier in the cycle, when the termination alone was treated as restoring the BUY. It does not, and the reason is arithmetic rather than sentiment:
The termination restored the security; the share price then took the value it was worth. On the midpoint of FY2026 adjusted EBITDA guidance, 158.8M shares and net leverage of 1.13x, that is an enterprise value of roughly $10.9B, or ≈10.4x — no longer a discount, and no longer the ≈9.4x at which the company was proposing to issue paper. (The 2026-08-31 report puts the same multiple at ≈11.2x; the gap is a share-count and net-debt basis difference, not a change in view. The figure above is computed from the inputs stated here.)
The three-year record is why fair value is not higher, and none of it has changed: adjusted EBITDA margin ran 29.9% → 25.7% → 25.2%, with 2025 EBITDA below 2023 in absolute dollars, and normalized standalone EPS is down 14% since 2023 — 24% excluding ConverDyn. 2025 free cash flow was $119M against $546M in 2024. The offsetting evidence also stands: 1H26 already exceeds all of 2025 on operating cash flow, free cash flow is up 45%, and capital expenditure at 169–184% of depreciation is growth spending rather than maintenance, which is itself part of why fixed cost is under-absorbed in the margin line.
The scorecard: 3.63 unchanged, two rationales changed
The weighted score does not move. Two of the five rationales do, and they are worth stating because the reasons changed even where the number did not.
| Dimension | Weight | Score | What changed |
|---|---|---|---|
| Financial Profile | 25% | 3.0 | Unchanged. Leverage is 1.13x standalone rather than heading to ≈3.5x, but that was already how the standalone case was scored |
| Competitive Position | 25% | 4.5 | Unchanged |
| Strategic Rationale | 20% | 4.0 | Rationale changed. Was “a separation followed by an acquisition that fixes the weakest segment”. Now a coherent separation from Honeywell’s three-way breakup leaving a focused platform — discounted only for the strategic detour of the Element attempt |
| Management & Governance | 20% | 3.5 | Rationale changed, and it is a credit. Walking away from a signed $14.5B deal, with no break fee, on shareholder feedback, is a governance credit rather than a debit. Still held below 4 by only four quarters of standalone history |
| Acquisition Potential | 10% | 2.5 | The merger no-shop is gone; §355(e) still blocks until October 2027. The constraint is now one thing, not two |
| Weighted Score | 3.63 | ||
| Investment Grade | A− · Strong Opportunity |
An earlier draft marked down both Strategic Rationale and Management for the price paid for Element. That was double-counting a single objection — the purchase price is already reflected in what a buyer pays today. The price was a valuation input, not a character flaw. The point is moot now in any case, and is recorded here so the reasoning is not repeated.
Capital allocation — the $500M authorisation
The buyback is the first genuinely new capital-allocation fact since the August 24 section, and it lands on a company that had been spending its cash on capex at 169–184% of depreciation while free cash flow fell to $119M in 2025.
What it signals is that the board, having just declined to spend $14.5B of paper on an acquisition, is willing to return capital instead. What it does not settle is whether the authorisation gets used: an authorisation is permission, not a commitment, and 1H26 free cash flow of $246M against a $500M program means this is a multi-year intention or a balance-sheet drawdown, not a quarter’s work. Worth watching in the Q3 filing rather than crediting now.
What would change this view
To A: refrigerant margin stabilising for two consecutive quarters — the single measurement that would convert the bull case from argument to evidence.
Down: evidence that the refrigerant decline is structural rather than cyclical and mix-driven.
The DCF is deliberately not re-run here. The standalone model already was the live branch, and re-running it against a price that moved 12.8% in a week would produce a number driven by the price rather than by the business. It is scheduled for after the next earnings report.
What this section supersedes
Everything below is retained exactly as written on August 24 — nothing has been edited, and the corrections rule is why. But the merger was load-bearing in several places, and those sections are now history rather than analysis:
| Section below | Status as of today |
|---|---|
| The one-line version (BUY; “the upside case is the deal not happening”) | Superseded by the box above. The call was right; it resolved |
| What the Element Solutions deal does to the mix | Historical — the mix is the standalone mix again |
| The Element Solutions acquisition and its subsections | Historical — retained for the reasoning, not the conclusion |
| The fixed exchange ratio makes it reflexive | Historical. The ratio never floated and now never will |
| Honeywell holds a veto | Moot. The veto was never exercised — the boards terminated it themselves |
| Financing ($4.685B bridge) | Moot — no financing was drawn and no cost was stranded |
| B — Preliminary pro forma, if the deal closes | Moot. Scenario A is the only live case |
| Break-up or takeover? The deal decides it | Reopened. The deal decided nothing; the question returns intact, still gated by §355(e) until October 2027 |
| A — Standalone: discounted cash flow | Still live, and now the only case |
| Everything on the business, segments, value chain, peers and tails | Still live — untouched by the deal |
Post-Spin Analysis — August 24, 2026
Written against the August 21 close of $56.16. Primary sources: the FY2025 Form 10-K (filed 2026-02-19) and the Q2 2026 Form 10-Q (filed 2026-07-30), which contains the Element Solutions merger disclosure.
The one-line version
The standalone business is cheap. The acquisition is what is expensive, and the market has priced Solstice as though it closes.
At $56.16 Solstice trades at 9.4x EV/EBITDA on its own forward earnings. It is issuing that paper to buy Element Solutions at 26.5x EV/EBITDA — 19.9x after guided synergies. That arithmetic, not arbitrage mechanics, is what took 22.5% out of the stock over two sessions in July.
The consequence is an unusual asymmetry. On a standalone basis the shares are worth roughly $61 on our model, +9%, on a range of $55–$69. On a pro-forma basis the combined company at today’s price is already 12.8x, or 11.6x with synergies — full. The upside case here is the deal not happening, and Honeywell holds a contractual consent right that could stop it.
Rating BUY. Target $62. Both paths pay, but neither pays spectacularly: the standalone business is worth $55–$69 if the deal breaks, and if it closes you own three growing franchises at 12.3x EV/EBITDA a year out, deleveraging to 7.1x by year five.
The target has moved twice, and both times on evidence rather than news. From $70 to $65, when three years of segment history showed the refrigerant margin declining in every year since 2023 rather than only since the spin — which removed the margin-recovery assumption the original target rested on. Then from $65 to $62, when the capital-allocation record showed capital expenditure running at 8.6–10.1% of sales against the 8%→6% the model assumed. What holds the rating at BUY is the floor rather than the ceiling: even if the decline runs uninterrupted for another seven years, the standalone business is worth roughly today’s price — and the nuclear franchise is a genuine unpriced call option.
What the business actually is
Honeywell’s advanced-materials arm, separated October 30, 2025 and added to the S&P 500. FY2025 net sales $3,886M, adjusted EBITDA margin 25.7%. Roughly 4,100 employees. Two segments built on the same fluorine chemistry:
| Segment | FY2025 sales | Segment EBITDA | Margin | What it is |
|---|---|---|---|---|
| Refrigerants & Applied Solutions | $2,789M | ~$1,023M | ~36.7% | LGWP refrigerants (Solstice, Genetron), blowing agents, solvents, healthcare packaging (Aclar), and its half of ConverDyn, the uranium-conversion joint venture |
| Electronic & Specialty Materials | $1,097M | $203M | 18.5% | Electronic materials, research and performance chemicals |
Two things in that table deserve more attention than they usually get.
The refrigerant business has a regulatory tailwind, not just a cyclical one. Low-global-warming-potential refrigerants are mandated — the 10-K notes LGWP refrigerants “are required in nearly every new car sold in regulated markets.” The company is named after its flagship HFO line. The global HFC phase-down forces a multi-decade product substitution toward exactly what Solstice sells.
The nuclear business is a genuine monopoly, and Solstice co-owns it. The Nuclear (AES) unit provides uranium hexafluoride conversion to utilities through ConverDyn — a joint venture between Solstice and General Atomics — operating the Metropolis Works facility in Illinois. The 10-K states it plainly: together with its joint-venture partner, “we are the only provider of these services in the U.S.” Solstice does not own this outright; it owns its share of a two-party JV, which matters both for how the economics consolidate and for who could eventually buy it. One of the few literal monopolies in the tracked universe, attached to a nuclear-power demand cycle, sitting inside a segment nobody discusses.
Management Team
| Role | Name | Background |
|---|---|---|
| President & CEO | David Sewell | Appointed October 2025. CEO of WestRock March 2021 – March 2025; before that 14 years at Sherwin-Williams, and 15+ years in GE’s Plastics and Advanced Materials division. 30+ years in materials and chemicals |
| CFO | Tina Pierce | CFO of Honeywell’s Advanced Materials business from May 2025, carried into the standalone company |
| Non-executive Chair | Dr. Rajeev Gautam | Four decades at Honeywell; President and CEO of Honeywell Performance Materials and Technologies until his 2021 retirement — the division this business came out of |
Two observations that matter more than the résumés.
The CEO is an acquirer by temperament, and the record is recent. Sewell’s previous role ended when WestRock combined with Smurfit Kappa — a transformative, transatlantic merger. Eight months into running Solstice he agreed to a $14.5B acquisition. That is not a criticism, but it is a pattern, and it is the single most useful thing to know when underwriting how this management team will deploy capital over the next five years. Expect more transactions, not fewer.
The chair ran the parent division. Deep domain knowledge, and the person best placed to judge what these assets are worth. It also means the board’s most senior figure is a Honeywell lifer at a company whose former parent holds a consent right over its strategy — a governance dynamic worth watching rather than worrying about.
The financial record — three years by segment
Revenue is not the problem. Margins are. And the margin decline is not two quarters old, which is how the post-spin reporting makes it look. It is three years old.
| ($M) | 2023 | 2024 | 2025 | 1H 2026 |
|---|---|---|---|---|
| Net sales | 3,649 | 3,770 | 3,886 | 2,139 |
| growth | +3.3% | +3.1% | +10.8% | |
| Gross margin | 35.2% | 34.6% | 32.2% | 32.1% |
| Adjusted EBITDA | 1,090 | 1,098 | 1,000 | 539 |
| Adjusted EBITDA margin | 29.9% | 29.1% | 25.7% | 25.2% |
Adjusted EBITDA in 2025 was lower in absolute dollars than in 2023 — $1,000M against $1,090M — on 6.5% more revenue. The business grew and earned less for it. That is the whole story of this page in one line, and no single reporting period shows it.
By segment, three different things are happening:
| ($M) | 2023 | 2024 | 2025 | 1H 2026 |
|---|---|---|---|---|
| Refrigerants & Applied Solutions | 2,629 | 2,721 | 2,789 | 1,561 |
| RAS adjusted EBITDA | 1,039 | 1,058 | 981 | 522 |
| RAS margin | 39.5% | 38.9% | 35.2% | 33.4% |
| Electronic & Specialty Materials | 1,020 | 1,049 | 1,097 | 579 |
| ESM adjusted EBITDA | 195 | 201 | 203 | 123 |
| ESM margin | 19.1% | 19.2% | 18.5% | 21.2% |
| Corporate and All Other | (144) | (161) | (184) | (106) |
| Corporate, % of sales | 3.9% | 4.3% | 4.7% | 5.0% |
RAS margin has fallen in every full year of the record — 435 basis points from 2023 to 2025, with no interruption. This is the finding the two-quarter view cannot deliver, and it is bad for the thesis: a decline that has run for three years through two different owners is much harder to call transitional than one that shows up the quarter after a spin.
One caveat, and it cuts the other way. Backing 1H out of the full years gives a half-yearly RAS path of 39.4% (1H25) → 31.0% (H2 25) → 33.4% (1H26) — a 240bp improvement on the most recent half. But refrigerants are a cooling-season business and H2 is seasonally weaker, so that sequence mixes season with trend and cannot be read as a turn. It does mean two things: the FY2025 figure of 35.2% embeds a seasonally weak half, and the only clean comparisons on this page are like-for-like halves (1H26 vs 1H25, down 600bp) and full years. We do not have 1H 2024 to size the seasonal amplitude, which is the single most useful disclosure the Q3 filing could give us.
ESM is the mirror image. Flat at roughly 19% for three straight years, then +270 basis points in 1H 2026 to 21.2%. Nothing about the spin caused that; the semiconductor and defense pull-through did. It is the smaller segment — 28% of sales — but it is the only part of Solstice whose earnings quality is improving.
Corporate cost has gone from 3.9% to 5.0% of sales and is still climbing as standalone functions stand up. On $4.3B of 2026 revenue, each further 50 basis points is $21M of EBITDA.
The part that argues against the bear case
The obvious reading of a three-year margin slide in a business facing Chinese capacity expansion is price erosion. The filings say that is not what is happening. Realised pricing has been favorable in every period disclosed:
- 2025: “favorable volume and pricing in refrigerants of $195 million”
- 1H 2026: RAS volume +$95M, pricing +$52M, FX +$22M
Price is rising in both segments. The compression is entirely in cost of goods sold — gross margin fell 310bp from 2023, while SG&A held at 10–11% of sales throughout. Solstice attributes it to “refrigerants product mix as a result of the ongoing transition to LGWP refrigerants”: the new molecules are more expensive to make than the legacy ones they displace, and new capacity carries under-absorbed fixed cost until it fills.
That distinction matters more than anything else on this page. Price erosion in a chemical business is usually permanent — it means a competitor has arrived. Cost absorption on ramping capacity mean-reverts as volume fills the plants. The record is consistent with the second, and 1H 2026’s 11% volume growth is what filling plants looks like. But three years is a long ramp, and the burden of proof has shifted to the company.
What would settle it: RAS margin stabilising or turning up in Q3/Q4 2026 on continued volume growth. If it makes a fourth consecutive annual decline in FY2026, “transitional” stops being a defensible word.
The quarterly detail
| Q2 2026 | Q2 2025 | 1H 2026 | 1H 2025 | |
|---|---|---|---|---|
| Net sales | $1,148M | $1,033M +11% | $2,139M | $1,930M +11% |
| Adjusted EBITDA | $290M | $304M −5% | $539M | $575M −6% |
| Adjusted EBITDA margin | 25.3% | 29.4% | 25.2% | 29.8% |
Revenue up 11%, EBITDA down 6%, margin down 460 basis points. Decomposed by segment for the first half:
| 1H26 sales | 1H25 sales | 1H26 EBITDA | 1H25 EBITDA | Margin move | |
|---|---|---|---|---|---|
| Refrigerants & Applied Solutions | $1,561M | $1,392M | $522M | $548M | 39.4% → 33.4% |
| Electronic & Specialty Materials | $579M | $538M | $123M | $105M | 19.5% → 21.2% |
| Corporate and All Other | — | — | (106) | (78) | +36% of cost |
This is the cleanest comparison available — like-for-like halves, same seasonality on both sides. RAS gives up 600 basis points on 12% volume-led growth; ESM gains 170 on 7.6%; corporate cost rises 36% as the standalone load arrives, which was expected and is the one line here that should stop growing once the separation is fully absorbed.
Where Solstice sits in the value chain
Solstice is not one power position. It is three, and they are unusually far apart — which is why a single margin number describes this company badly.
| Segment | Share of 2025 sales | What protects it | Can it raise price? |
|---|---|---|---|
| Nuclear (AES) (within RAS) | ~5% | A regulatory monopoly. The company’s own words: “the only U.S.-based supplier” of uranium hexafluoride conversion, and “together with our joint venture partner General Atomics, we are the only provider of these services in the U.S.” The Department of Energy has separately agreed to act to assure the facility’s continued operational availability | Yes, decisively |
| Refrigerants (the rest of RAS) | ~67% | Patents plus a legislated transition. Composition patents on R-1234yf run “into the 2030s”; the AIM Act obliges customers to move to low-GWP molecules that two Western companies make | Yes |
| Electronic & Specialty Materials | 28% | Qualification only. Sputtering targets, electronic polymers, high-purity etchants — sold to semiconductor makers who qualify multiple suppliers | Limited |
The evidence, and it is the reverse of what we found next door
Most of these questions have to be inferred. Here they can be read off the filings, because Solstice discloses what drove revenue:
- 2025: “favorable volume and pricing in refrigerants of $195 million”
- 1H 2026: RAS volume +$95M, pricing +$52M, currency +$22M
Realised price rose in every period disclosed. That is a materially different answer from the one the same test produces at Qnity, which separated four days after Solstice from a comparable American industrial parent into a comparable advanced-materials business — and which gave price back 1–2% in both segments in both 2024 and 2025, through the strongest semiconductor cycle on record.
Two advanced-materials spinoffs, four days apart, opposite pricing outcomes. The difference is what the protection is made of. Qnity is protected by qualification — a customer must requalify to switch, which is slow, so the socket is safe. But four to six suppliers are qualified in every category and the buyer is TSMC or Samsung, so the price is the customer’s to set. Solstice’s refrigerant business is protected by scarcity — a patent on a molecule that regulation obliges the customer to adopt. Two suppliers, a legal mandate, and a composition patent is a different thing entirely.
Qualification protects revenue. Scarcity protects price. Solstice sits on the better side of that distinction, and the price line is the proof.
And yet the margin still fell — which is the part worth sitting with
Solstice has the stronger power position and its adjusted EBITDA margin went 29.9% → 25.7% across the same period, with RAS falling 435 basis points. Both things are true, and reconciling them is the whole analytical content of this page: price rose and cost rose faster. Gross margin fell 310bp while SG&A held flat, so the compression is entirely in cost of goods sold — the new LGWP molecules cost more to make than the legacy ones they displace, and new capacity carries under-absorbed fixed cost until it fills.
Pricing power is necessary and not sufficient. A supplier who can raise price still loses margin if unit economics deteriorate faster than the price rises. That is the correct reading of this record, and it is more forgiving than the raw margin line suggests — because a cost problem on ramping capacity mean-reverts and a pricing problem does not.
What the Element Solutions deal does to the mix
It moves the average toward the weakest tier. Element sells wet chemistries, solder pastes and assembly materials into printed circuit boards and advanced packaging — qualification-gated, multi-supplier, sold to large sophisticated buyers. Structurally it is Qnity’s position, not the refrigerant business’s.
That is visible in the returns already: Element earns 21.4% and 21.6% segment margins against Solstice’s 25.7%. The page notes this as arithmetic dilution. The value-chain reading makes it structural — Solstice would be paying 26.5x to add roughly $2.5B of revenue in the one tier where it cannot set price, funded partly with paper issued against a business that can.
This is not an argument that the deal is wrong. Element is the best asset available in the fastest-growing end market, and the electronics franchise genuinely needed scale — that case is made in full above. It is an argument that the deal’s cost is larger than the multiple alone implies, because it buys revenue of a lower quality than the revenue funding it. Weigh it alongside the price paid rather than instead of it.
The Element Solutions acquisition
On July 6, 2026, eight months after separating, Solstice agreed to acquire Element Solutions for approximately $14.5B including net debt: $10.00 cash plus 0.500 Solstice shares per Element share, an implied $50.10 and a ~15% premium. Expected close H1 2027, with an outside date of July 6, 2027 that automatically extends to January 5, 2028 for regulatory approvals.
The market’s answer was immediate: −15.1% on 3.7x normal volume, then −8.7% on 4.5x the next session. A −22.5% two-day repricing.
What Element Solutions actually is
Worth establishing before judging the price, because the strategic case is better than the financial one.
Element Solutions (NYSE: ESI) is a specialty-chemicals company built around MacDermid Alpha Electronics Solutions. FY2025 net sales $2,551M, adjusted EBITDA $548M:
| Segment | FY2025 sales | Adj. EBITDA | Margin | What it sells |
|---|---|---|---|---|
| Electronics | $1,786M (70%) | $382M | 21.4% | “Wet chemistries” for metallisation, surface treatments and solderable finishes that form circuitry pathways; “assembly materials” — solder pastes, fluxes, adhesives — that join them. Printed circuit boards through advanced semiconductor packaging |
| Specialties | $765M (30%) | $165M | 21.6% | Industrial surface treatment, offshore energy, graphics |
Element’s electronics business grew 10% organic in 2025, with Q4 Assembly Solutions +12% and Semiconductor Solutions +13%, driven by data-center, high-performance-computing and advanced-packaging demand.
(Element reports a 26.5% adjusted EBITDA margin against the 21.5% computed here. The difference is pass-through metals pricing — solder is tin and silver, and the metal content flows through revenue at no margin. Both figures are correct on their own basis; the like-for-like comparison with Solstice uses the reported 21.5%.)
The strategic rationale — which is the strongest part of the case
Solstice’s weakest position is electronic materials. Element’s strongest is electronic materials. The fit is genuine.
| Electronics-facing revenue | |
|---|---|
| Solstice ESM standalone (includes Spectra fibres and research chemicals, so the true electronics figure is lower) | $1,097M |
| Element Electronics | $1,786M |
| Combined | ~$2.5–2.9B |
That is roughly a threefold step-up, and it moves Solstice from a mid-tier participant to a top-tier Western electronic-materials supplier — comparable in scale to Entegris, behind Qnity, and materially larger than it could have become organically. Against competitors of that size, sub-scale is a structural disadvantage in R&D spend and customer qualification. This deal fixes it in one step.
There is also a real chemistry adjacency: both companies formulate specialty materials into customer-specific process flows and sell into qualification-gated positions. Element’s data-center and advanced-packaging exposure is precisely the end-market strength Solstice’s own ESM segment lacks.
So the strategic logic is sound. The dispute is entirely about price — and about whether a company trading at 9.4x should be the one paying 26.5x to fix its weakest segment, rather than waiting, buying something smaller, or building.
Why the market reacted that way
| Solstice trades at | 9.4x EV/EBITDA on its own forward earnings |
| Solstice is paying | 26.5x EV/EBITDA for Element Solutions |
| …or after $180M of guided synergies | 19.9x |
A company issuing equity at 9.4x EV/EBITDA to buy an asset at 26.5x destroys value per share unless the synergies and the strategic case are extraordinary. That is the arithmetic, and it is not a matter of sentiment.
The fixed exchange ratio makes it reflexive
The 0.500 ratio does not float. So as Solstice falls, the consideration Element holders receive falls with it:
| Solstice share price | Consideration per Element share |
|---|---|
| ~$80 at announcement | $10.00 + $40.00 = $50.00 |
| $56.16 today | $10.00 + $28.08 = $38.08 |
The offer has lost 24% of its value since it was struck, and Element’s shareholders still have to vote on it. That is a live deal risk, not a footnote.
Honeywell holds a veto — and this is the part almost nobody has read
The 10-Q discloses that Solstice owes Element a termination fee of $385M or $513M if the deal is terminated in specified circumstances, “including pursuant to a competing proposal or in the event that Honeywell revokes its consent pursuant to the Tax Matters Agreement entered into between the Company and Honeywell, or otherwise seeks to prohibit the Mergers.”
The former parent has a contractual say over whether its spun-off subsidiary may complete this acquisition. That is Section 355(e) — the anti-Morris Trust rule — operating not as an abstract tax risk but as a negotiated consent right with a nine-figure price attached.
It is also why Element holders end up with ~44% of the combined company: six points below the 50% threshold that would make Honeywell’s separation retroactively taxable. The fixed ratio locks that percentage at signing so it cannot drift across the line on price movement.
Element Solutions, for its part, would owe Solstice $376M if it walks.
Financing
A $4.685B bridge facility from Goldman Sachs, since syndicated, with the credit agreement amended on July 24, 2026 to permit it. Permanent financing is intended in term loan B and unsecured notes. Receipt of financing is not a condition to closing — Solstice is obliged to complete the deal whether or not the permanent market cooperates.
Was this an arbitrage overshoot? The evidence says no
A reasonable hypothesis after a −22.5% two-day move in an acquirer is that merger-arbitrage funds were mechanically shorting the stock — long the target, short the acquirer — and pushed it below fair value, creating an opportunity that unwinds at closing. It is testable, and it fails.
The classic arb trade requires the target to trade below deal consideration, so the spread can converge. Here:
| Deal consideration at today’s Solstice price | $38.08 |
| Element Solutions share price | ~$43.64 |
Element trades roughly 15% above what the deal would pay. The arbitrage spread is negative — the standard trade loses money and is therefore not being put on at scale. Whatever drove Solstice down, it was not arbitrage supply.
What Element’s price does suggest is that the market assigns real probability to the deal not closing on these terms, or to a revised offer. An acquirer’s shareholders and a target’s shareholders both signalling dissatisfaction is the condition under which deals get renegotiated or abandoned.
Capital allocation
The page has until now said nothing about what Solstice does with its cash. It should, because the cash flow record is the least flattering exhibit on this page and the capital program is the most encouraging one.
| ($M) | 2023 | 2024 | 2025 | 1H 2026 |
|---|---|---|---|---|
| Cash from operating activities | 760 | 842 | 455 | 461 |
| Capital expenditures | (299) | (296) | (336) | (215) |
| Free cash flow | 461 | 546 | 119 | 246 |
| Depreciation | 170 | 175 | 191 | 107 |
| Capex / depreciation | 176% | 169% | 176% | ~184% |
| Dividends paid | — | — | — | (24) |
| Net transfers to Honeywell | (345) | (414) | (684) | — |
The 2025 collapse, and why it is mostly explicable
Free cash flow fell from $546M to $119M. Operating cash flow dropped $387M on a year in which adjusted EBITDA fell only $98M. The bridge is not mysterious — $117M of transaction costs, the mechanics of separating from a cash-pooling parent, and working capital — but the conversion rate is the number to hold: operating cash flow was 77% of adjusted EBITDA in 2024 and 46% in 2025.
The first half of 2026 says it was the year, not the business. Operating cash flow of $461M in six months already exceeds the whole of 2025, and free cash flow is up 45% year on year, from $170M to $246M. On that pace 2026 lands near the 2023–24 range, which is what a normalizing year should look like.
Capital spending is the encouraging half
Solstice has spent between 169% and 184% of depreciation in every period on record, and stepped capex up 54% year on year in the first half — $213M against $138M. For a chemicals business that is a growth program, not maintenance, and it is where the LGWP capacity build shows up.
It also complicates the margin story in the company’s favor. A business adding capacity faster than it depreciates carries under-absorbed fixed cost until the new plants fill — which is precisely the explanation offered for the gross-margin compression, and this line is the corroboration. Capex above depreciation and margin below trend are the same fact seen twice.
The parent took $1.4B on the way out, and then the debt
Net transfers to Honeywell ran $345M, $414M and $684M across 2023–25 — $1,443M cumulative — before the separation loaded roughly $2.0B of drawn debt onto the balance sheet. Extracting cash before loading debt is the ordinary shape of a levered separation; the scale here is modest relative to the business.
What is being returned, and what is not
| Dividend | $0.075 quarterly, $0.30 annualised — a 0.53% yield at $56.15. $24M paid in 1H 2026 |
| Share repurchases | None. No authorization exists. The 10-K mentions buybacks only in a risk factor about debt reducing the funds available for them |
| Debt | $1.0B of 5.625% senior notes due 2033, a $1.0B seven-year first-lien term B, an undrawn $1.0B revolver and $750M of uncommitted letter-of-credit facilities |
The dividend is a token and is meant to be. Management says it “currently expects to continue returning cash to shareowners through quarterly dividends” — a commitment to the habit rather than to an amount.
Capital allocation here is not really a choice at the moment, and that is the point. With the Element Solutions transaction pending, a bridge facility committed and permanent financing planned as a term loan B plus unsecured notes, essentially all of Solstice’s financial capacity is spoken for. There will be no buyback and no meaningful dividend growth while that is true.
Which makes the deal-break scenario better than it first looks. A company generating $500M+ of free cash flow, carrying 1.13x net leverage and no transaction to fund, would have an obvious and large use for its own shares at nine times EBITDA. That optionality exists only on the path where the deal does not happen, and it is not in any number on this page.
Valuation, both ways
Because the outcome is binary, the two cases are modeled separately.
A — Standalone: discounted cash flow, if the deal does not happen
Discounted cash flow
Unlevered FCF, FY2027–33, at an 11% WACC. Revenue growth easing 7% → 4% as the LGWP substitution matures; adjusted EBITDA margin recovering 25.2% → 28%, below the 29.8% achieved a year ago; capital expenditure easing 10% → 7% of sales — see the note below, because that assumption has been corrected.
Why 11% for this company. There is no single right rate for every business. The relevant inputs are capital structure, scale, maturity and how predictable the cash flows are, and for a company like this one the defensible range runs from roughly 8% to 12%. Solstice sits in the upper half of it: a three-quarter-old public company, cyclical chemical end markets, a pending transaction that would take leverage to ~3.8x, and realised volatility well above the market. A larger, more mature, less levered business with contracted revenue would be discounted nearer 8%.
The capital-expenditure assumption has been corrected, and it costs about $3 a share. An earlier version of this model assumed capex easing from 8% to 6% of sales. The capital-allocation record above shows that is too low: actual capex was 8.6% of sales in 2025 and 10.1% in the first half of 2026, and Solstice has never spent below 169% of depreciation in any period on file. The model now eases 10% → 7%, which still credits the LGWP capacity build finishing.
Margin path capex 8% → 6% (prior) capex 10% → 7% (corrected) Recovers to 28% $72 $69 Flat at 25.2% (carried) $64 $61 Declines to 23% $58 $55
| ($M) | FY27 | FY28 | FY29 | FY30 | FY31 | FY32 | FY33 |
|---|---|---|---|---|---|---|---|
| Revenue | 4,577 | 4,852 | 5,095 | 5,324 | 5,537 | 5,758 | 5,989 |
| EBITDA margin | 26.0% | 27.0% | 27.5% | 28.0% | 28.0% | 28.0% | 28.0% |
| EBITDA | 1,190 | 1,310 | 1,401 | 1,491 | 1,550 | 1,612 | 1,677 |
| Unlevered FCF | 497 | 587 | 661 | 738 | 795 | 856 | 920 |
| WACC ↓ / exit EV/EBITDA → | 9x | 10x | 11x | 12x | 13x |
|---|---|---|---|---|---|
| 10% | $62 | $68 | $73 | $79 | $84 |
| 11% (base) | $59 | $64 | $69 | $74 | $79 |
| 12% | $55 | $60 | $65 | $70 | $74 |
That model returns $69, or +23% to spot. Solstice standalone trades at 9.4x forward EBITDA with net debt of only $1.22B — 1.13x. For a business with a regulatory-mandated substitution cycle, a monopoly nuclear conversion asset and an improving electronics segment, that is inexpensive.
But the margin assumption is doing almost all of the work. The base case above assumes RAS stabilises and the blend recovers to 28% — a level last seen in 2024. The three-year record shows no such recovery yet. Running the same model across the three margin paths the record supports:
| Margin path to FY33 | FY33 EBITDA | Value | vs $56.16 |
|---|---|---|---|
| Recovers to 28% (the model above) | $1,677M | $69 | +23% |
| Flat at today’s 25.2% | $1,509M | $61 | +9% |
| Continues down to 23% | $1,377M | $55 | −2% |
Read the bottom row first: even if the margin decline continues for another seven years, the standalone business is worth roughly today’s price. That is the floor, and it is an unusually well-supported one — it assumes the single worst trend in the business persists uninterrupted for a decade. On the corrected capital-expenditure path that floor is $55 rather than $58, which is 2% below spot rather than 3% above it — thinner, but still a floor rather than a drop.
The cost is at the top. $69 is not a base case, it is the recovery case. We carry $61 as the standalone number, and the range $55–$69 is the honest width.
Earnings-based valuation
The DCF and the EV/EBITDA multiple both flatter this business, for a reason worth naming: the carve-out years carry almost no interest expense. 2023 and 2024 show $16M and $13M of interest against a standalone run-rate of roughly $106M — the debt only arrived at the October 2025 spin. Comparing reported carve-out earnings to reported post-spin earnings therefore measures the capital structure, not the business.
Normalizing all four years to the same basis — full standalone interest, transaction costs excluded, a 24% tax rate (2023 and 2024 both ran 24%; 2025’s reported 56% is spin distortion) — gives the like-for-like earnings record:
| 2023 | 2024 | 2025 | 2026E | |
|---|---|---|---|---|
| Clean pre-tax income | $815M | $823M | $764M | $718M |
| less standalone interest normalization | (90) | (93) | (78) | — |
| Normalized pre-tax | $725M | $730M | $686M | $718M |
| Tax @ 24% | (174) | (175) | (165) | (172) |
| less noncontrolling interest | (2)* | (11) | (48) | (70) |
| Normalized EPS | $3.48 | $3.43 | $2.98 | $2.99 |
| P/E at $56.16 | 16.1x | 16.4x | 18.8x | 18.8x |
*2023 NCI was a $2M loss, which adds. 2026E annualises 1H 2026.
On a like-for-like standalone basis, Solstice earns 14% less per share than it did in 2023, and 2026 is flat against 2025 despite 11% revenue growth. The 9.4x EV/EBITDA that makes this look cheap becomes 18.8x earnings, which does not. Specialty chemicals peers trade at 16–20x. On earnings, Solstice is priced at the middle of its peer group, not below it.
Why the two multiples disagree — and the part that is genuinely hidden
Three things separate 9.4x EBITDA from 18.8x earnings:
- Depreciation and amortization of $220M — 22% of EBITDA. This is a capital-intensive business, and EV/EBITDA ignores the capital.
- $1.22B of net debt, which the equity carries and the EBITDA multiple nets at face.
- ConverDyn — and this is the one almost nobody adjusts for.
Solstice owns 50% of ConverDyn, the uranium-conversion joint venture with General Atomics, but consolidates 100% of it because it is the primary beneficiary. Every EV/EBITDA calculation on this company therefore counts EBITDA that belongs to General Atomics. The size of it is visible in the noncontrolling interest line, and it has gone vertical:
| Net income attributable to NCI | 2023 | 2024 | 2025 | 1H 2026 |
|---|---|---|---|---|
| ConverDyn minority | $(2)M | $11M | $48M | $35M (+340% YoY) |
Deducting the roughly $70M of annualised EBITDA that is not Solstice’s takes the standalone multiple from 9.4x to about 10.1x, and the pro-forma combined multiple from 14.1x to roughly 14.8x. Not fatal — but it removes most of the apparent discount to the specialty-chemicals group.
The second-order point is more important. Solstice’s own 50% of ConverDyn has gone from nothing in 2023 to roughly $0.35 a share in 2026. Strip it out and normalized 2026E EPS is $2.65, against $3.48 in 2023 — a 24% decline in the core business, masked at the reported line by a uranium joint venture. The refrigerant franchise is deteriorating faster than the headline numbers show, and the thing offsetting it is a commodity-priced asset the market is not paying a chemicals multiple for.
Cross-check. Three standalone methods: DCF $61 (flat-margin), earnings $56–64 (18.8x on $2.99, or 19–21x — the peer midpoint — on the same), EV/EBITDA at 10.1x attributable against peers at 10–12x giving $60–70. They converge on the high $50s to low $60s, not on $69.
Does the criticism survive at the pre-announcement price?
A fair challenge to everything above: if Solstice’s current price is itself depressed by the deal, then judging the deal by that depressed price is circular. So test it at the price before the announcement.
| SOLS’s own EV/EBITDA | Paying for Element, EV/EBITDA (post-synergy) | Pro-forma EV/EBITDA | |
|---|---|---|---|
| Pre-announcement, ~$80 | 12.9x | 19.9x | 18.5x |
| Today, $56.16 | 9.4x | 19.9x | 14.1x |
The direction of the conclusion survives; the magnitude does not.
Even at $80, Solstice was issuing 12.9x paper to buy a 19.9x asset — dilutive on multiple arithmetic, though far less brutally so. The deal was never accretive on multiples; it has simply become much worse as the shares fell.
The more interesting reading is the pro-forma column. At $80 the market was paying 18.5x for the combined company — a full price for a 3.8x-levered integration. At $56.16 it pays 14.1x. So the decline has taken the pro-forma entity from expensive to reasonable, which is a different statement from “the shares are artificially depressed.”
The honest summary: the fall is a repricing, not a distortion. The market was paying a premium multiple for the combined entity in June and is paying a fair one now. That is what repricing looks like, and it is consistent with the negative arbitrage spread — there is no mechanical seller to blame.
B — Preliminary pro forma, if the deal closes
Labeled preliminary because no S-4 has been filed. Both companies are public, so the operating figures below are actual and complete; what remains outstanding is purchase accounting, the final financing mix, and any divestitures required by regulators. Those change the balance sheet, not the earning power.
Combined on reported FY2025 actuals:
| Sales | Adj. EBITDA | Margin | |
|---|---|---|---|
| Solstice — Refrigerants & Applied Solutions | $2,789M | ||
| Solstice — Electronic & Specialty Materials | $1,097M | ||
| Solstice total | $3,886M | $999M | 25.7% |
| Element — Electronics | $1,786M | $382M | 21.4% |
| Element — Specialties | $765M | $165M | 21.6% |
| Element total | $2,551M | $548M | 21.5% |
| COMBINED | $6,437M | $1,547M | 24.0% |
| plus guided synergies by year three | +$180M |
(The announcement cited “approximately $6.8B of net sales and $1.7B of adjusted EBITDA.” That sits above the sum of reported 2025 actuals and is presumably a forward or run-rate basis. The figures above are what both companies actually reported.)
| Capital structure at close | |
|---|---|
| Pro-forma shares (158.8M + ~125M issued) | ~284M |
| Element holders’ stake | ~44% (matches guidance) |
| Pro-forma net debt (existing $1.97B + $4.685B bridge, less cash) | ~$5.9B |
| Net leverage | 3.82x — 3.4x with synergies (guidance: ~3.5x) |
| Pro-forma EV at $56.16 | $21.8B → 14.1x EV/EBITDA |
The deleveraging case — the strongest argument the bulls have
The question that matters for a levered acquirer is not today’s multiple but what happens as free cash flow retires debt. Hold the share price flat at $56.16, grow revenue 6%, let margin drift up modestly on scale, phase the $180M of synergies over three years, and apply all free cash flow to debt:
| Year | Revenue | EBITDA | Net debt | FCF | EV/EBITDA at $56.16 | Net debt / EBITDA |
|---|---|---|---|---|---|---|
| At close | $6,437M | $1,547M | $5,907M | — | 14.1x | 3.82x |
| +1 | $6,823M | $1,715M | $5,134M | $773M | 12.3x | 2.99x |
| +2 | $7,233M | $1,892M | $4,208M | $926M | 10.6x | 2.22x |
| +3 | $7,667M | $2,077M | $3,118M | $1,091M | 9.2x | 1.50x |
| +4 | $8,127M | $2,212M | $1,894M | $1,224M | 8.1x | 0.86x |
| +5 | $8,614M | $2,334M | $541M | $1,353M | 7.1x | 0.23x |
Without the share price moving at all, the stock goes from 14.1x to 10.6x in two years and 7.1x in five, and leverage falls from 3.8x to nearly nothing. The equity captures every dollar of debt repaid.
What that is worth. At year five — $2,334M of EBITDA and essentially no net debt — an 11x EV/EBITDA multiple implies roughly $91 a share and 12x implies $99, against $56.16 today. That is a 10–12% annualised return, achieved with no multiple expansion whatsoever.
This is the case for owning it, and it deserves to be stated as strongly as the criticism of the price paid. A 10–12% annual return from deleveraging alone is respectable. It is also, precisely, a market-rate return — roughly equal to the cost of equity used to discount it. The deleveraging case makes Solstice fairly valued, not cheap, which is why the rating below is HOLD rather than BUY.
What would make it cheap is the same thing that would make it a BUY: margins turning, so that the EBITDA line above compounds faster than 6% revenue growth and flat margin implies. The model above deliberately assumes no recovery in the RAS margin that has fallen 600bp. Restore even half of that and every figure in the table improves materially.
Growth — the half of the story the margin debate obscures
Margin has dominated this analysis because margin is what moved. Growth is what the business is actually being bought for, and on that measure every line Solstice sells into is expanding:
| End market | Growth rate | Which business |
|---|---|---|
| Data center / HPC materials | ~14.2% CAGR | Element Electronics |
| HFO refrigerants | ~12.8% CAGR to 2030 | Solstice RAS |
| Advanced packaging | ~9.4–11.8% CAGR | Element Electronics |
| Semiconductor materials | ~5.5–5.8% CAGR | Solstice ESM + Element |
| Uranium conversion | ~5.8% CAGR, $1.2B → $2.1B by 2035 | ConverDyn JV |
And the companies are capturing it. Solstice grew revenue +11% in the first half. Element’s Electronics segment grew 10% organic in 2025, with Q4 Assembly Solutions +12% and Semiconductor Solutions +13% on advanced packaging demand.
The two fastest-growing exposures — data center materials and HFO refrigerants — are precisely where this deal concentrates the company. Data center construction is plausibly the largest single capital-spending program of the next several years, and Element sells the chemistry that forms and joins the circuitry inside it. That is the strategic case, and it is a growth case, not a cost-synergy case.
It also means the 6% blended growth used in the deleveraging model above is conservative, not aggressive. At 8% every figure in that table improves.
Where 12–14x EV/EBITDA sits against the market
| Sector | Typical EV/EBITDA |
|---|---|
| Commodity chemicals | ~8x |
| Specialty chemicals | 10–12x (11.2x average) |
| Semiconductors | ~31.6x |
| Semiconductor equipment & materials | ~34.9x |
Solstice pro-forma sits at 14.1x at close and 12.3x a year later — the top of the specialty-chemicals range, and a small fraction of where semiconductor materials trade. Which is right depends entirely on how the market classifies a company that would have ~40% of revenue in electronics.
Sum-of-the-parts on the combined company, valuing electronics-facing revenue (~$2,700M, ~$594M EBITDA) separately from everything else (~$3,737M, ~$960M EBITDA at 11x):
| Electronics valued at | Implied EV | Per share | vs $56.16 |
|---|---|---|---|
| 15x EV/EBITDA | $19.5B | $48 | −15% |
| 18x (roughly what the market implies today) | $21.3B | $54 | −4% |
| 20x EV/EBITDA | $22.4B | $58 | +4% |
| 25x EV/EBITDA | $25.4B | $69 | +22% |
| 30x EV/EBITDA | $28.4B | $79 | +41% |
At today’s price the market is implicitly valuing the combined electronics franchise at roughly 18x EV/EBITDA — a premium to specialty chemicals, but around half of where semiconductor materials trade. Re-rating that franchise even to 25x, still well below its sector, is worth $69 a share.
That is the case for the deal creating value despite the price paid: Solstice is buying an asset at 26.5x that the market may eventually value at a semiconductor-materials multiple rather than a chemicals one. Management may be paying a full price for a re-rating it expects to capture.
Price target: $62 · range $55–85 · BUY
Path Value Basis Deal breaks — standalone DCF, flat margin $61 11% WACC, 11x exit, margin 25.2%, capex 10%→7% Deal breaks — margin recovers to 28% $69 the recovery case; the record does not support it as a base Deal breaks — margin decline continues to 23% $55 the floor: seven more years of the current trend Deal breaks — return to the pre-deal price $80 where it traded on July 2 Deal closes — 13–14x EV/EBITDA on year-one pro-forma $61–67 EBITDA $1,715M, net debt already $5.1B Deal closes — electronics re-rated to 25x in a sum-of-the-parts $69 still below its sector Deal closes — five years of deleveraging, no re-rating $91–99 10–12% annualised Base $62 is +10% to the August 21 close.
Recommendation: BUY — on the floor, not the ceiling. The asymmetry is still the argument, but it is narrower than it looks:
- If the deal breaks, the standalone business is worth $55–$69 against $56.16 today. Honeywell holds a consent right that could cause exactly this. The low end of that range assumes the worst trend in the business runs uninterrupted for another seven years and still clears today’s price.
- If the deal closes, you own three growing franchises — refrigerants with a legislated substitution cycle, a uranium-conversion JV in a four-firm global market, and a top-tier electronics business selling into the data-center build — at 12.3x EV/EBITDA a year out, deleveraging to 7.1x by year five.
Both outcomes pay, and the downside is bounded by an unusually durable floor. That is what this buy rests on — not on a margin recovery that three years of segment data do not yet support.
On the price management paid
Earlier drafts of this analysis weighted the 26.5x EV/EBITDA purchase price heavily against the investment case. That conflates two different questions. What Solstice paid Element’s shareholders is a judgment on management. What you pay for the combined company is a separate matter, and at $56.16 you are buying the whole thing at 14.1x falling to 12.3x — the top of the specialty-chemicals range for a business with ~40% of revenue in electronics and every end market growing.
The overpayment, if it was one, has already been marked in the price. The −22.5% reaction was the market transferring that cost from Element’s shareholders to Solstice’s. A buyer today inherits the asset without having paid the premium.
What would still make this wrong: the RAS margin decline proving structural rather than transitional, or the combined entity failing to hold a specialty-chemicals multiple at 3.8x leverage. Both are live, and both are why the target is $70 rather than $85.
Sizing note. This is a levered, event-driven position with a binary catalyst and 3.8x pro-forma leverage. The asymmetry justifies owning it; it does not justify owning a lot of it before the Element vote resolves.
What this most resembles
Matching on what should drive the outcome — a fluorochemistry business spun from a diversified industrial parent, high margin, levered on the way out — the universe offers a small but pointed set.
| Company | Parent | Spun | vs Day 1 | Excess vs S&P | Max drawdown |
|---|---|---|---|---|---|
| ESAB | Enovis | Apr 2022 | +84.2% | +6.1pp | −41.8% |
| Corteva | DowDuPont | Jun 2019 | +246.8% | +3.3pp | −35.3% |
| Sylvamo | International Paper | Oct 2021 | +30.4% | −6.2pp | −62.6% |
| Kronos Worldwide | Valhi | Dec 2003 | +140.0% | −6.2pp | −89.2% |
| Chemours | DuPont | Jul 2015 | +47.8% | −8.3pp | −87.3% |
| Dow | DowDuPont | Apr 2019 | −8.9% | −17.4pp | −70.9% |
Two of six beat; median excess −6.2pp, close to the universe median of −7.2%. Chemicals spinoffs are ordinary. What is not ordinary is the drawdown column: four of six fell more than 60%, and two fell more than 87%.
Chemours is the analog that matters, and the reason it matters is not the
return
DuPont spun its fluoroproducts business in July 2015 — the same molecular chemistry, and its Opteon refrigerant line competes directly with Solstice. The shares fell more than 87% within a year of separation, on fears that legacy PFAS environmental liability inherited from the parent would overwhelm the equity.
Solstice does not carry that liability. Its recorded environmental reserve at year-end 2025 was $53 million, and the word “PFAS” does not appear anywhere in its 10-K. The nearest equivalent is a bounded, regulator-supervised asset retirement obligation at the nuclear conversion facility, backed by letters of credit.
That absence is the single most important structural difference between Solstice and the cautionary tale its business most resembles, and it is worth checking rather than assuming, because the assumption has cost people a great deal of money in this exact chemistry.
In depth: competitive dynamics
The sections above establish what happened and what it is worth. The three that follow go underneath that — who Solstice competes with, how it is valued against them, and who might eventually own it.
1. Where Solstice competes, and against whom
| Business | Position | Principal competitors | Assessment |
|---|---|---|---|
| Automotive refrigerants (HFO-1234yf) | ✅ Co-leader in a duopoly | Chemours (Opteon), with Arkema and Chinese producers at the margin | HFO-1234yf is ~87% of HFO market revenue and is produced principally by Solstice and Chemours. Mandated in nearly every new car in regulated markets |
| Stationary refrigerants | ✅ Top tier | Chemours, Arkema, Daikin, Dongyue | The five largest hold ~69% of the market. AIM Act phase-down forces conversion |
| Blowing agents & solvents | ✅ Strong US position | Chemours, Arkema, Central Glass | Formulation is customer-specific; switching is slow |
| Uranium conversion (UF6) | ✅ Only US provider, via a 50/50-style JV | Orano (28.7%), Rosatom (26.5%), Cameco (18.9%), ConverDyn (18.3%) | Four converters globally. ConverDyn is a Solstice / General Atomics joint venture — Solstice’s economics are its JV share, not the whole 18.3% |
| Healthcare packaging (Aclar) | ✅ Leader in high-barrier film | Tekni-Plex, Klöckner Pentaplast, Amcor | 50+ years of position; qualified into pharmaceutical filings |
| Spectra fibers (UHMWPE) | ⚠️ Number two | Avient (Dyneema, acquired from DSM), Toyobo, Chinese producers | Armor and rope; defense-exposed |
| Electronic materials | ⚠️ Mid-tier standalone → ✅ top-tier combined | Entegris, Qnity, JSR, Merck EMD, Element Solutions (the target) | The weakest position standalone. Combined with Element’s $1,786M Electronics segment, electronics-facing revenue reaches ~$2.5–2.9B — roughly Entegris scale. This is what the acquisition actually buys |
2. Market concentration
✅ Effective duopoly in the molecule that matters. HFO-1234yf — the automotive refrigerant mandated across regulated markets — is principally a Solstice / Chemours market. Patent estates, fluorine feedstock integration and OEM qualification make entry slow. This is the single best competitive position the company holds.
✅ Four-firm global oligopoly in uranium conversion, and Solstice co-owns one of the four through ConverDyn, its joint venture with General Atomics. More important than the 18.3% share: with Rosatom’s 26.5% effectively unavailable to Western utilities, the practical Western market is Orano, Cameco and ConverDyn. ConverDyn is the only US-domiciled option in a market where supply-chain domesticity has become policy.
⚠️ Sub-scale in electronic materials — standalone. Solstice is a participant, not a leader, against Entegris, Qnity, JSR and Merck EMD.
✅ The acquisition genuinely fixes this. Element’s Electronics segment is $1,786M of revenue growing 10% organic, with Q4 semiconductor solutions +13% on advanced packaging. Combined electronics-facing revenue of ~$2.5–2.9B puts the merged company at roughly Entegris scale — behind Qnity, ahead of most others, and past the threshold where R&D spend and customer qualification stop being a structural handicap. Whatever the price, the competitive logic is real, and it is the reason a break-up of the combined entity would be harder than a break-up of Solstice today.
3. Moats and weak spots
✅ Strongest moat: regulatory-mandated substitution. The AIM Act and equivalent regimes do not merely encourage LGWP refrigerants — they require them on a schedule. Demand is legislated rather than forecast, which is a materially better foundation than a cyclical end market.
✅ Strong moat: the conversion monopoly. Uranium hexafluoride conversion requires NRC licensing, decades of operating history and a facility nobody is going to permit quickly. Metropolis 2.0 — a proposed second facility — suggests management sees the demand.
✅ Qualification lock-in in healthcare packaging. Aclar is written into pharmaceutical filings; changing barrier film means re-filing.
⚠️ Weak spot: the transition compresses margin before it expands it. RAS margin fell 600bp while the substitution accelerated. The new molecules are the future; they are not yet the better business.
⚠️ Weak spot: sub-scale in electronics. Being seventh in a market of giants is not a position, which is precisely management’s argument for the acquisition.
❓ Emerging question: what replaces HFOs? Regulatory pressure that created the HFO opportunity does not stop at HFOs. Natural refrigerants — CO₂, propane, ammonia — are being pushed in parts of Europe, and trifluoroacetic acid, an HFO breakdown product, is under regulatory attention there. The molecule that is today’s tailwind could be tomorrow’s phase-down, on a decade-plus horizon.
4. Head-to-head: Solstice vs Chemours
The closest listed comparison, and the numbers are more flattering to Solstice than the market’s treatment of the two suggests:
| Solstice | Chemours | |
|---|---|---|
| Q2 2026 net sales | $1,148M | $1,591M |
| Q2 2026 adjusted EBITDA | $290M | $247M |
| Adjusted EBITDA margin | ✅ 25.3% | ⚠️ 15.5% |
| Q2 GAAP net income | positive | ⚠️ −$274M |
| Refrigerant segment margin | 32.9% (RAS) | 36.0% (TSS) |
| Environmental reserve | ✅ $53M | ⚠️ Multi-billion PFAS/PFOA settlements |
| Net leverage | ✅ 1.13x | higher |
Read that table carefully, because it cuts both ways.
✅ Solstice earns a 10-point higher blended margin and is profitable where Chemours is posting large GAAP losses. Chemours’ losses are legacy environmental — PFOA drinking-water accruals and litigation settlements — the liability Solstice does not carry.
⚠️ But in the directly comparable refrigerant segment, Chemours’ TSS runs 36.0% against Solstice’s RAS at 32.9%. A year ago Solstice’s RAS was at 39.4%. Solstice’s refrigerant margin has moved below its closest competitor’s.
Two data points across a single year do not establish a trend, and there are benign explanations: Chemours flagged a strong prior-year comparison in TSS aftermarket, the two companies’ mix and channel exposure differ, and the AIM Act transition is hitting each on a different schedule. This is recorded as something to monitor across the next several quarters, not as a conclusion, and the right next step is to ask management directly for the bridge.
(Chemours’ TSS is refrigerants alone; Solstice’s RAS also contains lower-margin healthcare packaging and nuclear services, so the comparison overstates the gap. Tracked quarterly from here.)
In depth: valuation against peers
1. Margin positioning
| Company | Adjusted EBITDA margin | Business mix |
|---|---|---|
| Solstice | ✅ 25.3% | Fluorochemistry, refrigerants, nuclear conversion, specialty materials |
| Element Solutions (the target) | 21.5% (26.5% excluding pass-through metals) | Electronics chemicals, assembly materials |
| Chemours | ⚠️ 15.5% | Refrigerants + TiO2 commodity + performance materials |
Chemours’ blended margin is dragged by Titanium Technologies, a commodity business Solstice has no equivalent of. On mix, Solstice is the cleaner specialty business of the two.
2. Where Solstice trades
| Multiple | |
|---|---|
| Solstice standalone, EV/EBITDA on FY2026E EBITDA of $1,078M | 9.4x |
| Solstice pro-forma, EV/EBITDA if the deal closes | 14.1x (12.7x with synergies) |
| What Solstice is paying for Element Solutions, EV/EBITDA | 26.5x (19.9x post-synergy) |
The internally inconsistent triangle. A company trading at 9.4x is issuing that paper to buy an asset at 26.5x. Either the market is wrong about Solstice, or management is wrong about Element Solutions, or Element is worth nearly three times Solstice per unit of EBITDA. All three cannot hold, and the −22.5% reaction was the market saying which one it believes.
We do not publish peer trading multiples we cannot source from primary documents. The multiples above are computed from filings and the announced deal terms; broker consensus multiples for Arkema, Celanese and others were not independently verifiable and are therefore omitted rather than estimated.
3. What the standalone multiple implies
At 9.4x, the market is valuing Solstice below where specialty chemistry with a legislated demand driver and a monopoly nuclear asset would normally clear. Applying the deal’s own logic — Solstice believes 19.9x post-synergy is a fair price for a ~24%-margin electronics business — the company’s own revealed view of fair value for a business like itself is far above where its own shares trade.
That is either an argument that the shares are cheap, or an argument that management is overpaying. It cannot be neither.
In depth: is Solstice an acquisition target?
Not before October 30, 2027 — but the question worth asking is who buys it after that, and the answer is more interesting than for most spinoffs this size.
Why it is blocked now
The §355(e) window from the Honeywell separation runs to October 30, 2027: an acquisition of 50% or more inside two years is presumed part of a plan related to the distribution and would make the separation taxable to Honeywell, with the cost landing on Solstice under the Tax Matters Agreement. On top of the statute, the Merger Agreement contains a no-shop, and the 10-Q concedes these provisions “may discourage a potential third-party acquirer.”
So Solstice is doubly locked: by tax law until October 2027, and by its own merger agreement until that deal resolves.
Who the buyers are once it clears
Standalone enterprise value is roughly $10B — comfortably digestible, unlike most large spinoffs. If the Element deal closes, that rises to roughly $22B and the buyer list shortens considerably. The two scenarios are genuinely different, which is itself a reason the deal’s outcome matters beyond the price.
| Acquirer | Fit | Assessment |
|---|---|---|
| Daikin | ✅ Best strategic fit | The world’s largest HVAC manufacturer buying its refrigerant supply. Vertical integration, obvious industrial logic, and the balance sheet to do it. Antitrust review would be manageable because Daikin is a customer, not a competitor, in most lines |
| Arkema | ⚠️ Strong fit, hard approval | French fluorochemicals with a direct refrigerant overlap. Serious antitrust problems in HFOs precisely because the fit is good |
| Orbia | ⚠️ Plausible | Fluorine value-chain integration from feedstock upward; smaller balance sheet |
| Private equity (Apollo, SK Capital, CD&R, Advent) | ✅ Credible at $10B | Specialty chemistry with 25% margins, legislated demand and low leverage is exactly the profile. SK Capital and Advent have specific chemicals track records. Far harder at $22B post-deal |
| Chemours | ❌ Unable | The most logical industrial combination in refrigerants, and completely foreclosed: Chemours is posting large GAAP losses on legacy environmental settlements and cannot fund it |
| Linde / Air Liquide | ❓ Adjacent | Industrial gases with fluorine-chain adjacency; neither is an obvious buyer of a refrigerants business |
Break-up or takeover? The deal decides it
Solstice’s three franchises have three different natural owners, and none of them wants all three. That is unusual and it is the most interesting structural fact about the company:
| Asset | Natural owner |
|---|---|
| Refrigerants & blowing agents | Daikin, Arkema, Orbia — or PE |
| Nuclear — Solstice’s stake in the ConverDyn JV | General Atomics has the obvious first call as the existing JV partner; otherwise Cameco or a utility consortium. A strategic US asset in a four-firm global market, with policy support for domestic fuel-cycle capacity |
| Spectra fibers (UHMWPE) | Avient, which already owns Dyneema, or a defense prime |
| Healthcare packaging (Aclar) | Amcor, Tekni-Plex, or packaging-focused PE |
| Electronic materials | Entegris — or whatever the Element Solutions combination becomes |
The sum-of-the-parts question this raises. A conversion monopoly, a mandated-substitution chemicals franchise, a defense fibre and a qualified pharmaceutical packaging business sit inside one 9.4x multiple. Each would likely clear at a higher multiple standing alone, and to different buyers.
The Element Solutions acquisition cuts against this, and that is an argument in its favor. It makes electronic materials a coherent, top-tier franchise rather than a sub-scale orphan — which is the one segment that most needed fixing and the one a break-up would have struggled to place well. The cost is that the combined company is larger, more levered and harder for anyone to buy, so it defers the break-up option rather than resolving it.
Both readings are legitimate. If you believe the sum of the parts exceeds the whole, the deal destroys that option. If you believe electronics needed scale to be worth anything, the deal creates the value a break-up could not. The price paid is what decides which is true, and at 26.5x it is a close call.
Probability, stated as judgment rather than fact:
| Scenario | Rough odds |
|---|---|
| Completes Element, remains independent | ⚠️ 55% |
| Deal breaks or is repriced, remains independent | ⚠️ 25% |
| Acquired whole after October 2027 | ❓ 10% |
| Break-up or divestiture of one franchise | ❓ 10% |
The investment case does not depend on a takeover. It depends on the standalone margin recovering and on the acquisition being priced sensibly. The acquisition optionality is a 2028 conversation, and it is worth more if the Element deal does not happen.
A possible transaction: does Qnity buy the electronics business?
Speculative, and set out because the pieces fit unusually well.
Once the Element acquisition closes, Solstice would hold roughly $2.5–2.9B of electronics-facing revenue alongside a refrigerants franchise and a uranium conversion JV — three good businesses with almost nothing in common. The natural question is whether someone eventually buys the electronics half.
Qnity Electronics is the obvious candidate, and the fit is better than it first looks:
| Complementary, not overlapping | Qnity sells front-end semiconductor materials — CMP pads and slurries, photoresists. Element sells back-end chemistry — metallisation, solderable finishes, assembly pastes. They meet at advanced packaging and barely compete elsewhere. Antitrust review would be far easier than for two front-end suppliers |
| Scale | Qnity at ~$5.6B plus ~$2.7B would be a ~$8B electronic-materials company — decisively the largest Western supplier |
| Capacity to pay | Qnity carries 1.80x net leverage with an undrawn $1.25B revolver and a ~$27B market capitalization. A ~$12B transaction is fundable in cash and stock without breaching its own §355(e) 50% stock-issuance ceiling |
| Timing | Qnity’s own two-year window closes November 3, 2027; Solstice’s closes October 30, 2027. Both clear within days of each other |
| Strategic logic for Solstice | Selling electronics would leave a focused refrigerants-and-nuclear company — arguably the cleanest version of what the Honeywell separation was meant to create |
Why it probably does not happen soon. Solstice would be selling, at some price, an asset it had just paid 26.5x EV/EBITDA for. Doing that within two or three years would be an admission that the acquisition was a mistake, and no management team volunteers for that. Realistically this is a 2029–2030 conversation, not a 2028 one — after integration, after the synergies are banked, and after the electronics franchise has a standalone track record worth paying for.
Why it is worth writing down anyway. It reframes the Element acquisition. If Solstice is assembling an electronics business of genuine scale, it is creating something with a natural buyer at a semiconductor-materials multiple rather than a chemicals one. That is a coherent value-creation path even if the entry price was full — buy at 26.5x in a chemicals wrapper, sell at a semiconductor multiple once the scale is visible.
Whether that is the plan or a retrospective rationalisation is unknowable from outside. It is, however, the most plausible answer to “why pay that much.”
Tail scenarios
Outcomes outside the base/bull/bear frame — low probability, high magnitude, but short of black swan. Roughly two to three standard deviations.
Upside tails
1. The nuclear asset stops being a rounding error. This is the largest mispriced optionality on the page, and the filings are unusually explicit about it. Solstice’s AES Facility is, in the company’s own words, “the only U.S.-based supplier” of uranium hexafluoride conversion, and “together with our joint venture partner General Atomics, we are the only provider of these services in the U.S.” The earnings ramp is already visible:
| Net income attributable to the ConverDyn minority | 2023 | 2024 | 2025 | 1H 2026 |
|---|---|---|---|---|
| $(2)M | $11M | $48M | $35M (+340%) |
Solstice’s own half runs alongside it. A business that contributed nothing in 2023 is contributing roughly $0.35 a share in 2026, and it is accelerating, not maturing. Conversion is a three-supplier Western market; the US restriction on Russian enriched uranium removed a large source of supply, and datacenter-driven nuclear demand is arriving on top. The Department of Energy has separately agreed to act to assure the facility’s continued operational availability, including reimbursing certain litigation costs — a level of state support that tells you how strategic the asset is.
If Solstice’s share of conversion earnings reaches $100M pre-tax and a strategic buyer — General Atomics has the first call — paid 15x, that is $1.5B, or about $9 a share, against an asset the market is currently valuing inside a specialty-chemicals blend. The market is paying a chemicals multiple for a regulated national-security monopoly.
2. Honeywell blocks the deal and the RAS margin turns. Two independent things both breaking right. The standalone recovery case is $69; a business demonstrably back on a 28% margin would not trade at 11x exit, and the same model at 13x reaches $82. This is the only path to a materially higher price in the next eighteen months.
3. Electronic & Specialty Materials gets valued for what it is. ESM is earning 21.2% and rising, in semiconductor and defense materials, against a semiconductor-materials peer group at ~35x. At even 20x its $203M of EBITDA, ESM alone is $4.1B against a $10.1B enterprise value — leaving the refrigerant and nuclear franchises at roughly 6x. If the Element deal closes, this stops being a tail and becomes the stated strategy, which is the strongest argument for the transaction that management has not made forcefully enough.
Downside tails
1. Chinese HFO capacity arrives before the patents run out. The 10-K names this directly: “If third parties expand their manufacturing capacity for refrigerants in China (including in respect of HFOs), third-party infringement of our intellectual property rights may increase.” And the protective wall is already thinning — on R-1234yf, “certain patents relating to applications of the technology have expired or are near expiration,” with composition patents running only “into the 2030s.”
This is how the HFC generation ended, and Solstice was the beneficiary that time. A molecule protected by composition patents earns 35–40% margins; the same molecule off-patent with Chinese capacity earns 15–20%. RAS at 20% instead of 35% is roughly $420M of lost EBITDA — more than 40% of the whole company’s earnings. The timing is a decade out, which is precisely the horizon a DCF terminal value is most sensitive to and least able to see.
2. The REACH Recast captures fluorinated chemistry. The company lists among its risks “other potential future regulations related to fluorinated chemistries … such as the REACH Recast, a large-scale revision of the current REACH regulation that will … expand the in-scope hazardous substances subject to REACH.” The entire LGWP thesis assumes regulators keep pushing users toward Solstice’s molecules. A European regime that treats fluorinated chemistry as the problem rather than the solution inverts the central driver of the business. Low probability on any given year; not remote over a decade.
3. The AES radiation litigation certifies as a class. Eight cancer suits were settled in 2024. Still live: municipal contamination claims from the city of Metropolis and Massac County, a personal-injury case, and a class action on behalf of every property owner within three miles of the plant. The company expects rulings on both summary judgment and class certification in 2026 and says it does not anticipate a material effect. Class certification would change that arithmetic, and it is a dated binary inside the next four months — sitting under the same asset that carries the largest upside tail above.
4. The deal closes into an electronics cycle top. Solstice would be paying 26.5x for Element at 3.8x pro-forma leverage, into semiconductor end markets at peak. If Element’s electronics EBITDA falls 25% post-close, combined EBITDA goes to roughly $1,450M and leverage to ~4.1x. A levered chemicals roll-up in a downcycle does not hold 14x; at 10x, the equity is worth about $8.6B across ~284M pro-forma shares — near $30 a share. This is the genuine tail risk of the transaction, and it is the mirror image of the deleveraging case above: the same leverage that compounds equity value at 24% margins destroys it at 20%.
What would change this view
| Direction | Trigger |
|---|---|
| Better | RAS margin stabilising for two consecutive quarters · the merger being abandoned or repriced downward · Element shareholders rejecting the deal · nuclear conversion capacity expansion, which would make a monopoly asset visible in the numbers |
| Worse | RAS margin falling below 32% and staying there, which would make the LGWP transition look structural · the deal closing and the combined entity failing to hold a 12x multiple at 3.5x leverage · permanent financing pricing materially above the assumed cost |
| Dated, in 2026 | Rulings expected this year on both summary judgment and class certification in the AES Facility radiation litigation — a three-mile-radius property class. The company expects no material effect; certification would test that |
| Thesis-breaking | Any PFAS-style environmental claim reaching this entity despite the current $53M reserve · loss of the exclusive US position in uranium conversion |
Investment Scorecard
Scored on the five weighted dimensions set out in our methodology.
| Dimension | Weight | Score | Rationale |
|---|---|---|---|
| Financial Profile | 25% | 3.0 | Net leverage of just 1.13x standalone and $750M of cash, on 11% revenue growth. Held down hard by the three-year record: adjusted EBITDA margin 29.9% → 25.7% → 25.2% with 2025 EBITDA below 2023 in absolute dollars, normalized standalone EPS down 14% since 2023 (24% excluding ConverDyn), and pro-forma leverage rising to ~3.5x if the deal closes |
| Competitive Position | 25% | 4.5 | A regulatory-mandated substitution cycle in LGWP refrigerants with established brands, plus the only US provider of uranium hexafluoride conversion. Three defensible franchises: a duopoly in HFO-1234yf, a four-firm global oligopoly in uranium conversion, and — post-Element — a top-tier Western electronic-materials business. Held below 5 by real competition in refrigerants |
| Strategic Rationale | 20% | 4.0 | A coherent separation, followed by an acquisition that fixes the weakest segment with the strongest available asset in the fastest-growing end market. Data-center construction is plausibly the largest capital program of the next several years and Element sells directly into it. Discounted only for the price paid |
| Management & Governance | 20% | 3.5 | A credentialed team acting decisively — a CEO who ran WestRock through a transatlantic combination, a chair who ran the Honeywell division these assets came from. The Element deal is strategically right even where the price is arguable. Held below 4 by three quarters of standalone history |
| Acquisition Potential | 10% | 2.5 | Blocked by §355(e) until October 2027 and by the merger no-shop. Beyond that, three separable franchises with distinct natural owners — and a plausible Qnity route for the electronics half |
| Weighted Score | 3.63 | ||
| Investment Grade | A− · Strong Opportunity |
What the capital-allocation and value-chain work changed: nothing, deliberately
Both sections were added after this grade was set, and the evidence in them nets out rather than moving a dimension:
- Financial Profile stays at 3.0. Against it: 2025 free cash flow of $119M against $546M in 2024, and cash conversion falling from 77% of adjusted EBITDA to 46%. For it: the first half of 2026 already exceeds all of 2025 on operating cash flow, free cash flow is up 45%, and capital expenditure at 169–184% of depreciation is growth spending rather than maintenance — the same fact that explains the under-absorbed fixed cost in the margin line.
- Competitive Position stays at 4.5. The value-chain section adds a genuine positive the original grade did not price — demonstrated pricing power, which the refrigerant patents and the AIM Act mandate together explain. Against it, the weakest of the three tiers is the one the Element acquisition would enlarge.
Neither is a small finding; they simply point in opposite directions within the same dimension. Recording that is more useful than moving a number by a quarter-point in either direction.
First grade for this company
Solstice has been carried as a completed spinoff without a grade since separation. A− (3.63) is where the scorecard lands.
An earlier draft scored 3.75 on a 3.5 Financial Profile, before the three-year segment history was pulled. That history moved Financial Profile to 3.0 — the margin decline is three years old, not two quarters — which is a genuine markdown and lands the score at 3.63. The band does not change, and it should not: the evidence changed the quality of the financial record, not the quality of the franchise.
An earlier draft scored it B+ (3.28), marking down Strategic Rationale and Management for the price paid for Element Solutions. That was double-counting a single objection — the purchase price is already reflected in the share price a buyer pays today, and penalising the strategy and the management for it as well charges the same fact three times. The strategic logic is sound, the end market is the fastest-growing one available, and the team executed decisively. The price is a valuation input, not a character flaw.
The grade takes effect with the next published report.
What would take it to A: RAS margin stabilising for two consecutive quarters, or the combined electronics franchise beginning to earn a semiconductor-materials multiple rather than a chemicals one. What would take it back down is evidence that the RAS decline is structural, or an integration that consumes the synergies.