Versant VSNT
-30.4%vs Day 1Spinoff of Comcast (CMCSA) · Classic Spinoff · Spun Jan 5, 2026
Expected return (11/13/2026): +12% Gain to loss: 2.4 : 1Cable networks in managed decline: about $1.2B of free cash flow in 2026 against $1.9B of net debt; the price implies a steeper decline than the recent record. Cases $80.53 / $37.08 / $23.83, weighted 15/60/25, $40; the best case needs programming costs to fall as fast as linear revenue. ACCUMULATE, target $40.
Current Stats
Post-Spinoff Performance
| Timeline | |
| Spinoff date | January 5, 2026 · Nasdaq |
| Days since spinoff | 313 days |
| Structure | Classic Spinoff |
| §355(e) window closes statutory; a tax matters agreement may bar more, and for longer | January 5, 2028 |
| Parent | Comcast (CMCSA) |
| Day-1 reaction | |
| Day 1 open | $45.17 |
| Day 1 return (open→close) | -10.2% |
| Day 1 price (close) | $40.57 reported $45.17 (open) |
| Day 1 range | $39.28 – $45.65 +16.2% spread |
| Day 1 low held? | Breached after 1 session to -30.8% below |
| Price levels | |
| Post-spin low (closing) | $27.42 on Feb 12, 2026 · 38 days post-spin |
| Current price (Nov 13, 2026) | $35.94 |
| Returns | |
| Return vs Day 1 (close) | -8.6% |
| — range by day 1 entry theoretical bounds | -18.8% to -5.6% |
| Return vs post-spin low (price) | +31.1% |
| Total return vs low incl. dividends since | +35.2% |
| First-quarter return (≈90d) | -6.8% |
| Versus benchmarks | |
| S&P 500 over same window | +10.6% |
| Shares & ownership | |
| Shares outstanding Sep 30, 2026 | 136,625,720 |
| Diluted average shares the EPS denominator | 138,538,000 |
| Free float | 135,236,904 99% of shares outstanding |
| Held by institutions | 91% insiders 0.4% |
| Share count trend Jun 2025 → Sep 2026 | -5.5% net buyback |
| Volume & liquidity | |
| Traded per day 20-session median | $59M |
| Normal volume baseline | 2,158,050 shares · now 0.81x |
| Day 1 volume | 19.2x normal · first week 9.2x |
| Decay | half in 2 sessions · normal by 20 |
Computed from split-adjusted closing prices. Returns are total return — (end price + dividends received − start price) ÷ start price — with no reinvestment assumed.
Price History
Closing price, split-adjusted, with volume below. The Price line excludes dividends; Price + dividends adds the cash paid out, with no reinvestment assumed. Individual payments are listed in the table below. Source: Yahoo Finance. Data through Nov 14, 2026.
Raw daily price & volume data · dividends marked
| Date | Open | High | Low | Close | Volume | Float | Turnover | Market cap | Dividend | Split |
|---|---|---|---|---|---|---|---|---|---|---|
| 2026-11-13 | $35.83 | $36.22 | $35.56 | $35.94 | 1,704,400 | 135,236,904 | 1.25% | $4.91B | — | — |
| 2026-11-12 | $36.26 | $36.34 | $35.53 | $35.54 | 1,237,100 | 135,236,904 | 0.91% | $4.86B | — | — |
| 2026-11-11 | $35.13 | $36.15 | $34.65 | $36.14 | 1,571,300 | 135,236,904 | 1.15% | $4.94B | — | — |
| 2026-11-10 | $34.95 | $35.09 | $34.27 | $34.93 | 2,227,900 | 135,236,904 | 1.63% | $4.77B | — | — |
| 2026-11-09 | $33.91 | $35.13 | $33.73 | $35.09 | 1,528,800 | 135,236,904 | 1.12% | $4.79B | — | — |
| 2026-11-06 | $33.50 | $34.48 | $33.29 | $33.69 | 1,996,900 | 135,236,904 | 1.46% | $4.60B | — | — |
| 2026-11-05 | $34.48 | $35.07 | $33.50 | $34.00 | 3,782,400 | 135,236,904 | 2.77% | $4.65B | — | — |
| 2026-11-04 | $33.18 | $34.99 | $33.07 | $33.98 | 4,531,400 | 135,236,904 | 3.32% | $4.64B | — | — |
| 2026-11-03 | $32.21 | $34.18 | $32.08 | $32.69 | 4,175,300 | 135,236,904 | 3.06% | $4.47B | — | — |
| 2026-11-02 | $31.50 | $32.65 | $31.45 | $32.34 | 3,777,900 | 135,236,904 | 2.77% | $4.42B | — | — |
| 2026-10-30 | $31.26 | $31.65 | $30.93 | $31.42 | 1,790,600 | 135,262,876 | 1.31% | $4.29B | — | — |
| 2026-10-29 | $30.66 | $31.02 | $30.59 | $31.00 | 1,425,200 | 135,262,876 | 1.04% | $4.24B | — | — |
| 2026-10-28 | $30.79 | $30.98 | $30.35 | $30.67 | 2,211,600 | 135,196,615 | 1.62% | $4.19B | — | — |
| 2026-10-27 | $30.58 | $31.26 | $30.33 | $30.85 | 2,114,700 | 137,714,359 | 1.55% | $4.21B | — | — |
| 2026-10-26 | $31.52 | $31.75 | $30.33 | $30.63 | 1,487,300 | 137,714,359 | 1.09% | $4.18B | — | — |
| 2026-10-23 | $31.84 | $32.26 | $31.34 | $31.43 | 1,124,100 | 137,714,359 | 0.82% | $4.29B | — | — |
| 2026-10-22 | $31.49 | $32.46 | $31.45 | $32.29 | 1,399,100 | 137,714,359 | 1.02% | $4.41B | — | — |
| 2026-10-21 | $31.70 | $31.70 | $31.11 | $31.35 | 1,569,000 | 137,714,359 | 1.15% | $4.28B | — | — |
| 2026-10-20 | $31.81 | $32.18 | $31.35 | $31.73 | 2,369,100 | 137,714,359 | 1.73% | $4.34B | — | — |
| 2026-10-19 | $31.77 | $31.80 | $31.26 | $31.54 | 1,674,800 | 137,714,359 | 1.23% | $4.31B | — | — |
| 2026-10-16 | $31.50 | $32.38 | $31.28 | $31.77 | 2,070,900 | 137,714,359 | 1.52% | $4.34B | — | — |
| 2026-10-15 | $31.07 | $31.52 | $30.90 | $31.24 | 1,788,300 | 137,714,359 | 1.31% | $4.27B | — | — |
| 2026-10-14 | $31.00 | $31.00 | $30.43 | $30.98 | 1,948,000 | 137,714,359 | 1.43% | $4.23B | — | — |
| 2026-10-13 | $30.69 | $31.20 | $30.64 | $31.06 | 1,328,700 | 137,714,359 | 0.97% | $4.24B | — | — |
| 2026-10-12 | $30.77 | $30.92 | $30.37 | $30.60 | 1,334,200 | 137,714,359 | 0.98% | $4.18B | — | — |
| 2026-10-09 | $31.60 | $31.62 | $30.53 | $30.64 | 1,278,900 | 137,714,359 | 0.94% | $4.19B | — | — |
| 2026-10-08 | $31.42 | $31.84 | $30.83 | $31.77 | 2,092,800 | 137,714,359 | 1.53% | $4.34B | — | — |
| 2026-10-07 | $31.36 | $31.60 | $31.07 | $31.44 | 1,733,000 | 137,714,359 | 1.27% | $4.30B | — | — |
| 2026-10-06 | $31.19 | $31.87 | $30.92 | $31.47 | 1,863,100 | 137,714,359 | 1.36% | $4.30B | — | — |
| 2026-10-05 | $30.81 | $31.06 | $30.14 | $31.02 | 2,180,700 | 137,714,359 | 1.60% | $4.24B | — | — |
| 2026-10-02 | $30.84 | $31.10 | $30.57 | $30.94 | 2,017,500 | 137,714,359 | 1.48% | $4.23B | — | — |
| 2026-10-01 | $31.47 | $31.47 | $29.75 | $30.84 | 2,631,700 | 137,714,359 | 1.93% | $4.21B | $0.38 | — |
| 2026-09-30 | $32.14 | $32.53 | $31.45 | $31.70 | 1,877,300 | 137,714,359 | 1.37% | $4.33B | — | — |
| 2026-09-29 | $32.39 | $32.67 | $32.10 | $32.17 | 1,269,100 | 137,714,359 | 0.91% | $4.48B | — | — |
| 2026-09-28 | $32.92 | $32.92 | $32.15 | $32.46 | 1,351,000 | 137,714,359 | 0.97% | $4.52B | — | — |
| 2026-09-25 | $33.26 | $33.96 | $32.76 | $32.80 | 1,322,600 | 137,714,359 | 0.95% | $4.56B | — | — |
| 2026-09-24 | $33.20 | $33.51 | $32.60 | $33.50 | 2,153,900 | 137,714,359 | 1.55% | $4.66B | — | — |
| 2026-09-23 | $33.50 | $33.61 | $32.77 | $33.04 | 1,415,600 | 137,714,359 | 1.02% | $4.60B | — | — |
| 2026-09-22 | $34.79 | $34.89 | $33.33 | $33.51 | 1,600,800 | 137,714,359 | 1.15% | $4.66B | — | — |
| 2026-09-21 | $35.35 | $35.39 | $34.38 | $34.70 | 1,656,700 | 137,714,359 | 1.19% | $4.83B | — | — |
| 2026-09-18 | $36.06 | $36.49 | $34.49 | $35.18 | 5,813,300 | 137,714,359 | 4.18% | $4.90B | — | — |
| 2026-09-17 | $37.82 | $37.95 | $36.24 | $36.33 | 1,733,900 | 137,714,359 | 1.25% | $5.06B | — | — |
| 2026-09-16 | $37.37 | $38.27 | $37.16 | $37.69 | 1,783,100 | 137,714,359 | 1.28% | $5.24B | — | — |
| 2026-09-15 | $37.46 | $37.81 | $37.15 | $37.49 | 1,493,600 | 137,714,359 | 1.07% | $5.22B | — | — |
| 2026-09-14 | $37.24 | $38.12 | $37.14 | $37.56 | 1,264,800 | 137,714,359 | 0.91% | $5.23B | — | — |
| 2026-09-11 | $37.36 | $37.61 | $36.82 | $37.19 | 1,021,700 | 137,714,359 | 0.73% | $5.18B | — | — |
| 2026-09-10 | $37.18 | $37.72 | $37.01 | $37.36 | 1,269,400 | 137,714,359 | 0.91% | $5.20B | — | — |
| 2026-09-09 | $38.25 | $38.25 | $37.18 | $37.21 | 1,316,600 | 137,714,359 | 0.95% | $5.18B | — | — |
| 2026-09-08 | $38.38 | $39.04 | $37.57 | $38.25 | 1,370,700 | 137,714,359 | 0.99% | $5.32B | — | — |
| 2026-09-04 | $40.75 | $40.75 | $38.52 | $38.61 | 1,387,600 | 137,714,359 | 1.00% | $5.37B | — | — |
| 2026-09-03 | $41.98 | $42.28 | $40.91 | $40.97 | 1,451,500 | 137,714,359 | 1.04% | $5.70B | — | — |
| 2026-09-02 | $40.29 | $42.36 | $40.29 | $41.53 | 1,612,100 | 137,714,359 | 1.16% | $5.78B | — | — |
| 2026-09-01 | $41.05 | $41.05 | $40.06 | $40.31 | 1,279,400 | 137,714,359 | 0.92% | $5.61B | — | — |
| 2026-08-31 | $40.95 | $41.45 | $40.67 | $41.12 | 1,919,900 | 137,714,359 | 1.38% | $5.72B | — | — |
| 2026-08-28 | $40.61 | $41.47 | $40.18 | $41.02 | 1,439,600 | 137,714,359 | 1.03% | $5.71B | — | — |
| 2026-08-27 | $39.28 | $40.26 | $39.11 | $39.48 | 1,825,200 | 137,714,359 | 1.31% | $5.49B | — | — |
| 2026-08-26 | $39.78 | $39.99 | $39.20 | $39.27 | 886,400 | 137,714,359 | 0.64% | $5.46B | — | — |
| 2026-08-25 | $39.33 | $39.95 | $38.70 | $39.87 | 845,000 | 137,714,359 | 0.61% | $5.55B | — | — |
| 2026-08-24 | $38.84 | $39.81 | $38.62 | $39.33 | 1,463,800 | 137,714,359 | 1.05% | $5.47B | — | — |
| 2026-08-21 | $38.89 | $39.31 | $38.38 | $38.75 | 1,484,600 | 137,714,359 | 1.07% | $5.39B | — | — |
| 2026-08-20 | $39.16 | $39.36 | $38.40 | $38.63 | 1,445,800 | 137,714,359 | 1.04% | $5.38B | — | — |
| 2026-08-19 | $39.29 | $40.31 | $39.14 | $39.26 | 1,226,900 | 137,714,359 | 0.88% | $5.46B | — | — |
| 2026-08-18 | $39.14 | $39.93 | $39.02 | $39.49 | 1,371,000 | 137,714,359 | 0.99% | $5.50B | — | — |
| 2026-08-17 | $39.21 | $39.52 | $38.53 | $39.23 | 1,388,200 | 137,714,359 | 1.00% | $5.46B | — | — |
| 2026-08-14 | $39.19 | $39.91 | $39.10 | $39.65 | 1,569,300 | 137,714,359 | 1.13% | $5.52B | — | — |
| 2026-08-13 | $37.88 | $39.06 | $37.79 | $38.91 | 1,705,000 | — | 1.23% | $5.41B | — | — |
| 2026-08-12 | $36.82 | $37.94 | $36.53 | $37.87 | 1,771,700 | — | 1.27% | $5.27B | — | — |
| 2026-08-11 | $36.76 | $37.06 | $36.35 | $36.76 | 1,700,300 | — | 1.22% | $5.12B | — | — |
| 2026-08-10 | $38.33 | $38.57 | $36.24 | $36.76 | 2,848,500 | — | 2.05% | $5.12B | — | — |
| 2026-08-07 | $38.05 | $39.17 | $37.42 | $38.67 | 2,179,400 | — | 1.57% | $5.38B | — | — |
| 2026-08-06 | $40.06 | $41.27 | $38.10 | $38.22 | 4,958,200 | — | 3.56% | $5.32B | — | — |
| 2026-08-05 | $36.77 | $36.77 | $35.50 | $35.79 | 1,900,300 | — | 1.37% | $4.98B | — | — |
| 2026-08-04 | $36.21 | $36.91 | $35.88 | $36.38 | 1,833,800 | — | 1.32% | $5.06B | — | — |
| 2026-08-03 | $36.25 | $36.94 | $36.19 | $36.82 | 1,397,200 | — | 1.00% | $5.12B | — | — |
| 2026-07-31 | $36.06 | $36.15 | $35.34 | $35.99 | 1,590,500 | — | 1.14% | $5.01B | — | — |
| 2026-07-30 | $36.56 | $37.00 | $35.67 | $35.89 | 1,255,500 | — | 0.90% | $4.99B | — | — |
| 2026-07-29 | $37.24 | $37.61 | $36.77 | $36.95 | 1,216,100 | — | 0.87% | $5.14B | — | — |
| 2026-07-28 | $35.91 | $37.47 | $35.90 | $37.24 | 1,553,400 | — | 1.12% | $5.18B | — | — |
| 2026-07-27 | $35.83 | $36.32 | $35.65 | $35.88 | 1,811,100 | — | 1.30% | $4.99B | — | — |
| 2026-07-24 | $35.49 | $36.14 | $35.26 | $35.38 | 1,436,100 | — | 1.03% | $4.92B | — | — |
| 2026-07-23 | $36.15 | $36.40 | $35.10 | $35.56 | 1,621,800 | — | 1.17% | $4.95B | — | — |
| 2026-07-22 | $36.28 | $36.50 | $35.97 | $36.19 | 1,319,700 | — | 0.95% | $5.04B | — | — |
| 2026-07-21 | $36.00 | $36.37 | $35.72 | $36.15 | 1,507,100 | — | 1.08% | $5.03B | — | — |
| 2026-07-20 | $35.85 | $36.42 | $35.71 | $35.96 | 1,315,500 | — | 0.95% | $5.00B | — | — |
| 2026-07-17 | $36.41 | $36.60 | $35.70 | $35.90 | 1,701,800 | — | 1.22% | $5.00B | — | — |
| 2026-07-16 | $36.07 | $36.78 | $35.85 | $36.35 | 1,904,800 | — | 1.37% | $5.06B | — | — |
| 2026-07-15 | $35.32 | $36.16 | $35.25 | $36.03 | 2,010,200 | — | 1.44% | $5.01B | — | — |
| 2026-07-14 | $35.53 | $35.93 | $34.56 | $34.80 | 1,919,800 | — | 1.38% | $4.84B | — | — |
| 2026-07-13 | $35.73 | $36.65 | $35.48 | $35.66 | 1,919,500 | — | 1.38% | $4.96B | — | — |
| 2026-07-10 | $36.02 | $36.20 | $35.16 | $35.39 | 1,644,000 | — | 1.18% | $4.92B | — | — |
| 2026-07-09 | $35.75 | $36.15 | $35.25 | $35.81 | 1,558,400 | — | 1.12% | $4.98B | — | — |
| 2026-07-08 | $37.32 | $37.37 | $35.89 | $36.00 | 1,537,500 | — | 1.10% | $5.01B | — | — |
| 2026-07-07 | $37.68 | $38.12 | $37.08 | $37.39 | 1,722,000 | — | 1.24% | $5.20B | — | — |
| 2026-07-06 | $37.92 | $38.13 | $36.17 | $37.22 | 2,334,400 | — | 1.68% | $5.18B | — | — |
| 2026-07-02 | $36.86 | $38.01 | $36.66 | $37.95 | 1,903,900 | — | 1.37% | $5.28B | — | — |
| 2026-07-01 | $35.76 | $36.97 | $35.75 | $36.36 | 1,967,100 | — | 1.41% | $5.06B | $0.38 | — |
| 2026-06-30 | $36.00 | $36.49 | $35.36 | $36.01 | 1,700,700 | — | 1.22% | $5.01B | — | — |
| 2026-06-29 | $36.56 | $37.69 | $35.89 | $35.97 | 2,217,500 | — | 1.57% | $5.09B | — | — |
| 2026-06-26 | $35.61 | $36.69 | $35.54 | $36.14 | 5,422,800 | — | 3.83% | $5.11B | — | — |
| 2026-06-25 | $37.95 | $38.00 | $35.79 | $35.85 | 2,252,400 | — | 1.59% | $5.07B | — | — |
| 2026-06-24 | $37.70 | $38.67 | $37.69 | $38.16 | 2,739,000 | — | 1.94% | $5.40B | — | — |
| 2026-06-23 | $38.28 | $38.39 | $37.15 | $37.88 | 2,127,100 | — | 1.50% | $5.36B | — | — |
| 2026-06-22 | $37.96 | $38.61 | $37.76 | $38.53 | 2,232,000 | — | 1.58% | $5.45B | — | — |
| 2026-06-18 | $37.97 | $38.30 | $37.35 | $38.21 | 5,241,400 | — | 3.70% | $5.41B | — | — |
| 2026-06-17 | $38.07 | $38.92 | $37.84 | $38.13 | 2,736,600 | — | 1.93% | $5.39B | — | — |
| 2026-06-16 | $38.85 | $39.15 | $37.72 | $38.62 | 2,000,200 | — | 1.41% | $5.46B | — | — |
| 2026-06-15 | $40.27 | $40.54 | $38.60 | $38.94 | 2,250,000 | — | 1.59% | $5.51B | — | — |
| 2026-06-12 | $40.06 | $40.54 | $39.57 | $40.53 | 1,352,000 | — | 0.96% | $5.73B | — | — |
| 2026-06-11 | $39.87 | $40.26 | $39.20 | $40.09 | 1,788,600 | — | 1.26% | $5.67B | — | — |
| 2026-06-10 | $40.82 | $40.98 | $39.39 | $39.49 | 1,291,500 | — | 0.91% | $5.59B | — | — |
| 2026-06-09 | $41.46 | $42.10 | $40.26 | $40.65 | 1,190,100 | — | 0.84% | $5.75B | — | — |
| 2026-06-08 | $40.69 | $42.02 | $39.95 | $41.46 | 1,467,900 | — | 1.04% | $5.87B | — | — |
| 2026-06-05 | $40.06 | $40.30 | $39.38 | $40.19 | 1,115,100 | — | 0.79% | $5.69B | — | — |
| 2026-06-04 | $40.23 | $40.72 | $39.80 | $40.22 | 1,225,500 | — | 0.87% | $5.69B | — | — |
| 2026-06-03 | $41.52 | $42.13 | $40.19 | $40.21 | 1,857,500 | — | 1.31% | $5.69B | — | — |
| 2026-06-02 | $42.42 | $42.61 | $41.40 | $41.51 | 1,831,300 | — | 1.29% | $5.87B | — | — |
| 2026-06-01 | $43.09 | $43.09 | $41.70 | $42.61 | 2,303,800 | — | 1.63% | $6.03B | — | — |
| 2026-05-29 | $42.80 | $43.16 | $42.46 | $43.14 | 1,884,300 | — | 1.33% | $6.10B | — | — |
| 2026-05-28 | $43.22 | $43.69 | $43.00 | $43.33 | 1,371,300 | — | 0.97% | $6.13B | — | — |
| 2026-05-27 | $42.63 | $43.82 | $42.60 | $43.40 | 1,287,100 | — | 0.91% | $6.14B | — | — |
| 2026-05-26 | $42.90 | $43.35 | $42.60 | $42.70 | 1,620,100 | — | 1.15% | $6.04B | — | — |
| 2026-05-22 | $42.11 | $43.05 | $42.03 | $42.67 | 1,637,300 | — | 1.16% | $6.04B | — | — |
| 2026-05-21 | $41.76 | $42.26 | $41.38 | $42.13 | 1,739,500 | — | 1.23% | $5.96B | — | — |
| 2026-05-20 | $42.52 | $42.95 | $41.71 | $41.88 | 1,426,500 | — | 1.01% | $5.93B | — | — |
| 2026-05-19 | $42.23 | $42.58 | $41.96 | $42.38 | 1,873,200 | — | 1.32% | $6.00B | — | — |
| 2026-05-18 | $43.17 | $43.50 | $42.10 | $42.29 | 1,895,700 | — | 1.34% | $5.98B | — | — |
| 2026-05-15 | $43.49 | $43.79 | $41.78 | $42.98 | 3,367,400 | — | 2.38% | $6.08B | — | — |
| 2026-05-14 | $43.25 | $45.58 | $41.35 | $44.43 | 4,770,400 | — | 3.37% | $6.29B | — | — |
| 2026-05-13 | $40.34 | $41.21 | $39.99 | $40.44 | 2,345,900 | — | 1.66% | $5.72B | — | — |
| 2026-05-12 | $41.00 | $41.22 | $39.46 | $40.37 | 3,354,200 | — | 2.37% | $5.71B | — | — |
| 2026-05-11 | $41.33 | $41.79 | $41.22 | $41.31 | 1,325,800 | — | 0.94% | $5.84B | — | — |
| 2026-05-08 | $40.50 | $41.18 | $40.12 | $41.14 | 1,253,100 | — | 0.89% | $5.82B | — | — |
| 2026-05-07 | $40.89 | $41.30 | $40.68 | $40.78 | 1,582,500 | — | 1.12% | $5.77B | — | — |
| 2026-05-06 | $41.28 | $41.49 | $40.71 | $40.97 | 1,175,000 | — | 0.83% | $5.80B | — | — |
| 2026-05-05 | $41.65 | $41.74 | $40.74 | $40.88 | 1,391,900 | — | 0.98% | $5.78B | — | — |
| 2026-05-04 | $40.75 | $41.76 | $40.61 | $41.40 | 1,387,500 | — | 0.98% | $5.86B | — | — |
| 2026-05-01 | $40.60 | $43.06 | $40.24 | $40.83 | 1,954,700 | — | 1.38% | $5.78B | — | — |
| 2026-04-30 | $39.35 | $40.59 | $39.35 | $40.19 | 1,725,000 | — | 1.22% | $5.69B | — | — |
| 2026-04-29 | $39.00 | $40.06 | $38.76 | $39.63 | 1,758,700 | — | 1.24% | $5.61B | — | — |
| 2026-04-28 | $40.15 | $40.19 | $39.15 | $39.16 | 1,525,400 | — | 1.08% | $5.54B | — | — |
| 2026-04-27 | $38.74 | $39.90 | $38.72 | $39.90 | 1,874,100 | — | 1.32% | $5.65B | — | — |
| 2026-04-24 | $40.36 | $40.68 | $38.36 | $38.74 | 2,275,200 | — | 1.61% | $5.48B | — | — |
| 2026-04-23 | $40.21 | $41.00 | $39.96 | $40.49 | 1,890,700 | — | 1.34% | $5.73B | — | — |
| 2026-04-22 | $40.20 | $40.35 | $39.63 | $40.32 | 2,373,000 | — | 1.68% | $5.70B | — | — |
| 2026-04-21 | $40.80 | $41.03 | $39.61 | $39.65 | 1,953,000 | — | 1.38% | $5.61B | — | — |
| 2026-04-20 | $40.70 | $41.69 | $40.44 | $40.80 | 1,948,500 | — | 1.38% | $5.77B | — | — |
| 2026-04-17 | $41.13 | $41.19 | $40.15 | $40.86 | 2,708,400 | — | 1.91% | $5.78B | — | — |
| 2026-04-16 | $41.48 | $42.17 | $40.91 | $41.08 | 2,150,300 | — | 1.52% | $5.81B | — | — |
| 2026-04-15 | $41.18 | $41.56 | $40.76 | $41.00 | 2,659,200 | — | 1.88% | $5.80B | — | — |
| 2026-04-14 | $40.99 | $41.37 | $40.41 | $41.15 | 2,505,600 | — | 1.77% | $5.82B | — | — |
| 2026-04-13 | $39.73 | $40.85 | $39.59 | $40.83 | 1,789,700 | — | 1.26% | $5.78B | — | — |
| 2026-04-10 | $38.81 | $40.06 | $38.49 | $39.75 | 1,655,200 | — | 1.17% | $5.62B | — | — |
| 2026-04-09 | $38.25 | $38.88 | $37.55 | $38.80 | 1,518,100 | — | 1.07% | $5.49B | — | — |
| 2026-04-08 | $38.46 | $38.90 | $38.40 | $38.53 | 1,972,100 | — | 1.39% | $5.45B | — | — |
| 2026-04-07 | $37.83 | $38.24 | $37.41 | $38.03 | 1,244,300 | — | 0.88% | $5.38B | — | — |
| 2026-04-06 | $37.58 | $38.23 | $37.41 | $37.83 | 1,653,800 | — | 1.17% | $5.35B | — | — |
| 2026-04-02 | $37.03 | $37.56 | $36.60 | $37.43 | 1,987,700 | — | 1.40% | $5.30B | — | — |
| 2026-04-01 | $36.62 | $37.45 | $36.34 | $37.18 | 1,929,400 | — | 1.36% | $5.26B | $0.38 | — |
| 2026-03-31 | $35.98 | $37.61 | $35.95 | $37.02 | 2,696,400 | — | 1.91% | $5.24B | — | — |
| 2026-03-30 | $35.10 | $36.19 | $35.10 | $35.59 | 2,177,700 | — | 1.51% | $5.14B | — | — |
| 2026-03-27 | $35.80 | $36.20 | $35.11 | $35.43 | 1,890,400 | — | 1.31% | $5.12B | — | — |
| 2026-03-26 | $36.25 | $36.48 | $35.83 | $36.09 | 1,757,000 | — | 1.22% | $5.22B | — | — |
| 2026-03-25 | $36.26 | $36.78 | $35.89 | $36.50 | 1,709,800 | — | 1.18% | $5.28B | — | — |
| 2026-03-24 | $36.50 | $37.25 | $35.47 | $36.13 | 2,166,900 | — | 1.50% | $5.22B | — | — |
| 2026-03-23 | $35.63 | $37.33 | $35.52 | $36.60 | 2,489,600 | — | 1.72% | $5.29B | — | — |
| 2026-03-20 | $35.71 | $36.29 | $34.99 | $36.23 | 6,009,200 | — | 4.16% | $5.24B | — | — |
| 2026-03-19 | $35.59 | $35.79 | $34.62 | $35.50 | 2,460,900 | — | 1.70% | $5.13B | — | — |
| 2026-03-18 | $37.75 | $37.79 | $35.10 | $35.91 | 3,170,200 | — | 2.19% | $5.19B | — | — |
| 2026-03-17 | $38.07 | $38.38 | $37.58 | $37.95 | 1,714,300 | — | 1.19% | $5.48B | — | — |
| 2026-03-16 | $37.54 | $38.29 | $37.00 | $38.00 | 2,550,600 | — | 1.76% | $5.49B | — | — |
| 2026-03-13 | $37.50 | $38.26 | $37.19 | $37.55 | 2,910,000 | — | 2.01% | $5.43B | — | — |
| 2026-03-12 | $38.26 | $38.65 | $37.46 | $37.65 | 3,003,700 | — | 2.08% | $5.44B | — | — |
| 2026-03-11 | $36.83 | $38.39 | $36.83 | $38.30 | 3,504,300 | — | 2.42% | $5.54B | — | — |
| 2026-03-10 | $37.28 | $37.51 | $36.42 | $36.61 | 2,488,500 | — | 1.72% | $5.29B | — | — |
| 2026-03-09 | $36.12 | $37.02 | $35.90 | $36.54 | 2,423,000 | — | 1.68% | $5.28B | — | — |
| 2026-03-06 | $36.53 | $37.56 | $36.25 | $36.70 | 2,715,500 | — | 1.88% | $5.30B | — | — |
| 2026-03-05 | $36.02 | $36.95 | $35.79 | $36.77 | 3,721,500 | — | 2.57% | $5.31B | — | — |
| 2026-03-04 | $34.28 | $36.26 | $34.28 | $36.02 | 5,282,300 | — | 3.65% | $5.21B | — | — |
| 2026-03-03 | $33.14 | $34.55 | $32.10 | $34.01 | 5,347,000 | — | 3.70% | $4.92B | — | — |
| 2026-03-02 | $32.64 | $33.46 | $32.20 | $32.74 | 2,165,800 | — | 1.50% | $4.73B | — | — |
| 2026-02-27 | $32.58 | $34.13 | $32.35 | $33.32 | 5,151,100 | — | 3.56% | $4.82B | — | — |
| 2026-02-26 | $30.86 | $32.51 | $30.81 | $32.48 | 3,116,100 | — | 2.16% | $4.69B | — | — |
| 2026-02-25 | $29.85 | $31.23 | $29.80 | $31.00 | 2,448,400 | — | 1.69% | $4.48B | — | — |
| 2026-02-24 | $29.73 | $30.31 | $29.47 | $29.85 | 3,147,000 | — | 2.18% | $4.31B | — | — |
| 2026-02-23 | $29.92 | $29.96 | $29.20 | $29.60 | 1,911,400 | — | 1.32% | $4.28B | — | — |
| 2026-02-20 | $30.06 | $30.47 | $29.75 | $30.03 | 2,068,000 | — | 1.43% | $4.34B | — | — |
| 2026-02-19 | $30.00 | $30.45 | $29.53 | $30.04 | 2,662,400 | — | 1.84% | $4.34B | — | — |
| 2026-02-18 | $29.88 | $30.74 | $29.51 | $29.57 | 2,647,400 | — | 1.83% | $4.27B | — | — |
| 2026-02-17 | $28.85 | $29.91 | $28.57 | $29.80 | 2,737,100 | — | 1.89% | $4.31B | — | — |
| 2026-02-13 | $27.50 | $28.73 | $27.37 | $28.72 | 2,065,600 | — | 1.43% | $4.15B | — | — |
| 2026-02-12 | $28.55 | $28.84 | $27.17 | $27.42 | 2,328,100 | — | 1.61% | $3.96B | — | — |
| 2026-02-11 | $28.87 | $29.10 | $28.08 | $28.40 | 2,333,100 | — | 1.61% | $4.10B | — | — |
| 2026-02-10 | $28.76 | $29.42 | $28.54 | $28.87 | 3,256,600 | — | 2.25% | $4.17B | — | — |
| 2026-02-09 | $29.39 | $29.97 | $28.61 | $28.67 | 2,181,300 | — | 1.51% | $4.14B | — | — |
| 2026-02-06 | $29.50 | $30.28 | $28.74 | $29.46 | 4,119,600 | — | 2.85% | $4.26B | — | — |
| 2026-02-05 | $30.43 | $30.46 | $29.24 | $29.78 | 3,144,400 | — | 2.18% | $4.30B | — | — |
| 2026-02-04 | $30.88 | $31.36 | $30.30 | $30.45 | 3,527,500 | — | 2.44% | $4.40B | — | — |
| 2026-02-03 | $32.36 | $32.63 | $30.70 | $30.92 | 3,007,600 | — | 2.08% | $4.47B | — | — |
| 2026-02-02 | $32.37 | $33.03 | $31.82 | $32.49 | 2,486,500 | — | 1.72% | $4.70B | — | — |
| 2026-01-30 | $32.45 | $32.64 | $31.88 | $32.58 | 2,561,700 | — | 1.77% | $4.71B | — | — |
| 2026-01-29 | $33.59 | $33.78 | $32.02 | $32.85 | 3,612,800 | — | 2.50% | $4.75B | — | — |
| 2026-01-28 | $33.19 | $34.58 | $33.18 | $33.59 | 3,515,700 | — | 2.43% | $4.85B | — | — |
| 2026-01-27 | $32.55 | $33.58 | $32.00 | $33.17 | 3,806,900 | — | 2.63% | $4.79B | — | — |
| 2026-01-26 | $31.78 | $33.17 | $31.62 | $33.09 | 4,229,500 | — | 2.93% | $4.78B | — | — |
| 2026-01-23 | $31.32 | $31.89 | $30.63 | $31.62 | 4,739,100 | — | 3.28% | $4.57B | — | — |
| 2026-01-22 | $32.74 | $33.25 | $31.17 | $31.38 | 3,840,100 | — | 2.66% | $4.54B | — | — |
| 2026-01-21 | $32.62 | $33.08 | $31.91 | $32.44 | 3,100,700 | — | 2.15% | $4.69B | — | — |
| 2026-01-20 | $33.10 | $33.39 | $32.31 | $32.65 | 3,155,600 | — | 2.18% | $4.72B | — | — |
| 2026-01-16 | $32.65 | $33.78 | $32.36 | $33.04 | 4,118,400 | — | 2.85% | $4.78B | — | — |
| 2026-01-15 | $33.05 | $33.28 | $32.19 | $32.65 | 4,644,100 | — | 3.21% | $4.72B | — | — |
| 2026-01-14 | $33.68 | $34.40 | $33.00 | $33.00 | 5,063,000 | — | 3.50% | $4.77B | — | — |
| 2026-01-13 | $33.97 | $35.31 | $33.62 | $34.11 | 17,391,200 | — | 12.03% | $4.93B | — | — |
| 2026-01-12 | $34.02 | $35.00 | $33.56 | $33.91 | 4,959,300 | — | 3.43% | $4.90B | — | — |
| 2026-01-09 | $33.90 | $35.16 | $33.34 | $34.41 | 7,665,700 | — | 5.30% | $4.97B | — | — |
| 2026-01-08 | $33.25 | $35.00 | $31.92 | $33.69 | 18,611,600 | — | 12.88% | $4.87B | — | — |
| 2026-01-07 | $35.46 | $35.84 | $33.00 | $33.27 | 16,966,000 | — | 11.74% | $4.81B | — | — |
| 2026-01-06 | $40.41 | $40.50 | $35.93 | $36.26 | 14,571,700 | — | 10.08% | $5.24B | — | — |
| 2026-01-05 | $45.17 | $45.65 | $39.28 | $40.57 | 41,362,800 | — | 28.62% | $5.86B | — | — |
Close is split-adjusted to current shares. It is not dividend-adjusted: dividends are listed separately, so total return is (end price + dividends received − start price) ÷ start price, checkable by hand. Volume is as-traded.
Momentum: MACD and RSI
Top: MACD (navy) and its signal line (gold); bars show the gap between them, teal when MACD is above.
Bottom: RSI over 14 days; above 70 is usually read as overbought and below 30 as oversold.
The lines start late because MACD needs 26 trading days of prices and RSI 14 before the first value.
The colored strip under the charts shows the state label day by day; hover for the state and the reason.
Both measure momentum in the price and say nothing about value. Hover for each day's arithmetic.
Source: closing prices from this site's daily price archive (Yahoo Finance), not adjusted for dividends. Data through Nov 14, 2026.
How these are calculated
Short Selling
Bars: shares sold short each day in trades reported to FINRA (off-exchange
trades, roughly half of all volume).
Line: the short share of that volume, averaged over 20 sessions.
Gold points: short interest, the shares sold short and not yet bought back,
reported twice a month, also shown as a percentage of the free float and of
shares outstanding.
Daily short volume includes market makers' routine hedging, so a change in the
share is more informative than its level. Hover for each day's figures.
Sources: FINRA; float from this site's daily share records; shares outstanding
from the company's latest quarterly filing. Data through Nov 13, 2026.
Index-Fund Holdings
Daily positions of State Street's SPDR index funds, by the fund's file date.
These are the index funds whose daily holdings can be collected; iShares and
Vanguard funds, often larger holders, publish holdings that cannot be
collected automatically and appear in the written analysis from their
quarterly filings.
Collection began on October 11, 2026. A fund that drops the stock shows as an
exit.
Source: State Street Global Advisors. Data through
Nov 12, 2026.
Update — November 3, 2026: third-quarter results — HOLD → ACCUMULATE, target $36 → $40
Rated at the November 3, 2026 close of $32.69. The results were released before the open that day and the 10-Q after the close. Sources: the third-quarter results release, the supplemental financial information and the third-quarter 10-Q, all of November 3, 2026. The analyses below are left as published; this section tests the results against the October 13, 2026 update, reruns the three scenarios on the reported balances and corrects the treatment of Full Swing.
The one-line version
The third quarter met one of the two tests the October 13, 2026 update set for raising the best case and missed the other. Distribution revenue fell 5.8%, under the 6% the page named, and Platforms grew 17.4% excluding the business sold and the one bought, but programming costs fell only 1.0% while linear revenue fell 6.3%, because of new sports rights. The revenue and EBITDA outlook was reaffirmed, and free cash flow, $1,210 million in nine months, is now expected to beat the $1.0–1.2 billion range. The weights stay at 15 / 60 / 25. The target rises from $36 to $40, mostly because of a correction. The October 7, 2026 valuation deducted the $536 million paid for Full Swing but left the business out; carried at cost it adds $3.92 a share to every case. The reported balances and the quarter add about $0.30 to the weighted value. At $32.69 the expected return is 23% and the gain to loss 4.4 to 1, the ACCUMULATE band; BUY needs a price below about $32.23.
Rating: BUY below $32.23 · ACCUMULATE $32.23–36.62 · HOLD $36.62–44.76 · TRIM $44.76–53.71 · SELL above $53.71 · Target $40
The quarter against the tests
| Test (October 13, 2026) | Third quarter 2026 | Verdict |
|---|---|---|
| Distribution revenue declining less than 6% would raise the best case | −5.8% ($935 million), after −7.3% in the first quarter and −6.2% in the second; −6.4% for the nine months. All the year’s planned carriage renewals are done | Met for the quarter; not yet for the year |
| Programming costs falling as fast as linear revenue would raise the best case | Programming and production −1.0% ($736 million) against linear revenue (distribution, advertising and licensing) −6.3%. Licensed programming, including sports, rose 7.5% to $558 million; owned programming fell 21% to $178 million | Not met |
| Advertising (base case −6% a year, plus 2 points in an election year) | −5.3% ($373 million), which the company attributes to the Ryder Cup a year earlier; −3.6% for the nine months | In line with the base case |
| Platforms (base case +8%, best case +12%) | +9.6% reported; +17.4% excluding SportsEngine (sold in the second quarter) and Full Swing (bought August 3, 2026), led by Fandango ticketing; +12.7% for the nine months on the same basis | Ahead of the best case |
| Short interest: a fall after the results would argue for a lighter worst case | 5.84 million shares at October 15, 2026, about 4.3% of the shares and 3.2 days of volume, against 5.81 million at September 30, 2026. The first figure after the results is published in late November 2026 | Not yet testable |
| Outlook | Revenue $6.20–6.45 billion and adjusted EBITDA $1.90–2.05 billion reaffirmed; free cash flow now expected to exceed $1.0–1.2 billion | Passes |
- Adjusted EBITDA was $353 million, down 7.4% from the $381 million the company estimates the business would have earned as a standalone company a year earlier. For the nine months it is $1,681 million, against $1,658 million.
- The stock rose 1.1% on the day, to $32.69 on 4.2 million shares, 2.3 times its 20-day average, while SPY rose 0.3%. The three earlier results days moved it up 3.9%, 9.9% and 6.8%.
What the outlook implies for the fourth quarter
The reaffirmed outlook leaves a wide range for the last three months of 2026:
| Fourth quarter 2026 | Low end | Midpoint | High end | Fourth quarter 2025 |
|---|---|---|---|---|
| Revenue | $1,275M | $1,400M | $1,525M | $1,610M ($1,576M without SportsEngine) |
| Adjusted EBITDA | $219M | $294M | $369M | $521M on the standalone basis |
- The nine months point to the top of the range. Revenue fell 3.5% in the third quarter excluding the two deals; the same decline in the fourth quarter gives about $1,550 million with Full Swing, above the high end.
- The cost of new sports rights falls mostly in the third and fourth quarters, the release says, which is the likeliest reason for the cautious EBITDA range.
- The valuation now uses the top of the EBITDA range for 2026, $2,050 million. The October 7, 2026 build had $2,072 million in the base case, above the outlook, because the extra revenue it forecast fell through to EBITDA. At the midpoint, $1,975 million, the target would be about $39.45 (an estimate).
Cash, buybacks and the debt
- Free cash flow was $302 million in the quarter and $1,210 million in nine months. About $60 million of the nine months came from working capital that tends to reverse (receivables used $392 million; content, payables and other liabilities supplied $452 million), so the valuation sets 2026 at about $1,175 million: the nine months, about $25 million in the fourth quarter, less that $60 million (estimates).
- Net debt was $1.92 billion at September 30, 2026: debt at face value of $2,971 million (the $1.0 billion of 7.25% notes due 2031, $988 million of Term Loan A and $983 million of Term Loan B) less cash of $1,051 million. The October 7, 2026 update estimated $2.05 billion. Net debt is about 0.94 times 2026 adjusted EBITDA (an estimate); the one covenant, first-lien net leverage of at most 3.5 times, applies from this quarter. The term loans began amortizing on September 30, 2026: $30 million in the rest of 2026 and about $120 million a year after.
- Shares were 136.6 million at September 30, 2026 (136.25 million Class A and 0.38 million Class B), against the 136.2 million estimated. Versant bought 7.6 million shares for $300 million in the nine months, including 2.57 million at an average of $38.98 under the third-quarter accelerated buyback; $700 million of the $1.0 billion authorization remains.
- A further $100 million accelerated buyback starts November 4, 2026. At $32.69 it would retire about 3.1 million shares, about 2.2% of the total. The dividend of $0.375 a quarter is unchanged (declared November 3, 2026, payable January 25, 2027).
Repaying the debt by its January 2031 maturity, on the reported balances:
| Base case | Worst case (with restructuring) | |
|---|---|---|
| Free cash flow, October 2026–2030 | $3.40B | $2.09B |
| Dividends at $1.50 a share, October 2026–2030 | − ~$0.87B | − ~$0.87B |
| Cash at September 30, 2026 (10-Q) | + $1.05B | + $1.05B |
| Available to repay debt | = ~$3.58B | = ~$2.27B |
| Debt outstanding at face value | − $2.97B | − $2.97B |
| Cash left after repaying all debt | = ~$0.61B | = − ~$0.70B (short) |
The October 13, 2026 table showed ~$0.57 billion left in the base case and ~$0.87 billion short in the worst. Buybacks at $400 million a year would leave the base case about $1.1 billion short as well, to be refinanced.
The scenarios and the asymmetry after the third quarter
The October 7, 2026 drivers are unchanged. Five inputs are updated, and the bridge shows what each does:
| Step (best guess 15 / 60 / 25) | Best | Base | Worst | Weighted |
|---|---|---|---|---|
| October 13, 2026 | $78.65 | $32.98 | $17.96 | $36.07 |
| Net debt $1.92 billion and 136.6 million shares at September 30, 2026 | + $0.72 | + $0.86 | + $0.90 | + $0.85 |
| Fourth-quarter free cash flow ~$25 million (the nine months are in the cash balance) | − $0.54 | − $0.54 | − $0.54 | − $0.54 |
| 2026 revenue: nine months reported, fourth quarter forecast | − $0.90 | + $0.39 | + $1.39 | + $0.45 |
| 2026 adjusted EBITDA $2,050 million and free cash flow ~$1,175 million | − $1.33 | − $0.52 | + $0.20 | − $0.46 |
| Full Swing at its $536 million cost (correction, below) | + $3.92 | + $3.92 | + $3.92 | + $3.92 |
| November 3, 2026 | $80.53 | $37.08 | $23.83 | $40.28 |
| vs $32.69 | +146% | +13% | −27% | +23% |
- The 2026 step lowers the base case. The model carries part of each year’s cash costs outside EBITDA (separation, timing) into later years: half in the base case and all of it in the worst. At 2026 EBITDA of $2,050 million and free cash flow of ~$1,175 million those costs are about $171 million, against $191 million in the October build.
- Platforms ahead of plan is not yet in the drivers. The base case keeps growth of 8% a year from 2027; at the best case’s 12% it is worth $2.11 a share more.
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $44.63 | +37% | 6.4 to 1 |
| Best guess: 15 / 60 / 25 (unchanged) | $40.28 | +23% | 4.4 to 1 |
| Stress: 10 / 40 / 50 | $34.80 | +6% | 1.5 to 1 |
| What the price implies: 2 / 60 / 38 | $32.69 | 0% | 1.0 to 1 |
The weights are a judgement. All values are estimates from the model.
- The weights are unchanged. One quarter of distribution under 6% meets a test the page set, but the nine months are at −6.4% and programming costs moved against the best case, which needs both. A second quarter of distribution under 6%, with programming costs falling at least 0.8 times as fast as linear revenue, would raise the best case’s weight.
- The price implies more weight on the worst case than the evidence supports. Holding the base case at 60%, the price is matched by 2% on the best case and 38% on the worst; on single assumptions it implies the base case at a discount rate of about 11.75% instead of 10%, or free cash flow declining about 9% a year after 2030 instead of 6%.
- Even the stress weighting is above the price, by about 6%.
| Measure | At $32.69 | Formula |
|---|---|---|
| Expected return (header chip) | +23% | (15% × $80.53 + 60% × $37.08 + 25% × $23.83) ÷ $32.69 − 1 = ($12.08 + $22.25 + $5.96) ÷ $32.69 − 1 |
| Gain to loss (header chip) | 4.4 to 1 | (15% × $47.84 + 60% × $4.39) ÷ (25% × $8.86) = ($7.18 + $2.63) ÷ $2.21 |
| Expected base gain ÷ expected worst loss | 1.2 to 1 | $2.63 ÷ $2.21 |
| Best gain ÷ worst loss | 5.4 to 1 | $47.84 ÷ $8.86 |
| Base gain ÷ worst loss | 0.5 to 1 | $4.39 ÷ $8.86 |
| Price-implied best weight, base at 60% | (price − 60% × base − 40% × worst) ÷ (best − worst) | ($32.69 − $22.25 − $9.53) ÷ $56.70 = 2% |
Both header chips take the color of the rating band the price is in: BUY green (an expected return of +25% or more with gain to loss of 3 to 1 or better), ACCUMULATE blue (+10% to +25%), HOLD gold (−10% to +10%), TRIM orange (−25% to −10%) and SELL red (below −25%). On the best guess they are green below $32.23, blue up to $36.62, gold up to $44.76, orange up to $53.71 and red above. At $32.69 both are blue, the ACCUMULATE band.
| Change to the base case, one at a time | Value | Change |
|---|---|---|
| Subscribers falling 10% a year | $31.86 | −$5.22 |
| A lost carriage agreement in 2028 (distribution revenue −7%) | $32.16 | −$4.92 |
| Programming costs falling 0.6 times as fast as linear revenue | $33.60 | −$3.48 |
| Decline after 2030 of 8% a year | $34.04 | −$3.04 |
| Advertising trend −9% a year | $34.05 | −$3.03 |
| Discount rate 11% | $34.46 | −$2.62 |
| Platforms growing 3% a year | $34.73 | −$2.35 |
| Discount rate 9.5% | $38.51 | +$1.43 |
| Platforms growing 12% a year | $39.19 | +$2.11 |
| Advertising trend −3% a year | $40.38 | +$3.30 |
| Programming costs falling one for one with linear revenue | $40.44 | +$3.36 |
| Decline after 2030 of 4% a year | $40.99 | +$3.91 |
| Subscribers falling 6% a year | $42.63 | +$5.55 |
| Decline after 2030 of 2% a year | $46.19 | +$9.11 |
Revenue, adjusted EBITDA and free cash flow by case, millions of dollars (Full Swing excluded):
| 2026E | 2027E | 2028E | 2029E | 2030E | |
|---|---|---|---|---|---|
| Best: revenue | 6,482 | 6,277 | 6,249 | 6,180 | 6,188 |
| Best: adjusted EBITDA | 2,098 | 2,006 | 1,990 | 1,950 | 1,950 |
| Best: free cash flow | 1,210 | 1,321 | 1,310 | 1,256 | 1,256 |
| Base: revenue | 6,431 | 6,033 | 5,823 | 5,580 | 5,415 |
| Base: adjusted EBITDA | 2,050 | 1,766 | 1,593 | 1,399 | 1,253 |
| Base: free cash flow | 1,175 | 1,050 | 922 | 755 | 647 |
| Worst: revenue | 6,366 | 5,647 | 5,027 | 4,663 | 4,377 |
| Worst: adjusted EBITDA | 1,990 | 1,410 | 1,323 | 1,195 | 1,106 |
| Worst: free cash flow | 1,131 | 690 | 426 | 508 | 442 |
Notes on earlier sections
- Full Swing was left out of the valuation while its cost was deducted. The October 7, 2026 update said Full Swing was “excluded throughout” and carried it at cost only in the sum of the parts. Its purchase price (about $530 million, $536 million in the 10-Q) was paid in cash and so reduced the cash in the net-debt figure each case deducts, but the business’s own cash flow was never added. Each case was therefore about $3.92 a share too low. The cases above carry Full Swing at its cost, since its profit is not disclosed; its revenue was $24 million in its first two months. A data correction (a method error), not a change in the business. Without the correction the target would be $36.36, still in the ACCUMULATE band.
- The September 30, 2026 estimates against the 10-Q. Net debt was $1.92 billion, not the estimated $2.05 billion (cash was higher at $1,051 million, and the debt is $2,971 million at face after the first amortization payment), and shares were 136.6 million, not 136.2 million. Together they add about $0.85 to the weighted value.
- 2026 adjusted EBITDA in the October 7, 2026 build was above the outlook. The base case had $2,072 million against the $1.90–2.05 billion range; it now uses $2,050 million, the top of the range.
What it means for the rating
HOLD → ACCUMULATE, target $36 → $40. The target is the best-guess value, $40.28. The rating follows the site’s rating scale (see the Methodology page): ACCUMULATE at an expected return of 10% to 25%, BUY at 25% or more with gain to loss of at least 3 to 1. At $32.69 the expected return is 23% and the gain to loss 4.4 to 1. Two things moved the rating. On the scale adopted on October 29, 2026, the October 13, 2026 figures (+18% at $30.60) were already in the ACCUMULATE band; and the Full Swing correction raises the target by $3.92.
It is ACCUMULATE rather than BUY because the price is about $0.46 above the BUY line and the expected gain still comes mostly from the best case, $7.18 of the $9.81, which needs programming costs to fall with revenue, and this quarter they did not. It is not HOLD because the base case is now 13% above the price, the stress weighting is above the price, and the quarter showed slower distribution losses, Platforms growth above plan and more cash than guided.
| Action | Level | Reason |
|---|---|---|
| Buy | Below about $32.23 | Expected return 25% or more on the best guess; gain to loss is 4.8 to 1 there |
| Accumulate | $32.23–36.62 | Expected return 10–25% |
| Hold | $36.62–44.76 | Expected return −10% to +10%, around the $40 target |
| Trim | $44.76–53.71 | Expected return −10% to −25%; the base case is $37.08 |
| Sell | Above about $53.71 | Expected return below −25% |
| Move the bands down | Distribution back above a 7% decline, a lost carriage agreement, programming costs rising while linear revenue falls, or a 2027 outlook that cuts the dividend or buybacks | The worst case’s weight rises; a lost agreement takes about $5 off the base case |
| Move the bands up | A second quarter of distribution under 6% with programming costs falling at least 0.8 times as fast as linear revenue, or short interest falling | The best case’s weight rises |
What the fourth-quarter results (about early March 2027, date not yet announced) must show:
| Item | Why it matters | The base case needs |
|---|---|---|
| Distribution revenue | −5.8% in the third quarter; the best case needs about −3% a year | Under 6% again |
| Programming against linear revenue | −1.0% against −6.3% in the third quarter, on new sports rights | Falling about 0.8 times as fast |
| Fourth-quarter adjusted EBITDA | The outlook implies $219–369 million; the valuation uses the top | About $369 million |
| 2026 free cash flow | Expected to exceed $1.2 billion; the valuation uses ~$1,175 million after working capital | At least $1.2 billion |
| Platforms growth without the two deals | +17.4% in the third quarter; the base case uses 8% from 2027 | Above 8% |
| 2027 outlook, dividend and buybacks | The first full-year outlook after the spin; $700 million of buybacks left | Dividend held; buybacks no larger than free cash flow allows |
| Short interest | 4.3% of the shares at October 15, 2026 | Falling |
Update — October 13, 2026: the scenarios and the asymmetry — HOLD, target $36
Written against the October 12, 2026 close of $30.60. Source: the three scenarios of the October 7, 2026 update, rerun unchanged at the same 10% discount rate, with net debt of about $2.05 billion and 136.2 million shares (estimates for September 30, 2026). The analyses below are left as published; this section adds the asymmetry measures, sets the scenario weights on the evidence, adds short interest and volatility, and corrects the repayment table of October 12, 2026. The rating is unchanged; the target moves from $41 to $36 because the weights change.
The one-line version
On the weights the evidence supports, 15% best, 60% base and 25% worst, Versant is worth about $36, an expected return of 18% with $2.70 of probability-weighted gain for each $1 of loss. The October 7, 2026 target of $41 used an even 25% on each tail; the best case needs four things to beat Versant’s record at once, and none is doing so today. If the worst case were the most likely outcome, the shares would be worth about what they trade at. The price implies roughly a 6% chance of the best case and 34% of the worst. The October 12, 2026 repayment table counted about $0.9 billion of 2026 cash twice: corrected, the base case leaves ~$0.57 billion after repaying all the debt, and the worst case is ~$0.87 billion short, which would have to be refinanced or found by cutting the dividend.
The scenarios and the asymmetry
The three cases are the ones built line by line on October 7, 2026, rerun without change. Each discounts free cash flow before interest at 10% and deducts the same net debt, so the differences come from the business alone.
| Best | Base | Worst | |
|---|---|---|---|
| What has to happen | Four things better than the recent record at once | The recent record continues | Several things go wrong together, then a restructuring |
| Subscribers, a year | −6% | −8% | −10%, plus a lost carriage agreement in 2028 |
| Advertising trend, a year | −3% | −6% | −9%, plus a recession in 2027 |
| Programming costs against linear revenue | Fall one for one | Fall 0.8 times as fast | Fall 0.6 times as fast until a 2028 restructuring |
| Platforms growth, a year | 12% | 8% | 3% |
| Decline in free cash flow after 2030 | 2% a year | 6% a year | 6% a year |
| Value per share | $78.65 | $32.98 | $17.96 |
| vs $30.60 | +157% | +8% | −41% |
Three weightings, and what the price implies. Every profile now shows the cases under three sets of weights. The standard set, 25 / 50 / 25, and the stress set, 10 / 40 / 50, are the same for every company, so companies can be compared and the downside read on a common basis. The best guess is set for each company from the evidence and can sit above or below the standard. It drives the target, the rating and the two chips at the top of the page.
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $40.64 | +33% | 4.2 to 1 |
| Best guess: 15 / 60 / 25 | $36.08 | +18% | 2.7 to 1 |
| Stress: 10 / 40 / 50 | $30.04 | −2% | 0.9 to 1 |
| What the price implies: 6 / 60 / 34 | $30.60 | 0% | 1.0 to 1 |
The weights are a judgement. All values are estimates from the model.
Why the best guess sits below the standard. The best case needs subscriber losses of 6% a year against 8% in each of the last two years, advertising declining 3% a year against 7–9%, programming costs falling one for one with linear revenue against about 80% in 2023–25, and Platforms growing 12% a year against 6%. All four have to happen together, and the first half of 2026 showed none of them, so it gets 15%. The worst case keeps 25%: the decline in homes reached is running at 8–9% a year, and the 2028 carriage renewals are a real risk of a lost agreement. The base case, the recent record continued, takes the remaining 60%. Evidence that would raise the best case: programming costs falling as fast as linear revenue, or distribution revenue declining less than 6%, in the third-quarter results.
What the price implies. Holding the base case at its 60% weight, the price is matched by the weighting that solves
best weight × $78.65 + 60% × $32.98 + (40% − best weight) × $17.96 = $30.60
which gives a best-case weight of ($30.60 − 60% × $32.98 − 40% × $17.96) ÷ ($78.65 − $17.96) = 6%, and so 34% on the worst case. The market is pricing the worst case as more likely than the evidence suggests, and the best case as less likely. The same reverse calculation on single assumptions gives the base case with free cash flow declining about 7.5% a year after 2030 instead of 6%, or a discount rate of about 10.9% instead of 10%.
The asymmetry on the best guess:
| Measure | At $30.60 | What it means |
|---|---|---|
| Expected return (header chip) | +18% | The probability-weighted value, $36.08, against the price |
| Gain to loss (header chip) | 2.7 to 1 | +$8.64 of probability-weighted gain against −$3.16 of loss; the best case supplies $7.21 of the $8.64 |
| Expected base-case gain ÷ expected worst-case loss | 0.45 to 1 | +$1.43 against −$3.16: without the best case the likely outcome does not pay for the bad one |
| Best-case gain ÷ worst-case loss | 3.8 to 1 | +$48.05 against −$12.64 |
| Base-case gain ÷ worst-case loss | 0.2 to 1 | +$2.38 against −$12.64 |
How the measures are calculated. Gain = case value − price; loss = price − case value. Weights are the best guess: 15% best, 60% base, 25% worst.
| Measure | Formula | At $30.60 |
|---|---|---|
| Expected return | (15% × best + 60% × base + 25% × worst) ÷ price − 1 | ($11.80 + $19.79 + $4.49) ÷ $30.60 − 1 = +18% |
| Gain to loss | (15% × best gain + 60% × base gain) ÷ (25% × worst loss) | ($7.21 + $1.43) ÷ $3.16 = 2.7 |
| Expected base ÷ expected worst | (60% × base gain) ÷ (25% × worst loss) | $1.43 ÷ $3.16 = 0.45 |
| Best ÷ worst | best gain ÷ worst loss | $48.05 ÷ $12.64 = 3.8 |
| Base ÷ worst | base gain ÷ worst loss | $2.38 ÷ $12.64 = 0.2 |
| Price-implied best weight | (price − base weight × base − (1 − base weight) × worst) ÷ (best − worst) | ($30.60 − $19.79 − $7.18) ÷ $60.69 = 6% |
The header chips are green at +25% or more and 3 to 1 or better, blue at +10–25% and 2–3 to 1, orange at 0–10% and 1–2 to 1, and red below zero and below 1 to 1. The two turn red together, since expected return is below zero exactly when gain to loss is below 1 to 1. On the best guess, expected return is green below $28.86, blue up to $32.80 and orange up to $36.08; gain to loss is green below $30.04, blue up to $32.45 and orange up to $36.08. Both are red above $36.08.
Even on the best guess, most of the expected gain comes from the best case: the best case’s 15% supplies $7.21 of the $8.64. The base case sits only 8% above the price and the worst case 41% below it.
| Change to the base case, one at a time | Value | Change |
|---|---|---|
| Subscribers falling 10% a year | $27.72 | −$5.26 |
| A lost carriage agreement in 2028 (distribution revenue −7%) | $28.03 | −$4.95 |
| Programming costs falling 0.6 times as fast as linear revenue | $29.53 | −$3.45 |
| Advertising trend −9% a year | $29.91 | −$3.07 |
| Decline after 2030 of 8% a year | $29.92 | −$3.05 |
| Discount rate 11% | $30.34 | −$2.63 |
| Platforms growing 3% a year | $30.65 | −$2.33 |
| Discount rate 9.5% | $34.42 | +$1.44 |
| Platforms growing 12% a year | $35.06 | +$2.09 |
| Programming costs falling one for one with linear revenue | $36.32 | +$3.34 |
| Advertising trend −3% a year | $36.32 | +$3.35 |
| Decline after 2030 of 4% a year | $36.90 | +$3.93 |
| Subscribers falling 6% a year | $38.57 | +$5.59 |
| Decline after 2030 of 2% a year | $42.14 | +$9.16 |
The rate of subscriber loss and the decline after 2030 move the value most. Each subscriber point is worth about $2.70 a share, and a single lost carriage agreement costs about as much as two extra points of subscriber loss. The discount rate matters less here than for a growing company because most of the value arrives in the next five years.
Short interest and volatility
The tables below show how much of the stock is sold short and how much the price moves. They are inputs to the weights above, and the tables update with the nightly data.
| Report | Settled | Short | % float | % outst. | Days to cover |
|---|---|---|---|---|---|
| First after the spin | Jan 15, 2026 | 2.29M | 1.7% | 1.6% | 1.0 |
| Lowest since the spin | Apr 15, 2026 | 1.63M | 1.2% | 1.2% | 1.0 |
| Three months earlier | Jul 15, 2026 | 4.02M | 2.9% | 2.9% | 2.2 |
| Latest | Oct 30, 2026 | 5.93M | 4.3% | 4.3% | 3.5 |
The latest share of float is higher than 19 of the 19 earlier reports since the spin. Short interest in shares, with its share of the float and of shares outstanding. FINRA settlement dates; figures are published about eight business days later. Days to cover is short interest divided by average daily volume, as reported by FINRA. Float and shares outstanding on or before each date, from this site's daily share records and the company's filings.
Short interest has more than doubled since the spin, from 1.7% of the float in January 2026 to 4.2% at September 30, 2026, and days to cover rose from 1.0 to 2.9, after peaking at 4.3 at the end of August 2026. Most of the rise came from July 2026, while the price fell. Nine months after the spin, hedges against Comcast shares should largely have been closed, so the increase more likely reflects positions betting on a decline. At about 4% of the float, the level is moderate; a common rule of thumb puts squeeze risk above about 10% of the float or five days to cover. It supports keeping the worst case at 25% and is too small to justify raising it. A fall in short interest after the third-quarter results would argue for lightening the worst case. The October 15, 2026 figure is published in late October 2026.
| Volatility, annualized | Last 20 sessions | Last 60 sessions | Since the spin |
|---|---|---|---|
| To November 13, 2026 | 32% | 33% | 39% |
At the last 60 sessions' volatility, one standard deviation over a month is about ±10%, or $32.72 to $39.48 from the $35.94 close; about two months in three end inside that range if volatility holds. The median daily move since the spin is 1.3%.
| Results day | Released | Close before | Close after | Move | Times a median day |
|---|---|---|---|---|---|
| March 3, 2026 | Before the open | $32.74 | $34.01 | +3.9% | 3.1× |
| May 14, 2026 | Before the open | $40.44 | $44.43 | +9.9% | 7.8× |
| August 6, 2026 | Before the open | $35.79 | $38.22 | +6.8% | 5.4× |
| November 3, 2026 | Before the open | $32.34 | $32.69 | +1.1% | 0.9× |
Average move on a results day: 5.4% either way, against a median day's 1.3%. The move is measured from the close before the release to the close of the first session after it.
Results days have moved the stock much more than ordinary days, and all three moved it up: +3.9%, +9.9% and +6.8%, an average of 6.8% against a median day’s 1.3%. Volatility has eased from 39% a year since the spin to 27% over the last 20 sessions. On the history, the November 3, 2026 results could move the price by about 7% either way. A fall of that size would take it to about $28.50, below the $28.86 at which both chips are green and close to the $28 accumulate level; a rise of that size would take it to about $32.70, just under the $32.80 at which expected return turns orange. With short interest higher than before the earlier releases, a good result could also bring buying by short sellers closing positions.
Notes on earlier sections
The repayment table of October 12, 2026 counted cash twice. It added free cash flow for the whole of 2026–2030 ($4.56 billion in the base case, $3.04 billion in the worst) to cash of ~$0.95 billion, which it labelled as cash at June 30, 2026. That ~$0.95 billion is the estimate for September 30, 2026, after the Full Swing purchase, and it already contains the free cash flow of the first nine months of 2026 (~$1.07 billion in the base case, ~$1.00 billion in the worst). The table also deducted ~$1.00 billion of dividends, including those already paid. Counting only the cash still to come, as the October 7, 2026 table did:
Base case Worst case (with restructuring) Free cash flow, October 2026–2030 $3.49B $2.04B Dividends at $1.50 a share, October 2026–2030 − ~$0.87B − ~$0.87B Cash at September 30, 2026, after the Full Swing purchase (estimate) + ~$0.95B + ~$0.95B Available to repay debt = ~$3.57B = ~$2.13B Debt outstanding − $3.00B − $3.00B Cash left after repaying all debt = ~$0.57B = − ~$0.87B (short) The October 12, 2026 table showed ~$1.51 billion left in the base case and the worst case about even, and the text said neither case needs a refinancing. Corrected, the base case repays all the debt only if buybacks stop (at $400 million a year it would need ~$1.1 billion refinanced), and the worst case needs ~$0.87 billion refinanced in January 2031 even without buybacks, unless the dividend is cut. The one-line summary’s statement that the worst case repays all the debt without refinancing is corrected in the same way. A refinancing of that size would be small against the worst case’s ~$1.09 billion of EBITDA in 2030, so the lenders remain well covered; the effect falls on what is left for shareholders. A data correction (an arithmetic error), not a change in the business. The covenant room and the interest forecast are unaffected.
What it means for the rating
HOLD, target $41 → $36. The target is the best-guess value, $36.08, in place of the $40.64 from the even 25 / 50 / 25 weights used on October 7, 2026; the cases themselves are unchanged. Both chips read blue at $30.60, and the stress weighting is slightly below the price, so the stock offers a reasonable return with a deep worst case. It stays at HOLD rather than ACCUMULATE because the expected gain still depends mostly on the best case. The action levels: accumulate below $28, where both chips turn green (+29% and 4.2 to 1) and the base case is worth about 18% more; trim above $36, the new target. The third-quarter results in early November 2026 test the drivers at the top of the sensitivity table, distribution revenue and programming costs against linear revenue, and either could move the best-case weight up or down.
Update — October 12, 2026: how the money moves, the debt, and where Versant is
Prices and ratings as of the October 8, 2026 close of $31.77, the price used in the October 9, 2026 update (the stock closed at $30.64 on October 9, 2026). Sources: the 2025 10-K, the second-quarter 2026 10-Q and results, the credit agreements and indenture filed with the Form 10 and the January 5, 2026 8-K, GolfNow’s public course directory, and press reports on Versant’s offices. The analyses below are left as published; this section adds three views the earlier ones lacked. The rating and target are unchanged.
The one-line version
Versant takes in $6.7 billion a year from four sources and spends most of it on sports rights, newsrooms and overheads: of each $100 of revenue in the first half of 2026, about $27 became free cash flow, though the company’s own guidance implies about $17 for the full year as sports costs land in the second half. Its $3.0 billion of debt is secure: on the worst case in the October 7, 2026 scenarios, free cash flow and cash on hand repay all of it by the January 2031 maturity without refinancing, and the leverage covenant would need EBITDA to fall about 72% to bite. The debt matters through its rules on cash: half of the proceeds of selling a network must repay debt at today’s leverage, and the tax agreement with Comcast limits buybacks until January 2028. Physically, Versant is two buildings and a set of leases: it owns the CNBC campus in Englewood Cliffs, leases its New York headquarters, and still uses Comcast’s Golf Channel studios and Washington bureau under the transition agreement. Its customers are spread across the country through pay-TV bundles (59–60 million homes per network, falling 8–9% a year) and GolfNow’s directory of 15,700 US courses.
How the money moves
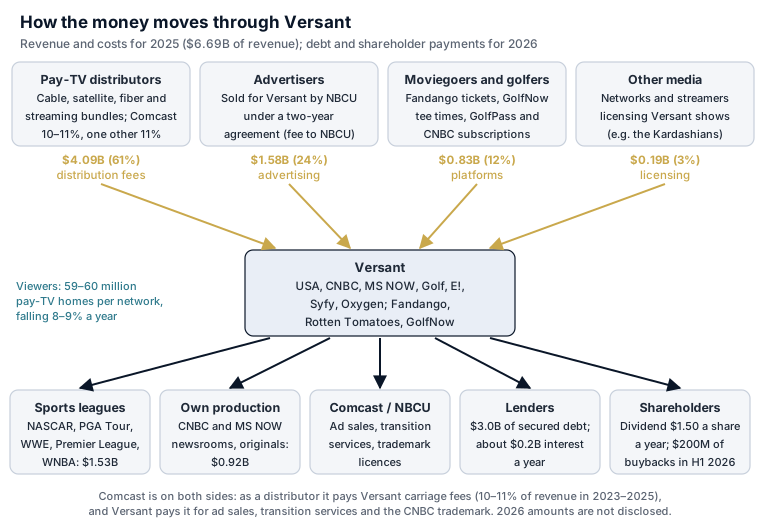
Four kinds of customer pay Versant. Pay-TV distributors pay a monthly fee per subscriber for the networks (61% of 2025 revenue); advertisers buy time, sold for Versant by NBCUniversal under a two-year agreement that charges a fee (24%); moviegoers and golfers pay Fandango and GolfNow per ticket or tee time, and subscribers pay for GolfPass and CNBC’s paid products (12%); and other networks and streamers license Versant’s shows (3%). The distribution fees rest on a base of 59–60 million homes per network that has fallen 8–9% a year since 2022.
Comcast is on both sides. As a distributor through Xfinity it paid 10–11% of Versant’s revenue in 2023–2025, and one other, unnamed customer paid 11% in 2025; the ten largest distributors held 54% of receivables at June 30, 2026. Versant in turn pays Comcast for advertising sales, transition services (technology, finance, human resources, mostly for up to two years) and the CNBC trademark. Since the spin Comcast is no longer a related party, so no 2026 amounts are disclosed in either direction; on the 2025 comparison basis the advertising agreement alone cost about $43 million a quarter.
Where each $100 of revenue went (first half of 2026). The first half flatters the year: a large licensing deal was booked in the first quarter, and sports-rights costs rise in the second half (NASCAR, WNBA, golf). The company’s 2026 guidance implies about $31 of adjusted EBITDA and $17 of free cash flow per $100 for the full year. Source: the second-quarter 2026 results and 10-Q; per-$100 figures are calculations.
Where it goes. Sports and other licensed programming took $19.40 of each $100 in the first half of 2026 and Versant’s own news and original programming $11.80; the rights it holds include the PGA Tour and the Open Championship, NASCAR to 2031, WWE SmackDown to 2029, the Premier League to the 2027–28 season and the WNBA to 2036, with $5.7 billion of programming commitments outstanding at the end of 2025, $1.4 billion of it due within a year. Overheads and selling, including NBCUniversal’s advertising fee, took $21.50. Of the $27.30 of free cash flow, $1.60 went in dividends and $6.00 in buybacks in the first half; Versant also spent $199 million on acquisitions and received $140 million for SportsEngine. The first half is the better half: sports costs rise from the third quarter, and the company has said third- and fourth-quarter EBITDA will probably not grow.
The debt, tranche by tranche
| Tranche | Amount ($M) | Rate | Matures | Repaying early | Security | Notes |
|---|---|---|---|---|---|---|
| 7.250% senior secured notes | 1,000 | 7.250% fixed; paid January 30 and July 30 | January 30, 2031 | Make-whole before January 30, 2028 (10% a year may be bought at 103); 103.625 from 2028, 101.813 from 2029, par from 2030 | First lien, equal with the loans; released if two agencies rate the notes investment grade | Must be offered at 101 on a change of control; at par from asset-sale proceeds not reinvested |
| Term loan A | 1,000 | SOFR + 1.75% (1.50% at first-lien leverage of 1.00× or less, 1.25% at 0.75× or less) | January 2, 2031 | Any time at par | First lien | Protected by the leverage covenant |
| Term loan B | 1,000 | SOFR + 3.50% | January 30, 2031 | Make-whole before January 2, 2027; 101 to January 2, 2028; par after | First lien | Excess-cash-flow sweep of 25–50% a year; no maintenance covenant |
| Total drawn | 3,000 | about 7% (first-half 2026 interest expense, annualized) | ||||
| Revolving credit facility | $750M | SOFR + 1.75% (same steps as term loan A); 0.25% on the unused amount | January 2, 2031 | First lien | Undrawn; up to $150M usable for letters of credit |
All three tranches are secured equally on substantially all of Versant’s assets, trademarks included, and guaranteed by 51 subsidiaries. $1.0 billion of interest-rate swaps fix part of the term loans; the filings do not say which loan or at what rate. Source: the indenture and credit agreements filed with the Form 10 and the January 5, 2026 8-K; the second-quarter 2026 10-Q, Note 5. As of June 30, 2026.
Principal due by year, including scheduled amortization. Term loan A amortizes 5% and term loan B 7% a year from September 30, 2026; everything else is due in January 2031.
Almost all the debt falls due in one month, January 2031: $2.46 billion after scheduled amortization of $60 million in 2026 and about $120 million a year from 2027. All three tranches are secured on substantially all of Versant’s assets, trademarks included, and rank equally.
Versant can repay the debt from its own cash. The October 7, 2026 scenarios, comparing the cash available to repay debt with the debt outstanding (2026–2030, estimates):
| Base case | Worst case (with restructuring) | |
|---|---|---|
| Free cash flow, 2026–2030 | $4.56B | $3.04B |
| Dividends at $1.50 a share | − ~$1.00B | − ~$1.00B |
| Cash at June 30, 2026, after the $530M Full Swing purchase | + ~$0.95B | + ~$0.95B |
| Available to repay debt | = ~$4.51B | = ~$2.99B |
| Debt outstanding | − $3.00B | − $3.00B |
| Cash left after repaying all debt | = ~$1.51B | = ~−$0.01B (~even) |
In the base case Versant repays all its debt by 2031 and still has ~$1.51B left, before any buybacks. In the worst case the cash just covers the debt, so buybacks would have to stop and nothing would be left over; neither case needs a refinancing.
Interest expense, 2026–2030
The term loans float, but the floating part shrinks every year. Term loan A pays SOFR plus 1.75% and term loan B SOFR plus 3.50%; $1.0 billion of swaps fix part of them, and the quarterly amortization pays both down. The forecast below uses SOFR at the path priced in fed funds futures on October 9, 2026 (rising from ~3.75% in 2026 to ~4.65% from 2028) and assumes the swaps fix ~3.65% and run to the loans’ maturity; the filings disclose neither the swaps’ rate nor their end date (all figures estimates, $ millions):
| $ millions | 2026 | 2027 | 2028 | 2029 | 2030 |
|---|---|---|---|---|---|
| SOFR, yearly average | ~3.75% | ~4.40% | ~4.65% | ~4.65% | ~4.65% |
| 7.25% notes (fixed) | $72 | $72 | $72 | $72 | $72 |
| Term loan A (SOFR + 1.75%) | + $55 | + $58 | + $58 | + $54 | + $51 |
| Term loan B (SOFR + 3.50%) | + $72 | + $73 | + $70 | + $64 | + $59 |
| Swaps on $1.0B (pay ~3.65% fixed, receive SOFR) | − $1 | − $8 | − $10 | − $10 | − $10 |
| Revolver fee (0.25% on $750M undrawn) | + $2 | + $2 | + $2 | + $2 | + $2 |
| Issuance costs written off over the term (non-cash) | + $10 | + $10 | + $10 | + $10 | + $10 |
| Interest expense | = ~$210 | = ~$209 | = ~$202 | = ~$193 | = ~$184 |
| Cash interest | ~$200 | ~$199 | ~$192 | ~$183 | ~$174 |
| Floating debt not covered by the swaps | ~$985 | ~$880 | ~$760 | ~$640 | ~$520 |
The 2026 figure matches the $105 million reported for the first half, doubled. Source: model in the site’s analysis files, from the credit agreements, the second-quarter 2026 10-Q and fed funds futures.
What a change in rates would do (interest expense, $ millions; per-share figures after tax at 21% on ~136 million shares):
| SOFR path | 2026 | 2027 | 2028 | 2029 | 2030 | Five years | Change | 2028, per share |
|---|---|---|---|---|---|---|---|---|
| 1 point lower | $207 | $200 | $194 | $187 | $179 | $968 | − $30 | + $0.04 |
| Futures path (base) | $210 | $209 | $202 | $193 | $184 | $998 | ||
| 1 point higher | $212 | $218 | $210 | $200 | $189 | $1,029 | + $30 | − $0.04 |
| 2 points higher | $215 | $226 | $217 | $206 | $195 | $1,059 | + $61 | − $0.09 |
| 2 points higher, and the swaps end in 2026 | $215 | $254 | $247 | $236 | $225 | $1,177 | + $178 | − $0.26 |
Rates barely move the cash flow while the swaps last: a 1-point rise costs ~$8–9 million a year, about 1% of guided free cash flow, which matches the company’s own estimate of ~$3 million a quarter. The unknown is the swaps’ end date. If they expired at the end of 2026 and rates rose 2 points, interest would be ~$45 million a year higher than the base case from 2027, ~$0.26 a share after tax; the third-quarter 10-Q is the place to look for the term.
Versant can also lower the cost. Term loan B, at SOFR plus 3.50%, is the most expensive tranche. From January 2, 2027 it can be repriced for a 1% fee and from January 2, 2028 repaid at par; a repricing to SOFR plus 2.75% would save ~$25 million over 2027–2030, ~$15 million after the fee (an estimate). Term loan A’s margin also falls to 1.50% when first-lien leverage is 1.00 times or less, worth ~$11 million over five years; the company has not said whether that step has applied.
| Covenant | Limit | Now | Room | Protects |
|---|---|---|---|---|
| First-lien net leverage (first-lien debt less cash, with cash counted up to the greater of $750M and 33% of EBITDA, over the last four quarters’ adjusted EBITDA) | 3.50× at most, tested quarterly from the third quarter of 2026 | about 0.97× (estimate, June 30, 2026) | EBITDA could fall about 72%, to about $640M | Term loan A and the revolver; term loan B and the notes have no maintenance test |
| Dividends and buybacks without limit | Total net leverage of 2.00× at most (notes, term loan B); 2.25× (term loan A) | about 0.66× at June 30, 2026; about 0.95× after the $530M Full Swing purchase in August 2026 (estimates) | Wide; fixed allowances apply above those levels | All three tranches |
| Proceeds of selling a network or business | Must repay debt with 100% of proceeds above set thresholds if first-lien leverage is above 1.00×, 50% between 0.75× and 1.00×, none at 0.75× or below; 18 months to reinvest instead | 50% band after the Full Swing purchase (estimate) | Thresholds: the greater of $112.5M a deal and $337.5M a year (term loan B), higher for term loan A | Term loans prepaid at par; notes offered at par |
| Excess cash flow | 50% of excess cash flow repays term loan B if first-lien leverage is above 1.25×, 25% at or below | 25% band | First payment after the 2026 annual report | Term loan B only |
The binding limit on buybacks is not the debt: under the tax matters agreement with Comcast, for two years from January 2, 2026, Versant may buy back shares only in the open market and below 20% of its stock. Leverage figures are estimates from the second-quarter 2026 10-Q and results; the company has not reported its covenant ratio.
The covenants shape how Versant uses its cash; solvency is not in question. The only maintenance test, first-lien net leverage of 3.50 times for term loan A and the revolver, has wide room: at about 0.97 times (an estimate, with cash counted only up to $763 million as the covenant requires), EBITDA would have to fall to about $640 million. Three rules shape what Versant can do with its money:
- Selling a network. Proceeds above set thresholds must repay debt in proportion to first-lien leverage: all of them above 1.00 times, half between 0.75 and 1.00 times, none at 0.75 or below, unless reinvested within 18 months. After the Full Swing purchase leverage is about 0.95 times (an estimate), so half the proceeds of a network sale would go to lenders, at par. The October 7, 2026 update discussed selling part of the portfolio; this is the cost of doing so before leverage falls.
- Excess cash flow. A quarter to half of each year’s excess cash flow repays term loan B, the most expensive tranche at SOFR plus 3.50%, from 2027.
- Buybacks. The debt allows unlimited dividends and buybacks below 2.00 times total net leverage. The tighter limit is the tax matters agreement with Comcast: until January 2, 2028, buybacks must be in the open market and below 20% of the stock, to protect the spin’s tax-free status.
The notes lose their security if rated investment grade. S&P and Fitch rate Versant BB with a stable outlook (as reported in January 2026; not confirmed from the agencies); two investment-grade ratings would release the collateral and suspend most of the notes’ covenants.
Where Versant is
The 10-K names only two properties: the leased New York headquarters and the owned Englewood Cliffs campus. Points marked “reported” come from press reports and directories. Click a point for details. Map data © OpenStreetMap contributors. Source: the 2025 10-K (Item 2) and second-quarter 2026 10-Q (Note 6) for the headquarters and Englewood Cliffs; press reports for the rest (Commercial Observer, NewscastStudio, Sports Video Group, The Real Deal). As of October 12, 2026.
Versant owns one major building. The 10-K names two properties: the leased headquarters at 229 West 43rd Street in New York, expanded in May 2026 to about 249,000 square feet on an 18-year lease, and the owned CNBC campus at 900 Sylvan Avenue in Englewood Cliffs, New Jersey, which houses CNBC’s studios and the master control for all the networks and was contributed by Comcast at about $168 million. Two key operations still run in Comcast’s buildings: Golf Channel is produced at NBC Sports in Stamford, Connecticut, under the transition agreement to the end of 2027, and MS NOW and CNBC share NBC News’s Washington bureau (both reported). Moving those is a cost still to come. CNBC’s international operations run from leased hubs in London and Singapore, with bureaus in Beijing and Abu Dhabi after Hong Kong closed in September 2026.
The audience is national, and shrinking at the same rate everywhere it is measured:
| Homes reached, millions (Nielsen) | 2022 | 2023 | 2024 | 2025 | Change, 2022–2025 |
|---|---|---|---|---|---|
| USA Network | 75 | 71 | 66 | 60 | −20% |
| E! | 75 | 71 | 65 | 59 | −21% |
| Syfy | 75 | 71 | 65 | 59 | −21% |
| MS NOW | 74 | 70 | 65 | 59 | −20% |
| CNBC | 73 | 70 | 64 | 59 | −19% |
| Oxygen | 64 | 64 | 62 | 60 | −6% |
| Golf Channel | 63 | 59 | 54 | 49 | −22% |
Year-end figures from Comcast’s 10-Ks for 2022–2024 and Versant’s 2025 10-K (Nielsen coverage estimates). Neither company reports subscribers by state or region.
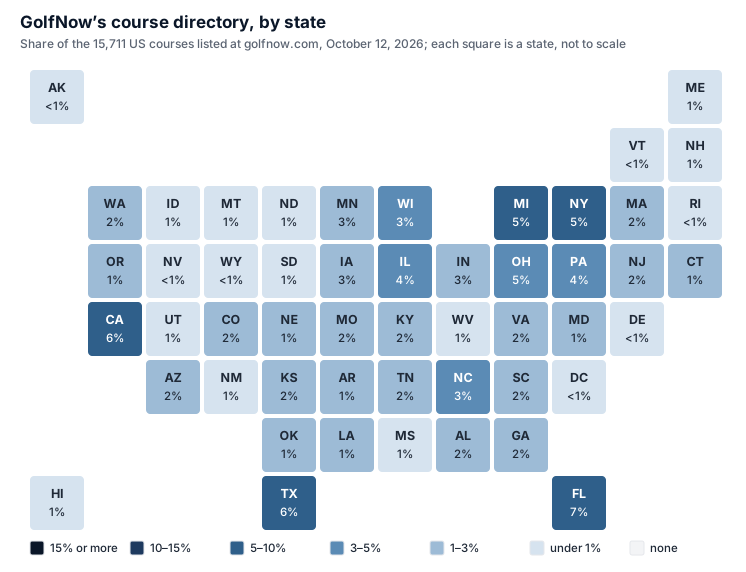
The growth businesses have a physical footprint of their own. GolfNow’s public directory lists about 15,700 US courses, spread like the country’s golf: Florida (7%), California (6%), Texas (6%), New York and Michigan (5% each). It lists about 3,900 more abroad, led by England (1,238), Canada (819), France (407), Australia (370), Ireland (365) and Scotland (325). A listing does not mean a course sells its tee times through GolfNow; the company does not disclose how many do.
Notes on earlier sections
- Maturity dates. The October 5, 2026 table gave “January 2031” for all three tranches and said the revolver’s maturity was not stated. From the agreements: the notes and term loan B mature on January 30, 2031, and term loan A and the $750 million revolver on January 2, 2031. A clarification, not a change.
- Covenant leverage. The October 5, 2026 update put first-lien net leverage at “about 0.8×”. On the covenant’s own definition, which counts cash only up to the greater of $750 million and 33% of EBITDA, it was about 0.97 times at June 30, 2026 (an estimate); on all cash it was about 0.66 times. The room under the 3.50 times test is wide on either measure. A clarification of basis.
What it means for the rating
Nothing here changes the rating: HOLD, target $41. The debt is safer than the equity: the lenders are covered even in the worst case, and the risk sits with shareholders through the decline in homes reached. The new points to watch are the cost of moving Golf Channel out of Comcast’s studios before the end of 2027, the advertising agreement’s renewal in about a year, and, if Versant sells a network, the share of the proceeds that would go to lenders instead of shareholders.
Update — October 9, 2026: who has been trading Versant, and why it fell in September 2026
Written against the October 8, 2026 close of $31.77. Sources: Versant’s SEC filings since the spin, including directors’ Forms 4 (for example David Novak’s March 2026 purchase) and the Schedule 13G filings of Vanguard and BlackRock; the buyback disclosures in its 10-Qs; S&P Dow Jones Indices’ December 23, 2025 announcement and its quarterly rebalance announcements since; MSCI’s May and August 2026 index reviews; FINRA short-interest and off-exchange volume data; the SEC’s Form 13F data sets for March 31 and June 30, 2026; funds’ Forms N-PORT; and closing prices for the stock and its peers. The analyses below are left as published. The rating and target are unchanged; this section is about the trading.
The one-line version
Versant fell 22.9% in September 2026, the same as Comcast and Charter (22.8%), while owners of other TV networks fell 9.3%. Investors sold it with the cable distributors after Comcast’s broadband warning on September 9, 2026, and there was no company news, index change or block trade to account for the move. Directors have bought shares this year and none has sold; the company has been the one steady buyer, through $300 million of repurchases. The holders who sold in September 2026 will be identifiable from the quarterly 13F filings due in mid-November 2026. The record through June 2026 shows the January 2026 exit of former Comcast holders, followed by event-driven funds handing their positions to index and quantitative funds.
What the price did
| Aug 31 – Sep 8, 2026 | Sep 8 – Sep 30, 2026 | Sep 30 – Oct 9, 2026 | |
|---|---|---|---|
| Versant | −7.0% | −17.1% | −2.7% |
| Cable distributors (Comcast, Charter) | −2.7% | −20.6% | −6.3% |
| TV networks and broadcasters (Fox, AMC Networks, Starz, Nexstar, Sinclair) | −3.7% | −5.8% | −1.8% |
| Russell 2000 | +0.3% | −5.7% | +0.3% |
| S&P 500 | −0.1% | −0.4% | +2.0% |
Closing prices rebased to August 31 = 100. Baskets are equal-weighted: cable distributors (Comcast, Charter); TV networks and broadcasters (Fox, AMC Networks, Starz, Nexstar, Sinclair); Russell 2000 and S&P 500 through their ETFs (IWM, SPY). Prices exclude dividends; Versant went ex-dividend $0.375 on October 1. Source: Yahoo Finance closes.
The month had two phases. In the first week Versant fell 7.0%, most of it in a single 5.8% decline on September 4, 2026 for which no company news or analyst action has been found. From September 8, 2026 it moved with the cable distributors: Comcast fell 6.6% on September 9, 2026 when its finance chief said broadband subscriber losses would not improve in the third quarter, Wolfe Research downgraded Charter on competition from fiber and satellite broadband, and the two companies ended the month down 22.8% together. Versant matched them to within a tenth of a point. Owners of other TV networks, whose economics are similar to Versant’s, fell less than half as much.
Versant’s own news in the period was neutral to positive. At Goldman Sachs' conference on September 8, 2026 management reiterated guidance, said the advertising market was “quite healthy” and confirmed a second $100 million accelerated buyback. Goldman cut its target from $46 to $43 on September 18, 2026 on a lower advertising estimate, the same day the White House barred MS NOW reporters, and Citi initiated at Buy with a $41 target on September 25, 2026. Versant announced its Verizon Fios renewal on October 2, 2026, completing the distribution agreements due in 2026.
The likely reason the stock traded with the distributors is that Versant’s largest revenue line, distribution fees, is paid by those companies for each video subscriber, and investors read a deteriorating outlook for cable operators as a risk to that line. The October 5, 2026 update judged Comcast’s warning to concern broadband rather than video and called the read-across sentiment; the trading in September 2026 shows that investors priced it as a direct exposure.
Whether the grouping is right. Versant has more reason than other TV-network owners to fall with the cable operators. Comcast and its affiliates are a direct customer, at $928 million or about 14% of 2025 revenue, a line that fell 31% over two years. Distribution fees are about 60% of Versant’s revenue, a larger share than at Fox or the broadcasters, whose retransmission fees have statutory protection. Versant also sells cable networks without broadcast stations or a streaming service to bundle with them, which is the weakest position from which to negotiate with a distributor under margin pressure. Against that, Comcast’s warning concerned broadband pricing, from which Versant earns nothing; Versant’s carriage fees are contracted, with every 2026 renewal done and two-thirds of agreements running to 2028 or later; and about 40% of its revenue comes from advertising, Platforms and licensing. Day to day, from August 2026 to early October 2026, its returns correlated more with the TV-network owners (0.56) than with Comcast and Charter (0.45), and on September 9, 2026 it fell 2.7% against Comcast’s 6.6%. On this evidence Versant belongs between the two groups. Had it fallen as far as the TV-network owners in September 2026, it would have closed the month near $37 rather than $31.70, so about $5–6 a share of the decline reflects the market’s closer grouping with the distributors.
On this site’s own numbers the current price is about fair. The base-case value in the October 7, 2026 update is $33, close to today’s price, which places the late-August 2026 price of $41 above fair value and makes the September 2026 decline the removal of that premium. The third-quarter distribution revenue, the trend in revenue from Comcast, and whether the September 2026 sellers of Versant were also selling Comcast and Charter, which the mid-November 2026 13F filings will show, are the evidence that would settle it.
Turnover since the spin
Daily volume (bars) and cumulative volume as a share of the 139.2 million shares outstanding (line). Gold bars mark days with a notable event; hover over one to see what happened. Source: this site's daily price archive (Yahoo Finance), through Oct 8, 2026.
| Average daily volume | Share of the company traded | Close | |
|---|---|---|---|
| January 2026 | 8.8M | 120.6% | $32.58 |
| February 2026 | 2.9M | 39.0% | $33.32 |
| March 2026 | 2.9M | 46.2% | $37.02 |
| April 2026 | 2.0M | 29.5% | $40.19 |
| May 2026 | 1.9M | 27.8% | $43.14 |
| June 2026 | 2.2M | 33.3% | $36.01 |
| July 2026 | 1.7M | 26.4% | $35.99 |
| August 2026 | 1.8M | 26.7% | $41.12 |
| September 2026 | 1.7M | 25.5% | $31.70 |
| October 2026 to the 8th | 2.1M | 9.0% | $31.77 |
| Since the spin | 384.0% |
More than the whole company changed hands in January 2026, as Comcast holders who did not want a cable-network company sold and small-cap index funds bought: S&P Dow Jones Indices placed Versant in the S&P SmallCap 600 from January 6, 2026, and Comcast stayed in the S&P 500. Volume settled at about 2 million shares a day by April 2026 and has stayed there. September 2026’s 22.9% decline came on about the same volume as July and August 2026, which is the pattern of buyers stepping back more than of a large holder selling in size. The heaviest day, September 18, 2026, at 5.8 million shares, was the quarterly options-expiry and index-update day.
Versant has had no S&P or MSCI index change since January 2026. It was not named in S&P’s March 2026, June 2026 or September 2026 rebalance announcements, nor in MSCI’s May 2026 or August 2026 changes. In the Russell indexes it inherited Comcast’s place at the spin, including the Russell Top 200, and moved from the Top 200 to the Russell Midcap at the June 26, 2026 reconstitution, as set out below.
Who has been buying and selling
Insiders bought and have not sold. Four directors bought in the open market in March 2026, none under a pre-arranged trading plan:
| Date | Director | Shares | Price |
|---|---|---|---|
| March 5, 2026 | David Novak | 143,000 | $36.85 |
| March 9, 2026 | Gerald Hassell | 10,000 | $36.07 |
| March 9, 2026 | Michael Conway | 1,350 | $36.14 |
| March 10–13, 2026 | Leonard Potter | 13,500 | $37.31–38.34 |
The only other dispositions by officers were shares withheld for tax on vesting awards. Brian Roberts, who holds the 377,775 Class B shares, has reported no trades.
The company has been the steadiest buyer.
| Quarter | Method | Shares | Average price |
|---|---|---|---|
| First | Open market | 2,694,125 | $37.12 |
| Second | Accelerated repurchase | 2,374,942 | $42.11 |
| Third | Accelerated repurchase, begun August 7, 2026 | Disclosed with third-quarter results |
Class A shares outstanding fell from 144.2 million at the spin to 138.8 million on July 31, 2026. A $100 million accelerated repurchase obliges the bank that runs it to buy shares in the market over the following weeks, so on the order of 2.5–2.7 million shares were bought for Versant between August 7, 2026 and the end of September 2026, an estimate based on the prices in that period.
Short interest rose through the summer and was flat into September 2026:
| Settlement date | Shares sold short | % of shares | Days of volume |
|---|---|---|---|
| April 30, 2026 | 1.68M | 1.2% | 0.9 |
| May 15, 2026 | 4.03M | 2.9% | 1.9 |
| June 30, 2026 | 3.82M | 2.7% | 1.3 |
| July 31, 2026 | 4.80M | 3.5% | 3.2 |
| August 31, 2026 | 5.90M | 4.2% | 4.3 |
| September 15, 2026 | 5.49M | 3.9% | 4.1 |
The increases coincide with the two accelerated repurchases, which start with the bank borrowing and delivering shares to the company and are commonly hedged with short positions. Part of the rise is therefore likely to be hedging rather than bets against the stock, an estimate that the third-quarter figures will test as the August 2026 repurchase settles. The September 30, 2026 figure has not yet been published.
Holders through June 30, 2026. Former Comcast holders received one Versant share for every 25 Comcast shares. Comparing their Comcast positions at December 31, 2025 with their Versant positions at June 30, 2026 shows who left:
| Holder | Shares received (estimated from Comcast holdings) | June 30, 2026 | Change |
|---|---|---|---|
| Vanguard | 14.8M | 16.0M | Held |
| BlackRock | 12.6M | 18.1M | Added |
| State Street | 7.5M | 4.8M | −36% |
| Capital World Investors | 5.6M | 0 | Sold out |
| Invesco | 5.0M | 0.9M | −82% |
| Dodge & Cox | 4.5M | 4.5M | Held |
| Geode | 3.6M | 3.6M | Held |
| Norges Bank | 3.3M | 4.5M | Added |
| Fidelity | 2.7M | 1.3M | −50% |
| JPMorgan | 2.5M | 0.6M | −76% |
| Capital Research Global Investors | 2.2M | 1.2M | −47% |
| Eagle Capital | 1.6M | 0 | Sold out |
The active managers that owned Comcast for its own sake sold most of what they received in the first months. Dodge & Cox, the largest traditional active manager among the holders, kept its whole position. Between March 31 and June 30, 2026 a second rotation followed: event-driven and hedge funds that had bought the spin reduced or sold out, among them Marshall Wace (−2.3 million shares), Ranmore, First Eagle, Gates Capital, Greenlight (−1.1 million) and Citadel (−0.9 million), while index and quantitative managers added, among them Goldman Sachs (+2.3 million), Dimensional (+2.0 million), Geode (+1.7 million), American Century (+1.5 million) and Qube (+1.0 million). Dimensional’s value funds kept adding through July 31, 2026.
The September 2026 sellers are therefore most likely among the remaining active and hedge-fund holders of June 30, 2026, including AQR (6.0 million shares), Dodge & Cox (4.5 million), Citadel and Greenlight, but no filing yet shows a September 2026 trade by any of them. The third-quarter Forms 13F, due by about November 16, 2026, will show each holder’s position at September 30, 2026, and the table above will be updated then.
Which indexes hold it, and which it could join
The largest index-fund holders are iShares’ S&P SmallCap 600 fund (8.5 million shares on June 30, 2026, about 6% of the company), Vanguard’s total-market fund (4.5 million), Vanguard’s small-cap and small-cap value funds (3.2 million and 2.1 million) and Vanguard’s extended-market fund (1.6 million). Funds tracking the S&P SmallCap 600 hold an estimated 8% of the company between them, and the Vanguard funds that follow Morningstar’s (formerly CRSP’s) indexes about 9%. Evidence below comes from funds' filings (N-PORT, mostly dated May to July 2026) and State Street’s daily holdings files for October 8, 2026.
Where it is now
| Index family | Index | Member | How it is known |
|---|---|---|---|
| S&P Dow Jones | S&P SmallCap 600, since January 6, 2026; classified as communication services | Yes | S&P’s December 23, 2025 announcement; State Street’s S&P 600 fund, October 8, 2026 |
| S&P Dow Jones | S&P 600 Value (all of its weight), S&P 600 Pure Value, S&P Composite 1500, Total Market, Completion, S&P 600 communication services sector | Yes | Fund holdings files and filings; S&P 600 Growth funds do not hold it |
| S&P Dow Jones | S&P U.S. Spin-Off Index | Yes | Invesco’s spinoff fund held 0.17 million shares (2.7% of the fund) on July 31, 2026 |
| S&P Dow Jones | S&P 500, S&P MidCap 400 | No | |
| FTSE Russell | Russell 1000 and Russell 3000 | Yes, since the spin | iShares Russell 1000 fund, March 31 and June 30, 2026 |
| FTSE Russell | Russell Top 200 (January to June 2026) → Russell Midcap and Russell 2500 (since June 26, 2026) | Midcap: yes | iShares Russell Top 200 funds held it on March 31, 2026 and not on June 30, 2026; iShares Russell Mid-Cap, Mid-Cap Value and Russell 2500 funds first held it on June 30, 2026 |
| FTSE Russell | Russell 1000 Value and Midcap Value (all of its weight); Russell 2000 | Value: yes. 2000: no | Value funds hold it; no Russell 1000 Growth or Russell 2000 fund does |
| MSCI | MSCI USA Small Cap; MSCI USA IMI | Yes | iShares MSCI USA small-cap and MSCI World small-cap funds; MSCI did not add it to the large- and mid-cap MSCI USA in February 2026 |
| FTSE | FTSE US and Global All Cap | Yes | Vanguard’s total world fund, July 31, 2026 |
| FTSE | FTSE All-World (large and mid) or FTSE Global Small Cap | Probably small cap | Inferred from size; no fund separates the two |
| Morningstar (formerly CRSP) | US Small Cap and Small Cap Value; not Mid Cap | Yes | Vanguard small-cap funds hold it; Vanguard’s mid-cap funds do not |
| Nasdaq | Nasdaq Composite; not the Nasdaq-100 | Yes | Fidelity’s Nasdaq Composite index funds, May 31, 2026 |
| Dividend indexes | Removed from FTSE High Dividend Yield (Vanguard VYM), S&P U.S. Dividend Growers (Vanguard Dividend Appreciation) and others it received from Comcast | No | Held on January 31, 2026 only |
| Dividend and cash-flow indexes | Pacer US Small Cap Cash Cows; Russell 1000 Yield Focus | Yes | Fund filings, June and July 2026 |
What could change, and when
The price thresholds use about 137 million shares and the close of $31.77 on October 8, 2026 (a market value of about $4.35 billion). Average daily volume over the past three months was about 1.7 million shares.
| Index move | The rule | Where Versant stands | Next dates | Likelihood (judgement) |
|---|---|---|---|---|
| Back into FTSE High Dividend Yield (Vanguard VYM) | Annual review of the FTSE US All Cap universe by forecast dividend yield; no minimum dividend history (ground rules) | A forecast yield of about 4.7%, in the top half of the universe; it was removed before it had paid a dividend | Annual review, estimated March 2027 from the timing of past changes in the fund’s holdings | Probable |
| WisdomTree U.S. dividend indexes | Regular cash dividends paid in the 12 months before the screening date (the last trading day of November 2026), with minimum size and liquidity; reconstituted each December (prospectus) | Three dividends paid by the November 2026 screen | Effective mid to late December 2026 | Probable |
| Morningstar Dividend Yield Focus (iShares HDV) | A dividend in the last 12 months, plus an economic-moat or credit-risk screen; ranked by trailing yield | Trailing yield about 3.5% on three payments; the credit screen is uncertain for a leveraged company | December 2026, June 2027 | Possible |
| Dividend-history indexes (Schwab SCHD, iShares DVY, SPDR SDY, Vanguard VIG) | 5 to 20 years of dividends | Under one year | Not before 2031 | No |
| Russell 1000 → Russell 2000 | Existing members keep their seat within a band around the breakpoint ($5.7 billion in June 2026); the smallest Russell 1000 member after banding was $2.7 billion (June 2026 summary) | $4.35 billion, inside the band; the June 2026 lower edge is equivalent to about $19.70 a share | Size measured October 30, 2026; effective after the close December 11, 2026; June 2027 | Low |
| S&P SmallCap 600 → S&P MidCap 400 | Migration at the committee’s discretion once in the $8.0–22.7 billion range (S&P) | Equivalent to about $58.40 a share | Quarterly, from December 2026 | Remote |
| Morningstar Small Cap → Micro Cap | Breakpoint near $3 billion, with a buffer | Equivalent to about $20–22 a share | Quarterly | Low |
| MSCI USA Small Cap → MSCI USA | Above a buffer over MSCI’s unpublished US cutoff; the smallest MSCI USA member was $6.2 billion on September 30, 2026 | At least $45–50 a share, an estimate | Review effective December 1, 2026 | Remote |
| Nasdaq-100 | The 100 largest non-financial Nasdaq companies | Equivalent to about $150 a share | December 2026 | Remote |
Both S&P and Russell class it entirely as value, and a change at their December 2026 style reviews is unlikely on its valuation (a judgement).
What the moves would mean for trading
These are estimates. The likely changes in the next year are small and all on the buy side: WisdomTree’s dividend funds in December 2026 (about 0.3–0.5 million shares), Vanguard’s high-dividend fund on its estimated March 2027 review (about 0.6 million, the size of its January 2026 position) and possibly iShares’ dividend-yield fund. Together that is about 1.0–1.3 million shares, under 1% of the company and less than one day of volume, spread over several months. Against this, index funds sell small amounts each quarter as the buybacks reduce the share count.
The size moves that would trade heavily are unlikely at this price. A fall to the Russell 2000 would mean net buying of an estimated 7% of the company (9–10 million shares, about five days of volume), because more money tracks the Russell 2000 than the Russell Midcap; it would need the price near $20 on a rank day. A fall to Morningstar’s micro-cap segment would mean Vanguard’s small-cap funds selling an estimated 6 million shares.
Versant has no index event due in December 2026. It already made its Russell move from the Top 200 to the Midcap in June 2026. December 11 and 18, 2026 should bring ordinary volume for this stock, apart from the quarterly options expiry on the 18th. For the rating this changes nothing. For holders, the 4.7% yield, which so far has cost Versant its place in dividend indexes for want of a record, starts to bring dividend-index buyers back from December 2026.
Two notes on earlier sections
- The Verizon Fios renewal was announced on October 2, 2026. The October 5, 2026 update listed it under September 2026, and the October 7, 2026 update said Verizon Fios “completed the cycle in September 2026”. Both should read October 2, 2026. This is a data correction; the substance, that every distribution agreement due in 2026 has been renewed, is unchanged.
- What moved the stock in September 2026. The October 5, 2026 update attributed the decline to higher interest rates and to sentiment carried over from Comcast. The trading shows a closer link: Versant moved with Comcast and Charter almost exactly and much further than other TV-network owners or small companies generally.
What it means for the rating
The rating stays HOLD and the target $41. The fall was a repricing of the cable bundle that Versant’s fees depend on, with no new information about Versant’s own results, and the October 7, 2026 scenarios already assume distribution revenue declining 6–7% a year in the base case. It does mean the stock will continue to trade with Comcast and Charter until its own results show whether distribution fees are declining faster. The third-quarter results on November 3, 2026 are the first test, and distribution revenue against the base case’s −6% to −7% is the line to read.
Update — October 7, 2026: the valuation by scenario and by brand — HOLD, target $41
Written against the October 7 close of $31.44. Sources: Versant’s 2025 10-K, its first-quarter and second-quarter 10-Qs, the second-quarter results release, the December 2025 investor presentation, the Tax Matters Agreement with Comcast, and the Full Swing acquisition release. Brand-level and transaction figures from third parties are linked where they are used. Versant reports a single segment and discloses nothing by brand, so every brand-level revenue, margin and value below is an estimate, and is labelled as one. The October 5 and September 10 analyses below are left as published; this section corrects five of their statements and replaces the valuation.
The one-line version
Revenue is falling about 4% a year underneath, not 2.5%, and free cash flow falls about three times as fast as revenue. Built line by line, the base case has free cash flow declining about 14% a year to 2030 — close to the 15.5% the market prices. The October 5 update read that 15.5% against a 2.5% revenue decline and called the market’s assumption several times too harsh; on a like-for-like basis it is roughly the base case.
The upside is real but sits in the tails: a best case worth $79 a share, a worst case worth $18, and a base case worth $33, about today’s price. By brand, the parts are worth $32–70 a share after the tax a sale would trigger, but the most valuable networks cannot be sold before January 2028, and the networks a seller would want to shed are exactly the ones a buyer pays least for.
Rating: ACCUMULATE → HOLD · Target $42 → $41 · Grade: B (2.75), unchanged
Revenue, line by line
From the 10-K and 10-Qs, in millions of dollars.
| 2023 | 2024 | 2025 | H1 2025 | H1 2026 | H1 change | |
|---|---|---|---|---|---|---|
| Linear distribution | 4,632 | 4,325 | 4,092 | 2,103 | 1,959 | −6.8% |
| Advertising | 1,865 | 1,731 | 1,577 | 814 | 791 | −2.8% |
| Platforms | 734 | 795 | 826 | 398 | 417 | +4.8% |
| Content licensing and other | 213 | 211 | 193 | 100 | 164 | +63.4% |
| Total | 7,445 | 7,062 | 6,688 | 3,415 | 3,331 | −2.4% |
| Change | −5.1% | −5.3% |
The first-half figure is flattered twice. A large content-licensing agreement recognized in the first quarter added about $64 million on its own (licensing revenue rose 112% in the quarter), and SportsEngine was sold on May 1. Stripping both out leaves the core of the business — distribution, advertising and Platforms excluding SportsEngine:
| Core revenue, change on a year earlier | |
|---|---|
| First quarter 2026 | −5.3% |
| Second quarter 2026 | −2.8% |
| First half 2026 | −4.1% |
The decline is easing, from −5.3% in 2025 to about −4%, but it has not halved.
Management’s own guidance points the same way. The raised range of $6.2–6.45 billion implies second-half revenue down 4.7% to 12.3% on a year earlier, −8.5% at the midpoint. Part of that is SportsEngine’s absence and the licensing deal not recurring; it is still not a company running ahead of its guidance.
Linear distribution — about 60% of revenue: contracted, and in permanent decline
Fees paid per subscriber by cable, satellite, fiber and streaming TV distributors. Subscribers fell 8% in both 2024 and 2025; contractual rate increases offset about 1.5 points in 2024 and 2.8 points in 2025. In 2026 the line is running at −6.8%.
- Resilient in the near term. Agreements run for several years; every renewal due in 2026 is done (Verizon Fios completed the cycle in September), and two-thirds of the agreements do not come up until 2028 or later.
- Weaker at renewal. The 10-K warns that Versant’s negotiating position may suffer without NBCUniversal’s broadcast networks, Bravo and Peacock to sell alongside it. A lost carriage agreement is a step, not a slope: a large one could take 5–8% of revenue at once.
- Concentrated in the former parent. Sales to Comcast and its affiliates were $928 million in 2025, about 14% of revenue, down from $1.34 billion in 2023 — a 31% fall in two years, much faster than the company as a whole.
Advertising — about 24%: the least resilient line
Network ratings fell 17% in 2025 and 8% in 2024, and advertising fell 8.9% and 7.2%. The second quarter of 2026 (−0.6%) was helped by better ratings — MS NOW’s viewing rose 14% — but also by revenue from an acquisition that is not quantified; the first quarter was −5.4%. NBCUniversal sells the inventory on Versant’s behalf for about two years after the separation. News advertising follows the election cycle, and the November midterms help the fourth quarter. A range of 0% to −9% a year is the realistic band.
Platforms — about 12.5%: the only growing line, and consumer-cyclical
GolfNow and GolfPass (tee times, on-course payments, subscriptions), Fandango and Rotten Tomatoes (tickets, rentals, a new cinema operating platform) and CNBC’s subscription products. Growth was 6.1% a year from 2023 to 2025 and 10.4% in the first half of 2026 excluding SportsEngine. Revenue is Versant’s fee or share on each transaction, not the ticket or green fee, so it moves with box office and discretionary spending: in a weak box-office year, 2025, the line grew 3.9%. Full Swing, acquired August 3, adds to it from the third quarter.
Content licensing and other — 3–5%: lumpy, and not a trend
Timing-driven: −8.5% in 2025, +112% in the first quarter of 2026 on a single agreement. It is excluded from every growth-rate argument above.
Corrections to the October 5 and September 10 analyses
- “The revenue decline halved” (September 10). The first-half figure of −2.5% includes the one-off licensing agreement and SportsEngine’s partial half-year. The underlying decline is about −4.1%. The second quarter was −3.8%, not −3.7%.
- “Tracking ahead of its own guidance on the top line” (September 10). Annualizing the first half overstates the year: guidance implies the second half declines 4.7–12.3%.
- Platforms “includes SportsEngine” (September 10). SportsEngine was sold to PlayMetrics on May 1, 2026 for $143 million.
- “Two consecutive quarters of revenue decline under 2%” (September 10, What would change this view). The first quarter’s −1.2% met this on the headline only because of the licensing agreement. The test should be read on core revenue, as above.
- “The market prices the decline at several times its current rate” (October 5 and September 10). That compared a market-implied free cash flow decline of 15.5% a year with a revenue decline of 2.5%. Costs do not fall one for one with revenue, so free cash flow falls faster: in the base case below, about 14% a year. This is the correction that changes the rating.
One change in the business, not a correction: net debt has risen since June 30. Full Swing cost about $530 million in cash (closed August 3), and the third quarter carried a $100 million accelerated buyback and a dividend. Net debt at September 30 is estimated at about $2.05 billion, against $1.52 billion at June 30, and the share count at about 136.2 million after the buyback.
Three scenarios, built line by line
Each revenue line has its own drivers, and the lines add to the total. 2026 is the reported first half plus a forecast second half; 2027–2030 grow each line on its drivers. All figures are estimates.
| Driver | Best | Base | Worst | Evidence |
|---|---|---|---|---|
| Subscribers, a year | −6% | −8% | −10% | −8% in both 2024 and 2025 |
| Distribution rate increases, a year | +3% | +2% | +1% | +1.5% and +2.8% implied in 2024–25 |
| Carriage loss | none | none | −7% of distribution at the 2028 renewals | Two-thirds of agreements renew from 2028 |
| Advertising trend, a year | −3% | −6% | −9%, plus a recession year in 2027 | −7.2% and −8.9% in 2024–25 |
| Election-year swing | ±2 points | ±2 points | ±2 points | Even years help news |
| Platforms excluding SportsEngine, a year | +12% | +8% | +3% | +10.4% in H1 2026; +3.9% in 2025 |
| Licensing and other, a year | $220M | $200M | $170M | $193–213M in 2023–25 |
Full Swing is excluded throughout: its revenue is not disclosed, and it is carried at its purchase price in the sum of the parts further down.
Revenue, millions of dollars:
| 2025 | 2026E | 2027E | 2028E | 2029E | 2030E | A year, 2025–30 | |
|---|---|---|---|---|---|---|---|
| Best | 6,688 | 6,508 | 6,301 | 6,272 | 6,202 | 6,208 | −1.5% |
| Base | 6,688 | 6,422 | 6,022 | 5,812 | 5,568 | 5,402 | −4.2% |
| Worst | 6,688 | 6,312 | 5,597 | 4,981 | 4,618 | 4,333 | −8.3% |
The base case by line:
| 2025 | 2026E | 2027E | 2028E | 2029E | 2030E | A year | |
|---|---|---|---|---|---|---|---|
| Linear distribution | 4,092 | 3,819 | 3,583 | 3,363 | 3,156 | 2,961 | −6.3% |
| Advertising | 1,577 | 1,531 | 1,409 | 1,352 | 1,244 | 1,194 | −5.4% |
| Platforms | 826 | 815 | 830 | 897 | 969 | 1,046 | +4.8% |
| Content licensing and other | 193 | 257 | 200 | 200 | 200 | 200 | — |
| Total | 6,688 | 6,422 | 6,022 | 5,812 | 5,568 | 5,402 | −4.2% |
| Platforms share | 12.4% | 12.7% | 13.8% | 15.4% | 17.4% | 19.4% |
Three things follow:
- 2027 looks worse than the trend in every case (−6.2% in the base case) because the licensing agreement and SportsEngine’s last half-year drop out of the comparison. The clean 2026 base is about $6.3 billion.
- Distribution decides the outcome. At 60% of revenue, each point of subscriber loss moves the total by about 0.6 points.
- No case reaches growth. Platforms reaches about a fifth of revenue by 2030 in all three. Management’s target of a third of revenue from outside pay-TV within three to five years requires acquisitions in every case — which its chief revenue officer has said (“we will have to do more M&A”).
From revenue to EBITDA and free cash flow
Cost assumptions, all estimates:
- Programming and production, about half of all costs, moves with linear revenue (distribution, advertising and licensing) at 100% / 80% / 60% of its decline in the best, base and worst cases. The evidence: from 2023 to 2025 programming fell 10.2% against linear revenue’s 12.6%, about 80%. For 2026 it is set so that the guided midpoint revenue produces the guided midpoint EBITDA of $1,975 million, which puts second-half programming about 5% above a year earlier, as new sports rights (PAC-12, Bundesliga) begin.
- Worst case includes a restructuring. A decline that steep would not be met with an unchanged cost base. Costs lag in 2027; from 2028 programming is cut 8% (unprofitable rights dropped at renewal) and then tracks revenue one for one, SG&A falls 6% a year, and the restructuring costs $200 million in cash.
- Platforms’ direct costs run at 57–61% of Platforms revenue (59% in the first half of 2026). SG&A starts at $1,440 million (the first half was $715 million excluding separation costs) and moves −1% / +1.5% / +3% a year.
- Interest about $200 million a year (the first half was $105 million). Cash taxes at 26% of EBITDA less interest and capital expenditure, which is fully deductible under the 2025 tax law. Capital expenditure $150 million a year.
- Other cash items: $191 million in 2026. This is the gap between an EBITDA-based build (about $1.29 billion of free cash flow) and the $1.1 billion guided midpoint — separation costs, working capital and tax timing that the filings do not break out. It recurs at 0% / 50% / 100% in the three cases.
| $ millions | 2026E | 2027E | 2028E | 2029E | 2030E | A year, 2026–30 |
|---|---|---|---|---|---|---|
| Base — revenue | 6,422 | 6,022 | 5,812 | 5,568 | 5,402 | −4.2% |
| Adjusted EBITDA | 2,072 | 1,785 | 1,611 | 1,415 | 1,269 | −11.5% |
| EBITDA margin | 32.3% | 29.6% | 27.7% | 25.4% | 23.5% | |
| Free cash flow | 1,172 | 1,055 | 926 | 758 | 649 | −13.7% |
| Per share | $8.60 | $7.75 | $6.80 | $5.56 | $4.77 | |
| Best — adjusted EBITDA | 2,151 | 2,057 | 2,040 | 1,997 | 1,996 | −1.9% |
| Free cash flow | 1,230 | 1,359 | 1,346 | 1,291 | 1,290 | +1.2% |
| Worst — adjusted EBITDA | 1,973 | 1,395 | 1,308 | 1,180 | 1,091 | −13.8% |
| EBITDA margin | 31.3% | 24.9% | 26.3% | 25.6% | 25.2% | |
| Free cash flow | 1,099 | 660 | 395 | 477 | 412 | −21.8% |
Cumulative free cash flow, 2026–2030, per share: best $47.85, base $33.48, worst $22.34 — against a share price of $31.44 and net debt of about $15 a share.
What happens to the cash. The scenarios do not allocate it. Debt is held at $3.0 billion (interest stays near $200 million a year, ignoring the scheduled term loan repayments), the share count is held at 136.2 million, and cash accumulates. The valuation below does not depend on that choice: it discounts free cash flow before interest and deducts today’s net debt, which is neutral to allocation as long as the cash earns roughly the 10% discount rate. Repaying term loan B saves about 8%; buying back stock at $31 against a base-case value of $33 returns a little more than 10%. Two things do depend on it:
- Per share figures. At the current pace of $100 million a quarter, buybacks would retire roughly a third of the shares by 2030, so free cash flow per share falls more slowly than shown. Buybacks at $31 are strongly accretive in the best case, about neutral in the base case, and destroy value in the worst case, where the shares are worth $18.
- The 2031 maturity. Estimated cash of about $950 million at September 30, plus free cash flow from the fourth quarter of 2026 through 2030, less the $1.50 dividend, set against $3.0 billion of debt:
| Scenario | Cash available by the end of 2030 | Against $3.0B of debt | With buybacks at $400M a year |
|---|---|---|---|
| Best | $5.5B | $2.5B surplus | $0.8B surplus |
| Base | $3.6B | $0.6B surplus | $1.1B to refinance |
| Worst | $2.1B | $0.9B to refinance | $2.6B to refinance |
Buybacks at the current pace and repaying the debt cannot both happen outside the best case. In the base case, sustaining the buyback means refinancing about $1.1 billion in 2031 for a business a fifth smaller than today’s; in the worst case, refinancing is needed even with no buybacks, or the dividend gives. That is the argument for starting to repay term loan B in January 2027, when its prepayment cost falls to 1%.
Which assumption matters most. Changing one base-case driver at a time, 2030 free cash flow of $649 million becomes:
| One change to the base case | 2030 free cash flow | Change |
|---|---|---|
| Subscribers fall 6% a year, not 8% | $776M | +20% |
| Programming falls one for one with linear revenue, not 80% | $724M | +12% |
| Advertising trend −3% a year, not −6% | $725M | +12% |
| SG&A flat, not +1.5% a year | $715M | +10% |
| Platforms +12% a year, not +8% | $699M | +8% |
The subscriber rate is the single largest driver, and the cost side, taken together, is about as large. Platforms growth, the centre of management’s strategy, moves the answer least.
Two features of the next eighteen months worth knowing in advance:
- Reported earnings will jump in 2027 and cash flow will not. Amortization of intangible assets is $884 million in 2026 and $9 million in 2027, according to the 10-K’s schedule. That adds roughly $4.75 a share to 2027 earnings. The intangibles carry little tax basis (the deferred tax liability on them was $169 million at year-end), so the deduction has largely gone already, and cash taxes do not change. The price-to-earnings ratio will look much cheaper next year for no change in the business.
- The second half of 2026 is thin. First-half free cash flow was $908 million against full-year guidance of $1.0–1.2 billion, which leaves $92–292 million for the second half. Part of the explanation is tax timing: first-half current tax was about $334 million, of which $208 million was paid. The third-quarter results will show whether the $191 million gap above is a one-time item or a recurring one.
The valuation, by scenario
Each scenario’s free cash flow, before interest, is discounted at 10% — the rate used on October 5 — with a terminal decline after 2030 of 2% a year in the best case and 6% in the base and worst cases. Net debt of about $2.05 billion is then deducted.
| Scenario | Enterprise value | EV / 2026 EBITDA | Per share | Weight |
|---|---|---|---|---|
| Best | $12.8B | 6.5× | $79 | 25% |
| Base | $6.5B | 3.3× | $33 | 50% |
| Worst | $4.5B | 2.3× | $18 | 25% |
| Probability-weighted | $41 (40.64) |
| Discount rate | Best | Base | Worst | Weighted |
|---|---|---|---|---|
| 10% | $79 | $33 | $18 | $41 |
| 10.5% | $75 | $32 | $17 | $39 |
| 11% | $72 | $30 | $16 | $37 |
The target is $41, the probability-weighted value at 10%. It replaces the $42 from October 5, whose two reverse-DCF methods assumed free cash flow declining 8% and 11% a year — slower than the base case built here.
The distribution matters more than the average. The weighted value is 29% above the price, but half the probability sits on the base case at $33, and a quarter on the worst case at $18. The median outcome is roughly today’s price; the gap to the target is the value of the best case. That is the reason for HOLD rather than ACCUMULATE.
The 25 / 50 / 25 weights are a judgement, not a measurement. No data assigns probabilities to these scenarios; the weights say only that the base case is the most likely outcome and that the two tails are treated evenly. The target moves with them:
| Weights, best / base / worst | Value per share |
|---|---|
| 30 / 50 / 20 | $44 |
| 25 / 50 / 25 (the target) | $41 |
| 20 / 60 / 20 | $39 |
| 15 / 70 / 15 | $38 |
| 10 / 80 / 10 | $36 |
| 10 / 60 / 30 | $33 |
What the best case requires — four things at once, each better than the recent record:
- Subscribers falling 6% a year, against 8% in both 2024 and 2025
- Advertising declining 3% a year, against 7–9% in 2024–25
- Programming costs falling one for one with linear revenue, against about 80% in 2023–25
- Platforms growing 12% a year, against 6% a year in 2023–25 and 10% in the first half of 2026
It also carries the mildest terminal assumption, a 2% annual decline after 2030, which accounts for about 60% of its value.
What the worst case requires — several things going wrong together:
- Subscribers falling 10% a year, against 8% in each of the two years disclosed
- A lost carriage agreement at the 2028 renewals, taking 7% of distribution revenue at once
- An advertising recession in 2027 on top of a 9% annual decline
- Costs lagging revenue for a year before a restructuring that costs $200 million
Two things follow, whatever the weights:
- Any even weighting of the two tails lands at or above the base case’s $33, because the best case sits much further above the base than the worst case sits below it. Only weights tilted toward the worst case reach today’s price: holding the worst case at 25%, $31.44 implies about a 5% chance of the best case.
- There is a fair argument that both tails deserve less than 25%, since each requires several departures from the record at once. At 15 / 70 / 15 the value is $38.
The target stays at $41, with this range stated. The HOLD rating does not depend on the weights: it rests on the base case sitting at the price and on the after-tax break-up value of about $32 under it.
Sum of the parts, by brand
Every figure in this table is an estimate. Distribution revenue is built from per-subscriber fee estimates — S&P Global Market Intelligence puts CNBC at $0.66 and MS NOW at $0.39 a month in 2025, as cited in Newsmax’s 10-K, and USA Network’s carriage revenue was about $1.6 billion in 2023 (Sportico). Fees for Golf Channel, E!, SYFY and Oxygen are not public and are estimated. The fee-based build falls about a fifth short of reported distribution revenue (international feeds, and fee estimates that lag renewals), so it is scaled up pro rata. Brand margins are estimates, set so that the brands add to the guided EBITDA after $257 million of head-office costs, close to the $273 million of standalone costs in Versant’s investor presentation. The news networks come to about $890 million of EBITDA, consistent with a 2024 report of about $1 billion between them, and with S&P’s 2022 estimate of MSNBC’s profit at $455 million on $903 million of revenue (Pew Research Center).
| Unit, 2026E | Revenue | EBITDA | Margin | EV / EBITDA, low · mid · high | Value, mid |
|---|---|---|---|---|---|
| CNBC, with its subscription products | 890 | 490 | 55% | 5 · 7 · 9× | 3,427 |
| MS NOW | 774 | 402 | 52% | 4 · 6 · 8× | 2,415 |
| USA Network | 2,061 | 515 | 25% | 3 · 4 · 5× | 2,061 |
| GolfNow and GolfPass | 370 | 92 | 25% | 10 · 13 · 16× | 1,202 |
| SYFY | 511 | 179 | 35% | 2 · 3 · 4× | 537 |
| E! | 507 | 178 | 35% | 2 · 3 · 4× | 533 |
| Golf Channel | 403 | 101 | 25% | 3 · 4.5 · 6× | 454 |
| Content licensing and other | 257 | 103 | 40% | 3 · 4 · 5× | 411 |
| Oxygen | 273 | 123 | 45% | 2 · 3 · 4× | 368 |
| Fandango and Rotten Tomatoes, Versant’s 75% | 330 | ~50 | 15% | 0.8 · 1.2 · 1.8× revenue | 297 |
| Full Swing and Free TV Networks, at cost | 700 | ||||
| SportsEngine, to May 1 | 46 | — | — | ||
| Head-office costs | (257) | 5 · 4.5 · 4× | (1,156) | ||
| Enterprise value | 6,422 | 1,975 | 3.8 · 5.7 · 7.5× | 11,248 |
| Per share | Low | Mid | High |
|---|---|---|---|
| Sum of the parts, less net debt | $40 | $68 | $94 |
| After-tax break-up value | $32 | $52 | $70 |
| Market: $31.44, 3.2× 2026 EBITDA |
The break-up line assumes the assets carry almost no tax basis, so a sale pays about 26% tax on the proceeds, plus 2% in deal costs; head-office costs disappear with the company. At $31, the stock trades at the low-case break-up value.
What the multiples rest on:
- Cable networks sell cheaply, when they sell. Hearst bought Disney’s half of A+E Networks in August 2026 for $1.2 billion, at what one analyst called a “low single-digit” EBITDA multiple, and below Disney’s book value (TheWrap). Warner Bros. Discovery’s bankers valued its cable networks at 4.0–5.0× 2026 EBITDA in February, against a range of 3.6–6.7× for listed U.S. peers (proxy).
- There is no recent sale of a major U.S. news network to mark CNBC or MS NOW against. Their multiples are judgement, not precedent — and those two networks carry about half the value.
- Versant’s own transactions: SportsEngine went for about 1.1× revenue (estimated), against the $400–500 million reported to be hoped for in 2025; Full Swing cost about 15× one analyst’s 2027 EBITDA estimate (TheWrap).
- Fandango is 75% owned. The remaining quarter has been reported as held by Warner Bros., which became part of Paramount Skydance on October 6. Versant’s balance sheet carries $110 million of noncontrolling interests.
Selling part of the portfolio
A sale creates value only if the after-tax proceeds, per dollar of EBITDA given up, beat buying back Versant’s own stock at 3.2×. At an estimated 26% tax on the proceeds:
| Sell | Price, EV / EBITDA | Kept after tax | Against a buyback at 3.2× |
|---|---|---|---|
| GolfNow and GolfPass | 14× | 10.4× | Strongly accretive |
| CNBC | 8× | 5.9× | Accretive |
| MS NOW | 7× | 5.2× | Accretive |
| Golf Channel | 4.5× | 3.3× | Break-even |
| USA Network | 4× | 3.0× | Slightly dilutive |
| E!, SYFY, Oxygen | 3× | 2.2× | Dilutive |
- Selling the lower-margin entertainment networks loses money. At 3× before tax, Versant would keep 2.2× for networks that still earn 35–45% margins. Unless a network is close to breaking even, cutting its programming costs is worth more than selling it.
- The accretive sales are the best assets. Selling CNBC or GolfNow at those prices adds a great deal per share — and leaves a shrinking group of entertainment networks with the debt. The arithmetic of a buyback funded that way flatters the next year and weakens the company that remains.
- A merger of the entertainment networks into a consolidator — the way Hearst consolidated A+E — could share cost savings and fetch more than an outright sale. That is a 2028 conversation.
Three constraints stand in the way of any of it:
- The Tax Matters Agreement. For two years after the January 2, 2026 distribution, Versant may not “dispose of … any interest in … any Specified Cable Television Network”, nor sell assets outside the ordinary course except those on a schedule that is not public — unless the IRS rules the sale harmless or Comcast accepts a tax opinion “in its sole discretion”. SportsEngine was sold inside the window, so it was presumably on that schedule. The earliest sale of a network is January 2028.
- Control. The Class B shares, held by Comcast’s chairman, carry a third of the vote. Selling a network does not need a shareholder vote, but any break-up of the company meets that veto.
- The Fandango partner would need to agree to any sale of Fandango.
The sum of the parts is therefore a floor and a 2028 option, not a 2026 target. It is not used in the $41 target.
October recommendation
Rating: ACCUMULATE → HOLD. Target: $42 → $41. Grade: B (2.75), unchanged.
What changed. The October 5 upgrade rested on the market pricing a decline “several times” Versant’s actual rate. Built line by line, with costs that fall more slowly than revenue, the base case declines about as fast as the market assumes. The stock is no longer obviously mispriced in the middle case; it is priced for the middle case.
Why HOLD rather than SELL.
- The downside has a floor that cash flow alone does not show. At $31.44 the shares trade at the low-case after-tax break-up value of about $32, with a 25%-plus free cash flow yield in 2026 and a dividend that uses under a fifth of it.
- The upside is real. Slower subscriber losses, steadier advertising, programming costs that fall in line with revenue and faster Platforms growth together give a best case worth $79.
- The worst case is survivable. With a restructuring, free cash flow after interest stabilizes at $400–480 million a year, about twice the $205 million dividend.
Why HOLD rather than ACCUMULATE.
- The median outcome is the current price. The base case is worth $33 a share, and the expected value relies on the best case.
- The biggest unknowns resolve within four weeks. The third-quarter results in early November show whether the $191 million gap between the cash-flow build and guidance is a one-time item, and whether programming costs are falling with revenue.
- The break-up value cannot be realized before January 2028, and then only with the Class B holder’s consent.
Action for October:
| Holders | Hold. Do not add before the third-quarter results |
| Accumulate below $28 | The base case alone is then worth about 18% more, and the price is about 12% under the low-case break-up value |
| Trim above $41 | The target; beyond it the price assumes the best case |
| Move to SELL | Full-year free cash flow below the $1.0 billion low end of guidance and distribution revenue falling faster than 8% — the worst-case path, worth about $18 |
| Move back to ACCUMULATE | Core revenue declining under 3% and programming costs falling at least as fast as linear revenue, for two quarters |
What to watch in the third-quarter results (early November):
| Line | The test |
|---|---|
| Distribution revenue | −6% to −7% is the base case; worse than −8% is the worst case’s subscriber path |
| Advertising | Against Goldman Sachs’ −5%; the midterms should help the fourth quarter |
| Programming and production costs | Falling at least 80% as fast as linear revenue — the largest cost lever |
| Free cash flow | Year-to-date against the maintained $1.0–1.2 billion, and an explanation of the second-half gap |
| Platforms | About 9–10% growth excluding SportsEngine, plus Full Swing’s first contribution |
| Capital allocation | The second $100 million buyback completed, and the split from here between buybacks and debt. A buyback pace of $400 million a year with no debt repayment points to refinancing in 2031 in all but the best case; term loan B repayment from January 2027 is the sign to look for |
Update — October 5, 2026: ACCUMULATE, target $42 reaffirmed
Written against the October 5 close of $31.02. Sources: Versant’s second-quarter results (August 6) and 10-Q, its 2025 10-K, and its remarks at Goldman Sachs’ Communacopia conference on September 8 (transcript). The September 10 analysis below is left as published; this section corrects three of its figures and re-runs the valuation.
The one-line version
Versant fell 17% in four weeks without any news of its own, and the valuation holds at $42. At $31.02 the market is pricing free cash flow to fall 15.5% a year, forever, against revenue down 2.5% in the first half and guidance that was raised in August. The September 10 analysis said to accumulate below $33; the stock is below it.
Rating: HOLD → ACCUMULATE · Target $42 (reaffirmed) · Grade: B (2.75)
What moved the stock
Nothing Versant said or filed. The fall since September 10 lines up with two outside forces:
- Rates. The 10-year Treasury yield rose from 4.94% to 5.31% over the period (4.76% at the end of August). Small companies and high-yield credit lagged: the Russell 2000 fell about 1.5% and high-yield bonds about 2%, while the S&P 500 rose about 2.4%.
- Comcast. On September 9 Comcast’s CFO warned that broadband subscriber losses would not improve in the third quarter, blaming “irrational” fiber pricing (TheStreet). Comcast fell 19% from the end of August. This was a broadband warning, not a pay-TV one: Versant earns its distribution fees on video subscribers, and nothing in it changes their rate of decline. The read-across is sentiment.
Versant’s own news since September 10 is neutral to positive:
| Date | Event | Read |
|---|---|---|
| Sep 8 | Communacopia: guidance reiterated; advertising “quite healthy”, with “no signs of near-term weakness”; a second $100 million accelerated buyback in the third quarter; no major distribution or sports-rights renewal due before 2027, two-thirds not until 2028 or later | Positive |
| September | A multi-year renewal with Verizon Fios completes the 2026 renewal cycle: every distribution agreement due this year is renewed (Yahoo Finance) | Removes the near-term blackout risk |
| Sep 18 | Goldman Sachs cut its price target from $46 to $43, Neutral, on a lower third-quarter advertising estimate: $376 million, down 5%. It left EBITDA at $315 million, in line with consensus (Investing.com) | An estimate, not a disclosure |
| Oct 22 | Third quarterly dividend of $0.375 | Unchanged |
Corrections to the September 10 analysis
- The 2026 guidance quoted below is the pre-August range. On August 6, before the analysis was written, Versant raised its outlook: revenue $6.2–6.45 billion (the analysis says $6.15–6.40 billion) and adjusted EBITDA $1.9–2.05 billion, midpoint $1,975 million (the analysis uses $1,925 million). Free cash flow guidance of $1.0–1.2 billion was maintained, and is unchanged below.
- Debt was overstated by about $200 million. The analysis gives gross debt of $3.20 billion and net debt of $1.71 billion. The 10-Q shows $3.0 billion of principal ($2,954 million net of issuance costs) and $1,478 million of cash at June 30: net debt about $1.52 billion, and net leverage of about 0.77× the raised EBITDA midpoint, not 0.89×.
- The gap to target on September 10 was 12.4%, not 11.5% ($42 ÷ $37.36 − 1).
None of the three changes the rating or the target; all three, if anything, help the case. The share count used below is 139.2 million, which includes 0.4 million Class B shares the analysis omitted.
The debt, tranche by tranche
| Tranche | Principal | Interest rate | Maturity | Amortization |
|---|---|---|---|---|
| 7.250% Senior Secured Notes | $1,000M | 7.250% fixed | January 2031 | None; due at maturity |
| Term Loan A | $1,000M | SOFR + 1.75% (steps down with leverage) | January 2031 | 5% a year, quarterly from September 30, 2026 |
| Term Loan B | $1,000M | SOFR + 3.50% | January 2031 | 7% a year, quarterly from September 30, 2026 |
| Revolving credit facility | $750M, undrawn | SOFR + 1.75%; 0.25% fee on the unused amount | not stated in the filings reviewed | — |
| Total drawn | $3,000M |
- Interest-rate swaps of $1.0 billion convert part of the term loans to fixed; about 67% of the debt is fixed-rate including the swaps, 33% floating.
- Scheduled repayments are $60 million in 2026 and about $120 million a year in 2027–2030, leaving about $2.5 billion due in 2031, all of it in one year.
- Covenant: first-lien net leverage of no more than 3.50×, tested from the third quarter of 2026 (term loan A and the revolver). At about 0.8× there is ample room.
Interest rates and the term loans
Higher rates cost Versant little in cash. Both term loans float, but $1.0 billion of swaps entered in March fix part of them (the filings do not say which loan), leaving about $1.0 billion exposed. Versant’s own sensitivity in the 10-Q: a 1-point move in rates changes interest expense by about $3 million a quarter, $10–12 million a year.
| Rate move | Interest a year | Per share | Share of guided free cash flow |
|---|---|---|---|
| +0.5 point (about the 10-year’s rise since September 10) | ≈ $5–6M | ≈ $0.04 | ≈ 0.5% |
| +1 point | ≈ $10–12M | ≈ $0.08 | ≈ 1% |
| +2 points | ≈ $20–24M | ≈ $0.16 | ≈ 2% |
Total interest expense was $105 million in the first half, about $210 million a year, against guided free cash flow of $1.0–1.2 billion. Rates reach this stock through its valuation, not its cash flow.
Versant can pay the term loans down, and from January 2027 it becomes cheap to do so. The terms, from the credit agreements:
| Tranche | Voluntary prepayment | Cost of prepaying |
|---|---|---|
| Term Loan A (SOFR + 1.75%) | Any time | None |
| Term Loan B (SOFR + 3.50%) | Any time | Make-whole (Treasuries + 0.50%) before January 2, 2027; 1% from then to January 2, 2028; par after |
| 7.250% Senior Notes | Callable | Make-whole before January 30, 2028; up to 10% a year at 103% before then |
Term loan B also has a mandatory excess-cash-flow sweep, and the two term loans amortize about $120 million a year from this quarter.
It has the means. Cash was $1,478 million at June 30, and guided free cash flow of $1.0–1.2 billion a year comfortably covers the dividend (about $210 million) and a buyback running near $100 million a quarter.
Where the cash should go is the real question:
- Term loan B is the expensive debt. At SOFR plus 3.50% it costs roughly 8% before tax, against perhaps 4% earned on cash. Repaying $1 billion would save on the order of $35–45 million a year before tax, and the 1% premium from January 2027, about $10 million, is earned back in three to four months.
- Term loan A is cheap to repay and cheap to keep. At SOFR plus 1.75%, little is gained by prepaying it.
- At $31, buying back stock is the higher return, if the valuation above is right: a 25% free cash flow yield against about 8% saved on term loan B.
- But deleveraging is the defensive answer to a declining business. About $2.5 billion falls due in a single year, 2031. A shrinking company with one large maturity is the pattern that hurt AMC Networks, and paying down term loan B from 2027 is the cleanest way to shrink that wall.
- Management’s stated direction is the other way. Its net leverage target is 1.25×, against about 0.8× today, which leaves room to add debt for buybacks or acquisitions rather than a stated plan to reduce it.
The mix we would want to see: buybacks while the shares sit below the $33 line, and term loan B repaid from January 2027. The third- and fourth-quarter results are the first chance to see which way the cash goes.
The valuation, re-run
The method is unchanged; the inputs are corrected and struck at $31.02.
| Input | September 10 | October 5 |
|---|---|---|
| Share price | $37.36 | $31.02 |
| Shares | 138.8M | 139.2M |
| Market capitalization | $5.19B | $4.32B |
| Net debt | $1.71B | $1.52B (corrected) |
| Enterprise value | $6.90B | $5.84B |
| 2026 adjusted EBITDA, guided midpoint | $1,925M | $1,975M (corrected) |
| EV / EBITDA | 3.6× | 3.0× |
| 2026 free cash flow, guided midpoint | $1.1B | $1.1B (unchanged) |
| Free cash flow yield | 21% | 25.5% |
| Market-implied perpetual decline in free cash flow, at a 10% discount rate | −11% a year | −15.5% a year |
The market now prices a decline half again as steep as it did a month ago, and no new fact supports it. Free cash flow per share is about $7.90 at the guided midpoint, and the $1.50 annual dividend uses less than a fifth of it.
| Method | Value per share | Weight |
|---|---|---|
| Reverse DCF at −8% perpetual decline (10% discount rate) | $44 | 40% |
| Reverse DCF at −11% perpetual decline (10% discount rate) | $38 | 20% |
| Earnings at 7.5× normalized $5.48 | $41 | 25% |
| EV/EBITDA at 4.0× the corrected 2026 guided midpoint, less corrected net debt | $46 | 15% |
| Weighted target | $42 (42.24) |
Reaffirmed at $42, 35% above $31.02. The two discounted cash flow methods give almost exactly what they did; the EV/EBITDA method rises from $43 to $46 on the corrected EBITDA and net debt.
On rates. The 10% discount rate already carries a wide premium for a BB-rated, declining business. Even raised to reflect the higher Treasury yields, the target barely moves:
| Discount rate | −8% case | −11% case | Weighted target |
|---|---|---|---|
| 10% (base) | $44 | $38 | $42 |
| 10.5% | $43 | $37 | $42 (41.59) |
| 11% | $42 | $36 | $41 (40.97) |
Rating
HOLD → ACCUMULATE. Target $42, reaffirmed. The September 10 analysis set the line at $33, “where the implied decline rate exceeds 14% and the free cash flow yield passes 24%”. At $31.02 both are passed: 15.5% and 25.5%.
ACCUMULATE, not BUY, because the risks that kept the rating at HOLD are unchanged: a business in structural decline, a Class B vote with a merger veto and no minority recourse, and a single $2.5 billion maturity in 2031. The case is the same as it was: the market prices the decline at several times its current rate, and being right requires only that it stay ordinary.
What to watch in the third-quarter results (early November)
| Line | The test |
|---|---|
| Distribution revenue | Down about 6%, as in the second quarter. Worse means subscriber losses are accelerating |
| Advertising | Against Goldman’s −5%. Management called the market healthy on September 8 |
| Free cash flow | On track for the maintained $1.0–1.2 billion |
| Buybacks | Completion of the second $100 million accelerated repurchase, and the pace beyond it at prices near $31 |
| Platforms | The 9% underlying growth management cited, and early results from the MS NOW and CNBC streaming launches |
Post-Spin Analysis — September 10, 2026
Written against the September 10 close of $37.36. Primary sources: Versant’s Form 10-K for the year ended December 31, 2025 (filed 2026-03-03) and its Form 10-Q for the quarter ended June 30, 2026 (filed 2026-08-06), with the separation terms from the Form 10 registration statement as amended through December 2025. Price, volume and float figures are computed from this site’s own daily archive.
The one-line version
Versant is a declining business that is not declining as fast as its price implies, attached to a capital structure built by someone else. Revenue has fallen at about 5% a year for three years and slowed to −2.5% in the first half of 2026, while the shares are priced for an indefinite decline of roughly 11% a year. The gap between those two numbers is the entire investment case.
The objection is not the cable networks, which everyone can see. It is that Comcast took roughly $8.5 billion of cash out of this business in three and a half years while spending about six cents of capital expenditure per dollar of depreciation — and then attached $3.2 billion of BB-rated debt to it on the way out. What you are buying is a cash machine that has been run for cash, by a seller, for a long time.
Rating: HOLD · Target $42 · Grade: B (2.75)
What the business actually is
Two businesses with opposite trajectories, reported together.
| What it is | Direction | |
|---|---|---|
| Cable Networks | MS NOW (formerly MSNBC), CNBC, USA Network, Syfy, E!, Oxygen, Golf Channel | Secular decline. The pay-TV subscriber base shrinks every year and carriage fees follow it |
| Platforms | Fandango, Rotten Tomatoes, GolfNow, GolfPass, SportsEngine, and Full Swing (acquired 2026) | Growing. Revenue up 4% to $826 million in 2025 |
The company reports that its brands reached more than 120 million viewers a month as of the second quarter of 2026. That figure is a reach statistic, not a revenue statistic, and the two have been diverging for a decade.
The number that actually matters is the mix: non-pay-TV revenue grew from 17% to 19% of the total during 2025, and management has said it is targeting 33% within three to five years. At $826 million of Platforms revenue against $6.69 billion of total revenue, reaching a third of the business means either roughly tripling Platforms or shrinking Networks by half. Management is explicit that it intends the former. The arithmetic permits the latter.
Management Team
Thirteen named officers, and the striking thing is how few of them are new. This is the NBCUniversal cable leadership bench, moved across intact.
| Officer | Role |
|---|---|
| Mark Lazarus | Chief Executive Officer |
| Anand Kini | Chief Financial Officer & Chief Operating Officer |
| Val Boreland | President, Entertainment |
| Roy Cho | President, Distribution & Partnerships |
| Matt Hong | President, USA Sports |
| Rebecca Kutler | President, MS NOW |
| KC Sullivan | President, CNBC |
| Will McIntosh | President, Digital Platforms and Ventures |
| Jeff Mayzurk | President, Operations & Technology |
| David Pietrycha | Chief Revenue and Business Officer |
| Jordan Fasbender | General Counsel & Corporate Secretary |
| Keith Cocozza | Chief Communications Officer |
| Brian Dorfler | Chief Human Resources Officer |
The distinction that matters is operator versus caretaker, and this reads as operator. Every network has its own named president — CNBC, MS NOW, Entertainment, USA Sports — which is how the assets were run inside NBCUniversal, not a structure assembled to shepherd a disposal. Distribution & Partnerships exists as its own presidency, which is the correct emphasis for a company whose revenue is decided in carriage negotiations.
Two roles are worth noting. Anand Kini holds both CFO and COO, which concentrates the financial and operating decisions in one person at a company whose central problem is managing decline — efficient, and a key-person dependency. And Will McIntosh’s Digital Platforms and Ventures presidency is the seat the entire re-rating case depends on: Platforms is what has to reach a third of revenue.
The board, and the fact that changes the analysis
Ten directors, all seated effective 11:59 p.m. on January 2, 2026, from the separation 8-K’s Item 5.02.
| Director | Role |
|---|---|
| David Novak | Chair · Compensation Committee |
| Mark Lazarus | Director · Chief Executive Officer |
| Maritza Montiel | Audit Committee Chair (continuing director) |
| Gerald Hassell | Compensation Committee Chair |
| Creighton Cordon | Governance Committee Chair |
| Rebecca Campbell | Audit Committee |
| Leonard Potter | Audit Committee |
| Michael Conway | Compensation Committee |
| David Eun | Governance Committee |
| Scott Mahoney | Governance Committee |
The notable thing is who is absent. Brian Roberts is not on this board, and neither is any other Comcast executive. The chair is independent, all three committees are chaired by directors other than the CEO, and the only management seat is Lazarus’s. On every conventional governance screen this is a well-constituted board.
Which is precisely why the Class B matters more than it appears to. Control here is not exercised through board seats, where it would be visible and contestable. It sits in the charter, where a 33⅓% voting block and a merger veto operate regardless of who the directors are or how independent they look. A reader checking governance by counting independent directors would conclude the opposite of the truth.
The filings say so directly:
“Our Class B common stock has substantial voting rights and separate approval rights over certain potentially material transactions, and Brian L. Roberts, the Chairman and CEO of Comcast, has considerable influence over Versant through his beneficial ownership of our Class B common stock.” — Versant Form 10-K, year ended December 31, 2025
Versant is a controlled company, and the control did not stay with Comcast — it stayed with Brian Roberts personally. The amended articles of incorporation, filed with the January 5, 2026 separation 8-K, set the mechanics out precisely, and they are more severe than the conventional dual-class arrangement:
| Class A outstanding | 143,790,841 shares |
| Class B outstanding | 377,775 shares — 0.26% of the economics |
| Class B votes per share | fifteen (15) |
| Class B aggregate voting power | fixed at 33⅓% of all votes cast |
| Class A votes per share | the residual — computed so that Class B always reaches its 33⅓% |
That third row is the one that matters, and it is not the usual 10-to-1. The charter does not merely give Class B extra votes; it fixes Class B’s share of the vote at one third by construction, with Class A’s per-share vote defined as whatever quotient makes that true. Issuing Class A stock dilutes economics without diluting control.
Class B also holds a separate class vote over, among other things, “mergers, consolidations, or transactions resulting in any person or group owning more than 10% of combined voting power” and any amendment limiting Class B rights. That is a categorical veto over a change of control, held by one person.
This is the Comcast governance structure reproduced in the spinoff. It is disclosed, it is legal, and it is easy to miss because every conventional ownership screen reports Versant as 99.2% float with 0.2% insider holding — which is true of the economics and irrelevant to the control.
The financial record — three years, and what the separation costs
From the Form 10-K. All figures in millions of dollars.
| 2023 | 2024 | 2025 | |
|---|---|---|---|
| Revenue | 7,445 | 7,062 | 6,688 |
| Costs of revenue | 3,154 | 3,064 | 2,937 |
| Selling, general and administrative | 1,231 | 1,167 | 1,469 |
| Depreciation and amortization | 991 | 989 | 1,010 |
| Operating income | 2,069 | 1,841 | 1,272 |
| Operating margin | 27.8% | 26.1% | 19.0% |
| EBITDA (operating income + D&A) | 3,060 | 2,830 | 2,282 |
| EBITDA margin | 41.1% | 40.1% | 34.1% |
| Interest expense | — | — | (13) |
| Net income | 1,540 | 1,365 | 931 |
Revenue is declining steadily. Earnings are declining much faster, and in 2025 the gap was mostly self-inflicted. Revenue fell 5.1% then 5.3%. Operating income fell 11.0% then 30.9% — apparent downside operating leverage of about 5.8 times in 2025.
That number overstates the operating reality, and the line that explains it is SG&A, which rose $302 million in a year revenue fell $374 million. Costs of revenue behaved normally, falling 4.1% against revenue’s 5.3%. Strip the SG&A increase and operating income would have declined about 14.5%, or roughly 2.7 times the revenue decline — still high, but a different animal. The 2025 margin compression is substantially the cost of becoming a company rather than the cost of losing subscribers.
⚠️ Interest expense of $13 million is the most misleading figure in the table, and it is misleading in the direction that flatters. Versant’s 2023 and 2024 statements are carve-out financials: the business carried none of the debt it now carries. The $3.2 billion of gross debt was raised around the separation, so 2025 captures only weeks of it. A full year of that debt at BB-rated coupons is plausibly $210–250 million of interest — against 2025 net income of $931 million, that is roughly a fifth of earnings arriving as a new, permanent cost that no year in the table above reflects. A spinoff’s pre-separation accounts carry none of the debt it takes on at the spin, and Versant is a clean example of it.
The first half of 2026, which is the first evidence of the standalone company:
| H1 2025 | H1 2026 | Change | |
|---|---|---|---|
| Revenue | 3,415 | 3,331 | −2.5% |
| Net income | 670 | 497 | −25.8% |
| D&A | 489 | 514 | +5.1% |
| Capital expenditure | 63 | 59 | −6.3% |
The revenue decline halved. From −5.3% across 2025 to −2.5% in the first half of 2026, with the second quarter at −3.7%. Annualised, first-half revenue runs at about $6.66 billion against management’s full-year guidance of $6.15–6.40 billion — the company is tracking ahead of its own guidance on the top line.
Earnings kept falling anyway, and the reason is the previous paragraph: interest and standalone costs now land in full.
The cash Comcast took, which is the real story
This is the section that changed my view of the company, and it comes straight from the cash flow statement.
| 2023 | 2024 | 2025 | H1 2026 | |
|---|---|---|---|---|
| Net cash from operations | 2,428 | 2,211 | 2,022 | — |
| Capital expenditure | (56) | (54) | (167) | (59) |
| Capex as % of D&A | 5.7% | 5.5% | 16.5% | 11.5% |
| Net transfers to Comcast | (2,359) | (2,142) | (1,745) | (2,250) |
Comcast took approximately $8.5 billion out of this business in three and a half years. Over the same period the business spent $336 million of capital expenditure against $3,504 million of depreciation and amortization — under ten cents of investment per dollar of consumption, and under six cents in 2023 and 2024.
There are two readings and they are not mutually exclusive.
The benign one: these are content and carriage businesses whose D&A is substantially amortization of acquired intangibles and content rights, not machinery that wears out. Low capex against that kind of D&A is normal and not evidence of starvation.
The uncomfortable one: a business run at 5% capex-to-D&A for years by an owner who had already decided to sell it is not a business that has been prepared for independence. The Platforms assets — Fandango, GolfNow, SportsEngine — are the growth engine the entire equity story depends on, and they were funded out of that same $54 million. The 2025 and 2026 step-up in capex, and the $199 million spent acquiring Full Swing in the first half of 2026, are the first evidence of a different policy. Two quarters is not a record.
The $2.25 billion transfer in the first half of 2026 is the separation consideration itself: Versant raised the debt and handed the proceeds to Comcast, retaining roughly $500 million. That is a disclosed, ordinary feature of a leveraged spin. It is included above because a reader looking at “cash taken by the parent” should see all of it in one place.
Price and volume: a violent debut that resolved quickly
The separation terms were 1 Versant share for every 25 Comcast shares, with regular-way trading opening January 5, 2026.
| When-issued (Dec 15, 2025) | $55.00 |
| Opening print | $45.17 |
| Day-1 close | $40.57 |
| Day-1 range | $39.28 – $45.65 (a 16.2% spread) |
| Day-1 low held? | No — broken on the very next session |
| Deepest breach of the day-1 low | −30.8% |
| Post-spin low | $27.42 on February 12, 2026 — day 38 |
| Current (Sep 10, 2026) | $37.36 |
The when-issued market said $55 and the regular-way market said $40.57 within three weeks. That is a 26% repricing between the two populations of holders, and it is the cleanest illustration in this cohort of what when-issued prices are worth.
The volume data says the forced selling was violent and brief.
| Day-1 volume against the name’s own baseline | 19.2× |
| First-week average | 9.2× |
| Sessions until volume halved from day 1 | 2 |
| Sessions until volume returned to within 1.5× baseline | 20 |
| Volume today against baseline | 0.66× |
Twenty sessions from spin to normal, with the half-life at two. The selling pressure was over well before the February 12 price low — which means the low was not made by forced selling. By day 38 the index funds and the mandate-constrained holders were long gone; what took the stock from roughly $33 to $27.42 was people who had decided.
That distinction matters for anyone treating spin drawdowns as mechanical. It also cuts the other way: volume at 0.66× baseline today is a third below the name’s own normal, which is interest draining away rather than a coiled spring. At about $55 million of daily dollar volume, liquidity is a constraint on position size for a large holder, not a reason to avoid the name.
The recovery has been real but incomplete: +36.3% off the low, still −6.1% against the day-1 close, against an S&P 500 that returned +13.1% over the same window. Versant has underperformed the index by roughly 19 points since separation.
The interval record, from this site’s archive:
| D1 | D10 | M1 | M2 | M3 | M6 | |
|---|---|---|---|---|---|---|
| Price return | −10.6% | −19.5% | −24.9% | −9.5% | −7.7% | −6.5% |
| Total return | −10.6% | −19.5% | −24.9% | −9.5% | −6.8% | −4.6% |
| Income contribution | — | — | — | — | 0.9pp | 1.9pp |
The trough is at one month, not at one day. And by six months the dividend is already contributing 1.9 points — on a name yielding roughly 4%, income becomes a material part of the return quickly.
Capital allocation
The standalone record is eight months long, so this is a statement of policy rather than a track record.
Declared within sixty days of independence: a $0.375 quarterly dividend (roughly a 4.0% yield at $37.36) and a $1 billion buyback authorisation — about 19% of the current market capitalization. Executed by June 30, 2026: $200 million of repurchases and $53 million of dividends.
Bought: Full Swing for $199 million. Sold: businesses generating $140 million of proceeds. Net, about $59 million of portfolio reshaping toward Platforms.
That is a coherent posture for a declining business: return most of the cash, buy back stock while it is cheap, and redirect a modest amount of capital toward the growing segment. The buyback at these prices is accretive in a way it would not be at 10× earnings. The thing to watch is whether the buyback continues if the price recovers — a management team that buys stock at $27 and keeps buying at $50 is telling you it has nothing better to do with the money.
Valuation
The reverse discounted cash flow
I have run this backwards rather than forwards, because the forward version requires a terminal decline rate that is the entire question.
Assumptions, all stated:
- Shares outstanding 138.8 million at $37.36 → market capitalization $5.19 billion
- Gross debt $3.20 billion, cash $1.48 billion, net debt $1.71 billion — materially more leverage than the $2.75 billion headline separation financing implies, because borrowing continued after the spin ($986M drawn in 2025 and a further $1,973M in the first half of 2026)
- Enterprise value ≈ $6.90 billion
- 2026 guided free cash flow $1.0–1.2 billion, midpoint $1.1 billion
- Discount rate 10%, appropriate for a BB-rated, levered, declining business
At a $1.1 billion free cash flow midpoint against a $5.19 billion equity value, the market is paying a 21% free cash flow yield. Solved as a declining perpetuity at a 10% discount rate, that implies the market expects free cash flow to decline about 11% a year, forever.
Sensitivity on the load-bearing assumption — the perpetual decline rate:
| Perpetual FCF decline | Implied equity value | Per share | vs $37.36 |
|---|---|---|---|
| −15% | $4.4B | $31.70 | −15% |
| −11% | $5.2B | $37.36 | market |
| −8% | $6.1B | $44.03 | +18% |
| −5% | $7.3B | $52.84 | +41% |
| −3% | $8.5B | $60.97 | +63% |
| 0% | $11.0B | $79.26 | +112% |
About $2 a share for each percentage point of perpetual decline rate, in the region that matters.
Set against that: revenue declined 5.3% in 2025 and 2.5% in the first half of 2026. If free cash flow declines at the rate revenue does, the shares are worth something in the $45–55 range. The market’s −11% requires the decline to roughly double from here and never stop.
The honest counter, and it is a real one. Free cash flow does not have to decline at the revenue rate. Carriage renewals are step functions, not glide paths — a single lost distribution agreement can take several points of revenue at once and nearly all of it falls to the bottom line. Interest expense is fixed and rising as a share of a shrinking base. And the perpetuity model is generous to a business whose assets amortise: at 6% capex-to-D&A, the maintenance requirement is being deferred, not avoided.
Earnings-based cross-check
2025 net income of $931 million against 138.8 million shares is $6.71 of earnings per share, or 5.6×. Adjust for a full year of interest on $3.2 billion — roughly $224 million pre-tax, $170 million after tax at the 2025 effective rate of 24.2% — and normalized standalone EPS is about $5.48, or 6.8×.
Even at $5.48, a 6.8× multiple on a business whose revenue is declining 2.5% is the market pricing terminal decline rather than managed decline.
Price target
| Method | Value | Weight |
|---|---|---|
| Reverse DCF at −8% perpetual decline | $44 | 40% |
| Reverse DCF at −11% (market-implied) | $37 | 20% |
| Earnings at 7.5× normalized $5.48 | $41 | 25% |
| EV/EBITDA at 4.0× 2026 guided midpoint, less net debt | $43 | 15% |
| Weighted target | $42 |
$42 is 11.5% above the current price. That is not enough to make this a BUY at $37.36, which is the whole reason the rating below is what it is.
What this most resembles
Eight media and entertainment separations from this site’s own universe, all measured on the same basis — day-1 close to the September 10, 2026 close. Each name links to its own profile.
| SpinCo | Parent | Spun | vs Day 1 | CAGR | vs S&P (ann.) | Day-1 volume |
|---|---|---|---|---|---|---|
| Versant | Comcast | Jan 2026 | −6.1% | — | — | 19.2× |
| AMC Networks | Cablevision | Jul 2011 | −69.7% | −7.6% | −21.9pp | 16.2× |
| USA Today Co | Tegna | Jun 2015 | −27.3% | −2.8% | −17.3pp | 1.2× |
| Sirius XM | Starz | Sep 2024 | +13.4% | +6.5% | −13.7pp | 3.1× |
| Warner Bros. Discovery | AT&T | Apr 2022 | +13.8% | +3.0% | −12.3pp | 3.1× |
| Fox Corp | 21st Century Fox | Mar 2019 | +73.0% | +7.6% | −8.5pp | 2.9× |
| News Corp | 21st Century Fox | Jul 2013 | +114.2% | +5.9% | −8.7pp | 5.8× |
| MSG Entertainment | Sphere | Apr 2023 | +144.4% | +30.2% | +8.2pp | 2.9× |
| Starz Entertainment | Lionsgate | May 2025 | +126.1% | +83.5% | +55.1pp | 17.5× |
Only one of these eight beat the S&P 500 on an annualized basis, and it is the one that owns arenas rather than networks. Every pure content or distribution business in the table underperformed the index, several of them severely, and that is the base rate Versant is being measured against.
AMC Networks is the case that matters. A cable-networks pure-play spun from a distributor, left with the linear assets while the parent kept the growth — the same structure, fifteen years earlier. It is down 69.7% and has compounded at −7.6% while trailing the index by 21.9 points a year. If Versant is AMC Networks, the market’s −11% implied decline rate is not pessimistic; it is roughly right.
The rebuttal is the volume column. Versant’s day-1 volume was 19.2× its own baseline — the highest in this table, with AMC Networks at 16.2× and Starz at 17.5×. Those three names went to −69.7%, +126.1% and −6.1% respectively. Spike magnitude tells you how violent the handover was, and nothing whatever about where the stock goes. Anyone reading a large day-1 dislocation as a signal should look at that row twice.
Against the 2026 separations by float, Versant is about as cleanly distributed as a spin gets: 99.2% float, 89.0% institutional, no retained parent stake, no election. That reading now needs the qualification set out in the Management section — clean economically, controlled through the Class B.
In depth: competitive dynamics
The cable networks compete for a shrinking pool of carriage fees against Warner Bros. Discovery’s networks, Paramount’s, and Disney’s linear portfolio — all of which face the same subscriber arithmetic and all of which have been separated, written down, or put up for sale in the last three years. The competitive question in linear television is not share, it is exit order. Being a pure-play here means no diversified parent absorbing the decline, and also no parent cross-subsidising a competitor’s bid for the same rights.
CNBC and MS NOW are the more defensible half. News viewership is older, stickier and less substitutable by streaming than entertainment, and both carry brand equity that survives the distribution pipe. Golf Channel plus GolfNow, GolfPass and Full Swing is a genuinely integrated vertical — content, tee times, instruction and simulators around one sport — and is the clearest example of what management means by Platforms.
Fandango and Rotten Tomatoes compete with Google and the studios’ own direct channels for the moviegoing transaction. They are good businesses with a weak structural position: they sit between a consumer and a studio, either of whom can route around them.
In depth: valuation against peers
Computed from the filings, not taken from a screen. Share counts are from each company’s latest cover page and include every class; prices are the September 10, 2026 closes from this site’s archive; debt and cash are from the most recent balance sheet; earnings are as stated below. The basis for each line is given because the three companies do not share a fiscal calendar.
| Shares (all classes) | Market cap | Net debt | Enterprise value | EBITDA | EV/EBITDA | Net debt/EBITDA | |
|---|---|---|---|---|---|---|---|
| Versant | 138.8M | $5,185M | $1,722M | $6,907M | $1,925M | 3.6× | 0.89× |
| AMC Networks | 41.2M | $498M | $1,197M | $1,695M | $171M | 9.9× | 7.00× |
| Fox Corp | 419.7M | $25,785M | $2,401M | $28,186M | $3,906M | 7.2× | 0.61× |
Versant: 10-K FY2025 and 10-Q Q2 2026; EBITDA is the 2026 guided midpoint. AMC Networks: 10-Q for the quarter ended June 30, 2026 (Class A 29,765,563 + Class B 11,484,408; cash $464.0M, long-term debt $1,661.0M); EBITDA is H1 2026 operating income plus D&A, annualized. Fox: FY2026 10-K, year ended June 30, 2026 (Class A 199,401,385 at $65.18 + Class B 220,248,764 at $58.06; cash $4,205M, borrowings $6,606M); EBITDA is revenue $17,126M less operating expenses $10,853M less SG&A $2,367M, plus back D&A $410M.
| Revenue growth | Earnings | P/E | |
|---|---|---|---|
| Versant | −2.5% (H1 2026) | $6.71 FY2025 · $5.48 normalized | 5.6× · 6.8× |
| AMC Networks | −5.7% (H1 2026) | operating income −63% YoY | n/m |
| Fox Corp | +5.1% (FY2026) | $3.91 basic FY2026 | 16.7× |
Versant trades at half Fox’s EV/EBITDA while carrying comparable leverage. 0.89× against 0.61× — both modest, both a world away from AMC Networks at 7.00×. The difference between Versant and Fox is business quality, and it is real: Fox grew 5.1% last fiscal year and Versant is shrinking 2.5%. The question the price is asking is whether a 7.6-point swing in growth rate is worth a 50% discount on the multiple and a 67% discount on earnings.
The leverage column is the one that decides which of the two comparisons is apt. Versant’s balance sheet looks like Fox’s, not AMC’s. That is not a detail: AMC Networks’ equity is a stub because three-quarters of its enterprise value belongs to lenders, and no operational recovery reaches the shareholder first. Versant’s lenders have a claim on 25% of the enterprise. Whatever happens to the business, the equity holder is still the residual claimant on most of it.
The AMC Networks comparison is the one that matters, and it inverts
The obvious reading is that Versant at 3.6× is cheap against AMC Networks at 9.9×. That reading is wrong, and the reason is the denominator.
| AMC Networks | H1 2025 | H1 2026 |
|---|---|---|
| Revenue | $1,155.3M | $1,089.6M |
| Operating income | $128.7M | $47.1M |
| Operating income + D&A | $176.1M | $85.3M |
| Implied EV/EBITDA at today’s price | 4.8× | 9.9× |
AMC Networks’ EBITDA halved in twelve months — down 52% — and its multiple doubled without the share price doing anything helpful. A year ago AMC Networks screened at 4.8×, which is almost exactly where Versant screens today.
That is the bear case stated properly. The objection to Versant is not that 3.6× is a fair multiple for a declining business. It is that a cable-networks pure-play trading at 4.8× is not cheap if EBITDA can halve in a year, and AMC Networks has just demonstrated that it can. A low multiple on a collapsing denominator is not a margin of safety.
Two things separate Versant from that outcome, and they are the whole investment case. Versant’s revenue decline is slowing (−5.3% in 2025 to −2.5% in H1 2026) where AMC’s operating income fell off a cliff. And Versant’s capital structure is survivable: net debt of $1,722M against guided EBITDA of $1,925M is 0.89×, where AMC Networks carries $1,197M of net debt against $171M of annualized EBITDA — 7.0×, which is why nearly three-quarters of AMC’s enterprise value belongs to its lenders and its equity is a stub.
Versant is the same business at an earlier point on the same path, with fifteen years of runway AMC no longer has. Whether that is an opportunity or a delay is the question the price is asking.
In depth: is Versant an acquisition target?
No — and the reason is stronger than the §355(e) clock.
The clock is real: the separation was a tax-free distribution under §355, so an acquisition of Versant before January 5, 2028 risks retroactively taxing the separation to Comcast. §355(e) also binds Versant as an acquirer, which constrains any large stock-funded roll-up of its own for the next sixteen months.
But the clock expires and the Class B does not. Brian Roberts holds supervoting stock with separate approval rights over certain potentially material transactions — a veto, held personally, by the chairman and chief executive of the company that spun Versant off. A hostile bid is not available, and a friendly one requires his agreement. Any acquisition thesis here is a thesis about what one individual wants.
That is a genuine markdown to the case I would otherwise make, because the financial logic is excellent:
Private equity is the natural owner on paper. A business generating $1.0–1.2 billion of free cash flow at a 21% yield with BB debt already in place is a textbook leveraged buyout, and a predictable decline rate is a feature in that model. The obstacle is not financing or price; it is the veto.
A strategic consolidator — a combination with another orphaned linear portfolio — offers real cost synergy and no revenue synergy, and the regulatory path is easier than it once was precisely because the category is shrinking. Same obstacle.
A break-up is the live one, and it is the only route that does not require a change of control. Platforms at $826 million of growing revenue would attract a different and better-paying buyer than the networks. Selling or separating Platforms is a transaction management can execute, and the first half of 2026 shows them already trading the portfolio in both directions — $199 million spent on Full Swing, $140 million received from disposals.
What this means for the score: Acquisition Potential comes down. The arithmetic is attractive and the control structure means the arithmetic may never be tested.
Tail scenarios
Upside tails
A carriage renewal at flat rates (2σ). The bear case assumes each renewal takes a step down. One major distributor renewing flat, publicly, would reset the market’s decline assumption directly — and the sensitivity table says every point off the decline rate is about $2 a share. Worth $8–12 a share if it moves the implied rate from −11% to −6%.
Platforms reaching the 33% target early (2σ). If Platforms compounds toward a third of revenue faster than the three-to-five-year plan, the terminal value argument changes in kind rather than degree — a business that is one-third growing digital assets does not get valued as a declining perpetuity. Worth $15–25 a share, and it is the only path to a genuine re-rating.
A buyout at a private-market multiple (2σ). Legally blocked until January 2028 but not unthinkable thereafter. Precedent leveraged buyouts of cash-generative declining assets clear at 5–6× EBITDA, which against $1.9 billion implies $55–70 a share.
Downside tails
A major distributor drops the networks (2σ). The step-function risk. A single large carriage loss could take 5–8% of revenue at once, almost entirely at margin, and would validate the −11% decline assumption in a single announcement. Worth −$8 to −$12 a share.
Leverage becomes binding (2–3σ). At BB, with roughly $1.71 billion of net debt against declining EBITDA, the covenant arithmetic tightens every year the business shrinks. It is comfortable today at 0.89× net leverage on guided EBITDA. It becomes uncomfortable if EBITDA halves, which at −11% a year takes six years. The debt is not the near-term risk; it is the reason the terminal value is not zero-risk.
The buyback is the wrong use of the cash (2σ). Retiring 19% of the equity in a business that then declines faster than expected converts a valuation error into a permanent capital loss. This is the tail that management controls.
What would change this view
Better:
- Two consecutive quarters of revenue decline under 2%, which would put the realized rate at less than a fifth of the implied one
- Platforms revenue growth accelerating above 8%, or a Platforms segment disclosure that lets the two businesses be valued separately
- A carriage renewal disclosed at flat or better
Worse:
- Revenue decline re-accelerating above 5%, reversing the 2026 improvement
- Capex staying at 6% of D&A once the separation-year step-up laps — that would confirm harvesting rather than investment
- Any covenant amendment
Dated:
- Q3 2026 results, early November 2026 — the first quarter with a full standalone cost base and a full quarter of interest. This is the print that shows the real earnings power, and it is the single most important scheduled event for this name.
- January 5, 2028 — the §355(e) window closes and the acquisition case becomes live.
- Comcast’s NBCUniversal separation — Versant is the market’s read-across, and the causality runs both ways once the larger entity trades.
Thesis-breaking:
- Free cash flow falling below $800 million on a full-year basis, which would mean the market’s decline assumption was right and the valuation support goes with it
- The dividend being cut, which in a business held for cash returns would re-rate the equity downward regardless of the operating reason
Investment Scorecard
| Dimension | Weight | Score | Rationale |
|---|---|---|---|
| Financial Profile | 25% | 3.0 | $2.0B of operating cash flow and a 21% free cash flow yield, against a three-year record of revenue −5%/yr and operating income −11% then −31%. Held at 3.0 because the 2025 earnings decline is substantially a one-time separation cost — and because no year in the audited record carries a full year of the interest the company now pays on $3.2B |
| Competitive Position | 25% | 2.0 | A structurally declining category where the competitive question is exit order rather than share. CNBC and MS NOW are defensible; Fandango and Rotten Tomatoes sit between a consumer and a studio, either of whom can route around them. The golf vertical is the one genuinely integrated position |
| Strategic Rationale | 20% | 3.5 | A clean, complete, 99.2%-float separation with no retained economic stake and no election — and a coherent one: Comcast’s remaining media assets are priced separately now. Marked down because the rationale was the parent’s, and the parent took $8.5B out on the way |
| Management & Governance | 20% | 3.0 | Now earned rather than carried. Thirteen named officers, every network with its own president — the operating bench moved across intact, not a caretaker team assembled for a disposal. Offset by the Class B: Brian Roberts holds 0.26% of the economics with supervoting rights and a veto over material transactions, and minority holders have no governance recourse. A credit and a debit that net out |
| Acquisition Potential | 10% | 2.0 ⬇️ | Cut from 3.5. §355(e) blocks any deal until January 2028, and the clock expiring does not free the stock: the Class B veto is held personally by the chairman and CEO of the former parent. The leveraged-buyout arithmetic is excellent and may never be tested. A Platforms separation is the one route that needs no change of control |
| Weighted Score | 2.75 | ||
| Investment Grade | B | Moderate Opportunity |
What moved and what deliberately did not.
This is Versant’s first investment grade on this site. The company has been carried in the research universe since January 2026 and covered in nine monthly reports without a letter grade.
Competitive Position at 2.0 is the score doing most of the work, and it is charged once. The secular decline of linear television is the objection to this company and it belongs in exactly one dimension. It is deliberately not re-charged to Financial Profile — where the three-year record is already reflected — nor to Strategic Rationale, where the separation itself was competently executed. Charging one objection to three dimensions is how a scorecard turns a single fact into a verdict, and the Qnity and Solstice reviews both had to unwind exactly that.
The Class B structure is charged once too, to Acquisition Potential, where its effect is mechanical and decisive. It is described under Management & Governance because that is where a reader looks for it, but it is not scored twice. Governance nets to 3.0 on its own merits: a genuine operating bench against a genuine absence of minority recourse.
Rating: HOLD. Target $42. The 11.5% gap to target is not enough to buy at $37.36, and the recovery from $27.42 has already taken the discount that made this interesting in February. The bear case is visible and the bull case is arithmetic: everyone can see cable is dying, and the market has priced it dying at roughly twice the rate it is currently dying. Being right requires only that the decline stay ordinary — and AMC Networks, down 69.7% over fifteen years on the same structure, is the reminder that it may not.
Accumulate below $33, where the implied decline rate exceeds 14% and the free cash flow yield passes 24%.
Nothing on this page is investment advice. Figures are drawn from the primary filings linked at the top and from this site’s own price archive; where a figure could not be primary-sourced, that is stated in the text rather than estimated silently.