Versigent VGNT
+47.4%vs Day 1Spinoff of Aptiv (APTV) · Classic Spinoff · Spun Apr 1, 2026
Expected return (11/13/2026): +19% Gain to loss: 2.5 : 1Global Tier-1 supplier of vehicle wiring, 90% low voltage. Most reported growth is copper and currency pass-through; volume added 0.5% in Q3 2026. Value turns on cost savings keeping pace with yearly price cuts to carmakers; three carmakers buy 53%. Cases $81.54 / $57.30 / $25.20, weighted 10/60/30, $50. ACCUMULATE, target $50.
Current Stats
Post-Spinoff Performance
| Timeline | |
| Spinoff date | April 1, 2026 · NYSE |
| Days since spinoff | 227 days |
| Structure | Classic Spinoff |
| §355(e) window closes statutory; a tax matters agreement may bar more, and for longer | April 1, 2028 |
| Parent | Aptiv (APTV) |
| Day-1 reaction | |
| Day 1 open | $28.27 |
| Day 1 return (open→close) | -1.5% |
| Day 1 price (close) | $27.85 |
| Day 1 range | $26.88 – $30.02 +11.7% spread |
| Day 1 low held? | Breached after 2 sessions to -2.0% below |
| Price levels | |
| Post-spin low (closing) | $26.94 on Apr 7, 2026 · 6 days post-spin |
| Lowest traded | $26.34 on Apr 9, 2026 · 8 days post-spin |
| Current price (Nov 13, 2026) | $42.19 |
| Returns | |
| Return vs Day 1 (close) | +52.0% |
| — range by day 1 entry theoretical bounds | +41.0% to +57.4% |
| Return vs post-spin low (price) | +56.6% |
| Total return vs low incl. dividends since | +57.1% |
| First-quarter return (≈90d) | +50.8% |
| Versus benchmarks | |
| S&P 500 over same window | +15.8% |
| Shares & ownership | |
| Shares outstanding Sep 30, 2026 | 70,841,248 |
| Diluted average shares the EPS denominator | 72,250,000 |
| Free float | 70,266,566 99% of shares outstanding |
| Held by institutions | 100% insiders 0.8% |
| Share count trend Dec 2024 → Sep 2026 | -0.3% net buyback |
| Volume & liquidity | |
| Traded per day 20-session median | $27M |
| Normal volume baseline | 1,014,400 shares · now 0.64x |
| Day 1 volume | 26.8x normal · first week 11.1x |
| Decay | half in 2 sessions · normal by 16 |
Computed from split-adjusted closing prices. Returns are total return — (end price + dividends received − start price) ÷ start price — with no reinvestment assumed.
Price History
Closing price, split-adjusted, with volume below. The Price line excludes dividends; Price + dividends adds the cash paid out, with no reinvestment assumed. Individual payments are listed in the table below. Source: Yahoo Finance. Data through Nov 14, 2026.
Raw daily price & volume data · dividends marked
| Date | Open | High | Low | Close | Volume | Float | Turnover | Market cap | Dividend | Split |
|---|---|---|---|---|---|---|---|---|---|---|
| 2026-11-13 | $42.67 | $42.98 | $41.72 | $42.19 | 449,900 | 70,266,566 | 0.64% | $2.99B | — | — |
| 2026-11-12 | $42.47 | $43.00 | $41.93 | $42.46 | 416,800 | 70,266,566 | 0.59% | $3.01B | — | — |
| 2026-11-11 | $42.76 | $43.10 | $42.28 | $42.89 | 495,400 | 70,266,566 | 0.70% | $3.04B | — | — |
| 2026-11-10 | $41.16 | $42.32 | $41.16 | $42.30 | 755,100 | 70,266,566 | 1.07% | $3.00B | — | — |
| 2026-11-09 | $41.78 | $42.21 | $40.87 | $41.62 | 1,254,600 | 70,266,566 | 1.77% | $2.95B | — | — |
| 2026-11-06 | $40.48 | $41.77 | $39.60 | $40.96 | 1,027,800 | 70,266,566 | 1.45% | $2.90B | — | — |
| 2026-11-05 | $42.38 | $42.41 | $40.10 | $40.28 | 1,161,500 | 70,266,566 | 1.64% | $2.85B | — | — |
| 2026-11-04 | $40.20 | $45.00 | $40.20 | $41.97 | 1,899,000 | 70,266,566 | 2.68% | $2.97B | — | — |
| 2026-11-03 | $41.51 | $42.40 | $40.26 | $40.69 | 2,229,000 | 70,266,566 | 3.15% | $2.88B | — | — |
| 2026-11-02 | $41.55 | $43.00 | $40.93 | $40.98 | 1,086,800 | 70,266,566 | 1.53% | $2.90B | — | — |
| 2026-10-30 | $41.62 | $42.50 | $40.46 | $41.06 | 532,300 | 70,266,566 | 0.75% | $2.91B | — | — |
| 2026-10-29 | $42.00 | $42.83 | $41.24 | $42.32 | 926,000 | 70,263,183 | 1.31% | $3.00B | — | — |
| 2026-10-28 | $41.75 | $42.17 | $40.89 | $41.49 | 652,900 | 70,257,249 | 0.92% | $2.94B | — | — |
| 2026-10-27 | $41.95 | $42.18 | $41.18 | $41.58 | 751,400 | 70,257,249 | 1.06% | $2.95B | — | — |
| 2026-10-26 | $41.56 | $42.34 | $41.04 | $41.40 | 634,900 | 70,257,249 | 0.90% | $2.93B | — | — |
| 2026-10-23 | $41.70 | $41.72 | $40.11 | $41.40 | 556,500 | 70,257,249 | 0.79% | $2.93B | — | — |
| 2026-10-22 | $43.00 | $43.33 | $42.02 | $42.35 | 654,100 | 70,257,249 | 0.92% | $3.00B | — | — |
| 2026-10-21 | $44.14 | $44.14 | $42.78 | $43.39 | 457,000 | 70,257,249 | 0.65% | $3.07B | — | — |
| 2026-10-20 | $43.41 | $44.29 | $43.19 | $43.87 | 605,400 | 70,257,249 | 0.85% | $3.11B | — | — |
| 2026-10-19 | $44.49 | $44.49 | $43.50 | $43.69 | 424,000 | 70,257,249 | 0.60% | $3.10B | — | — |
| 2026-10-16 | $43.92 | $45.58 | $43.72 | $44.22 | 794,700 | 70,257,249 | 1.12% | $3.13B | — | — |
| 2026-10-15 | $42.23 | $43.91 | $41.56 | $43.71 | 834,100 | 70,257,249 | 1.18% | $3.10B | — | — |
| 2026-10-14 | $43.00 | $43.50 | $42.17 | $42.56 | 707,000 | 70,257,249 | 1.00% | $3.02B | — | — |
| 2026-10-13 | $43.40 | $43.79 | $43.12 | $43.65 | 534,300 | 70,257,249 | 0.75% | $3.09B | — | — |
| 2026-10-12 | $44.50 | $44.60 | $43.23 | $43.44 | 520,600 | 70,257,249 | 0.73% | $3.08B | — | — |
| 2026-10-09 | $44.50 | $44.96 | $43.81 | $44.19 | 543,800 | 70,257,249 | 0.77% | $3.13B | — | — |
| 2026-10-08 | $44.86 | $45.08 | $43.82 | $44.16 | 1,496,500 | 70,257,249 | 2.11% | $3.13B | — | — |
| 2026-10-07 | $46.97 | $46.97 | $44.34 | $45.29 | 676,000 | 70,257,249 | 0.95% | $3.21B | — | — |
| 2026-10-06 | $47.08 | $47.72 | $46.67 | $47.37 | 432,900 | 70,257,249 | 0.61% | $3.36B | — | — |
| 2026-10-05 | $46.35 | $47.82 | $45.99 | $47.27 | 834,700 | 70,160,205 | 1.18% | $3.35B | — | — |
| 2026-10-02 | $46.96 | $47.63 | $46.41 | $46.43 | 579,800 | 70,160,205 | 0.82% | $3.29B | — | — |
| 2026-10-01 | $44.94 | $46.60 | $44.19 | $46.26 | 567,900 | 70,160,205 | 0.80% | $3.28B | — | — |
| 2026-09-30 | $45.64 | $46.00 | $44.92 | $44.94 | 1,021,400 | 70,160,205 | 1.44% | $3.18B | — | — |
| 2026-09-29 | $45.50 | $45.81 | $44.58 | $45.66 | 520,100 | 70,160,205 | 0.73% | $3.23B | — | — |
| 2026-09-28 | $46.28 | $46.46 | $45.06 | $45.40 | 690,000 | 70,160,205 | 0.97% | $3.22B | — | — |
| 2026-09-25 | $45.53 | $46.92 | $45.51 | $46.73 | 592,100 | 70,160,205 | 0.84% | $3.31B | — | — |
| 2026-09-24 | $46.10 | $46.15 | $44.30 | $45.22 | 567,800 | 70,160,205 | 0.80% | $3.20B | — | — |
| 2026-09-23 | $46.55 | $47.14 | $45.75 | $46.20 | 370,300 | 70,160,205 | 0.52% | $3.27B | — | — |
| 2026-09-22 | $47.69 | $47.69 | $45.91 | $47.09 | 630,800 | 70,160,205 | 0.89% | $3.33B | — | — |
| 2026-09-21 | $46.27 | $47.30 | $45.64 | $47.07 | 725,900 | 70,160,205 | 1.03% | $3.33B | — | — |
| 2026-09-18 | $47.68 | $47.68 | $45.11 | $45.86 | 2,606,900 | 70,160,205 | 3.68% | $3.25B | — | — |
| 2026-09-17 | $46.00 | $47.58 | $45.80 | $47.52 | 1,066,800 | 70,160,205 | 1.51% | $3.37B | — | — |
| 2026-09-16 | $45.47 | $46.29 | $44.91 | $45.42 | 832,800 | 70,160,205 | 1.18% | $3.22B | — | — |
| 2026-09-15 | $45.75 | $46.14 | $45.12 | $45.19 | 630,000 | 70,160,205 | 0.89% | $3.20B | — | — |
| 2026-09-14 | $46.08 | $46.71 | $45.86 | $46.08 | 633,300 | 70,160,205 | 0.89% | $3.26B | — | — |
| 2026-09-11 | $47.17 | $47.34 | $46.47 | $46.89 | 372,500 | 70,160,205 | 0.53% | $3.32B | — | — |
| 2026-09-10 | $45.01 | $47.11 | $44.87 | $46.40 | 470,600 | 70,160,205 | 0.66% | $3.29B | — | — |
| 2026-09-09 | $47.09 | $47.58 | $44.99 | $45.74 | 1,137,700 | 70,160,205 | 1.61% | $3.24B | — | — |
| 2026-09-08 | $50.00 | $50.19 | $47.30 | $47.39 | 784,600 | 70,160,205 | 1.11% | $3.36B | — | — |
| 2026-09-04 | $48.44 | $50.25 | $48.03 | $50.22 | 524,100 | 70,037,660 | 0.74% | $3.56B | $0.13 | — |
| 2026-09-03 | $47.66 | $48.98 | $47.34 | $48.42 | 588,400 | 70,037,660 | 0.83% | $3.43B | — | — |
| 2026-09-02 | $46.48 | $47.85 | $46.42 | $46.81 | 509,300 | 70,037,660 | 0.72% | $3.31B | — | — |
| 2026-09-01 | $46.37 | $46.74 | $45.00 | $46.19 | 792,300 | 70,037,660 | 1.12% | $3.27B | — | — |
| 2026-08-31 | $48.20 | $49.05 | $47.24 | $47.40 | 630,200 | 70,037,660 | 0.89% | $3.36B | — | — |
| 2026-08-28 | $48.67 | $49.32 | $48.07 | $48.21 | 460,600 | 70,037,660 | 0.65% | $3.41B | — | — |
| 2026-08-27 | $47.10 | $48.76 | $47.10 | $48.56 | 789,100 | 70,037,660 | 1.11% | $3.44B | — | — |
| 2026-08-26 | $47.31 | $48.01 | $47.15 | $47.36 | 573,600 | 70,037,660 | 0.81% | $3.35B | — | — |
| 2026-08-25 | $47.02 | $47.40 | $46.16 | $47.22 | 457,200 | 70,037,660 | 0.65% | $3.34B | — | — |
| 2026-08-24 | $48.97 | $49.62 | $46.92 | $46.96 | 676,500 | 70,037,660 | 0.96% | $3.33B | — | — |
| 2026-08-21 | $46.84 | $49.46 | $46.84 | $49.23 | 937,000 | 70,037,660 | 1.32% | $3.49B | — | — |
| 2026-08-20 | $47.00 | $48.00 | $46.07 | $46.65 | 401,800 | 70,037,660 | 0.57% | $3.30B | — | — |
| 2026-08-19 | $47.40 | $48.39 | $46.77 | $47.40 | 756,300 | 70,037,660 | 1.07% | $3.36B | — | — |
| 2026-08-18 | $46.30 | $46.84 | $45.82 | $46.69 | 617,600 | 70,037,660 | 0.87% | $3.31B | — | — |
| 2026-08-17 | $46.00 | $47.33 | $44.82 | $46.78 | 758,000 | 70,037,660 | 1.07% | $3.31B | — | — |
| 2026-08-14 | $45.43 | $46.95 | $44.87 | $46.20 | 906,900 | 70,037,660 | 1.28% | $3.27B | — | — |
| 2026-08-13 | $45.52 | $46.15 | $44.74 | $45.54 | 776,500 | — | 1.10% | $3.22B | — | — |
| 2026-08-12 | $46.47 | $46.68 | $45.25 | $45.43 | 768,400 | — | 1.09% | $3.22B | — | — |
| 2026-08-11 | $44.28 | $46.68 | $44.05 | $46.06 | 741,800 | — | 1.05% | $3.26B | — | — |
| 2026-08-10 | $44.00 | $44.21 | $43.20 | $44.05 | 682,400 | — | 0.96% | $3.12B | — | — |
| 2026-08-07 | $43.11 | $45.13 | $42.79 | $44.10 | 837,100 | — | 1.18% | $3.12B | — | — |
| 2026-08-06 | $44.66 | $44.86 | $42.78 | $42.82 | 903,600 | — | 1.28% | $3.03B | — | — |
| 2026-08-05 | $46.08 | $46.71 | $44.80 | $45.03 | 1,234,100 | — | 1.74% | $3.19B | — | — |
| 2026-08-04 | $45.55 | $47.01 | $42.81 | $45.80 | 2,472,500 | — | 3.49% | $3.24B | — | — |
| 2026-08-03 | $41.35 | $42.97 | $41.06 | $42.04 | 1,210,700 | — | 1.71% | $2.98B | — | — |
| 2026-07-31 | $41.70 | $42.29 | $40.15 | $41.35 | 892,800 | — | 1.26% | $2.93B | — | — |
| 2026-07-30 | $43.28 | $43.55 | $41.28 | $41.89 | 785,000 | — | 1.11% | $2.97B | — | — |
| 2026-07-29 | $43.72 | $44.68 | $42.85 | $43.02 | 715,600 | — | 1.01% | $3.05B | — | — |
| 2026-07-28 | $41.71 | $44.61 | $41.00 | $44.17 | 1,238,700 | — | 1.75% | $3.13B | — | — |
| 2026-07-27 | $41.91 | $42.11 | $40.79 | $41.72 | 608,500 | — | 0.86% | $2.95B | — | — |
| 2026-07-24 | $41.27 | $42.39 | $40.66 | $41.65 | 712,400 | — | 1.01% | $2.95B | — | — |
| 2026-07-23 | $40.72 | $41.11 | $40.02 | $41.08 | 1,455,600 | — | 2.06% | $2.91B | — | — |
| 2026-07-22 | $41.12 | $42.53 | $40.83 | $41.16 | 789,500 | — | 1.11% | $2.91B | — | — |
| 2026-07-21 | $40.86 | $42.13 | $40.07 | $41.07 | 1,023,500 | — | 1.45% | $2.91B | — | — |
| 2026-07-20 | $40.99 | $41.05 | $39.77 | $40.02 | 1,043,500 | — | 1.47% | $2.83B | — | — |
| 2026-07-17 | $39.00 | $40.68 | $38.44 | $40.01 | 653,700 | — | 0.92% | $2.83B | — | — |
| 2026-07-16 | $40.35 | $41.13 | $38.80 | $40.27 | 1,222,200 | — | 1.73% | $2.85B | — | — |
| 2026-07-15 | $40.71 | $41.90 | $39.65 | $40.79 | 1,010,000 | — | 1.43% | $2.89B | — | — |
| 2026-07-14 | $40.99 | $41.57 | $39.62 | $39.64 | 702,500 | — | 0.99% | $2.81B | — | — |
| 2026-07-13 | $41.44 | $41.53 | $40.27 | $40.63 | 871,500 | — | 1.23% | $2.88B | — | — |
| 2026-07-10 | $40.77 | $42.05 | $40.68 | $41.30 | 900,300 | — | 1.27% | $2.92B | — | — |
| 2026-07-09 | $40.52 | $41.50 | $40.00 | $40.72 | 1,052,400 | — | 1.49% | $2.88B | — | — |
| 2026-07-08 | $41.37 | $41.96 | $39.59 | $40.43 | 1,572,100 | — | 2.22% | $2.86B | — | — |
| 2026-07-07 | $42.47 | $42.47 | $39.55 | $39.80 | 1,368,100 | — | 1.93% | $2.82B | — | — |
| 2026-07-06 | $40.83 | $42.67 | $40.40 | $42.52 | 1,448,600 | — | 2.05% | $3.01B | — | — |
| 2026-07-02 | $41.47 | $43.00 | $39.64 | $40.20 | 1,744,200 | — | 2.46% | $2.85B | — | — |
| 2026-07-01 | $41.52 | $42.10 | $40.64 | $41.83 | 1,310,500 | — | 1.85% | $2.96B | — | — |
| 2026-06-30 | $39.74 | $42.30 | $39.74 | $42.01 | 1,660,300 | — | 2.34% | $2.97B | — | — |
| 2026-06-29 | $40.78 | $41.05 | $39.34 | $39.40 | 1,977,500 | — | 2.79% | $2.79B | — | — |
| 2026-06-26 | $41.46 | $42.25 | $39.71 | $41.40 | 12,273,600 | — | 17.31% | $2.93B | — | — |
| 2026-06-25 | $42.86 | $43.83 | $41.90 | $42.31 | 1,151,600 | — | 1.62% | $3.00B | — | — |
| 2026-06-24 | $42.33 | $42.97 | $41.36 | $42.22 | 1,628,400 | — | 2.30% | $2.99B | — | — |
| 2026-06-23 | $46.00 | $46.00 | $42.63 | $42.70 | 1,507,500 | — | 2.13% | $3.03B | — | — |
| 2026-06-22 | $45.54 | $47.19 | $44.85 | $45.43 | 1,327,100 | — | 1.87% | $3.22B | — | — |
| 2026-06-18 | $46.22 | $46.79 | $44.69 | $45.89 | 2,125,600 | — | 3.00% | $3.25B | — | — |
| 2026-06-17 | $46.95 | $47.56 | $44.76 | $45.16 | 1,003,800 | — | 1.42% | $3.20B | — | — |
| 2026-06-16 | $46.79 | $48.25 | $45.95 | $46.21 | 929,300 | — | 1.31% | $3.28B | — | — |
| 2026-06-15 | $47.86 | $48.36 | $45.78 | $46.94 | 1,252,100 | — | 1.77% | $3.33B | — | — |
| 2026-06-12 | $47.95 | $48.91 | $46.15 | $46.69 | 844,400 | — | 1.19% | $3.31B | — | — |
| 2026-06-11 | $47.45 | $48.64 | $46.00 | $48.24 | 911,700 | — | 1.29% | $3.42B | — | — |
| 2026-06-10 | $49.03 | $49.55 | $47.32 | $47.38 | 1,018,800 | — | 1.44% | $3.36B | — | — |
| 2026-06-09 | $49.12 | $50.89 | $48.22 | $49.37 | 1,030,000 | — | 1.45% | $3.50B | — | — |
| 2026-06-08 | $48.20 | $49.66 | $47.76 | $49.07 | 1,342,600 | — | 1.89% | $3.48B | — | — |
| 2026-06-05 | $50.12 | $50.55 | $46.86 | $47.40 | 1,639,300 | — | 2.31% | $3.36B | — | — |
| 2026-06-04 | $49.32 | $50.66 | $47.98 | $50.17 | 1,740,900 | — | 2.46% | $3.56B | — | — |
| 2026-06-03 | $45.00 | $49.92 | $44.40 | $49.81 | 2,825,300 | — | 3.99% | $3.53B | — | — |
| 2026-06-02 | $45.41 | $47.15 | $44.74 | $45.16 | 1,141,800 | — | 1.61% | $3.20B | — | — |
| 2026-06-01 | $43.51 | $44.98 | $43.32 | $44.67 | 1,075,300 | — | 1.52% | $3.17B | — | — |
| 2026-05-29 | $44.05 | $45.69 | $43.39 | $44.12 | 1,271,100 | — | 1.79% | $3.13B | — | — |
| 2026-05-28 | $43.63 | $44.67 | $42.75 | $44.30 | 1,043,500 | — | 1.47% | $3.14B | — | — |
| 2026-05-27 | $41.30 | $44.26 | $40.64 | $44.13 | 1,578,300 | — | 2.23% | $3.13B | — | — |
| 2026-05-26 | $41.43 | $42.37 | $40.45 | $41.10 | 1,288,700 | — | 1.82% | $2.91B | — | — |
| 2026-05-22 | $41.07 | $43.05 | $40.97 | $41.13 | 955,800 | — | 1.35% | $2.92B | — | — |
| 2026-05-21 | $42.59 | $42.59 | $40.80 | $40.87 | 1,836,300 | — | 2.59% | $2.90B | — | — |
| 2026-05-20 | $42.70 | $43.43 | $41.42 | $42.59 | 656,800 | — | 0.93% | $3.02B | — | — |
| 2026-05-19 | $43.72 | $43.98 | $42.31 | $42.60 | 1,047,000 | — | 1.48% | $3.02B | — | — |
| 2026-05-18 | $43.49 | $47.27 | $42.96 | $44.45 | 1,717,800 | — | 2.42% | $3.15B | — | — |
| 2026-05-15 | $44.29 | $44.49 | $42.44 | $42.80 | 1,282,900 | — | 1.81% | $3.03B | — | — |
| 2026-05-14 | $44.04 | $45.70 | $44.04 | $44.83 | 992,800 | — | 1.40% | $3.18B | — | — |
| 2026-05-13 | $43.96 | $44.45 | $42.84 | $43.80 | 880,100 | — | 1.24% | $3.11B | — | — |
| 2026-05-12 | $43.16 | $43.51 | $41.92 | $43.34 | 948,100 | — | 1.34% | $3.07B | — | — |
| 2026-05-11 | $42.13 | $43.87 | $41.75 | $43.72 | 1,985,300 | — | 2.80% | $3.10B | — | — |
| 2026-05-08 | $39.80 | $41.93 | $39.02 | $41.83 | 1,173,100 | — | 1.65% | $2.97B | — | — |
| 2026-05-07 | $41.80 | $41.80 | $38.80 | $39.00 | 1,938,500 | — | 2.73% | $2.76B | — | — |
| 2026-05-06 | $38.25 | $42.46 | $37.55 | $41.55 | 2,841,600 | — | 4.01% | $2.95B | — | — |
| 2026-05-05 | $36.23 | $37.68 | $35.91 | $37.50 | 1,831,400 | — | 2.58% | $2.66B | — | — |
| 2026-05-04 | $37.03 | $37.39 | $35.39 | $36.17 | 1,629,000 | — | 2.30% | $2.56B | — | — |
| 2026-05-01 | $34.99 | $37.08 | $34.87 | $37.07 | 1,574,000 | — | 2.22% | $2.63B | — | — |
| 2026-04-30 | $34.36 | $35.64 | $33.88 | $34.97 | 1,071,600 | — | 1.51% | $2.48B | — | — |
| 2026-04-29 | $34.29 | $35.04 | $33.86 | $34.34 | 1,090,200 | — | 1.54% | $2.43B | — | — |
| 2026-04-28 | $35.09 | $35.52 | $33.29 | $34.22 | 1,295,700 | — | 1.83% | $2.43B | — | — |
| 2026-04-27 | $34.67 | $35.22 | $34.25 | $34.94 | 770,500 | — | 1.09% | $2.48B | — | — |
| 2026-04-24 | $34.22 | $36.03 | $33.02 | $34.96 | 1,342,600 | — | 1.89% | $2.48B | — | — |
| 2026-04-23 | $34.66 | $35.26 | $33.85 | $34.31 | 988,700 | — | 1.39% | $2.43B | — | — |
| 2026-04-22 | $35.34 | $36.70 | $33.83 | $34.83 | 1,416,600 | — | 2.00% | $2.47B | — | — |
| 2026-04-21 | $35.38 | $36.87 | $34.00 | $35.01 | 2,064,400 | — | 2.91% | $2.48B | — | — |
| 2026-04-20 | $34.99 | $36.31 | $34.41 | $34.77 | 2,181,100 | — | 3.08% | $2.46B | — | — |
| 2026-04-17 | $33.75 | $35.08 | $33.14 | $34.70 | 3,056,100 | — | 4.31% | $2.46B | — | — |
| 2026-04-16 | $34.20 | $34.72 | $32.52 | $32.61 | 2,054,500 | — | 2.90% | $2.31B | — | — |
| 2026-04-15 | $32.78 | $34.55 | $32.25 | $34.21 | 1,816,800 | — | 2.56% | $2.43B | — | — |
| 2026-04-14 | $30.60 | $33.33 | $30.60 | $32.92 | 2,809,500 | — | 3.96% | $2.33B | — | — |
| 2026-04-13 | $31.44 | $31.50 | $29.78 | $30.52 | 2,172,700 | — | 3.06% | $2.16B | — | — |
| 2026-04-10 | $29.79 | $32.16 | $29.19 | $31.14 | 3,204,200 | — | 4.52% | $2.21B | — | — |
| 2026-04-09 | $26.55 | $30.00 | $26.34 | $29.49 | 4,417,300 | — | 6.23% | $2.09B | — | — |
| 2026-04-08 | $27.19 | $28.36 | $26.87 | $26.95 | 7,166,300 | — | 10.11% | $1.91B | — | — |
| 2026-04-07 | $27.80 | $28.14 | $26.49 | $26.94 | 9,335,000 | — | 13.17% | $1.91B | — | — |
| 2026-04-06 | $28.10 | $28.94 | $26.52 | $28.34 | 5,758,200 | — | 8.12% | $2.01B | — | — |
| 2026-04-02 | $27.21 | $30.13 | $27.05 | $28.10 | 6,991,800 | — | 9.86% | $1.99B | — | — |
| 2026-04-01 | $28.27 | $30.02 | $26.88 | $27.85 | 27,163,800 | — | 38.32% | $1.97B | — | — |
Close is split-adjusted to current shares. It is not dividend-adjusted: dividends are listed separately, so total return is (end price + dividends received − start price) ÷ start price, checkable by hand. Volume is as-traded.
Momentum: MACD and RSI
Top: MACD (navy) and its signal line (gold); bars show the gap between them, teal when MACD is above.
Bottom: RSI over 14 days; above 70 is usually read as overbought and below 30 as oversold.
The lines start late because MACD needs 26 trading days of prices and RSI 14 before the first value.
The colored strip under the charts shows the state label day by day; hover for the state and the reason.
Both measure momentum in the price and say nothing about value. Hover for each day's arithmetic.
Source: closing prices from this site's daily price archive (Yahoo Finance), not adjusted for dividends. Data through Nov 14, 2026.
How these are calculated
Short Selling
Bars: shares sold short each day in trades reported to FINRA (off-exchange
trades, roughly half of all volume).
Line: the short share of that volume, averaged over 20 sessions.
Gold points: short interest, the shares sold short and not yet bought back,
reported twice a month, also shown as a percentage of the free float and of
shares outstanding.
Daily short volume includes market makers' routine hedging, so a change in the
share is more informative than its level. Hover for each day's figures.
Sources: FINRA; float from this site's daily share records; shares outstanding
from the company's latest quarterly filing. Data through Nov 13, 2026.
Index-Fund Holdings
Daily positions of State Street's SPDR index funds, by the fund's file date.
These are the index funds whose daily holdings can be collected; iShares and
Vanguard funds, often larger holders, publish holdings that cannot be
collected automatically and appear in the written analysis from their
quarterly filings.
Collection began on October 11, 2026. A fund that drops the stock shows as an
exit.
Source: State Street Global Advisors. Data through
Nov 12, 2026.
Update — November 4, 2026: third-quarter results — ACCUMULATE, target $48 → $50
Rated at the November 4, 2026 close of $41.97. The results were released before the open that day and the 10-Q during the session. Sources: the third-quarter results release and the third-quarter 10-Q, both of November 4, 2026. The analyses below are left as published; this section tests the results against the October 15, 2026 update and reruns the three scenarios on the reported balances and the new guidance. The weights are unchanged.
Overview Summary
The third quarter passed the tests that would have raised the worst case’s weight and missed the one that would have lowered it. Guidance was tightened with the free cash flow range raised to $275–325 million, and the adjusted EBITDA margin was 11.2%, above the 10% the page named, but volume added only 0.5% to sales and the three largest customers rose to 53% of sales. The margin includes $39 million of gains on copper and currency hedges; without them it would have been about 9.6% (an estimate). The target rises from $48 to $50 on lower net debt and the higher cash guidance, with the weights unchanged at 10 / 60 / 30. At $41.97 the expected return is +19.4% and the gain to loss 2.6 to 1, the ACCUMULATE band.
Rating: BUY below $40.08 · ACCUMULATE $40.08–45.54 · HOLD $45.54–55.66 · TRIM $55.66–66.79 · SELL above $66.79 · Target $50
The quarter against the tests
| Test (October 15, 2026) | Third quarter 2026 | Verdict |
|---|---|---|
| A cut to 2026 guidance would raise the worst case | Net sales $9.5–9.6 billion (from $9.4–9.6 billion), adjusted EBITDA $970 million–1.01 billion (from $950 million–1.03 billion, the midpoint unchanged at $990 million), free cash flow $275–325 million (from $200–300 million) | Passes |
| Adjusted EBITDA margin below 10% on copper would raise the worst case | 11.2% ($275 million), against 10.8% a year earlier; about 9.6% without $39 million of hedge gains (copper $19 million, currencies $20 million) | Passes, with the hedge gains doing part of the work |
| Volume growth near 4% with the margin intact would lower the worst case | Volume added $11 million, 0.5% of sales; sales growth without copper pass-through and currencies was about 1% (3% for the nine months) | Not met |
| Share of the three largest customers | 19%, 19% and 15%, 53% in total, against 52% in the second quarter and 47% in 2025; the top ten 81% | Higher again |
| Copper’s effect on the margin | Copper prices added $112 million to sales and took $7 million from EBITDA; $355 million of copper is hedged, with hedges running to September 2028 | Contained this quarter |
- Net pricing was positive, +$21 million, after −$18 million in the second quarter, so price recoveries outweighed the price cuts carmakers take. With currencies (+$8 million), volume (+$2 million) and operations (+$3 million), less copper (−$7 million), adjusted EBITDA rose from $248 million to $275 million.
- Sales were $2,450 million, up 7.2%: low voltage $2,208 million (+8.2%), high voltage $242 million (−1.2%). By region, Asia Pacific grew 18%, North America 6%, and Europe, the Middle East and Africa fell 6%.
- Bookings were $2.1 billion in the quarter, after $5.4 billion in the first half.
- The stock rose 3.1% on the day, to $41.97, while SPY rose 1.7% and Aptiv rose 4.6%. It had fallen from $42.56 on October 14, 2026, the price of the last update, to $40.69 on November 3, 2026.
What the guidance leaves for the fourth quarter
| Fourth quarter 2026 | Guidance range | Fourth quarter 2025 |
|---|---|---|
| Net sales | $2,394–2,494M | $2,302M |
| Adjusted EBITDA | $220–260M | $232M |
| Free cash flow | $28–78M |
The EBITDA range is about level with a year earlier on sales up 4–8%, most of it copper pass-through. The hedge gains continue: the 10-Q expects $83 million of gains in cost of sales over the next 12 months.
Cash and the debt
- Free cash flow was $170 million in the quarter and $247 million in nine months, after $172 million of capital spending, which rose with the number of program launches.
- Net debt was $1.51 billion at September 30, 2026: debt at face value of $2,151 million (the $800 million of 6.125% notes due 2031, the $800 million of 6.375% notes due 2034, $500 million of Term Loan A and $51 million of leases and other) less cash of $638 million. The cases on October 15, 2026 used $1.67 billion at June 30, 2026. Net debt is about 1.5 times the guided 2026 EBITDA. The revolving credit facility is undrawn.
- No shares were bought under the $250 million program approved in April 2026. The dividend of $0.13 a quarter continues (payable December 17, 2026). Diluted shares were 72.25 million in the quarter, against the 71.9 million the cases used.
- Minority partners’ share of the equity was $209 million and affiliates $146 million, against $199 million and $149 million.
The scenarios and the asymmetry after the third quarter
The October 8, 2026 drivers are unchanged. 2026 is now the nine months reported plus a forecast fourth quarter, each case’s 2026 EBITDA and free cash flow sit at the bottom, middle and top of the tightened guidance, and the balances are those of September 30, 2026.
| Step (best guess 10 / 60 / 30) | Best | Base | Worst | Weighted |
|---|---|---|---|---|
| October 15, 2026 | $81.15 | $55.69 | $22.60 | $48.31 |
| Net debt $1.51 billion, minority partners, affiliates and 72.25 million shares at September 30, 2026 | + $1.60 | + $1.72 | + $1.88 | + $1.76 |
| Fourth-quarter cash flow only (the nine months are in the cash balance) | − $0.29 | − $0.80 | − $1.31 | − $0.90 |
| 2026 sales: nine months reported, fourth quarter forecast | + $0.04 | $0.00 | − $0.30 | − $0.09 |
| 2026 free cash flow at the raised guidance ($275 / 300 / 325 million) | + $0.34 | + $0.68 | + $1.02 | + $0.75 |
| 2026 EBITDA at the tightened guidance ($970 million–1.01 billion) | − $1.30 | $0.00 | + $1.30 | + $0.26 |
| November 4, 2026 | $81.54 | $57.30 | $25.20 | $50.09 |
| vs $41.97 | +94% | +37% | −40% | +19.4% |
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $55.34 | +32% | 4.2 to 1 |
| Best guess: 10 / 60 / 30 (unchanged) | $50.09 | +19.4% | 2.6 to 1 |
| Stress: 10 / 40 / 50 | $43.67 | +4% | 1.2 to 1 |
| What the price implies: 0 / 52 / 48 | $41.97 | 0% | 1.0 to 1 |
The weights are a judgement. All values are estimates from the model.
- The weights are unchanged. Neither of the page’s triggers for the worst case was hit, which argues against raising it, and the trigger for lowering it, volume growth near 4%, was not met. The margin’s reliance on hedge gains and the rising share of the three largest customers also argue for keeping the worst case at 30%.
- The price implies no weight on the best case. With the best case at zero, the price is matched by 52% on the base case and 48% on the worst, against the best guess of 30% on the worst.
| Measure | At $41.97 | Formula |
|---|---|---|
| Expected return (header chip) | +19.4% | (10% × $81.54 + 60% × $57.30 + 30% × $25.20) ÷ $41.97 − 1 = ($8.15 + $34.38 + $7.56) ÷ $41.97 − 1 |
| Gain to loss (header chip) | 2.6 to 1 | (10% × $39.57 + 60% × $15.33) ÷ (30% × $16.77) = ($3.96 + $9.20) ÷ $5.03 |
| Expected base gain ÷ expected worst loss | 1.83 to 1 | $9.20 ÷ $5.03 |
| Best gain ÷ worst loss | 2.4 to 1 | $39.57 ÷ $16.77 |
| Base gain ÷ worst loss | 0.91 to 1 | $15.33 ÷ $16.77 |
Both header chips take the color of the rating band the price is in: BUY green (an expected return of +25% or more with gain to loss of 3 to 1 or better), ACCUMULATE blue (+10% to +25%), HOLD gold (−10% to +10%), TRIM orange (−25% to −10%) and SELL red (below −25%). On the best guess they are green below $40.08, blue up to $45.54, gold up to $55.66, orange up to $66.79 and red above. At $41.97 both are blue, the ACCUMULATE band.
What it means for the rating
ACCUMULATE, target $48 → $50. The target is the best-guess value, $50.09. The rating follows the site’s rating scale (see the Methodology page): at $41.97 the expected return is +19.4%, inside the ACCUMULATE band of 10% to 25%. It is not BUY because the price is above $40.08, where the expected return reaches 25%, and because the quarter’s margin leaned on hedge gains while volume barely grew. It is not HOLD because the base case is 37% above the price, guidance was raised on cash, and net debt fell by about $160 million in a quarter.
| Action | Level | Reason |
|---|---|---|
| Buy | Below about $40.08 | Expected return 25% or more on the best guess; gain to loss is 3.25 to 1 there |
| Accumulate | $40.08–45.54 | Expected return 10–25% |
| Hold | $45.54–55.66 | Expected return −10% to +10%, around the $50 target |
| Trim | $55.66–66.79 | Expected return −10% to −25% |
| Sell | Above about $66.79 | Expected return below −25% |
| Move the bands down | A guidance cut, an EBITDA margin below 10% once hedge gains fade, a lost program at one of the three largest customers, or 2027 production forecasts turning negative | The worst case’s weight rises |
| Move the bands up | Volume growth near 4% with the margin held without hedge gains, or the three largest customers’ share falling | The worst case’s weight falls |
What the fourth-quarter results (about early February 2027, date not yet announced) must show:
| Item | Why it matters | The base case needs |
|---|---|---|
| Volume | +0.5% of sales in the third quarter; the base case needs about 4.5% a year in low voltage from 2027 | Positive, and 2027 guidance near 3–4% |
| Margin without hedge gains | About 9.6% in the third quarter; $83 million of gains expected over the next 12 months | Near 10%, with the 2027 guidance showing how much hedge gain remains |
| Net pricing | +$21 million in the third quarter, after price cuts earlier in the year | Price cuts covered by savings |
| Free cash flow | $28–78 million left for the fourth quarter by the guidance | Within the range |
| The three largest customers | 53% of sales in the third quarter | No higher |
| 2027 guidance | The first full-year outlook as a standalone company | Sales growth above production; EBITDA above $990 million |
Update — October 15, 2026: the asymmetry, the money, the debt and where Versigent is — ACCUMULATE, target $54 → $48
Written against the October 14, 2026 close of $42.56. Sources: the information statement, the second-quarter 2026 10-Q and results, the indenture and credit agreement filed with the spin; Mobility Global’s and AutoForecast Solutions’ light-vehicle forecasts, Cox Automotive and ACEA for production and inventory, Aptiv’s and Lear’s results for history; job postings, news reports and Aptiv’s plant lists for the sites. The three scenarios of October 8, 2026 are unchanged. The analyses below are left as published; this section sets the scenario weights and adds stress tests, the money, the debt, the footprint, short interest and volatility. The rating is unchanged; the target moves from $54 to $48 because the weights change.
The one-line version
Versigent still offers more upside than downside, but less than the October 8, 2026 target said. Weighted 10% best, 60% base and 30% worst, it is worth about $48, an expected return of 14% with just under $2 of probability-weighted gain for each $1 of loss; the price implies a 40% chance of the worst case. Three carmakers buy 52% of what it makes, and the industry expects flat or lower production in 2027, which is why the weights lean toward the downside. The biggest lever is the gap between the price cuts carmakers take and the savings that pay for them: half a point either way is worth about $14 a share. The debt is manageable in the base case; in the worst case about $0.4 billion would need refinancing in 2031.
How the money moves
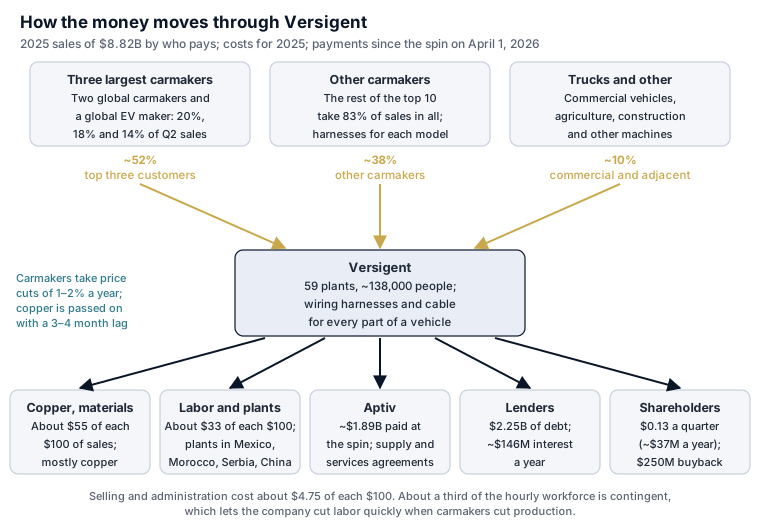
Who pays:
- Three carmakers took 52% of second-quarter 2026 sales: 20%, 18% and 14%. The filings do not name them; they describe two “Global OEMs” and a “Global EV OEM”, and name GM, Ford and Stellantis among the largest customers. The top ten took 83%, and the share of the top three rose from 47% in 2025.
- Orders carry no minimum quantities: Versigent sells what carmakers build, and accepts price cuts of 1–2% a year over each program’s life.
- About 10% of sales go to trucks and other machines, such as agriculture and construction.
- By region, 2025 sales were 43% in the Americas, 33% in Asia and 24% in Europe, the Middle East and Africa.
Where each $100 of revenue went, 2025, as if standalone (2025 carve-out results with standalone interest). Material, mostly copper, is about $55 of each $100 of sales; contracts pass on part of copper’s moves with a lag. Capital spending was unusually low in 2025 (1.8% of sales); 2026 guidance implies about 2.5%, and 2026 free cash flow is guided to $200–300M, about $2.60 per $100, after separation and restructuring costs. Source: the information statement and the second-quarter 2026 10-Q; per-$100 figures are calculations.
About $4.60 of each $100 became free cash flow in 2025 as a standalone company (an estimate). It is thin because copper and other materials take about $55 of each $100, and labor and plants most of the rest. Copper is passed on to customers for about three-quarters of the exposure, with a lag of three to four months, so a copper rise squeezes the margin for a quarter or two; copper is now about 10% above the price management assumed in its 2026 guidance.
The debt, tranche by tranche
The debt was raised before the April 1, 2026 spin, and about $1.89 billion went to Aptiv.
| Tranche | Amount ($M) | Rate | Matures | Repaying early | Security | Notes |
|---|---|---|---|---|---|---|
| 6.125% senior notes | 800 | 6.125% fixed | April 15, 2031 | Make-whole to April 15, 2028; then 103.063%, 101.531%, par from 2030 | Senior unsecured; guaranteed by the credit-facility guarantors | |
| 6.375% senior notes | 800 | 6.375% fixed | April 15, 2034 | Make-whole to April 15, 2029; then 103.188%, 101.594%, par from 2031 | Senior unsecured; guaranteed | |
| Term loan A | 500 | SOFR + 1.50% (grid 1.25–2.00% by leverage) | About April 2031 | At par | Senior secured | Repays 1.25–2.50% a quarter from June 2027 |
| Finance leases and local debt | 151 | Various | Mostly within a year | — | — | Mostly non-U.S. subsidiaries |
| Total drawn | 2,251 | ~6.0% (notes fixed at 6.125% and 6.375%; term loan A floating at SOFR + 1.50%) | ||||
| Revolving credit | $850M | SOFR + 1.25–2.00%; 0.20–0.35% on the unused amount | About April 2031 | Senior secured | Undrawn; no letters of credit |
The notes and the term loan were raised before the April 1, 2026 spin; about $1.89 billion was paid to Aptiv. No interest-rate hedges. Finance leases and local borrowings of $151M, mostly due within a year, are shown separately. Source: the second-quarter 2026 10-Q, Note 10, the indenture and the credit agreement. As of June 30, 2026.
Principal due by year, including scheduled amortization. Nothing beyond term-loan amortization is due before 2031.
The base case repays the 2031 maturities from its own cash; the worst case falls short. Comparing the cash available by April 2031 with the debt due by then (estimates):
| Base case | Worst case | |
|---|---|---|
| Free cash flow, July 2026–March 2031 | $1.65B | $0.70B |
| Dividends at $0.13 a quarter | − ~$0.18B | − ~$0.18B |
| Cash at June 30, 2026 | + ~$0.55B | + ~$0.55B |
| Available to repay debt | = ~$2.03B | = ~$1.08B |
| 2031 notes, term loan and local debt | − $1.45B | − $1.45B |
| Cash left after repaying them | = ~$0.58B | = − ~$0.37B (short) |
In the worst case about $0.37 billion would need refinancing in 2031, or a smaller dividend, before any buybacks; the $0.8 billion of notes due in 2034 come after that. The $250 million buyback authorised in April 2026 has not been used.
Interest expense, 2026–2031
Most of the debt is fixed. The $1.6 billion of notes pay 6.125% and 6.375%; the $500 million term loan floats at SOFR plus 1.50% and is unhedged. On the SOFR path priced in fed funds futures on October 9, 2026, as on the site’s other profiles (all figures estimates, $ millions):
| $ millions | 2026* | 2027 | 2028 | 2029 | 2030 | 2031 |
|---|---|---|---|---|---|---|
| SOFR, yearly average | ~3.75% | ~4.40% | ~4.65% | ~4.65% | ~4.65% | ~4.65% |
| 6.125% notes, 2031 | $37 | $49 | $49 | $49 | $49 | $49 |
| 6.375% notes, 2034 | + $38 | + $51 | + $51 | + $51 | + $51 | + $51 |
| Term loan A (SOFR + 1.50%) | + $20 | + $29 | + $29 | + $26 | + $24 | + $6 |
| Revolver fee, leases and local debt | + $11 | + $11 | + $11 | + $11 | + $11 | + $11 |
| Issuance costs written off (non-cash) | + $6 | + $6 | + $6 | + $6 | + $6 | + $6 |
| Interest expense | = ~$112 | = ~$146 | = ~$146 | = ~$144 | = ~$142 | = ~$123 |
*2026 from the April 1 spin. 2031 assumes the term loan is repaid at its April maturity. Source: model in the site’s analysis files.
Each point of SOFR costs about $5 million a year, about $0.05 a share after tax; one point lower saves about the same.
| Covenant | Limit | Now | Room | Protects |
|---|---|---|---|---|
| Total leverage (debt less up to $500M of cash, over EBITDA as the agreement defines it, which adds back restructuring and up to 25% for cost savings) | 4.25× for the first four tests (from June 30, 2026), then 4.00×, then 3.75× | ~1.9× at June 30, 2026 (an estimate) | EBITDA could fall about half | Credit agreement |
| Interest coverage (EBITDA over net cash interest) | At least 3.00× | ~7× (an estimate) | Wide | Credit agreement |
| Dividends and buybacks | $250M a year plus up to 7% of market value; unlimited at total leverage of 1.80× or less | ~1.9×, just above the unlimited level | The $250M buyback and $0.13 quarterly dividend fit | Credit agreement (the notes have no such covenant) |
| Change of control | Notes: 101% repurchase only if control changes and two agencies cut the rating below investment grade. Bank debt: default if anyone holds over 50% | — | — | Notes; bank debt |
| Mergers and buybacks (tax matters agreement with Aptiv, not the debt) | To about April 2, 2028: no sale of 40% or more of the stock in a combined transaction, no merger, no sale of over 20% of assets; buybacks only within the IRS open-market safe harbour | $250M authorized April 2026; none disclosed through June 30, 2026 | Restrictions end about April 2, 2028 | Shares and M&A |
No ratings are disclosed in the filings; a third-party source reports Ba2/BB-/BB+. The collateral and guarantees on the bank debt fall away if two agencies rate it investment grade.
The covenants have room, though less in a downturn. Total leverage is about 1.9 times against a 4.25 times limit that steps down to 3.75 times; in the worst case, with EBITDA falling to about $630 million in 2027, it rises to about 2.8–2.9 times, and interest coverage stays above four times against the 3.00 minimum.
Where Versigent is
Versigent builds harnesses by hand, close to the carmakers and where labor is cheap. The Form 10 counts 59 manufacturing sites in 25 countries and six technical centers but names none; the sites below come from job postings, news reports and Aptiv’s plant lists, and most are placed at the city centre.
59 manufacturing sites in 25 countries (Americas 23, Europe, Middle East and Africa 15, China 13, rest of Asia 8) and about 138,000 employees, 43% in the Americas, 23% in EMEA, 22% in China and 12% in the rest of Asia. Most points are placed at the city centre. Click a point for details. Map data © OpenStreetMap contributors. Source: the information statement (site counts, employees, sales by region) and, for individual sites, Versigent job postings, news reports and Aptiv’s plant lists; coordinates from OpenStreetMap. As of October 15, 2026.
Mexico: the harness plants that supply U.S. assembly lines, many near the border (Ciudad Juárez, Nuevo Laredo) and in Chihuahua, Durango, Nuevo León and Zacatecas. Versigent reports this production as U.S. sales; Aptiv said over 99% of its Mexican imports were USMCA-compliant in 2025. Click a point for details. Map data © OpenStreetMap contributors. Source: the information statement (site counts, employees, sales by region) and, for individual sites, Versigent job postings, news reports and Aptiv’s plant lists; coordinates from OpenStreetMap. As of October 15, 2026.
Europe and North Africa: plants in Morocco (Tangier, Kenitra, Meknès, Oujda), Serbia, Tunisia, Romania, Poland, Portugal, Hungary and Turkey supply European carmakers, with engineering offices next to customers in Germany, France, Czechia and Sweden. Sales in the region fell 11% in the second quarter of 2026. Click a point for details. Map data © OpenStreetMap contributors. Source: the information statement (site counts, employees, sales by region) and, for individual sites, Versigent job postings, news reports and Aptiv’s plant lists; coordinates from OpenStreetMap. As of October 15, 2026.
- About 138,000 people work for Versigent: 43% in the Americas (mostly Mexico), 23% in Europe, the Middle East and Africa (mostly Morocco and Serbia), 22% in China and 12% in the rest of Asia (mostly India). About a third of the hourly workforce is contingent, which lets the company cut labor quickly.
- Mexico supplies U.S. assembly lines, from plants near the border and in Chihuahua, Durango, Nuevo León and Zacatecas. Versigent reports this production as U.S. sales and does not disclose how much qualifies under the trade agreement with Canada and Mexico; Aptiv said over 99% of its Mexican imports did in 2025. The annual reviews of that agreement, after the U.S. declined to renew it in July 2026, are the main tariff risk.
- Morocco and Serbia supply Europe, where sales fell 11% in the second quarter of 2026 and a European plant is being closed.
- China has a technical center and plants in Shanghai, Wuhan (a new plant opened in August 2026) and other cities; more than a third of Chinese output is now exported.
The scenarios and the asymmetry
The three cases are the ones built on October 8, 2026: best $81.15 (low-voltage volume up 5.5–6.5% a year and high voltage recovering to +12%), base $55.69 (low voltage up 4–4.5%, price cuts of 1.5% a year offset by productivity) and worst $22.60 (a 2027 recession, then a lost program at a top-three customer in 2028 and hedge gains reversing), against $42.56 (+91%, +31% and −47%).
Stress tests, one change at a time (estimates):
| Change | Value | vs $42.56 |
|---|---|---|
| A 2027 recession at the worst case’s depth, without the lost program | $27.07 | −36% |
| Price cuts of 2% of sales a year (not 1.5%) | $41.51 | −2% |
| Flat 2027 volume, as the industry forecasts now suggest, then the base path | $46.59 | +9% |
| A lost top-three program in 2028 alone | $49.26 | +16% |
| Hedge gains falling $90 million in 2027 (not $50 million) | $52.20 | +23% |
| Price cuts of 1% of sales a year | $70.06 | +65% |
Three weightings, and what the price implies. The standard set, 25 / 50 / 25, and the stress set, 10 / 40 / 50, are the same for every company; the best guess drives the target and the two chips at the top of the page.
| Weights, best / base / worst | Value | Expected return | Gain to loss |
|---|---|---|---|
| Standard: 25 / 50 / 25 | $53.78 | +26% | 3.3 to 1 |
| Best guess: 10 / 60 / 30 | $48.31 | +14% | 1.96 to 1 |
| Stress: 10 / 40 / 50 | $41.69 | −2% | 0.9 to 1 |
| What the price implies: 0 / 60 / 40 | $42.56 | 0% | 1.0 to 1 |
The weights are a judgement. All values are estimates from the model.
Why the best guess leans toward the downside:
- The best case is unlikely, about 10%. It needs low-voltage volume growth of about 6% a year, one and a half to two times management’s own framework of 3–4% growth, against industry forecasts of flat or lower production in 2027 (North America about flat, Europe about −2%, China weaker) and a guidance that implies flat volume in the second half of 2026. High voltage is still shrinking, and GM and Ford have cancelled electric-vehicle programs.
- The worst case gets 30%. The full combination, a deep recession and a lost top-three program, is unlikely on its own, perhaps 5%; but the more likely bad outcomes sit close to it. A recession of that depth without the lost program is worth $27; recession odds for the next twelve months are 20–29% on the main surveys; and three customers buying 52% of sales, with no minimum quantities, leave little room if one of them cuts.
- The base case takes 60%: awards have held up ($5.4 billion in the first half of 2026) and Asia and North America are growing, but the industry is flat.
- Evidence that would move the weights: a cut to 2026 guidance, or EBITDA margin below 10% on copper, in the third-quarter results (worst case up); volume growth held near 4% with the margin intact (worst case down).
What the price implies. Holding the base case at its 60% weight, even no weight on the best case leaves 60% base and 40% worst worth $42.45, about the price. So the market gives the best case no chance and the worst case about 40%, solving
base weight × $55.69 + (100% − base weight) × $22.60 = $42.56
for a base weight of ($42.56 − $22.60) ÷ ($55.69 − $22.60) = 60%.
The asymmetry on the best guess:
| Measure | At $42.56 | What it means |
|---|---|---|
| Expected return (header chip) | +14% | The probability-weighted value, $48.31, against the price |
| Gain to loss (header chip) | 1.96 to 1 | +$11.74 of probability-weighted gain against −$5.99 of loss |
| Expected base-case gain ÷ expected worst-case loss | 1.3 to 1 | +$7.88 against −$5.99: the likely outcome pays for the bad one without the best case |
| Best-case gain ÷ worst-case loss | 1.9 to 1 | +$38.59 against −$19.96 |
| Base-case gain ÷ worst-case loss | 0.66 to 1 | +$13.13 against −$19.96 |
How the measures are calculated. Gain = case value − price; loss = price − case value. Weights are the best guess: 10% best, 60% base, 30% worst.
| Measure | Formula | At $42.56 |
|---|---|---|
| Expected return | (10% × best + 60% × base + 30% × worst) ÷ price − 1 | ($8.12 + $33.41 + $6.78) ÷ $42.56 − 1 = +14% |
| Gain to loss | (10% × best gain + 60% × base gain) ÷ (30% × worst loss) | ($3.86 + $7.88) ÷ $5.99 = 1.96 |
| Expected base ÷ expected worst | (60% × base gain) ÷ (30% × worst loss) | $7.88 ÷ $5.99 = 1.3 |
| Best ÷ worst | best gain ÷ worst loss | $38.59 ÷ $19.96 = 1.9 |
| Base ÷ worst | base gain ÷ worst loss | $13.13 ÷ $19.96 = 0.66 |
| Price-implied base weight, best at zero | (price − worst) ÷ (base − worst) | ($42.56 − $22.60) ÷ $33.09 = 60% |
The header chips are green at +25% or more and 3 to 1 or better, blue at +10–25% and 2–3 to 1, orange at 0–10% and 1–2 to 1, and red below zero and below 1 to 1. On the best guess, expected return is green below $38.65, blue up to $43.92 and orange up to $48.31; gain to loss is green below $38.67, blue up to $42.38 and orange up to $48.31. Both are red above $48.31. At $42.56 gain to loss is just below two to one, so its chip is orange.
Short interest and volatility
The tables below show how much of the stock is sold short and how much the price moves. They are inputs to the weights above, and the tables update with the nightly data.
| Report | Settled | Short | % float | % outst. | Days to cover |
|---|---|---|---|---|---|
| First after the spin | Apr 15, 2026 | 1.71M | 2.4% | 2.4% | 1.0 |
| Lowest since the spin | May 29, 2026 | 1.60M | 2.3% | 2.2% | 1.3 |
| Three months earlier | Jul 15, 2026 | 4.03M | 5.8% | 5.7% | 3.4 |
| Latest | Oct 30, 2026 | 2.21M | 3.1% | 3.1% | 3.5 |
The latest share of float is higher than 4 of the 13 earlier reports since the spin. Short interest in shares, with its share of the float and of shares outstanding. FINRA settlement dates; figures are published about eight business days later. Days to cover is short interest divided by average daily volume, as reported by FINRA. Float and shares outstanding on or before each date, from this site's daily share records and the company's filings.
Short interest is moderate, at 3.7% of the float on September 30, 2026, down from 5.7% at the end of June; days to cover rose to 3.0 as trading volume fell. It does not change the weights.
| Volatility, annualized | Last 20 sessions | Last 60 sessions | Since the spin |
|---|---|---|---|
| To November 13, 2026 | 29% | 38% | 51% |
At the last 60 sessions' volatility, one standard deviation over a month is about ±12%, or $37.79 to $47.11 from the $42.19 close; about two months in three end inside that range if volatility holds. The median daily move since the spin is 1.7%.
| Results day | Released | Close before | Close after | Move | Times a median day |
|---|---|---|---|---|---|
| May 5, 2026 | After the close | $37.50 | $41.55 | +10.8% | 6.4× |
| August 4, 2026 | Before the open | $42.04 | $45.80 | +8.9% | 5.3× |
| November 4, 2026 | Before the open | $40.69 | $41.97 | +3.1% | 1.9× |
Average move on a results day: 7.6% either way, against a median day's 1.7%. The move is measured from the close before the release to the close of the first session after it.
Both results days moved the stock up sharply, +10.8% and +8.9%, against a median day’s 1.8%. The October 2026 fall, from $47.37 on October 6 to $42.56, came without company news, while Aptiv and Lear fell about 2%: copper near record highs and a director’s planned sales are the visible factors. The November 4, 2026 results show whether copper has squeezed the margin and whether second-half volume is flat, as the guidance implies.
What it means for the rating
ACCUMULATE, target $54 → $48. The target is the best-guess value, $48.31; the October 8, 2026 target used the standard weights. At $42.56 the expected return is about 14% and the gain to loss about two to one, and the base case alone is 31% above the price, so the upside does not depend on the best case. It is ACCUMULATE rather than BUY because three customers buy half the output, the industry outlook for 2027 is flat, and the worst case is close to half the price.
| Action | Level | Reason |
|---|---|---|
| Buy | Below about $39 | Both chips green: expected return above 25% and gain to loss above 3 to 1 |
| Accumulate | $39–44 | Expected return 10–25% |
| Hold | $44–56 | |
| Trim | Above $56 | The base case |
| Move to HOLD | 2026 guidance cut, or EBITDA margin below 10% on copper or volume | |
| Move to BUY | Volume growth near 4% and margin held through the copper peak, with buybacks started |
The table of what the third-quarter results must show, in the October 8, 2026 update below, stands, with two additions: the effect of copper on the margin, and any change in the share of the three largest customers.
Update — October 9, 2026: who has been trading Versigent, and the October 2026 dip
Written against the October 8, 2026 close of $44.16; peer comparisons run to the October 9, 2026 close of $44.74. Sources: Versigent’s SEC filings since the spin, including director Kevin Clark’s Form 4 and Form 144 and the Schedule 13G filings of BlackRock and Vanguard; S&P Dow Jones Indices' March 30, 2026 announcement and its quarterly rebalance announcements since; FTSE Russell’s June 2026 reconstitution and September 2026 FTSE review; MSCI’s May and August 2026 reviews; FINRA short-interest and off-exchange volume data; the SEC’s Form 13F data sets for December 31, 2025 and June 30, 2026; funds’ Forms N-PORT and SPDR’s daily holdings files; and closing prices for the stock and its peers. The analyses below are left as published. The rating and target are unchanged; this section is about the trading.
The one-line version
Versigent has traded with the auto suppliers since the spin, and in September 2026 it fell 10.5% against 12.2% for the group. The 5.6% decline from October 6, 2026 to October 9, 2026 followed a 5.4% rise in the week before and came on the day the 10-year Treasury yield reached its highest level since 2002; from September 30, 2026 to October 9, 2026 the stock was down 0.4%, in line with the suppliers. Since the spin it is up 61% while the suppliers are flat. The forced trades were index moves at the spin and at the Russell reconstitution in June 2026. Most of the active managers that owned Aptiv sold the Versigent shares they received, and index funds, AllianceBernstein, Fidelity and a group of hedge funds bought them. The one insider seller, director Kevin Clark, has room under his trading plan to sell about 97,000 more shares by the end of the year.
What the price did
| Aug 31 – Sep 4, 2026 | Sep 4 – Sep 30, 2026 | Sep 30 – Oct 6, 2026 | Oct 6 – Oct 9, 2026 | |
|---|---|---|---|---|
| Versigent | +5.9% | −10.5% | +5.4% | −5.6% |
| Auto suppliers (Lear, BorgWarner, Magna, Adient, Visteon, Autoliv) | +4.6% | −12.2% | +3.3% | −2.4% |
| Carmakers (General Motors, Ford, Stellantis) | +2.6% | −17.1% | +4.7% | −1.2% |
| Aptiv | +7.1% | −10.3% | +4.0% | −2.5% |
| Russell 2000 | +0.7% | −6.1% | +1.2% | −0.7% |
| S&P 500 | +0.4% | −1.0% | +2.2% | −0.1% |
Closing prices rebased to August 31 = 100. Baskets are equal-weighted: auto suppliers (Lear, BorgWarner, Magna, Adient, Visteon, Autoliv); carmakers (General Motors, Ford, Stellantis); Aptiv, the former parent; Russell 2000 and S&P 500 through their ETFs (IWM, SPY). Source: Yahoo Finance closes.
From August 31 to October 9, 2026 Versigent fell 5.6%, against 7.3% for the auto suppliers and 11.9% for the carmakers. Its daily returns since the end of July 2026 correlate at 0.76 with the suppliers and 0.65 with the carmakers, and at 0.06 with Aptiv, which now trades as a different business.
September 2026 was a sector decline. U.S. carmakers reported weak third-quarter sales (General Motors −5.5%, Ford −6.6%, Stellantis flat with Jeep down 20%), the 50% U.S. tariffs on Canadian vehicles and parts announced in late August 2026 loomed over 2027, and the USMCA review stayed deadlocked over U.S. content rules and the Section 232 tariffs on Mexican vehicles; in early October 2026 several European carmakers, among them Volkswagen and Volvo Cars, cut their outlooks. Analysts cut targets across the suppliers, including JPMorgan’s downgrades of Aptiv and Lear.
October 7 and 8, 2026 were the only days Versigent fell much more than its peers, 4.4% and 2.5% against about 1.5% and 0.7% for the suppliers. October 7, 2026 was the day the 10-year yield touched 5.365% and industrial stocks led the market down; Goldman Sachs had trimmed its Versigent target by a dollar, to $58, with a Buy rating the day before. No company news, filing or analyst action on either day has been found. On October 8, 2026, 71% of the off-exchange volume was recorded as short sales, against 30–50% on most days; that figure includes market makers’ trading and is a weak signal on its own.
Turnover since the spin
Daily volume (bars) and cumulative volume as a share of the 70.8 million shares outstanding (line). Gold bars mark days with a notable event; hover over one to see what happened. Source: this site's daily price archive (Yahoo Finance), through Oct 8, 2026.
| Average daily volume | Share of the company traded | Close | |
|---|---|---|---|
| April 2026 | 4.2M | 124.5% | $34.97 |
| May 2026 | 1.4M | 40.2% | $44.12 |
| June 2026 | 1.9M | 57.1% | $42.01 |
| July 2026 | 1.1M | 32.7% | $41.35 |
| August 2026 | 0.8M | 24.8% | $47.40 |
| September 2026 | 0.8M | 22.7% | $44.94 |
| October 2026 to the 8th | 0.8M | 6.5% | $44.16 |
| Since the spin | 308.5% |
Two index events account for the heaviest days. S&P Dow Jones Indices placed Versigent in the S&P SmallCap 600 from April 2, 2026, so S&P 500 index funds that received it sold at the close on April 1, 2026, when 27.2 million shares, 38% of the company, traded. Versigent entered the Russell indexes in the Russell 1000, as part of Aptiv, and at the June 2026 reconstitution it moved to the Russell 2000: on June 26, 2026, 12.3 million shares traded, nine times June 2026’s normal volume, as small-cap index funds bought. MSCI holds it in its small-cap index, FTSE removed it from the FTSE All-World index at the close on September 18, 2026, and no S&P rebalance has touched it since April 2026. Volume has settled at about 0.8 million shares a day since August 2026.
Who has been buying and selling
One insider has sold and none has bought. Director Kevin Clark sold 122,722 shares on September 8 and 9, 2026 at $44.99–50.12, about $5.7 million, under a Rule 10b5-1 plan adopted on June 3, 2026. His Form 144 registered up to 220,000 shares, and the plan runs to December 31, 2026, so up to about 97,000 more shares can be sold under it. He holds 124,849 shares directly. The other insider filings are awards, tax withholding and dividend equivalents.
The company has not bought. The board authorized a $250 million repurchase program in April 2026; the second-quarter 10-Q reports no purchases.
Short interest rose around the Russell move and has eased since:
| Settlement date | Shares sold short | % of shares | Days of volume |
|---|---|---|---|
| May 29, 2026 | 1.60M | 2.3% | 1.3 |
| June 15, 2026 | 2.42M | 3.4% | 1.8 |
| June 30, 2026 | 4.03M | 5.7% | 1.6 |
| July 31, 2026 | 3.31M | 4.7% | 3.6 |
| August 31, 2026 | 3.42M | 4.8% | 5.3 |
| September 15, 2026 | 3.04M | 4.3% | 4.7 |
The rise in days of volume reflects lower trading; the short position itself has fallen by a quarter from its June 2026 peak. The September 30, 2026 figure has not yet been published.
Holders. Aptiv’s holders received one Versigent share for every three Aptiv shares. Their entitlements, estimated from their Aptiv 13F positions at December 31 and March 31, 2026, compared with their Versigent positions at June 30, 2026:
| Holder | Shares received (estimated) | June 30, 2026 | Change |
|---|---|---|---|
| BlackRock | 6.3M | 11.2M | Added, through S&P 600 and Russell 2000 funds |
| Vanguard | 8.4M | 8.2M | Held |
| State Street | 3.3M | 2.9M | −12% |
| Geode | 1.9M | 1.8M | Held |
| Norges Bank | 2.8M | 1.5M | −46% |
| MFS | 2.9M | 0.5M | −84% |
| Hotchkis & Wiley | 1.2M | 1.0M | −11% |
| Barrow Hanley | 1.7M | 0 | Sold out |
| UBS Asset Management | 1.7M | 0 | Sold out |
| Nordea | 1.6M | 0.1M | −94% |
| Impax | 1.5M | 0 | Sold out |
| Boston Partners | 1.4M | 0 | Sold out |
| Allspring | 1.0M | 0 | Sold out |
The active managers that held Aptiv sold most of the wiring business they received; Barrow Hanley sold all of it while adding to Aptiv. The buyers were index funds, AllianceBernstein (3.4 million shares at June 30, 2026), Fidelity (2.8 million), Capital International (1.3 million) and a group of hedge funds that had not owned Aptiv, among them Greenlight (2.3 million, filing as DME Capital), Voss, Moore, Woodline and Rubric (each about 0.9–1.0 million), Soros, Citadel, Marshall Wace and ExodusPoint. BlackRock reported 15.0% of the shares on its Schedule 13G at June 30, 2026, and Vanguard’s two filing entities 11.5% together.
The holders who sold in September and October 2026 will be identifiable from the third-quarter Forms 13F, due by about November 16, 2026. A shareholder base with a large hedge-fund component after a 61% rise is more likely than an index-heavy one to trade around results and macro news, which fits the two outsized down days in October 2026, but no filing yet shows who sold on them.
A note on an earlier section
The October 6, 2026 update recorded Kevin Clark’s sale of about 122,700 shares and gave the prices as $45.49–49.67, which are the weighted averages of the individual lots; the full range of prices was $44.99–50.12. The same update did not report that the Form 144 and the trading plan allow sales of up to 220,000 shares through December 31, 2026, which leaves about 97,000 shares that can still be sold.
What it means for the rating
The rating stays ACCUMULATE and the target $54. The trading since August 2026 shows a stock moving with its sector and slightly ahead of it, and the October 2026 dip reversed a short rally on a day of broad selling in industrial stocks. At $44.16 the price is below the $46 level where the October 8, 2026 update recommends accumulating. The third-quarter results on November 4, 2026 are the next test: the adjusted EBITDA margin with hedge gains shown separately, and price cuts against productivity in the company’s own bridge.
Update — October 8, 2026: the valuation by scenario — BUY → ACCUMULATE, target $54
Written against the October 7 close of $45.29. Sources: the Form 10 information statement (three years of audited carve-out financials), the first-quarter and second-quarter 10-Qs, and the second-quarter results release with its guidance. Forecasts and scenario values are estimates. The October 6 and August 25 analyses below are left as published; this section builds the forecast line by line, corrects two statements, and replaces the target.
The one-line version
About half of this year’s revenue growth is copper and currency passed through to customers, which earns nothing. Underlying growth is 4–5%, not 10%. Built line by line, the base case is worth $56 a share, the best case $81 and the worst case $23; weighted, $54, 19% above the price.
The value turns on one spread: the 1–3% price cuts carmakers take every year against the cost savings that pay for them. Half a point either way is worth about $14 a share, more than volume, electric vehicles or working capital.
The market prices the base case at a 5× exit multiple. The stock is cheap, but less cheap than a $62 target said, and the worst case — a recession, a lost program and the hedge gains reversing — halves it.
Rating: BUY → ACCUMULATE · Target $62 → $54 · Grade: B+ (3.20), unchanged
Revenue, line by line
From the Form 10 and the 10-Qs, in millions of dollars.
| 2023 | 2024 | 2025 | H1 2025 | H1 2026 | H1 change | |
|---|---|---|---|---|---|---|
| Low voltage electrical architecture | 7,807 | 7,496 | 7,876 | 3,745 | 4,227 | +12.9% |
| High voltage electrical architecture | 1,025 | 813 | 942 | 485 | 429 | −11.5% |
| Total | 8,832 | 8,309 | 8,818 | 4,230 | 4,656 | +10.1% |
Where the change comes from. The company splits every change in sales into volume (net of the price cuts in its contracts), currency, and commodity pass-through — copper costs recovered from customers through escalation clauses:
| Change in sales | Volume, net of price cuts | Currency | Copper pass-through | Total |
|---|---|---|---|---|
| 2024 | −554 | −41 | +72 | −523 |
| 2025 | +372 | +52 | +85 | +509 |
| First quarter 2026 | +66 | +66 | +56 | +188 |
| Second quarter 2026 | +102 | +40 | +96 | +238 |
The headline growth is about half real. The company’s own adjusted growth, excluding currency and commodities, was 5% in the second quarter and 4% in the first half, against 10.8% and 10.1% reported. Pass-through protects profit dollars but adds none: in the second quarter, copper added $96 million of sales and cost $9 million of EBITDA, because the recovery lags the cost.
Low voltage — about 90% of sales: the business, and growing
Wiring harnesses, cables and connectors. Volume rose 5% in 2025 against global vehicle production of +4%, and 3% in the first quarter of 2026 against production of −3%: Versigent is gaining share on new programs. 2024 is the resilience test: volume fell 8%, yet adjusted EBITDA margin slipped only from 9.8% to 9.3%, because restructuring and cost actions absorbed most of it.
High voltage — about 10% of sales: small, volatile and shrinking
The electric-vehicle architecture: $1,025 million in 2023, $813 million in 2024, $942 million in 2025, and down 11.5% in the first half of 2026 as carmakers slow electric programs. It is too small to carry the company either way.
By region, first half of 2026
| Region | H1 2026 | Change | Note |
|---|---|---|---|
| North America | 1,919 | +10% | Much of it built in Mexico; the USMCA review is open |
| Asia Pacific | 1,564 | +20% | Mainly China |
| Europe, Middle East and Africa | 1,033 | −3% | Shrinking with European production |
| South America | 140 | +21% |
Customers
Three customers took 52% of second-quarter sales (20%, 18% and 14%), one of them a manufacturer of electric vehicles only; the top ten took 83%. There are no long-term supply contracts: sales run on purchase orders and production schedules under multi-year program awards. Losing a program at one of the three is the largest single risk the company carries.
What the guidance implies for the second half. Net sales of $9.4–9.6 billion means second-half growth of 3.4% to 7.8%; adjusted EBITDA of $950–1,030 million means second-half EBITDA of $475–555 million against about $480 million a year earlier.
Corrections to the October 6 and August 25 analyses
- “Price / second-quarter adjusted EPS, annualized ($1.92 × 4): 6.2×” (October 6) and the 7.1× P/E on second-quarter annualized earnings (August 25). The second quarter carried the best margin in the company’s record (11.1% adjusted EBITDA), so four times it overstates a year. On the base case below, 2027 adjusted EPS is $6.52, a P/E of about 6.9×. The 2026 figure of about $7.55 is itself flattered by a first quarter with a tax benefit and almost no interest, since the debt was raised at the spin.
- “EV / 2026 adjusted EBITDA 5.1×” (October 6) is right on guidance, but 2026 is not the base for what follows: the base case has 2027 EBITDA slightly lower, $976 million, as part of the $102 million of hedge gains expected over the next twelve months fails to repeat.
Three scenarios, built line by line
Each product line grows on its own volume; contractual price cuts are charged separately at 100% to profit, as they are in practice; pass-through moves sales but not EBITDA. 2026 is anchored to guidance (EBITDA $955 million, $990 million and $1,025 million; free cash flow $200 million, $250 million and $300 million).
| Driver, a year, 2027–2030 | Best | Base | Worst | Evidence |
|---|---|---|---|---|
| Low voltage volume, before price cuts | +5.5–6.5% | +4–4.5% | −8.5% in 2027, then +0.5% to +4.5% | Volume +5% in 2025; −8% in 2024 |
| High voltage volume | +11.5–13.5% | +1.5–6.5% | −13.5% in 2027, then +1.5–3.5% | −11.5% in H1 2026 |
| Contractual price cuts, % of sales | 1.5% | 1.5% | 1.5% | “Typically 1% to 3%” per the filings |
| Cost productivity, % of sales | 0.8% | 0.8% | 0.9%, plus 1% more cost-out in 2028 | Margin held through 2024 |
| EBITDA on each extra dollar of volume | 25% | 25% | 20% | Q2 2026: $30M on $120M of volume |
| Hedge gains not repeated in 2027 | $20M | $50M | $90M | $102M expected over the next twelve months |
| Copper pass-through | +1% of sales in 2027 | none | −3% of sales in 2027 | Moves sales, not profit |
| A lost program at a top-three customer | — | — | −4% of sales in 2028 | Three customers are 52% of sales |
Below EBITDA, the same in each case: depreciation 2.3% of sales; interest $140 million a year (the second quarter was $36 million); tax 22%; $20 million to minority partners in consolidated joint ventures; $15 million of equity income; 71.9 million diluted shares. Free cash flow also carries restructuring of $50–110 million a year, capital spending of 2.6–2.8% of sales, and working capital of 12–14% of each dollar of sales growth.
| $ millions | 2025 | 2026E | 2027E | 2028E | 2029E | 2030E |
|---|---|---|---|---|---|---|
| Base — net sales | 8,818 | 9,476 | 9,735 | 10,027 | 10,299 | 10,580 |
| Low voltage | 7,876 | 8,627 | 8,885 | 9,152 | 9,381 | 9,615 |
| High voltage | 942 | 849 | 849 | 875 | 919 | 965 |
| Adjusted EBITDA | 896 | 990 | 976 | 1,020 | 1,057 | 1,096 |
| EBITDA margin | 10.2% | 10.4% | 10.0% | 10.2% | 10.3% | 10.4% |
| Adjusted EPS | $7.55 | $6.52 | $6.93 | $7.27 | $7.62 | |
| GAAP EPS | $5.93 | $5.77 | $6.17 | $6.51 | $6.86 | |
| Free cash flow | 481 | 250 | 308 | 331 | 357 | 379 |
| Best — net sales | 9,593 | 10,217 | 10,795 | 11,361 | 11,912 | |
| Adjusted EBITDA (margin) | 1,025 | 1,110 | 1,225 | 1,336 | 1,442 (12.1%) | |
| Adjusted EPS | $7.90 | $7.85 | $8.97 | $10.03 | $11.03 | |
| Free cash flow | 300 | 388 | 471 | 547 | 619 | |
| Worst — net sales | 9,354 | 8,126 | 7,754 | 7,980 | 8,139 | |
| Adjusted EBITDA (margin) | 955 | 630 | 606 | 630 | 639 (7.9%) | |
| Adjusted EPS | $7.20 | $3.18 | $3.00 | $3.21 | $3.27 | |
| Free cash flow | 200 | 269 | 137 | 68 | 81 |
The 2025 EBITDA is adjusted operating income plus depreciation from the Form 10, which matches the company’s definition within a few million dollars.
Three things the scenarios show:
- Free cash flow has stepped down for good. The $481 million of 2025 came before any interest, with capital spending at 1.8% of sales after two years of cuts. As a standalone company Versigent pays $140 million of interest and full taxes, and spends nearer 2.8%. The base case climbs back only to about $380 million by 2030.
- Working capital cushions a downturn. Receivables that absorbed cash on the way up release it on the way down, so in the worst case 2027 free cash flow rises while EBITDA falls by a third. The damage arrives in 2028–2030.
- Earnings fall in 2027 in every case but the best, as a full year of interest and a normal tax rate replace the first quarter’s.
The valuation, by scenario
The method of the August analysis, unchanged: free cash flow before interest discounted at 11.5%, a terminal value at 6× 2030 EBITDA, less net debt of $1,670 million at June 30. This bridge also deducts the $199 million book value of minority partners’ interests and adds the $149 million of equity-method affiliates, which the earlier bridge did not.
| Scenario | Enterprise value | Per share | vs $45.29 | Weight |
|---|---|---|---|---|
| Best | $7.6B | $81 | +79% | 25% |
| Base | $5.7B | $56 | +23% | 50% |
| Worst | $3.3B | $23 | −50% | 25% |
| Probability-weighted | $54 (53.79) | +19% |
| Discount rate | Best | Base | Worst | Weighted |
|---|---|---|---|---|
| 10.5% | $85 | $58 | $24 | $56 |
| 11.5% | $81 | $56 | $23 | $54 |
| 12.5% | $78 | $53 | $21 | $51 |
| Exit multiple, base case | Per share |
|---|---|
| 4.5× | $41 |
| 5× | $46 — today’s price |
| 6× | $56 |
| 7× | $66 |
The target is $54, the probability-weighted value. It replaces $62, which rested on a discounted cash flow that let margin rise to 8.5% of operating income without charging price cuts separately, and on 10× normalized earnings.
The 25 / 50 / 25 weights are a judgement, but here they move the answer little, because the two tails sit at similar distances from the base case:
| Weights, best / base / worst | Value per share |
|---|---|
| 30 / 50 / 20 | $57 |
| 25 / 50 / 25 (the target) | $54 |
| 20 / 60 / 20 | $54 |
| 15 / 70 / 15 | $55 |
| 10 / 80 / 10 | $55 |
| 10 / 60 / 30 | $48 |
What the price implies. Even with no weight at all on the best case and 25% on the worst, the value is $47, above the price. Weighing only the base and worst cases, $45.29 implies about a 31% chance of the worst case — a recession, a lost program and the hedge gains reversing, all within three years.
What the best case requires: low voltage volume growing 5.5–6.5% a year for four years — faster than in any year of the record, though first-half 2026 ran at 4–5% underlying; high voltage recovering to double-digit growth as electric programs resume; and copper adding a little to sales. Margin then reaches 12.1%, two points above anything the company has reported for a full year.
What the worst case requires — three things together:
- An auto recession in 2027: low voltage volume down 8.5%, high voltage down 13.5%, copper falling 3%
- A lost program at one of the three largest customers in 2028, 4% of sales
- $90 million of the hedge gains reversing, with cost savings lagging revenue for a year before a further 1% of sales is cut
Margin then settles near 7.9%, below the 2024 trough of 9.3%. This is harsher than the auto-recession scenario in the October 6 and August 25 analyses ($54), which assumed a one-year dip with no program loss and no hedge reversal.
Which assumption matters most
Changing one base-case driver at a time:
| One change to the base case | Per share | Change |
|---|---|---|
| Price cuts 1.0% a year, not 1.5% | $70 | +$14 |
| Price cuts 2.0% a year, not 1.5% | $42 | −$14 |
| Cost productivity 0.3 points higher | $65 | +$9 |
| Low voltage volume 1 point a year higher | $62 | +$6 |
| Low voltage volume 1 point a year lower | $50 | −$6 |
| No hedge gains lost in 2027 | $60 | +$4 |
| $100 million of hedge gains lost | $51 | −$4 |
| High voltage growing 10% a year | $59 | +$4 |
| Working capital at half the usage | $57 | +$1 |
This is a margin business, not a growth business. Every supplier gives back 1–3% of price each year; the ones that hold margin find the same amount in cost. Half a point either way on that spread outweighs a point of volume, the electric vehicle cycle and working capital combined. That is what the third-quarter margin, with the hedge gains shown separately, will begin to answer.
October recommendation
Rating: BUY → ACCUMULATE. Target: $62 → $54. Grade: B+ (3.20), unchanged.
What changed. The business did not. The line-by-line build finds underlying growth of 4–5% rather than 10%, charges the yearly price cuts that every supplier pays, and assumes part of this year’s hedge gains does not repeat. On those terms the base case is worth $56 and the weighted value $54, not $62. Nineteen percent of upside on a cyclical supplier with a worst case of −50% is a position to build gradually, not a full-size buy.
Why not HOLD.
- The median outcome is above the price. The base case is worth 23% more than $45.29, and the price implies about a one-in-three chance of the worst case.
- The tails are balanced. Unlike a story stock, the value does not depend on the best case: with no weight on it at all, the value is still above the price.
- The balance sheet carries a downturn. Nothing matures before 2031, and working capital releases cash in a recession.
Why not BUY.
- The upside is 19%, not 31%, and the stock moves with vehicle production, rates and tariffs.
- The margin case is one quarter old. The 11.1% second-quarter margin included hedge gains that will not all repeat; the third quarter is the first test.
- Concentration. Three customers are 52% of sales, and the USMCA review that governs the Mexican footprint is unresolved.
Action for October:
| Accumulate below $46 | The base case at a 5× exit multiple; today’s price |
| Hold between $46 and $54 | |
| Trim above $54 | The target; beyond it the price needs the best case |
| Back to BUY | Third-quarter adjusted EBITDA margin above 10.5% with hedge gains disclosed and excluded, and adjusted sales growth of 4% or more |
| Move to HOLD | Margin below 9.5% excluding hedges, or a disclosed program loss at one of the three largest customers |
What to watch in the third-quarter results (early November):
| Line | The test |
|---|---|
| Adjusted EBITDA margin | Above 10% with the hedge contribution shown separately |
| Price cuts against productivity | The company’s own bridge: pricing at −1% to −1.5% of sales, with operational performance at least offsetting it |
| Adjusted sales growth | 4–5%, as distinct from copper and currency |
| High voltage | Whether the 11.5% decline is stabilising |
| Free cash flow | Year-to-date on track for $200–300 million; second-half cash of $123–223 million |
| Customers and trade | The three largest customers’ shares, and any USMCA outcome |
Update — October 6, 2026: BUY, target $62 maintained
Written against the October 5 close of $47.27. Sources: Versigent’s second-quarter results release (August 4), its SEC filings since August 20 (insider Forms 4 and 144 only), and the news linked below. The August 25 analysis is left as published; this section brings it up to date and corrects two points in it.
The one-line version
Nothing since August 25 changes the case, and the stock is where it was then. But the August analysis missed two things in the second-quarter release: Versigent had already declared its first dividend, and it had guided 2026 adjusted EBITDA to $950–1,030 million, below the ~$1,023 million the valuation used. The two roughly cancel.
Interest rates matter little here. Only $500 million of debt floats, and the valuation ends on an exit multiple rather than perpetual growth, so half a point on the discount rate is worth about $2 a share.
The test is the third quarter, in early November: whether the 9.0% margin holds once the hedge gains are separated out, and whether cash conversion improves.
Rating: BUY, maintained · Target $62 · Grade: B+ (3.20)
What happened since August 25
| Date | Event | Read |
|---|---|---|
| Aug 3–4 (before the August analysis) | The board declared an inaugural quarterly dividend of $0.13 a share ($0.52 a year), payable September 18 to holders of record on September 4. The same release raised 2026 net-sales guidance to $9.4–9.6 billion and reaffirmed adjusted EBITDA of $950–1,030 million and free cash flow of $200–300 million | See Corrections below |
| Aug 5–13 | RBC Capital upgraded to Outperform ($52); Argus raised its target to $54 | Already in the price on August 25 |
| Sep 8–9 | Director Kevin Clark, Aptiv’s former chief executive, sold about 122,700 shares at $45.49–49.67, roughly $5.7 million, under a Rule 10b5-1 trading plan adopted on June 3. He holds about 124,800 shares afterwards, roughly half his position | Pre-scheduled, so a weak signal; worth recording |
| Sep 18–22 | Dividend-equivalent credits on executives’ and directors’ stock awards | Routine |
| September | The USMCA review stays unresolved. The September round in Washington left the main dispute open: the United States wants 50% U.S. content for preferential access, and Mexico wants relief from the 25% Section 232 tariff on autos (Automotive World) | An open risk for a Mexico-heavy footprint; already a “worse” trigger in the August analysis |
| August | S&P Global Mobility raised its North American light-vehicle production forecast by 22,000 units for 2026 and 224,000 for 2027 (forecast) | Mildly positive |
Versigent filed no 8-K after the second-quarter release, and has no buyback authorization. Analysts’ average target is about $57, between $52 and $65, with 11 buy and 3 hold ratings (stockanalysis.com). The stock has round-tripped: $46.96 on August 24, $50.22 on September 4, $44.94 on September 30, and $47.27 on October 5.
Corrections to the August 25 analysis
1. A dividend had been declared. The analysis said that five months after the spin “no dividend has been declared”, and called a dividend initiation “the single most informative announcement this company could make”. That announcement had been made on August 4, three weeks earlier: $0.13 a quarter. Dated notes now sit beside both passages. The point about its meaning still stands, in a smaller form: at $0.52 a year on 70.8 million shares, the dividend costs about $37 million, about 15% of guided 2026 free cash flow, far short of the 50% payout and 5% yield the analysis sketched as upside. It is a signal of confidence, not yet a return of capital that moves the valuation.
2. The 2026 guidance was not used. The valuation put 2026 adjusted EBITDA at about $1,023 million, near the top of the company’s reaffirmed range of $950–1,030 million. At the $990 million midpoint, enterprise value is 5.1× EBITDA rather than 4.9×. The analysis also did not note why the net-sales guidance rose: higher commodity pass-throughs and currency, not volume. The company’s own adjusted sales growth in the second quarter was about 5%, against 10.8% reported, which supports the August conclusion that the growth story is thinner than the headline.
Neither correction changes the target. The discounted cash flow model starts in 2027, on $1,002 million of EBITDA, inside the guided range.
Interest rates
The cash flow barely moves. Of $2.22 billion of debt, only the $500 million term loan floats (SOFR plus 1.50%). The two note issues, $1.6 billion in all, are fixed at 6.125% and 6.375%. A one-point rise in rates costs about $5 million a year, roughly 6 cents a share after tax.
The discount rate matters less than for most of what we cover. The model already uses 11.5%, for the cyclical end market and the concentration in three customers, and it ends on an exit multiple of 6× EBITDA rather than perpetual growth, so little of the value depends on how far-off cash flows are discounted. From the August grid, at a 6× exit:
| Discount rate | Value per share | vs $47.27 |
|---|---|---|
| 11.0% | $66 | +40% |
| 11.5% (base) | $64 | +35% |
| 12.0% | $62 | +31% |
| 13.0% | $58 | +23% |
About $2 a share per half point. The larger exposure is to the exit multiple itself, which is where higher rates show up for a cyclical supplier: at a 5× exit the base case is $56.
Macro sensitivity: rates, inflation, recession and oil
Versigent is the most macro-exposed name we rate a BUY, because its revenue is vehicle production multiplied by content per vehicle. Four pressures in the current environment reach it in different ways:
| Pressure | How it reaches Versigent | Direction |
|---|---|---|
| Higher interest rates | Mainly through car demand: dearer auto loans mean fewer vehicles sold and built, which the rates table above does not capture. Then through valuation, where supplier multiples compress as rates rise. The floating-rate cost is negligible | Downside |
| Higher inflation | Copper is largely passed through, so it inflates sales without adding profit: margin as a percentage falls even when profit dollars hold. Labor is the real exposure: harness assembly is labor-intensive, carmakers expect yearly price cuts from suppliers, and wage inflation is recovered only by renegotiation, with a lag. The peso is hedged until the hedges roll off | Downside, lagged |
| Higher recession odds | Production falls. Our auto-recession scenario (revenue down 8% in a year, then recovery) is worth $54. A downturn deeper than 10% arriving with the hedge roll-off is a thesis-breaking event, and recession raises the chance that one of the three customers at 14–20% of sales cuts programs. Two cushions: working capital, which absorbed cash on the way up, releases it on the way down; and nothing matures before 2031 | Downside, with cushions |
| High oil prices | The one tailwind: high fuel prices shift buyers toward hybrids and electric vehicles, which carry much more wiring per vehicle. Against it, household budgets are squeezed, resins are petrochemical and less often passed through than copper, and logistics costs rise | Mixed |
What it does to the cases. The base case of $64 already allows for an ordinary cycle through its 11.5% discount rate and 6× exit. The upside cases, the 9.0% margin holding and capital returns growing, need steady production, and most of these pressures work against them; only the shift toward electrified vehicles helps. The downside is where they compound. The bear case of $46, flat revenue at the three-year margin of 7.4%, assumes a 6× exit. If higher rates also take the exit multiple to 5×, the bear case falls to about $40, roughly 16% below the October 5 price. That figure is our estimate: one turn of the bear case’s EBITDA of about $910 million, discounted seven years at 11.5%, is about $6 a share. In the rising rates, sticky inflation and recession combination, the August conclusion that “the bear case is roughly today’s price” would no longer hold.
The practical reading: the stock is cheap enough to price an ordinary cycle, not a stagflationary one. Of the names we rate a BUY, it is the one to hold smaller if a downturn looks likely.
The valuation at a glance
At $47.27: market capitalization $3.35 billion on 70.8 million shares, net debt $1.67 billion at June 30, enterprise value $5.02 billion.
| Measure | At $47.27 | At $46.96 (August 24) |
|---|---|---|
| EV / 2026 adjusted EBITDA, guidance midpoint ($990M) | 5.1× | 5.0× |
| EV / 2026 adjusted EBITDA, our estimate ($1,023M) | 4.9× | 4.9× |
| Price / second-quarter adjusted EPS, annualized ($1.92 × 4) | 6.2× | 6.1× |
| Price / 2026 guided free cash flow ($250M midpoint) | 13.4×, a 7.5% yield | 13.3× |
| Dividend yield ($0.52) | 1.1% | — |
Price target: $62 · BUY, maintained
$62 is 31% above the October 5 close. The methods are those of the August 25 analysis, unchanged: the discounted cash flow at $64 and 10× normalized earnings at $63, which land within a dollar of each other. The BUY holds across the discount rates in the table; it would not hold at a 5× exit multiple combined with a margin back at the three-year average of 7.4%.
What the third-quarter results (early November) must show
| Line | The test |
|---|---|
| Adjusted operating margin | The 9.0% of the second quarter holding, with the hedge contribution disclosed separately: about $102 million of hedge gains flow through cost of sales and will not repeat |
| Free cash flow | Conversion improving on the first half’s 21% of adjusted operating income, toward the $200–300 million guided for the year |
| Volume versus pass-through | Adjusted sales growth, as distinct from copper and currency |
| Restructuring | A second quarter without charges |
| Trade | Any outcome in the USMCA review, and any change to tariffs on Mexican-built content |
| Capital return | The dividend maintained; any buyback authorization |
Post-Spin Analysis — August 25, 2026
Written against the August 24 close of $46.96. Primary sources: the Q2 2026 Form 10-Q (filed 2026-08-04), the Q1 2026 Form 10-Q, and the Form 10 information statement, which carries three years of audited carve-out financials. No annual report exists yet — Versigent began trading on April 1, 2026.
The one-line version
Versigent is up 68.6% since the April spin and still trades at 4.9x EV/EBITDA and roughly 7.4x normalized earnings — below BorgWarner at ~7.5x EV/EBITDA, below the 5.5–8.5x range for Tier-1 supplier transactions, and below the 8–12x P/E where auto suppliers usually trade.
The cheapness is real. The growth story is thinner than two quarters make it look. The Form 10 carries three years of carve-out history, and over that period revenue went $8,832M → $8,309M → $8,818M — a −0.1% CAGR. The 10.8% growth reported last quarter is a recovery off a weak 2024, not an established trend.
Adjusted operating margin tells the same story: 7.6% → 6.9% → 7.6% across the three years, then 7.9% in 1H26 and 9.0% in Q2. That last quarter is the best in the company’s recorded history — but it is one quarter, and Q1 2026 was down year on year.
Rating BUY. Target $62. Base case +36%; the bear case — flat revenue forever at the three-year average margin — is roughly fair value, not a loss. You are paying a distressed multiple for a business that has proven it can earn ~7.5% margins through a cycle, with a free option on the Q2 improvement being real.
The distribution is wider than that in both directions. The upside tails — the restructuring program genuinely ending, working capital reversing, capital return beginning — are worth $73–95. The downside tails are faster: losing one of three customers at 14–20% of sales is worth −31% to −57%, and ~$102M of hedge gains currently flowing through cost of sales will not repeat. See Tail scenarios.
Grade B+ (3.20).
What the business actually is
The electrical distribution business separated from Aptiv on April 1, 2026 — wiring harnesses, connectors and the signal, power and data architecture that runs through a vehicle. Roughly $9.3B of annualised revenue, making it one of the largest names in the tracked universe by sales and one of the smallest by market capitalization.
| Product line | Q2 2026 | Q2 2025 | Change | Share of sales |
|---|---|---|---|---|
| Low Voltage Electrical Architecture | $2,222M | $1,945M | +14.2% | 90.9% |
| High Voltage Electrical Architecture | $222M | $261M | −14.9% | 9.1% |
| Total | $2,444M | $2,206M | +10.8% |
Read that table before anything else. The market’s assumption about this industry is that high-voltage architecture — the EV-linked business — is the growth story and traditional low-voltage wiring is the melting ice cube. Versigent’s numbers say the reverse. High voltage is 9% of sales and shrinking 15%; low voltage is 91% and growing 14%.
Geographically it is genuinely global: North America $1,022M, EMEA $524M, with the balance in Asia Pacific and South America. Manufacturing is labor-intensive and sited accordingly, which is both the margin structure and the tariff exposure.
Management also flags adjacent markets — agriculture, construction, grid and infrastructure, off-grid power storage and robotics. Nothing is sized yet, so it is optionality rather than a number.
Management Team
| Role | Name | Background |
|---|---|---|
| CEO | Joseph Liotine | Ran the EDS business inside Aptiv as EVP and President from 2024; a career senior operator in global industrials |
| CFO | Doug Ostermann | 30+ years leading finance across automotive and industrial businesses |
The CEO already ran this business. That is a different proposition from an outside hire learning a spun-off asset — the Q2 margin step-up came from someone who knew where the cost was before the separation.
The pairing is otherwise conventional: an operator who knows the assets and a finance executive brought in from outside. Two quarters is not a track record, and the scorecard reflects that.
The financial record, over three years rather than two quarters
The Form 10 carries audited carve-out financials back to 2023. They are essential context, and they temper the story the quarterly numbers tell.
| Net sales | YoY | Operating income | Adj. operating income | Adj. margin | |
|---|---|---|---|---|---|
| FY2023 | $8,832M | — | $587M | $672M | 7.6% |
| FY2024 | $8,309M | −5.9% | $457M | $576M | 6.9% |
| FY2025 | $8,818M | +6.1% | $534M | $670M | 7.6% |
| 1H 2025 | $4,230M | — | $254M | $302M | 7.1% |
| 1H 2026 | $4,656M | +10.1% | $273M | $367M | 7.9% |
| Q2 2026 | $2,444M | +10.8% | $199M | $221M | 9.0% |
Adjusted for amortization, restructuring, separation costs, acquisition and portfolio project costs, and asset impairments, per the Form 10 reconciliation.
Three things the longer record establishes:
1. Revenue has been flat, not growing. 2023 to 2025 is a −0.1% CAGR. Revenue fell 5.9% in 2024 and recovered 6.1% in 2025 — back to roughly where it started. The 10.8% growth in Q2 2026 is measured against a soft comparison, and 1H 2026 revenue of $4,656M annualises to $9.3B, which would be the first year genuinely above the 2023 level.
2. Margin is cyclical around ~7.5%, not on a trend. 7.6% → 6.9% → 7.6%. The 1H26 figure of 7.9% is modestly above that band and Q2’s 9.0% is the best quarter in the record — but the annual pattern is a business that earns roughly 7.5% through a cycle and dips in bad years.
3. Restructuring is persistent, which makes “adjusted” generous. Restructuring charges ran $48M, $101M and $86M across the three years — roughly 1% of sales, every year. A cost that recurs annually is arguably an operating cost rather than an adjustment. Strip it out entirely and the margins read 7.1% / 5.7% / 6.6%.
What is genuinely new, and worth watching
Q2 2026 carried zero restructuring charges — the first clean quarter in the record — and delivered a 9.0% adjusted margin on 10.8% revenue growth. That is a real result, and it is why the stock rose 8.9% the day it was reported.
But Q1 2026’s adjusted margin was 6.6%, down from 7.1% a year earlier. One quarter up sharply, one quarter down. Q3 is the test, and the valuation below deliberately does not require the 9.0% to hold.
Where Versigent sits in the value chain
This is a genuinely weak bargaining position, and the valuation is arguably the correct response to it rather than an inefficiency. Establishing it properly matters, because the bull case rests on 4.9x being too cheap.
| Against | Position |
|---|---|
| Customers — vehicle OEMs | Weak, and structurally so. Three customers are 14–20% of sales each. Annual price-down expectations are the industry norm, written into supply agreements. The buyer is larger, more concentrated and more sophisticated than the supplier |
| Suppliers — copper, resins | Weak. Copper is an exchange-traded commodity. Versigent hedges it, which is why roughly $102M of hedge gains are currently flowing through cost of sales — a real cost it cannot pass through in the moment |
| Labor | The actual battleground. Harness assembly is hand-intensive and sited for cost — Mexico, North Africa, Eastern Europe, Asia. Wage inflation and tariffs land here directly |
| Competitors — Sumitomo, Yazaki, Furukawa, Leoni, Motherson | A stable global oligopoly. Share moves slowly, at platform award |
What protects it is cost position, not pricing power
A harness is designed into a specific vehicle platform. It is engineered around that model’s architecture, routing and packaging; switching supplier mid-program is close to impossible. That protects the revenue for the five to seven years a platform runs.
It confers nothing at the rebid. When the next platform is awarded, the OEM runs a competitive process among four or five capable global suppliers, and the winner is whoever can build it cheapest at the required quality. Design-in protects the program; it does not protect the price.
The same distinction separates two other recent industrial separations, and Versigent sits at the harder end of it. Solstice’s refrigerant business is protected by scarcity — a patent on a molecule regulation obliges the customer to buy — and it raises price. Qnity is protected by qualification — the socket is safe, but four to six suppliers are qualified and the buyer is TSMC, so it gives price back. Versigent is protected by neither. It is protected by being the low-cost producer, which is a real advantage and a completely different one: it defends margin rather than creating it.
That is why the margin is what it is. Adjusted operating margin of 7.6% → 6.9% → 7.6% across three years is not a business failing to expand. It is a business being held at a cost-plus outcome by customers who can see its cost base, and the stability of that number across a cycle is the evidence.
The tailwind is content, not units
Global vehicle production is flat to declining. Versigent’s content per vehicle is not. Every additional sensor, camera, display, domain controller and electrified subsystem adds wiring, connectors and signal architecture. The shift toward zonal electrical architectures is a redesign of exactly what this company sells.
That is the growth mechanism, and it is more durable than the volume line suggests — it does not require anyone to build more cars, only to put more electronics in the ones they build.
And the page’s most contrarian finding sits here. Low-voltage architecture is 91% of sales and grew 14.2%; high-voltage — the EV-linked business — is 9% and shrank 14.9%. The market’s model of this industry is that high voltage is the growth engine and low voltage the melting ice cube. On Versigent’s numbers that is backwards, and the reason is content: hybrids and conventional vehicles are gaining electronics faster than EV volumes are growing.
So is 4.9x wrong, or right?
Partly right, and that is the honest answer. A business that cannot raise price, has three customers at 14–20%, and competes on manufacturing cost should trade below a supplier with proprietary technology. The 8–12x where auto suppliers usually trade is not the right benchmark for the weakest position in the sector.
But 4.9x is below even its own tier. BorgWarner trades near 7.5x, and Tier-1 supplier transactions have cleared at 5.5–8.5x. The discount to those is what has to be explained, and the candidates are the customer concentration, the hedge gains that will not repeat, the flat three-year revenue line, and five months of listed history. Those are reasons for a discount to the sector. They are not obviously reasons for a discount to the discount — which is the whole of the bull case, stated precisely.
Why the stock has re-rated
There is no single event in the price history. The move is a grind:
| Month end | Close |
|---|---|
| April 2026 | $34.97 |
| May 2026 | $44.12 |
| June 2026 | $42.01 |
| July 2026 | $41.35 |
| August 24 | $46.96 |
Day-1 close $27.85 · post-spin low $26.94 on April 7, six sessions in · all-time high $50.17 on June 4 · now 6.4% below that high and 74.3% above the low.
The forced-selling flush was shallow and fast. Day-1 volume ran 25.6x the eventual baseline, the low arrived on session six at just 3.3% below the day-1 close, and volume now runs 0.74x baseline. The mechanical seller was done inside two weeks.
Every one of the seven largest single-session moves is positive, and all came on modest volume — 1.3x to 2.3x normal. The two largest, +10.8% on May 6 and +8.9% on August 4, are the days after the two quarterly reports. This is a business re-rating on results, not a story stock.
Realised volatility is 58.9% annualised, which is high and matters for position sizing.
Valuation
| At $46.96 | |
|---|---|
| Shares outstanding | 70.8M |
| Market capitalization | $3.33B |
| Total debt | $2,224M |
| Cash | $554M |
| Net debt | $1,670M |
| Enterprise value | $5.00B |
| EV / FY26E EBITDA (~$1,023M) | 4.9x |
| EV / FY26E adjusted EBIT | 6.8x |
| P/E on Q2 annualised EPS of $6.64 | 7.1x |
| P/E on 1H annualised EPS of $5.52 | 8.5x |
| Net leverage | 1.63x |
Debt structure: $500M Term Loan A due 2031, 6.125% senior notes due 2031, 6.375% senior notes due 2034, and an undrawn $850M revolver. Nothing matures before 2031.
Cash conversion is the weak spot, and it is real
| 1H 2026 | |
|---|---|
| Operating cash flow | $194M |
| Capital expenditure | ($117M) |
| Free cash flow | $77M |
| Adjusted operating income | $367M |
| FCF conversion | 21% |
The gap is working capital: receivables absorbed $278M in the first half against $426M of incremental revenue, partly offset by payables. This is a business that consumes cash as it grows, and the faster it grows the more it consumes. Capex is modest at 2.5% of sales and depreciation is 2.4%, so this is a working-capital story, not a capital-intensity one.
The valuation below charges for it: the model applies a 14-cent working-capital absorption on every incremental revenue dollar.
The capital-spending half of the story is set out separately below, and it runs the other way: capex was cut a third in the two years before the spin and is now rising, which flatters the 2025 free-cash-flow figure and depresses this one. Neither 21% nor the 2025 number is the run-rate.
Discounted cash flow
Every assumption is stated, because on a business with three years of history and two quarters of public reporting the assumptions are the analysis.
| Input | Value | Why |
|---|---|---|
| Revenue growth | 3.5% in FY27, easing to 2.0% by FY33 | The wiring-harness market grows ~2%. Versigent has taken share, so a modest premium is warranted — but the three-year record is flat, so the model does not extrapolate 10.8% |
| Adj. operating margin | 8.0% rising to 8.5% | Above the three-year average of 7.4%, below Q2’s 9.0%. Splits the difference between the record and the recent result |
| Depreciation & amortization | 2.4% of sales | 1H26 actual: $112M on $4,656M |
| Capital expenditure | 2.8% of sales | 1H26 actual was 2.5%; rounded up for maintenance |
| Working capital | 14% of every incremental revenue dollar | 1H26 receivables absorbed $278M against $426M of incremental revenue, partly offset by payables. This business consumes cash as it grows |
| Tax rate | 21% | Consistent with the 1H26 effective rate |
| WACC | 11.5% | Cyclical auto end market, 52% of sales in three customers, 58.9% realised volatility, two quarters of public history. Moderate 1.63x leverage and no maturity before 2031 keep it from being higher |
| Terminal | 6x exit EV/EBITDA | Below BorgWarner’s ~7.5x and at the low end of the 5.5–8.5x Tier-1 transaction range |
| ($M) | FY27 | FY28 | FY29 | FY30 | FY31 | FY32 | FY33 |
|---|---|---|---|---|---|---|---|
| Revenue | 9,638 | 9,927 | 10,225 | 10,480 | 10,743 | 10,957 | 11,177 |
| growth | 3.5% | 3.0% | 3.0% | 2.5% | 2.5% | 2.0% | 2.0% |
| Adj. EBIT | 771 | 814 | 849 | 880 | 913 | 931 | 950 |
| margin | 8.0% | 8.2% | 8.3% | 8.4% | 8.5% | 8.5% | 8.5% |
| EBITDA | 1,002 | 1,052 | 1,094 | 1,132 | 1,171 | 1,194 | 1,218 |
| Unlevered FCF | 525 | 563 | 588 | 618 | 642 | 662 | 675 |
| WACC ↓ / exit EV/EBITDA → | 5x | 6x | 7x | 8x |
|---|---|---|---|---|
| 10.0% | $62 | $71 | $79 | $88 |
| 11.0% | $58 | $66 | $74 | $83 |
| 11.5% (base) | $56 | $64 | $72 | $80 |
| 12.0% | $54 | $62 | $69 | $77 |
| 13.0% | $50 | $58 | $65 | $72 |
Scenarios
| Scenario | Value | vs $46.96 |
|---|---|---|
| Q2’s 9.0% margin proves durable | $69 | +47% |
| Base — growth 3.5% → 2%, margin to 8.5% | $64 | +36% |
| Margin holds at the three-year average of 7.4% | $54 | +15% |
| Auto recession — revenue −8% in year one, then recovery | $54 | +15% |
| Bear — flat revenue forever at the 7.4% three-year margin | $46 | −3% |
The bear case is roughly fair value, not a loss. That is the honest version of the asymmetry: you are not being paid to take a large downside, you are being paid because the downside is small.
Tail scenarios — the outcomes outside the base/bull/bear frame
The scenarios above vary growth and margin within a plausible band. These are the low-probability outcomes that are still specific and foreseeable — not black swans, but the two-to-three-standard-deviation cases with identifiable causes. They are listed because the distribution here is genuinely wider than the base case implies, in both directions.
Upside tails
1. The restructuring program actually ends. Charges ran $48M, $101M and $86M across 2023–25, and Q2 2026 was the first quarter in the record with zero. If that is a program completing rather than a pause, reported margin converges toward adjusted permanently: +$86M pre-tax, +$0.96 of EPS, and normalized EPS goes $6.31 → $7.26. At 10x that is $73 rather than $63. This is the single most likely of the tails, and Q3 will show it.
2. The margin trend is real and continues. The sequence is 7.6% → 6.9% → 7.6% → 7.9% → 9.0%. If 9.0% is the new base and scale plus adjacent-market mix carries it toward 10%:
| Margin on ~$9.8B revenue | EPS | at 10x | at 12x |
|---|---|---|---|
| 9.0% | $8.46 | $85 | $101 |
| 9.5% | $9.00 | $90 | $108 |
| 10.0% | $9.55 | $95 | $115 |
3. Working capital stops absorbing cash. Free-cash-flow conversion was 21% in 1H26 because receivables took $278M as sales grew. That is a growth cost, not a structural one — if growth moderates it reverses:
| FCF conversion | Free cash flow | FCF yield on today’s market cap |
|---|---|---|
| 21% (1H26 actual) | $154M | 4.6% |
| 45% | $331M | 10.0% |
| 60% | $441M | 13.3% |
4. Capital return begins. No dividend or buyback has been declared. At 45% conversion, a 50% payout is a 5% dividend yield, and retiring 5% of the shares a year adds roughly 5% to EPS annually. For a company at 7.4x earnings that is a material re-rating trigger on its own.
Correction (October 6, 2026): a dividend had been declared when this was written. The board declared an inaugural quarterly dividend of $0.13 a share on August 3, announced with the second-quarter results on August 4. See the October 6 update at the top of this page.
5. The adjacent markets get sized. Management names agriculture, construction, grid and infrastructure, off-grid power storage and robotics. None is quantified anywhere. Power and data distribution for data-center build-out is the same engineering problem as a vehicle harness, and it is the largest capital-spending program in the industrial economy right now. If any of this is disclosed as a real number, it changes the multiple rather than the earnings.
Downside tails
1. Losing one of the three large customers. Three names are 20%, 18% and 14% of sales. Operating leverage makes the consequence non-linear, because the terminal and engineering base does not shrink with the volume:
| Revenue | Operating income | Margin | EPS | at 9x | |
|---|---|---|---|---|---|
| Base | $9,312M | $736M | 7.9% | $6.82 | $61 |
| Lose the 14% customer | $8,008M | $449M | 5.6% | $3.63 | $33 (−31%) |
| Lose the 20% customer | $7,450M | $326M | 4.4% | $2.25 | $20 (−57%) |
A 20% revenue loss takes roughly half the operating income. This is the single largest risk on this page and it is why the position sizing note exists.
2. The hedge gains reverse — and this one is already dated. The 10-Q discloses $125M of net gains on cash flow hedges sitting in AOCI, of which approximately $102M is scheduled to flow into cost of sales over the next twelve months. That is 1.1% of sales — roughly 1.1 percentage points of operating margin — and it is temporary.
Part of the margin improvement this analysis is valuing may be a hedge gain rather than an operating gain. Strip the full 1.1pp and normalized margin falls 7.9% → 6.8%, EPS $6.82 → $5.68, and a 10x multiple gives $57 instead of $68. The hedges extend only to June 2028, after which the company reprices at spot.
This does not invalidate the thesis — $57 is still above today’s price — but it is the most concrete reason the Q2 margin may not be what it appears, and it is more specific than “one quarter is not a trend.”
3. Peso or tariff shock. The company hedges $1,022M notional of Mexican peso and 57.6M pounds of copper ($354M notional). The peso figure reveals how much of the cost base is Mexican labor. Beyond the hedge horizon:
| Adverse move | Annual cost | EPS | at 9x |
|---|---|---|---|
| 5% | +$69M | $6.06 | $55 |
| 10% | +$138M | $5.29 | $48 (roughly flat to spot) |
4. Both at once. A vehicle-production downturn of 10% with the hedge benefit rolling off puts margin near 6.2% — the 2024 level minus the hedge — for EPS of $4.41 and roughly $35 at 8x, or −25%.
What the tails say about the position
The upside tails are larger and more numerous than the downside tails, but the downside tails are faster. A customer loss is a single announcement; the margin trend proving durable takes four quarters to establish.
That argues for exactly what the sizing note says: own it, size it for the customer-concentration case, and let the Q3 and Q4 prints resolve whether the upside tails are live.
Earnings-based valuation
For a mature, cyclical manufacturer, earnings are as informative as cash flow — and here they need one adjustment. Versigent’s carve-out history carries no interest expense, because Aptiv’s debt was never attributed to it. Every figure below is pro-forma for the ~$144M of annual interest on the $2.2B raised at separation.
| Earnings basis | Adj. EBIT | Normalized net income | EPS | P/E at $46.96 |
|---|---|---|---|---|
| FY2023 actual margin, 7.6% | $671M | $433M | $6.11 | 7.7x |
| FY2024 actual margin, 6.9% | $573M | $355M | $5.01 | 9.4x |
| FY2025 actual margin, 7.6% | $670M | $432M | $6.09 | 7.7x |
| Three-year average, 7.4% | $689M | $447M | $6.31 | 7.4x |
| 1H26 run-rate, 7.9% | $736M | $483M | $6.82 | 6.9x |
| Q2 26 annualised, 9.0% | $838M | $564M | $7.97 | 5.9x |
Auto-component suppliers typically trade at 8–12x forward earnings. Versigent trades at 7.4x on its three-year average margin — below the range on the most conservative earnings basis available, before crediting any of the recent improvement.
What a peer multiple implies, on normalized EPS of $6.31:
| P/E | Value | vs spot |
|---|---|---|
| 8x | $50 | +7% |
| 9x | $57 | +20% |
| 10x | $63 | +34% |
| 11x | $69 | +47% |
| 12x | $75 | +60% |
The DCF and the earnings work agree: $63–64 on mid-range assumptions, which is where the target below sits.
Price target: $62 · range $50–75 · BUY
Method Value DCF — 11.5% WACC, 6x exit EV/EBITDA $64 10x P/E on normalized EPS of $6.31 $63 9x P/E on normalized EPS $57 6.5x EV/EBITDA on FY26E $71 Margin reverts to the three-year average $54 Bear — flat revenue forever at 7.4% margin $46 Base $62 is +32% to the August 24 close. Two independent methods — a discounted cash flow and a peer earnings multiple — land within a dollar of each other.
Recommendation: BUY, and the reason is the shape of the distribution rather than the size of the upside. The bear case is roughly today’s price. Flat revenue in perpetuity at the margin this business earned through 2023–2025 is worth about what you pay now. Everything better than that — the market’s 2% growth, any of the share gains of the last two quarters, any part of the Q2 margin proving durable — is upside you are not paying for.
What you are buying: a global Tier-1 supplier at 7.4x normalized earnings and 4.9x EV/EBITDA, with an undrawn $850M revolver, nothing maturing before 2031, and a management team that already ran the business inside Aptiv.
What you are underwriting: that 52% customer concentration does not bite, that flat is the floor rather than the trend, and that a labor-intensive manufacturer holds price through a tariff cycle.
Why the target does not move on the hedge finding. The tail analysis shows ~$102M of hedge gains flowing into cost of sales over the next twelve months — about 1.1pp of margin. That is a reason Q2’s 9.0% overstates the run-rate, and this valuation already declines to extrapolate it: the normalized EPS of $6.31 is built on the three-year average margin of 7.4%, a period that contains its own hedge gains and losses through a cycle. The finding reinforces the conservative anchor rather than undermining it. It does mean the upside tails require the operating improvement to be real, not hedged.
Sizing note. 58.9% realised volatility, three customers at half of revenue, and a three-year revenue record that is flat. The asymmetry justifies a position; none of the above justifies a large one.
What this most resembles
Matching on the characteristics that should drive the outcome — an asset-heavy, labor-intensive vehicle-component business spun from a parent repositioning toward higher-multiple technology — the universe offers a small and pointed set.
| Company | Parent | Spun | vs Day 1 | Excess vs S&P | Max drawdown |
|---|---|---|---|---|---|
| PHINIA | BorgWarner | Jul 2023 | +102.5% | +12.0pp | −34.9% |
| Garrett Motion | Honeywell | Oct 2018 | +42.8% | −5.8pp | −93.1% |
| Solventum | 3M | Apr 2024 | +32.1% | −7.2pp | −31.5% |
| Adient | Johnson Controls | Oct 2016 | −54.7% | −21.5pp | −92.4% |
One of four beat the S&P; median excess −6.5pp. Vehicle-supplier spinoffs are not a good category on average, and two of the four drew down more than 90%.
PHINIA is the analog that matters
BorgWarner spun its fuel systems and aftermarket business in July 2023 — the internal-combustion parts that the market had written off as terminal in an electrifying world. It is up 102.5%, beating the index by 12 percentage points annualised.
The trade was that the market mispriced a “declining” legacy business. Versigent is the same shape: 91% of its revenue is traditional low-voltage wiring, the part investors assume is being displaced, and it is growing 14% while the high-voltage EV business shrinks.
The difference cuts in Versigent’s favor on cyclicality — PHINIA carried more aftermarket revenue, which is steadier than OEM production. It cuts against on concentration.
Garrett Motion is in the table but is not a true comparable
It is included because it screens as one — a cheap component supplier spun from a large industrial parent — and because excluding it silently would flatter the cohort. But it failed for a reason that has nothing to do with turbochargers.
Garrett was spun from Honeywell in October 2018 carrying an indemnity obligation of roughly $1.5 billion, requiring it to pay Honeywell 90% of asbestos liabilities arising from the legacy Bendix brake business. Garrett sued its former parent in December 2019, alleging the spin-off was devised to offload those liabilities and that the agreement was not negotiated at arm’s length. It filed for Chapter 11 in September 2020, and the reorganization eliminated the indemnity in exchange for a $375M cash payment and preferred stock issued to Honeywell.
That is a different category of transaction — a parent disposing of a legal liability using an operating business as the vehicle. Judged on operations Garrett was viable; it was the parent agreement that broke it.
The relevant question for Versigent is therefore narrow: does it carry anything similar? The Form 10 and both 10-Qs disclose no indemnity of that character. What it carries is ordinary: $2,224M of debt at 6.125%–6.375%, nothing due before 2031, an undrawn $850M revolver and 1.63x leverage. Excluding Garrett from the operating comparison, the auto-supplier cohort is PHINIA, Solventum and Adient — one of three beat.
Capital allocation
The page has treated cash conversion as a working-capital story. The three-year record says capital spending is the other half of it, and that half was flattered going into the separation.
| ($M) | 2023 | 2024 | 2025 | 1H 2026 |
|---|---|---|---|---|
| Cash from operating activities | 180 | 707 | 641 | 194 |
| Capital expenditures | (244) | (206) | (160) | (117) |
| Free cash flow | (64) | 501 | 481 | 77 |
| Depreciation (annualised) | ~220 | ~220 | ~220 | 111 |
| Capex / depreciation | 111% | 94% | 73% | 105% |
Capex was cut by a third into the spin, and is now going back up
Capital expenditure fell 34% across 2023–2025 — $244M to $160M — and dropped to 73% of depreciation in the final year under Aptiv. In the first half of 2026 it is running $117M against $79M, up 48% year on year and back above depreciation.
That reframes the free-cash-flow figures on both sides. The $481M reported for 2025 was earned partly by underspending; the $77M for the first half of 2026 is depressed partly by catching up. Neither number is the run-rate, and the existing 21% conversion figure on this page is the low end of a range rather than a level.
It is a recognizable pattern — capital spending trimmed in the years a parent prepares to separate a business, then normalizing afterwards. It is not evidence of anything improper; it is a reason to discount the pre-spin cash flow and to expect the post-spin figure to be worse before it is better.
The separation moved $1.9B to Aptiv and left almost no equity behind
| ($M) | |
|---|---|
| Proceeds from senior notes and credit agreement, net of costs | 2,063 |
| Cash distribution paid to Aptiv | (1,894) |
| Net transfers to Aptiv | (47) |
| Total to the former parent | ≈(1,941) |
Total shareholders’ equity is $284M, of which $199M is a noncontrolling interest — leaving $85M attributable to Versigent shareholders against $5,359M of total assets. That is not negative book equity, but it is close, and it is the mechanical result of the same structure seen at every levered separation in this set.
The debt is expensive, and the credit market agrees with the equity market
| Instrument | Amount | Coupon | Due |
|---|---|---|---|
| Senior notes | $800M | 6.125% | 2031 |
| Senior notes | $800M | 6.375% | 2034 |
| Term Loan A | $500M | SOFR + 1.50% | 2031 |
| Finance leases and other | $151M | ||
| Total debt | $2,224M | ≈6.2% blended | |
| Revolving credit facility | $850M, five-year | ||
| Cash | $554M | ||
| Net debt | ≈$1,670M |
A 6.2% blended coupon is high for a borrower of this size with no maturity before 2031. Lenders priced it off the same facts the equity market did: thin margins, three customers at 14–20% of sales, and no ability to set price. That is a useful cross-check on the “too cheap” thesis — two independent markets reached the same view of the risk, and neither of them is the stock price.
The maturity profile is comfortable: nothing due before 2031, an undrawn $850M revolver, and covenant compliance confirmed.
Nothing is being returned, and something was promised
The Form 10 states plainly: “We currently expect to pay regular dividends to our shareholders following the Spin-Off.” Five months on, no dividend has been declared and no repurchase authorization exists. The only distribution in the cash flow statement is $4M to minority shareholders of consolidated affiliates — not to Versigent’s own holders.
This is the clearest near-term test of management’s confidence. The company said it intended to pay a regular dividend, generated $481M of free cash flow in its final year under Aptiv, and has not initiated one. Either the cash conversion is not yet trusted to support it, or the capital-spending catch-up comes first. Both are defensible. Neither is what a management team confident in a 45%-conversion business does with a stock at 4.9x EBITDA.
A dividend initiation would be the single most informative announcement this company could make, and at a 50% payout on normalized free cash flow it would yield around 5%. It is listed in the tail scenarios above as upside for exactly that reason.
Correction (October 6, 2026): a dividend had been declared when this was written. The board declared an inaugural quarterly dividend of $0.13 a share on August 3, announced with the second-quarter results on August 4. See the October 6 update at the top of this page.
In depth: competitive dynamics
1. Where Versigent sits
The wiring-harness market is roughly $43B growing at about 2% a year — a slow, mature industry dominated by Japanese incumbents.
| Supplier | Position |
|---|---|
| Yazaki + Sumitomo Electric | Together more than 50% of the global market |
| plus Fujikura and Furukawa | The four together exceed 60% |
| Versigent | Among the largest Western suppliers; the former Aptiv EDS franchise |
| Leoni | German, financially distressed in recent years |
2. The number that defines the competitive question
Versigent grew 10.8% into a market growing 2%. That gap has to come from somewhere, and only three explanations are available:
- Share gain — plausible given Leoni’s distress and the general retreat of European suppliers;
- Content per vehicle — every added feature, sensor, screen and electrified subsystem adds harness content, so revenue can grow faster than unit volumes;
- Mix and pricing — including tariff and raw-material pass-through.
The 10-Q does not decompose it, which is the single most important undisclosed number for this company. Global vehicle production rose about 4% from 2024 to 2025, so Versigent is growing at roughly 2.5x industry volume. Whatever the mechanism, it is working.
3. Moats and weak spots
✅ Design-in lock. Harnesses are engineered to a specific vehicle platform and qualified through the program’s life. Switching mid-program is impractical, which makes revenue visible several years out.
✅ Global manufacturing footprint. Harness assembly is labor-intensive and must sit near low-cost labor but within reach of assembly plants. Replicating that network is slow and expensive.
⚠️ Customer concentration is severe. The top ten customers are 83% of sales, and three customers alone are 20%, 18% and 14% — 52% in three names. Losing one platform at one of them would be material; losing a customer would be structural. This is the largest single risk on this page.
⚠️ Labor intensity cuts both ways. It keeps capital requirements low — capex is 2.5% of sales — but exposes the business to wage inflation and to tariff and trade-policy shifts that change where a harness can economically be built.
❓ The long-run question is content, not volumes. If vehicle architectures move toward zonal designs and higher-voltage backbones, total harness content per vehicle could eventually fall even as electronics rise. That is a decade-long question, not a 2027 one — but it is the reason this business is priced as a melting ice cube.
In depth: valuation against peers
| EV/EBITDA | |
|---|---|
| Versigent | 4.9x |
| BorgWarner (June 2026) | ~7.5x |
| Diversified Tier-1 suppliers, transaction range | 5.5–8.5x |
| Mono-platform Tier-2 suppliers, transaction range | 4.0–6.5x |
Versigent trades below the Tier-1 transaction range entirely, and inside the range that private buyers pay for mono-platform Tier-2 suppliers — businesses with one customer and one product. Versigent has ten customers, a global footprint and $9.3B of revenue.
Two honest reasons the discount might be deserved: customer concentration at 52% in three names is closer to a Tier-2 profile than a Tier-1 one, and two quarters of history is not enough for the market to underwrite the margin.
Neither explains a multiple this far below the peer set, and the reverse DCF result — zero growth priced in perpetuity — is the sharper way to see it.
In depth: is Versigent an acquisition target?
Not before April 1, 2028. The separation was structured to be tax-free under §355, and an acquisition of 50% or more within two years would be presumed part of a plan related to the distribution, making the spin taxable to Aptiv — a cost that would fall on Versigent under the tax matters agreement.
After that date the profile is genuinely attractive, more so than for most names this size:
| Acquirer | Assessment |
|---|---|
| Private equity | ✅ The most credible path. A $5B enterprise value, 1.63x leverage, low capex and a design-in revenue base is exactly the LBO profile. The working-capital intensity is the complication a sponsor would model carefully |
| Sumitomo Electric / Yazaki | ⚠️ Obvious industrial logic and impossible antitrust. The two already exceed 50% of the market between them |
| A Chinese or Korean supplier | ⚠️ Plausible on strategy, difficult on CFIUS and on European review |
| Motherson (Samvardhana) | ✅ A serial consolidator of wiring and vehicle components with an explicit acquisition strategy and prior harness deals |
| Aptiv (re-acquisition) | ❌ Foreclosed — the whole point was separation |
The more likely outcome is that it stays independent and re-rates. At 4.9x EV/EBITDA with a growing top line, the equity does not need a buyer to work. Acquisition is optionality, not the thesis — which is the healthiest way for it to sit in a valuation.
What would change this view
| Direction | Trigger |
|---|---|
| Better | Q3 confirming the 9.0% margin with the hedge contribution disclosed separately, which would validate the step-change · a second consecutive quarter with zero restructuring · disclosure decomposing growth into share versus content · adjacent markets (agriculture, grid, robotics) sized for the first time · a dividend or buyback initiated |
| Worse | Q3 margin falling back toward 7% · restructuring charges resuming · working capital continuing to absorb cash so free cash flow stays near 20% of EBIT · tariff action raising the cost of the Mexican manufacturing footprint · the peso appreciating beyond the hedge book |
| Thesis-breaking | Loss of one of the three customers at 14%+ of sales — worth roughly −31% to −57% on the tail analysis · a global vehicle-production downturn deeper than 10% arriving together with the hedge roll-off · evidence that zonal architecture is cutting harness content per vehicle sooner than expected |
Investment Scorecard
Scored on the five weighted dimensions set out in our methodology.
| Dimension | Weight | Score | Rationale |
|---|---|---|---|
| Financial Profile | 25% | 3.0 | Net leverage 1.63x, no maturity before 2031, an undrawn $850M revolver, and a Q2 adjusted margin of 9.0% on 10.8% growth. Held down by a flat three-year revenue record (−0.1% CAGR), margin that has cycled around 7.5% rather than trended up, persistent ~1%-of-sales restructuring, and 21% free-cash-flow conversion |
| Competitive Position | 25% | 3.0 | Design-in lock through vehicle program life and a global low-cost footprint that is hard to replicate — but marked down from 3.5 once the bargaining position was set out properly: three customers at 14–20% of sales each, annual price-down expectations written into the industry, and protection that comes from cost position rather than pricing power, which defends margin without creating it. The stable 7.6% / 6.9% / 7.6% margin line is the evidence — that is a cost-plus outcome, not a franchise. |
| Strategic Rationale | 20% | 3.5 | A coherent separation: Aptiv kept the higher-multiple electronics and software, Versigent gets to run the harness business for margin and cash rather than competing internally for capital. Discounted because this was the asset the parent chose to shed |
| Management & Governance | 20% | 3.5 | A CEO who already ran this business inside Aptiv and a CFO with 30 years of relevant experience, who delivered a 180bp margin step in their second reported quarter. Held down by two quarters of public track record |
| Acquisition Potential | 10% | 3.0 | Blocked by §355(e) until April 2028. Beyond that, a $5B enterprise value with low capex and design-in revenue is a credible private-equity target, and Motherson is a plausible strategic consolidator |
| Weighted Score | 3.20 | ||
| Investment Grade | B+ · Solid Opportunity |
What the capital-allocation and value-chain work changed
Competitive Position 3.5 → 3.0, and it is the only score that moved. Setting out the bargaining position properly makes the case worse than “design-in lock” implied: the customer position is genuinely weak, and the protection is manufacturing cost rather than anything the customer cannot get elsewhere. Weighted score 3.33 → 3.20; the band holds.
Financial Profile stays at 3.0, and the capital-spending finding is why it did not fall. Capex was cut 34% into the separation and is now rising, which makes both the 2025 free cash flow and the current 21% conversion misleading in opposite directions. But the discounted cash flow already models capex at 2.8% of sales against 2.4% depreciation — above every year on record. The finding validates the model rather than correcting it, which is the opposite of what the same work did at Solstice.
The target is unchanged at $62. Nothing here touches the cash flows in the model.
First grade for this company, and grade and rating point different ways
Versigent has been carried as a completed spinoff without a grade since separation. B+ (3.20) is where the scorecard lands: a decent business, not an exceptional one. Customer concentration at 52% in three names and a mature end market are real constraints, and no amount of cheapness changes them.
The rating is BUY anyway, and the two are not in conflict. The grade measures business quality; the rating measures price. A B+ business at 7.4x normalized earnings is a better proposition than an A− business at 28x — and the bear case here, flat revenue in perpetuity at the margin this business earned through 2023–2025, is roughly the current price.
The grade takes effect with the next published report.
What would take it to A−: two or three quarters establishing that revenue growth and the 9.0% margin are a trend rather than a recovery off a soft 2024, plus any disclosure decomposing growth into share versus content. What would take it down: a customer loss, or revenue returning to the flat 2023–2025 line.